
 India Ethoxylates Market | 2026-2036
India Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
India Ethoxylates Market Insights
Asset-light toll manufacturing and third-party contract ethoxylation is fragmenting competitive entry barriers across India's specialty chemicals landscape. India Glycols Limited leverages its integrated ethylene oxide feedstock position to sustain cost leadership in fatty alcohol ethoxylates. Godrej Industries Limited anchors its presence through backward integration into oleochemicals, while Clariant IGL Specialty Chemicals Private Limited differentiates via technology licensing for narrow-range ethoxylation.
Ethoxylates are non-ionic surfactants produced by reacting ethylene oxide with hydrophobic substrates such as fatty alcohols, fatty acids, or alkylphenols, yielding products with tunable hydrophilic-lipophilic balance values typically ranging from 8 to 18. These compounds function primarily as surface-active agents that reduce interfacial tension in aqueous systems, enabling dispersion, emulsification, and detergency across industrial and consumer formulations. Fatty alcohol ethoxylates dominate volume throughput due to their biodegradability profile and versatility in personal care and household applications, while fatty acid ethoxylates command margin premiums in agrochemical emulsifier formulations where hydrolytic stability determines performance. Alkyl phenol ethoxylates face structural decline amid regulatory pressure on endocrine-disrupting precursors, redirecting R&D expenditure toward lauryl alcohol ethoxylates as compliant substitutes in textile and institutional cleaning segments.
BIS purity standards, CDSCO cosmetic ingredient notifications, and the CEA's environmental compliance mandates for effluent discharge from ethoxylation plants collectively elevate capital requirements for new manufacturing capacity. The PLI scheme for specialty chemicals is channeling investment toward import-substitution grades of high-purity ethoxylates previously sourced from Southeast Asian suppliers. Stakeholders must monitor feedstock volatility in ethylene oxide pricing and the pace of BIS harmonization with REACH-equivalent standards to calibrate capacity expansion timelines.
Market Dynamics
BIS certification tightening for chemical purity grades is compressing input specifications across domestic supply chains, forcing reformulation investments from Maharashtra's personal care manufacturers and Gujarat's specialty chemicals cluster.
Growth Catalysts
- PLI scheme for specialty chemicals:The production-linked incentive framework channels capital toward import-substitution grades of high-purity ethoxylates previously sourced from Southeast Asian suppliers.
- Sulfate-free surfactant demand:Personal care manufacturers in Mumbai and Gujarat are expanding ethoxylate procurement for milder formulation chemistries in shampoo and body wash segments.
- Narrow-range ethoxylation technology:Technology licensing agreements enable domestic producers to manufacture ethoxylates with tighter ethylene oxide distribution, improving performance consistency for agrochemical emulsifiers.
Market Restraints
- Ethylene oxide feedstock volatility:Crude-linked pricing swings in ethylene oxide create margin compression for non-integrated ethoxylate manufacturers lacking captive ethylene supply.
- Alkylphenol ethoxylate regulatory phase-out:CDSCO and state pollution control boards are restricting endocrine-disrupting precursors, forcing R&D redirection toward compliant substitutes.
- Capital intensity of BIS-compliant capacity:New ethoxylation plants require effluent treatment investments meeting CEA environmental mandates, elevating break-even thresholds.
Strategic Opportunities
- Lauryl alcohol ethoxylate substitution:Textile and institutional cleaning segments present white space for APEO-free alternatives as regulatory pressure accelerates precursor displacement.
- Asset-light toll manufacturing:Third-party contract ethoxylation services lower competitive entry barriers for regional formulators lacking dedicated reaction vessels.
- Maharashtra-Gujarat corridor consolidation:Logistics optimization between Mumbai's personal care hub and Ahmedabad's oleochemical base enables integrated supply chain configurations.
Industry Challenges
- REACH-equivalent BIS harmonization timeline:Uncertainty around full adoption of EU-aligned purity standards complicates long-term capacity planning for domestic producers.
- Specialized process engineering talent:Narrow-range ethoxylation and high-pressure reactor operations require skilled technicians scarce outside legacy petrochemical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ethoxylates Market |
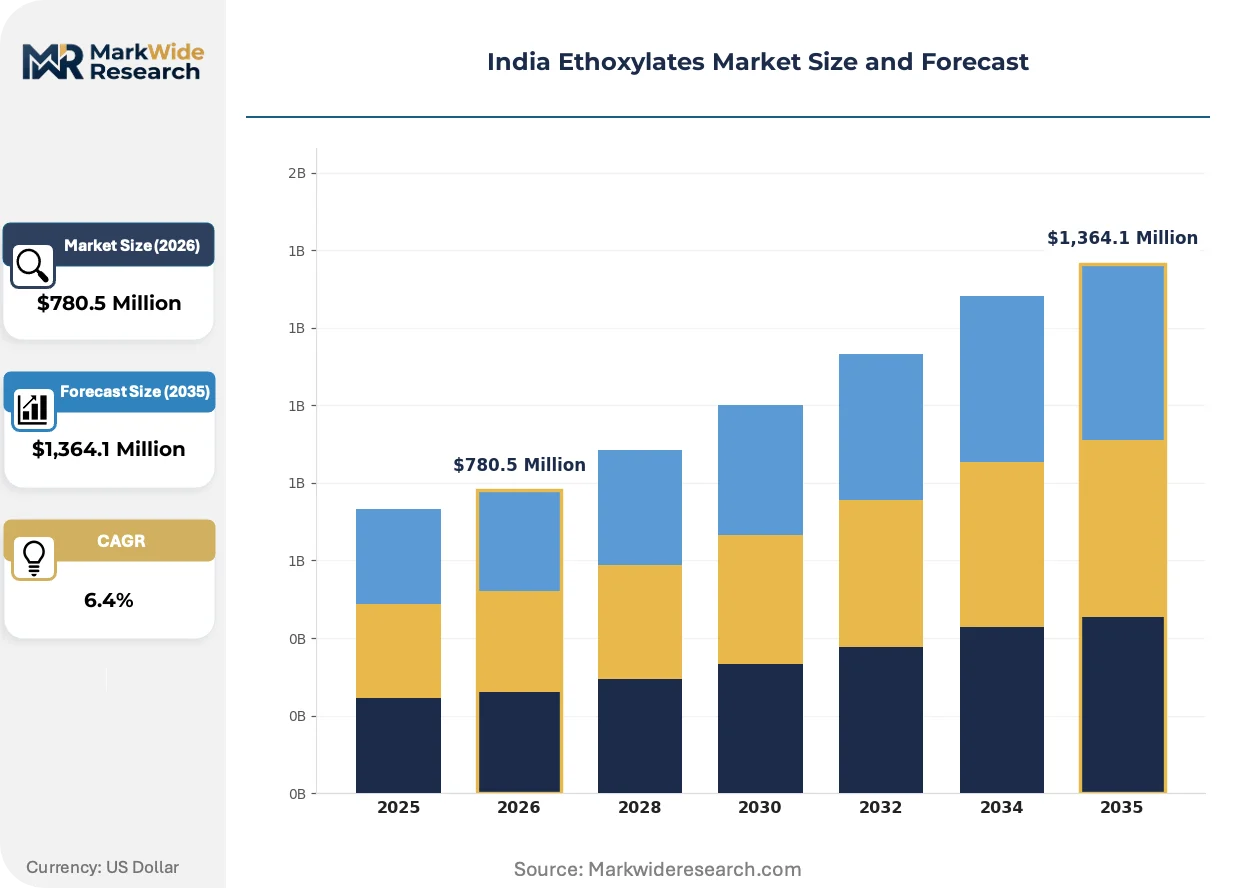
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,364.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
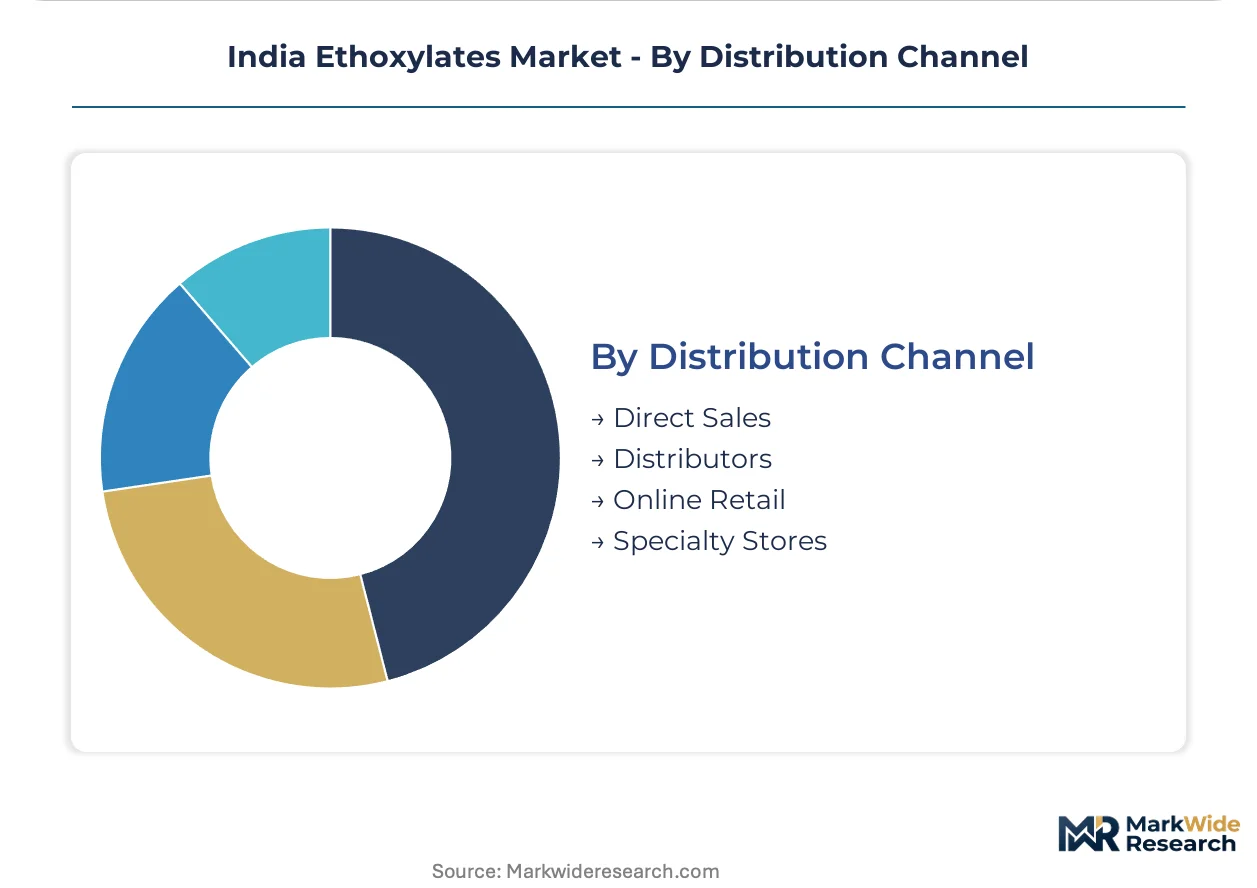
| Segmentation | Product Type: Fatty Alcohol Ethoxylates, Fatty Acid Ethoxylates, Alkyl Phenol Ethoxylates, Lauryl Alcohol Ethoxylates Application: Surfactants, Emulsifiers, Wetting Agents, Cleaning Agents End User: Personal Care, Household Products, Industrial Cleaning, Agrochemicals Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | Core Chemicals Pvt. Ltd., Matangi Industries, Godrej Industries Limited, Rimpro-India, Fibrol Non-Ionics Pvt. Ltd., Clariant IGL Specialty Chemicals Private Limited, Esteem Industries Pvt. Ltd., India Glycols Limited, APL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ethoxylates Market Trends and Innovations
Process intensification and regulatory chemistry shifts are restructuring how ethoxylates are manufactured, specified, and procured across Indian industrial applications.
Narrow-range ethoxylation catalyst systems is collapsing the performance gap between commodity fatty alcohol ethoxylates and premium narrow-distribution grades. Agrochemical formulators in Gujarat are adopting these materials for emulsion stability without paying historical specialty premiums. The technology is collapsing price stratification between standard and performance-tier ethoxylates in crop protection applications.
CDSCO cosmetic ingredient notifications are tightening purity documentation requirements for ethoxylates used in rinse-off personal care products. Manufacturers must now submit batch-level ethylene oxide residual data and dioxane testing certificates prior to market placement. Mumbai-based personal care brands are responding by consolidating supplier bases toward BIS-certified producers with established analytical capabilities.
Direct mill procurement of ethoxylate concentrates is displacing distributor-mediated supply for Maharashtra's textile processing sector. Large fabric finishers in Surat and Bhiwandi now negotiate annual contracts with ethoxylate manufacturers, bypassing traditional chemical traders. This pattern is most visible in institutional laundry and textile wet processing segments where volume concentration enables formula customization.
India Ethoxylates Market Segmentation
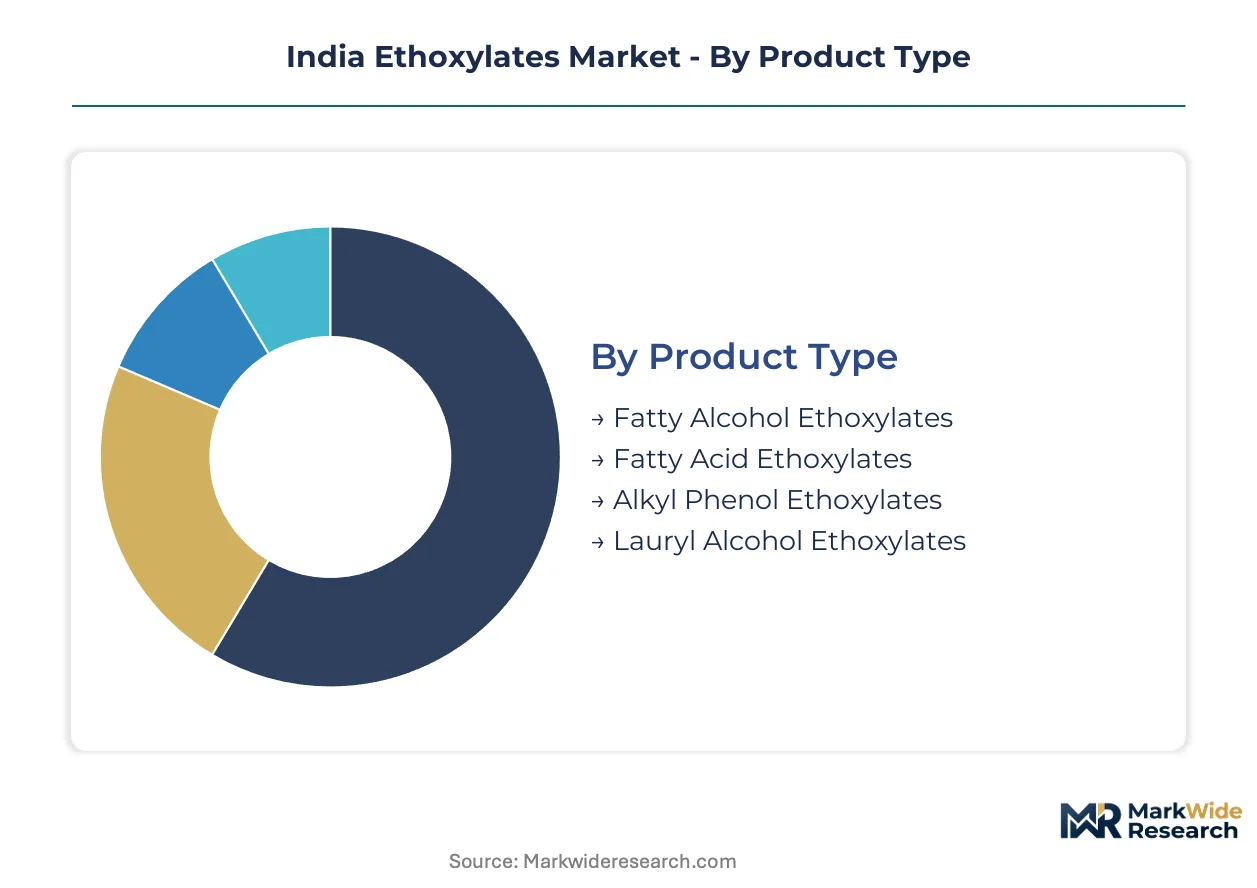
Ethoxylate specifications vary sharply across Indian industrial applications, with BIS purity grades and end-use performance requirements driving procurement decisions. Manufacturers must align product selection with formulation chemistry, regulatory compliance, and supply chain configuration.
Product Type:
Cost tier positioning separates commodity-grade materials from performance-specified alternatives requiring narrow-range ethoxylation technology.
- Fatty Alcohol Ethoxylates:These biodegradable surfactants, synthesized from linear fatty alcohols and ethylene oxide, deliver tunable hydrophilic-lipophilic balance values. Maharashtra's personal care manufacturers in Mumbai procure these heavily for sulfate-free shampoo and body wash formulations as CDSCO cosmetic notifications tighten purity documentation.
- Lauryl Alcohol Ethoxylates:Derived from coconut or palm kernel oil feedstocks, these compounds offer superior foaming profiles and regulatory compliance. Gujarat's textile processors in Surat are redirecting procurement toward these APEO-free alternatives as state pollution control boards restrict endocrine-disrupting precursors in institutional cleaning applications.
- Fatty Acid Ethoxylates:Produced through ethylene oxide addition to fatty acids, these materials command margin premiums in agrochemical emulsifier formulations where hydrolytic stability determines field performance.
- Alkyl Phenol Ethoxylates:Facing structural decline amid regulatory phase-out pressures; remaining demand concentrates in legacy industrial applications pending compliant substitution completion.
Fatty alcohol ethoxylates command the established base. The steepest expansion runs through lauryl alcohol ethoxylates.
Application:
Application selection maps directly to interfacial tension reduction requirements across aqueous formulation systems.
- Surfactants:Surface-active agents reduce interfacial tension in personal care and household products. Mumbai-based formulators specify these for mild cleansing chemistries as consumer preference shifts away from sulfated systems.
- Emulsifiers:Stabilize oil-water interfaces in agrochemical and cosmetic formulations. Gujarat's crop protection sector drives specification toward narrow-range grades for improved emulsion stability under field storage conditions.
- Wetting Agents:Enable substrate penetration in textile processing and industrial coatings. Surat fabric finishers negotiate direct mill procurement contracts bypassing traditional chemical distributors.
- Cleaning Agents:Deliver detergency in institutional and household applications. BIS certification requirements are compressing supplier bases toward certified producers with established analytical capabilities.
Surfactant applications anchor current volume. Emulsifier demand is climbing the fastest as agrochemical formulators upgrade specification requirements.
End User:
End-user concentration determines margin structure, with personal care and agrochemical segments offering divergent pricing power and technical service intensity.
- Personal Care:Rinse-off and leave-on cosmetic formulations require batch-level ethylene oxide residual documentation. CDSCO notifications mandate dioxane testing certificates prior to market placement, consolidating procurement toward BIS-certified suppliers.
- Agrochemicals:Crop protection emulsions demand hydrolytic stability and narrow ethylene oxide distribution. Gujarat's specialty chemicals cluster anchors domestic formulation activity with integrated supply from Ahmedabad's oleochemical base.
- Household Products:Laundry detergents and hard surface cleaners specify standard-grade ethoxylates with cost-optimized hydrophilic-lipophilic balance profiles.
- Industrial Cleaning:Institutional and commercial maintenance applications prioritize bulk volume procurement with formula customization for specific substrate compatibility.
Personal care represents the most profitable segment per kilogram. Agrochemicals are gaining share fastest as domestic crop protection manufacturing expands.
Distribution Channel:
Channel selection reflects volume concentration and technical service requirements across customer segments.
- Direct Sales:Annual contract negotiations between ethoxylate manufacturers and large fabric finishers in Surat and Bhiwandi displace traditional chemical traders. This pattern dominates textile wet processing where volume concentration enables formula customization.
- Distributors:Regional chemical traders serve fragmented personal care and household product manufacturers lacking procurement scale for direct manufacturer relationships.
- Specialty Stores:Technical service-oriented outlets support small-batch formulators with application guidance and regulatory documentation assistance.
- Online Retail:Emerging channel for standard-grade materials serving research institutions and pilot-scale formulation development.
Direct sales channels capture the highest-value relationships. Distributor-mediated supply is expanding most quickly to serve Maharashtra's fragmented SME formulator base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's personal care hub commands premium pricing power over Gujarat's agrochemical belt, reflecting divergent purity standards and technical service intensity across India's ethoxylate demand centers.
Maharashtra
Mumbai's personal care manufacturers drive sulfate-free surfactant procurement for shampoo and body wash reformulations. CDSCO cosmetic ingredient notifications mandate batch-level ethylene oxide residual documentation and dioxane testing certificates prior to market placement. Large formulators in Mumbai consolidate supplier bases toward BIS-certified producers with established analytical capabilities.
Gujarat
Ahmedabad's oleochemical base anchors integrated supply for crop protection emulsions requiring hydrolytic stability and narrow ethylene oxide distribution. The PLI scheme for specialty chemicals channels capital toward import-substitution grades previously sourced from Southeast Asian suppliers. Surat's textile processors negotiate direct mill procurement contracts for APEO-free alternatives in institutional cleaning applications.
Karnataka
Bengaluru's personal care and homegrown formulation startups generate emerging demand for small-batch ethoxylates with regulatory documentation support. State pollution control boards enforce CEA environmental compliance mandates for effluent discharge from ethoxylation operations. Specialty chemical distributors serve fragmented SME formulators lacking procurement scale for direct manufacturer relationships.
Tamil Nadu
Chennai's industrial corridor hosts textile wet processing and leather chemical applications specifying standard-grade ethoxylates with cost-optimized hydrophilic-lipophilic balance profiles. BIS certification tightening compresses input specifications across domestic supply chains. Regional chemical traders mediate supply for household product manufacturers in Coimbatore's industrial belt.
Telangana
Hyderabad's pharmaceutical and agrochemical formulation activity generates specialized emulsifier demand with narrow-range ethoxylation performance requirements. CDSCO and state regulators align on purity documentation for cross-sector chemical applications. Emerging toll manufacturing capacity serves regional formulators lacking dedicated high-pressure reactor infrastructure.
India Ethoxylates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, capturing margin through feedstock control and technology licensing. India's ethoxylate competitive structure fragments across integrated petrochemical players, oleochemical-anchored specialists, and technology-licensed joint ventures. Three archetypes dominate: ethylene oxide-integrated manufacturers with captive feedstock, backward-integrated oleochemical producers, and narrow-range technology licensees. Competitive moves center on capacity expansion for BIS-compliant grades and strategic partnerships for toll manufacturing access.
Within the integrated feedstock tier, India Glycols Limited and Godrej Industries Limited exemplify divergent integration strategies—one through ethylene oxide captivity, the other through oleochemical backward integration. Clariant IGL Specialty Chemicals Private Limited occupies the technology-licensed specialist position, representing narrow-range ethoxylation capability transfer. These three anchors illustrate how competitive positioning in India's ethoxylate landscape depends on upstream control depth and technology access rather than scale alone.
| Leading Market Players |
|---|
| Core Chemicals Pvt. Ltd. |
| Matangi Industries |
| Godrej Industries Limited |
| Rimpro-India |
| Fibrol Non-Ionics Pvt. Ltd. |
| Clariant IGL Specialty Chemicals Private Limited |
| Esteem Industries Pvt. Ltd. |
| India Glycols Limited |
| APL |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Maharashtra's BIS-certified ethoxylate production is tightening supplier pricing power while compressing margins for non-integrated toll manufacturers competing on standard-grade volumes. This utilization imbalance rewards ethylene oxide-integrated producers with captive feedstock positions, forcing reformulation investments from personal care brands seeking sulfate-free surfactant security.
Pricing Analysis
The customization-premium spread between narrow-range ethoxylates and commodity fatty alcohol grades is collapsing as catalyst technology licensing democratizes performance-tier production. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification status, ethylene oxide distribution width, and volume contract duration. Cost compression in standard-grade materials is intensifying because toll manufacturing fragmentation erodes batch-size premiums. SME formulators in Karnataka exhibit highest price sensitivity, while agrochemical emulsifier buyers in Gujarat prioritize hydrolytic stability over unit cost.
Supply Chain Analysis
Third-party contract ethoxylation capacity concentrates among Clariant IGL Specialty Chemicals, Rimpro-India, and regional toll operators in Gujarat's specialty chemicals cluster. Manufacturing draws from ethylene oxide feedstock anchored in India Glycols' integrated Kashipur complex, fatty alcohol streams from Godrej Industries' oleochemical operations, and imported lauryl alcohol for APEO-free substitution grades. Single-source vulnerability runs through ethylene oxide supply interruptions at integrated petrochemical hubs. Distribution runs through direct mill procurement contracts for Surat textile processors and distributor-mediated channels serving fragmented Maharashtra personal care SMEs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as PLI scheme incentives accelerate import-substitution capacity for high-purity grades previously sourced from Southeast Asian suppliers. Sulfate-free surfactant adoption in personal care formulations provides structural tailwind for domestic ethoxylate demand growth.
For Market Incumbents: Harden BIS-certified capacity positions through effluent treatment upgrades meeting CEA environmental mandates, insulating against regulatory disqualification of toll competitors. Deepen backward integration into oleochemical feedstocks to neutralize ethylene oxide price volatility exposure from non-captive supply. Narrow-range ethoxylation technology licensing from European partners provides defensive moat against commodity-grade margin erosion. For New Entrants and Emerging Players: Karnataka's underpenetrated personal care formulation base offers white-space opportunity for small-batch ethoxylates with CDSCO documentation support. Toll manufacturing access bypasses capital intensity of high-pressure reactor infrastructure, enabling service-based entry without capacity ownership. Institutional cleaning segments in Tamil Nadu present fastest-penetration target for APEO-free lauryl alcohol alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward technology-licensed specialists with established narrow-range ethoxylation capability and BIS analytical infrastructure. Long-term viability hinges on REACH-equivalent harmonization completion and feedstock integration depth. The signal to watch is ethylene oxide pricing volatility duration and pace of APEO regulatory phase-out enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemicals | Godrej Industries' captive fatty alcohol supply neutralizes feedstock cost swings for ethoxylate production. |
| Narrow-Range Ethoxylation Technology Licensing | Clariant IGL's catalyst systems enable premium-grade manufacturing without historical specialty capital requirements. |
| PLI Scheme Capacity Expansion | Government incentives channel investment toward import-substitution grades reducing Southeast Asian supply dependence. |
| Direct Mill Procurement Contracts | Surat textile processors bypass distributors, enabling formula customization and volume-based pricing negotiation. |
| Toll Manufacturing Network Buildout | Asset-light contract ethoxylation lowers entry barriers for regional formulators lacking dedicated reactor infrastructure. |
Research Methodology
A spread of perspectives from plant managers at integrated ethoxylate manufacturers, procurement leads at Maharashtra personal care formulators, distribution channel partners in Gujarat's specialty chemicals corridor, and technical R&D directors at agrochemical emulsifier producers converged on the working assumptions. Secondary validation drew from BIS certification registries, CDSCO cosmetic ingredient notifications, CEA environmental compliance records, and customs trade data for ethylene oxide derivatives. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down capacity assessments across India's ethoxylation reactor base.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions including grade tier (commodity vs narrow-range), end-use industry (personal care, agrochemicals, textiles, institutional cleaning), packaging format (bulk tanker, drum, intermediate bulk container), and regional production hub (Maharashtra, Gujarat, Tamil Nadu). CAGRs derived from ethylene oxide feedstock cost trajectory assumptions, BIS harmonization timeline scenarios, and substitution rates for APEO-free alternatives. Industry-specific inputs incorporated PLI scheme disbursement schedules and CDSCO purity documentation enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by ethylene oxide-integrated petrochemical players or accelerated REACH-equivalent BIS adoption would shift outcomes beyond modeled ranges. Cross-checking against Southeast Asian ethoxylate export pricing and European narrow-range technology licensing terms is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Resorcinol Market
Chemicals
Betaine Market
Chemicals
Cumene Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Periodic Acid Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Paint Stripper Market
Chemicals
Tributyl Phosphate Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Electroplating Chemicals Market
Chemicals
Allyl Alcohol Market
Chemicals
North America Tartaric Acid Market
Chemicals
Calcium Hydroxide Market
Chemicals
Global Cresols Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Detergent Alcohols Market