
 Chemical Distribution Market | 2026-2036
Chemical Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Distribution Market Analysis
Biobased solvent formulations is hardening cost structures for traditional petrochemical intermediates. Brenntag AG leverages its European terminal network to secure feedstock access for specialty blends. Univar Solutions anchors North American demand through technical service centers that co-develop formulations with industrial customers. IMCD competes by embedding application laboratories inside regional hubs, shortening development cycles for coatings and adhesives producers.
Chemical distribution encompasses the procurement, warehousing, blending, and delivery of industrial chemicals with specifications ranging from bulk sulfuric acid at technical grade to pharmaceutical excipients meeting USP-NF monographs, serving as the critical intermediary between producers and downstream manufacturing operations. Specialty chemicals command margin premiums due to technical support requirements and regulatory documentation burdens, while bulk chemicals operate on throughput efficiency and logistics optimization. The coatings application segment draws intensive distributor investment as VOC regulations in multiple jurisdictions force continuous reformulation cycles requiring just-in-time delivery of compliant raw materials.
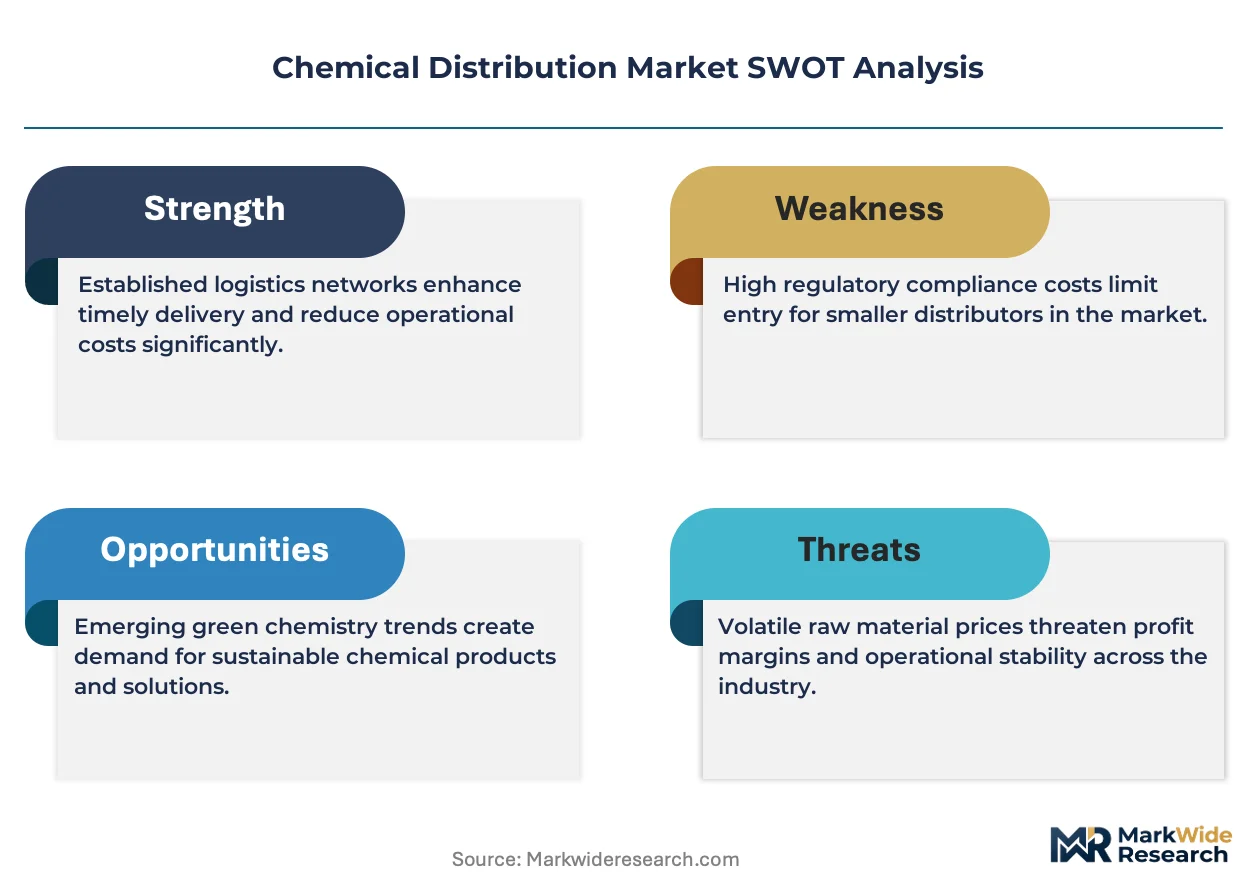
EPA enforcement of TSCA Section 5 premanufacture notifications shapes which novel chemicals enter commercial distribution channels in the United States, while REACH registration dossiers in Europe determine market access for substances above one-ton thresholds. FDA oversight of pharmaceutical raw materials under IPEC-PQG guidelines imposes qualification protocols that distributors must maintain across temperature-controlled supply chains. Stakeholders must weigh capital allocation between automated bulk handling infrastructure and high-touch specialty technical services as regulatory complexity diverges across chemical categories.
Market Dynamics
REACH registration dossiers in Europe are forcing distributors to consolidate supplier networks as substance authorization thresholds tighten, while biobased feedstock mandates in multiple jurisdictions reconfigure procurement priorities across specialty chemical portfolios.
Growth Catalysts
- Pharmaceutical excipient qualification:FDA oversight under IPEC-PQG guidelines drives distributor investment in temperature-controlled infrastructure for active pharmaceutical ingredient supply chains.
- REACH substance authorization:ECHA's tightening of SVHC candidate lists compels downstream manufacturers to seek pre-qualified distribution partners with compliant documentation systems.
- Coatings reformulation cycles:VOC regulations across Germany, France, and Italy force continuous raw material substitution, accelerating just-in-time delivery requirements for compliant solvents and resins.
Market Restraints
- Petrochemical feedstock volatility:Naphtha and natural gas liquid price swings compress margin predictability for commodity chemical intermediates stored in bulk terminals.
- Specialty chemical supply concentration:Pharmaceutical-grade solvents and high-purity reagents source predominantly from German and Swiss manufacturing clusters, creating single-point vulnerability.
- TSCA Section 5 friction:EPA premanufacture notification timelines for novel chemicals extend market entry delays, freezing distributor inventory planning for innovative formulations.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH guidelines creates qualified distributor demand for excipient supply chains serving generic API producers in Hyderabad and Ahmedabad clusters.
- EU Green Deal biobased mandates:Renewable carbon content requirements in packaging and coatings open technical service contracts for distributors blending bio-attributed intermediates.
- Digital inventory integration:ERP-to-ERP connectivity between distributor warehouses and customer MRP systems enables vendor-managed inventory programs in automotive coatings supply chains.
Industry Challenges
- Regulatory affairs specialization:REACH dossier maintenance, SDS authoring, and country-of-origin certification require scarce technical staff that distributors struggle to recruit and retain.
- Multi-temperature infrastructure:Simultaneous storage of ambient bulk acids, refrigerated pharmaceutical excipients, and frozen biologics demands segmented warehouse capex with diverging payback periods.
- Legacy system integration:Customer portals for order tracking and regulatory document retrieval must interface with decades-old ERP platforms prevalent in industrial chemical purchasing departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Distribution Market |
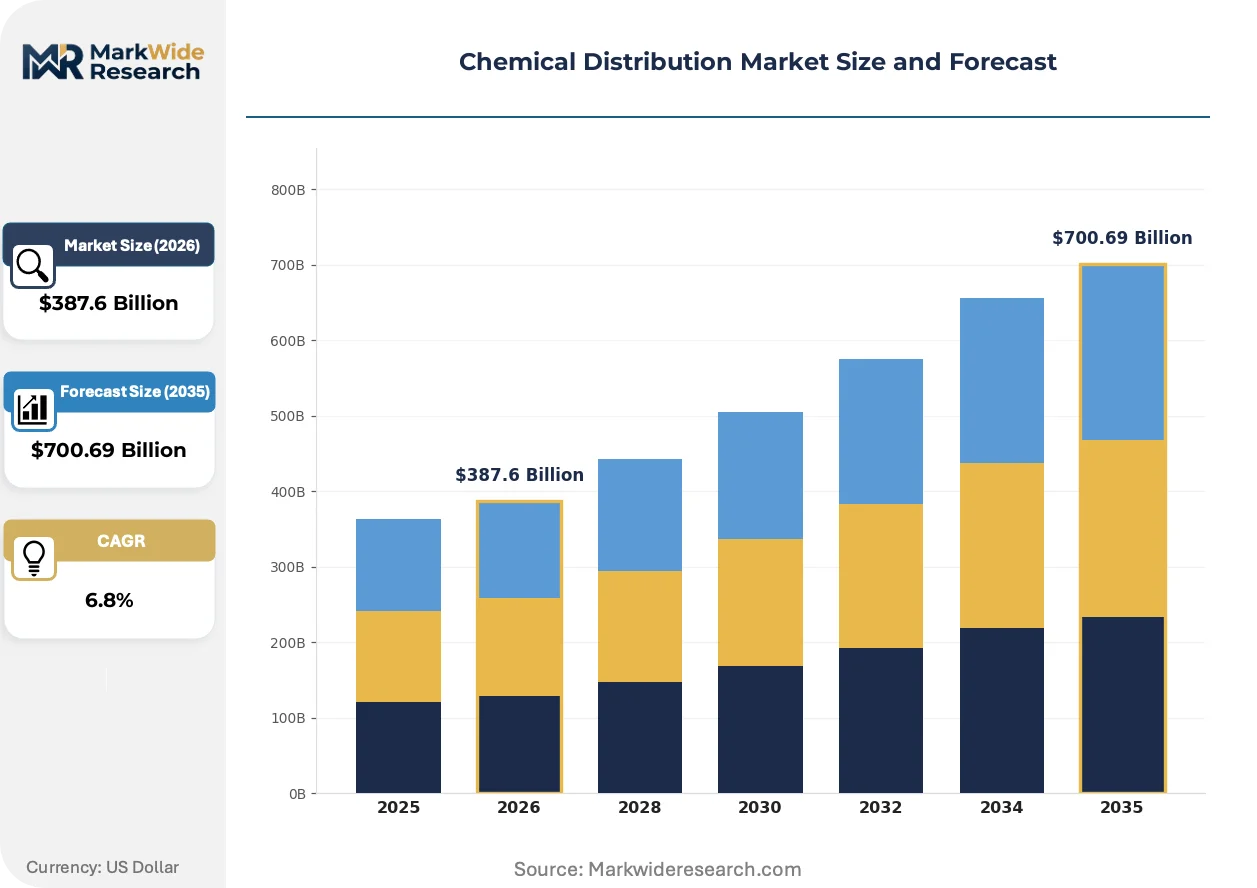
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Chemicals, Specialty Chemicals, Commodity Chemicals, Fine Chemicals Application: Agriculture, Pharmaceuticals, Food & Beverage, Coatings Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retailer Sales Customer Type: Manufacturers, Distributors, Retailers, End Users |
| Companies Covered | Brenntag AG, Univar Solutions Inc., Tricon Energy, Nagase & Co, IMCD, Helm AG, Azelis, Barentz, ICC Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Distribution Market Emerging Trajectories
Digital twin technology is compressing formulation development timelines as distributors embed predictive modeling tools within technical service offerings, while sustainability verification requirements penetrate procurement specifications.
Blockchain-enabled provenance tracking is modularizing supply chain transparency for pharmaceutical and food-contact chemicals. European distributors serving cosmetics and personal care manufacturers adopt distributed ledger systems to authenticate batch-level origin documentation. This technology is modularizing compliance cost structures by automating audit trail generation that previously required manual document reconciliation across multiple supplier tiers.
EU F-Gas Regulation phase-down schedules are forcing refrigerant gas distributors to pivot portfolios toward hydrofluoroolefin alternatives and natural refrigerant blends. Industrial cold chain operators face retrofit requirements for existing equipment, creating technical advisory demand from distributors with application engineering capabilities. The coatings and adhesives segment responds by qualifying low-global-warming-potential blowing agents for polyurethane formulations ahead of mandated phase-out dates.
Consolidated procurement desks at multinational coatings manufacturers now mandate single-source distributor relationships with integrated formulation support, displacing fragmented multi-vendor purchasing. Technical service contracts bundle raw material supply with application laboratory access and regulatory documentation management. This concentration is most visible in German automotive OEM supply chains, where tier-one paint shops demand distributor co-location for just-in-time color-matching and VOC compliance verification.
Chemical Distribution Market Segmentation
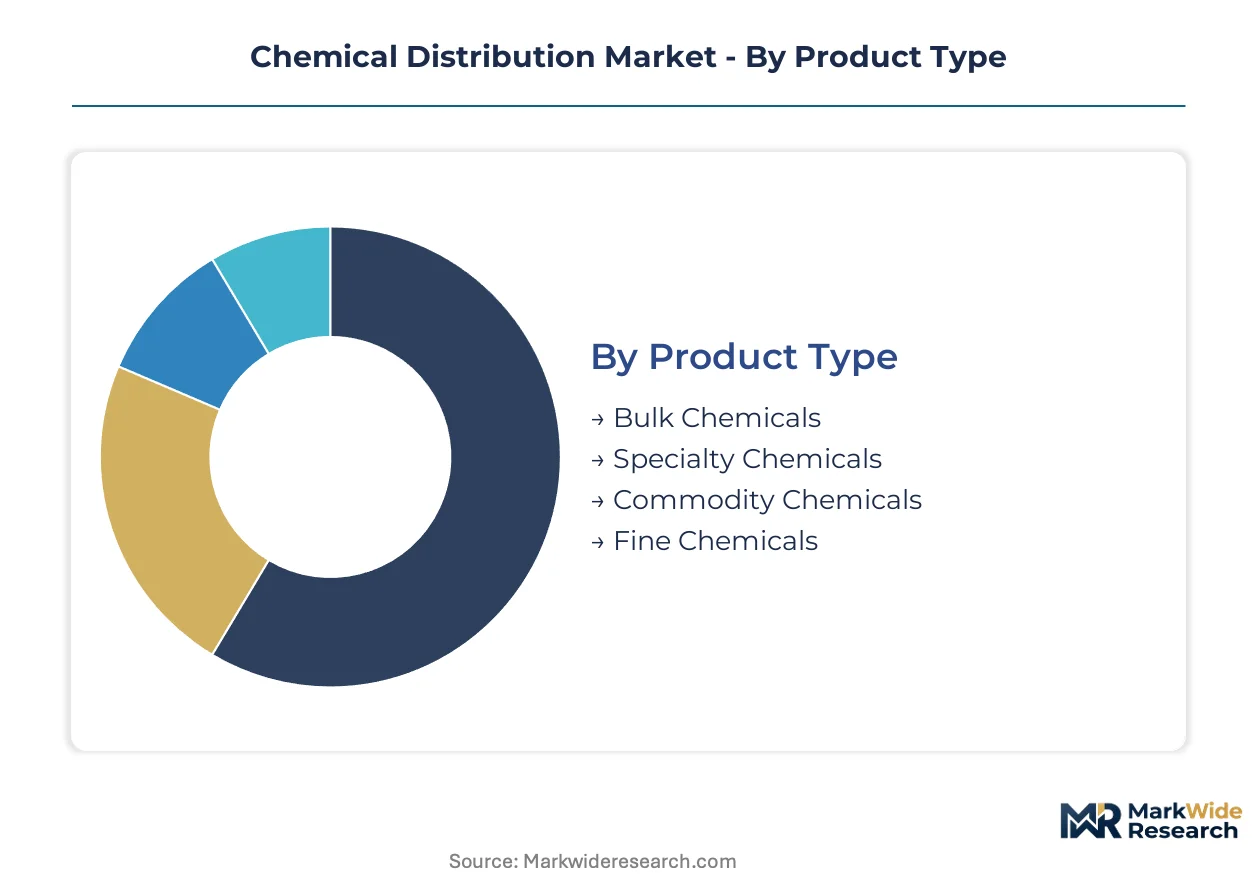
Chemical distribution segmentation reveals divergent margin structures and service intensity requirements. Product chemistry determines storage infrastructure investment, while application end-use dictates regulatory compliance burden and technical support depth.
Product Type:
Buyers in this category separate by specification tolerance and documentation requirements rather than volume alone.
- Specialty Chemicals:High-purity substances with defined performance characteristics requiring certificate-of-analysis documentation and application technical support. Pharmaceutical formulation houses in Germany's industrial corridor drive specification intensity as REACH SVHC screening tightens.
- Bulk Chemicals:Undifferentiated commodities traded on specification grade and delivered via tanker, railcar, or pipeline with minimal value-added services. Margin compression from naphtha feedstock volatility forces distributors toward terminal network efficiency.
- Commodity Chemicals:Standardized intermediates such as methanol, acetone, and toluene moving through high-velocity distribution centers.
- Fine Chemicals:Low-volume, high-specification compounds for pharmaceutical and agrochemical synthesis requiring batch-level traceability.
Volume sits with Bulk Chemicals; growth tilts toward Specialty Chemicals.
Application:
Regulatory jurisdiction determines distributor capability requirements more than chemistry complexity.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients governed by FDA IPEC-PQG guidelines and EMA GMP standards. Cold chain integrity and qualification documentation separate qualified distributors from commodity handlers.
- Coatings:Architectural and industrial formulations facing VOC limits under Germany's TA Luft, France's Decree 2021-655, and Italy's Legislative Decree 161. Continuous reformulation cycles demand just-in-time solvent and resin delivery.
- Agriculture:Fertilizer and crop protection chemicals distributed through seasonal demand patterns with storage cost seasonality.
- Food & Beverage:Food-grade acids, preservatives, and processing aids requiring FSSC 22000 certification and allergen segregation protocols.
Coatings commands the densest technical service investment; pharmaceuticals shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects customer procurement sophistication and order fragmentation.
- Direct Sales:Relationship-based contracting for large-volume industrial accounts with integrated supply chain planning. ERP-to-ERP connectivity enables vendor-managed inventory programs.
- Wholesalers:Intermediate stocking points serving fragmented regional manufacturers with consolidated SKU availability and shorter lead times.
- Online Sales:Self-service portals for standard products with transparent pricing and rapid reordering functionality.
- Retailer Sales:Small-package formats for maintenance-repair-operations customers and specialty trade channels.
Direct Sales retains value concentration; Online Sales gains share fastest.
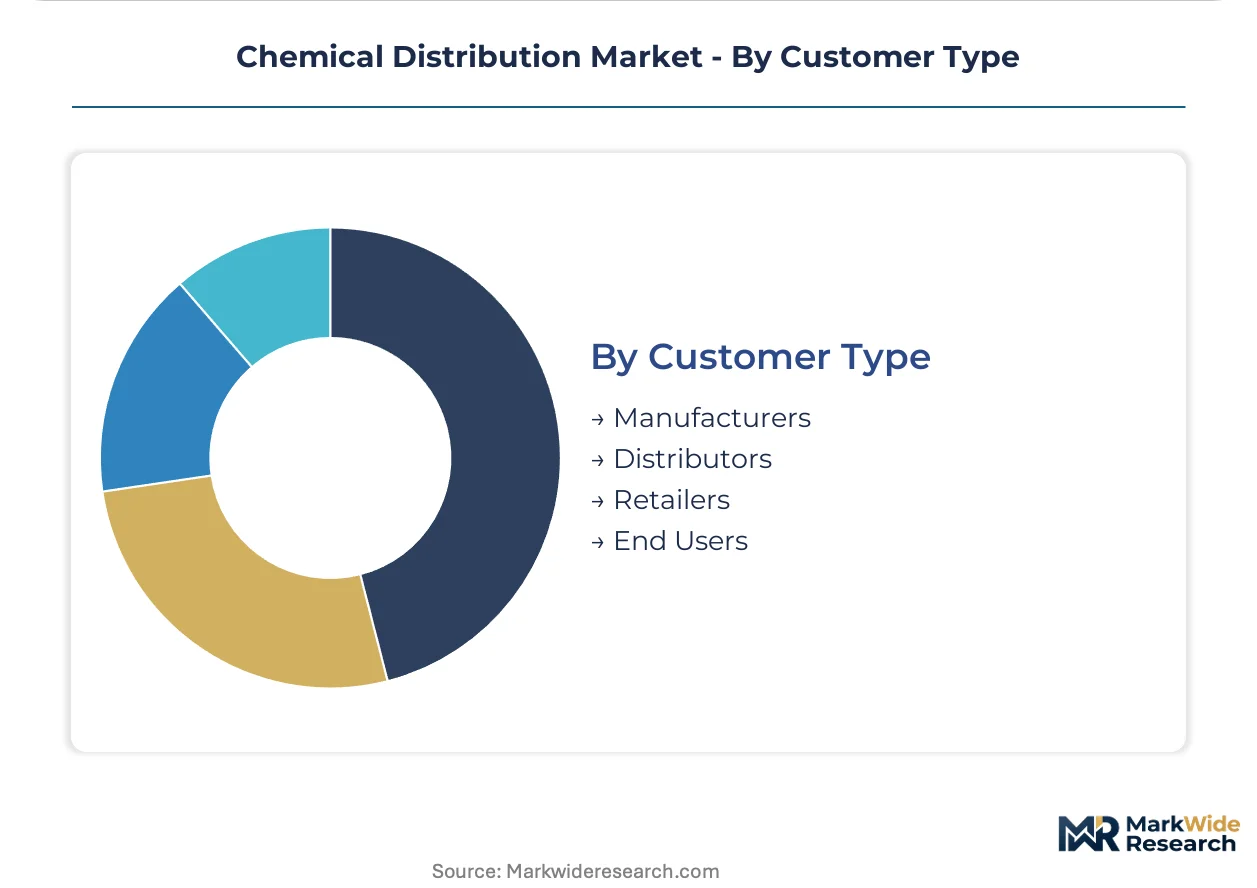
Customer Type:
Procurement scale and technical integration depth define service level differentiation.
- Manufacturers:Downstream chemical processors and formulators requiring co-development partnerships and regulatory documentation bundles. Automotive OEM paint shops in Germany mandate distributor co-location for color-matching support.
- Distributors:Secondary wholesalers and regional redistributors purchasing for geographic or niche market coverage.
- Retailers:Trade channel outlets serving professional applicators and institutional maintenance buyers.
- End Users:Direct consumption by industrial facilities with captive chemical processing or treatment requirements.
Manufacturers absorb the deepest technical engagement; End Users are expanding most quickly as direct sourcing platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for qualified chemical distribution partners clusters in manufacturing-intensive economies with stringent regulatory environments. REACH compliance documentation and pharmaceutical-grade cold chain infrastructure separate premium distributors from commodity handlers across major industrial corridors.
Germany
Automotive OEM paint shops in Bavaria and Baden-Württemberg mandate distributor co-location for just-in-time color-matching and VOC verification under TA Luft standards. ECHA's SVHC candidate list expansion compels downstream manufacturers to pre-qualify distribution partners with compliant documentation systems. The Rhine-Ruhr industrial corridor anchors specialty chemical warehousing investment for coatings and adhesives producers.
United States
EPA enforcement of TSCA Section 5 premanufacture notifications shapes which novel chemicals enter commercial distribution channels. Gulf Coast petrochemical terminals feed bulk intermediate demand from Texas and Louisiana processors. Houston's concentration of specialty chemical blenders drives technical service center placement for formulated product co-development.
China
Yangtze River Delta pharmaceutical manufacturers seek distributors with NMPA-aligned qualification protocols for active pharmaceutical ingredient supply chains. Dual carbon goals accelerate biobased solvent procurement mandates across coatings producers in Jiangsu and Zhejiang provinces. Shanghai's free-trade zone infrastructure supports temperature-controlled import logistics for high-purity reagents.
India
CDSCO alignment with ICH guidelines creates qualified distributor demand for excipient supply chains serving generic API producers. Hyderabad and Ahmedabad pharmaceutical clusters require cold chain integrity for temperature-sensitive raw materials. Gujarat's specialty chemical manufacturing belt drives regional warehousing investment with multi-temperature segmentation.
Switzerland
Swissmedic oversight of pharmaceutical raw materials imposes qualification protocols that distributors must maintain across alpine logistics corridors. Basel's concentration of fine chemical synthesis operations anchors high-purity reagent distribution for agrochemical and pharmaceutical R&D. The country's central European positioning enables cross-border supply chain coordination with German and French manufacturing bases.
Chemical Distribution Market Vendor Landscape
Portfolio diversification dominates the current landscape as distributors balance bulk terminal efficiency against specialty technical service investments. The vendor base organizes into three tiers: integrated multinational networks with regional hub density, mid-cap specialists with application laboratory capabilities, and regional wholesalers serving fragmented local demand. Scale-driven players compete through ERP-to-ERP connectivity for vendor-managed inventory programs. Technical specialists embed formulation chemists within customer facilities to capture reformulation cycle revenue.
Within the integrated network tier, Brenntag AG and Univar Solutions Inc. exemplify divergent geographic anchoring strategies. Brenntag's European terminal network secures feedstock access for specialty blends across German industrial corridors. Univar Solutions anchors North American demand through technical service centers that co-develop formulations with industrial customers. IMCD occupies a position between these models, embedding application laboratories inside regional hubs to shorten development cycles for coatings and adhesives producers.
| Leading Market Players |
|---|
| Brenntag AG |
| Univar Solutions Inc. |
| Tricon Energy |
| Nagase & Co |
| IMCD |
| Helm AG |
| Azelis |
| Barentz |
| ICC Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement desks at multinational coatings manufacturers now mandate single-source distributor relationships with bundled formulation support, forcing supply networks to absorb technical service costs into contract pricing. This buyer-driven consolidation compresses margin pools for fragmented multi-vendor distributors while rewarding integrated networks with vendor-managed inventory scale.
Pricing Analysis
Volume sits with bulk chemicals traded on spot indices; margin concentrates in specialty grades with certificate-of-analysis documentation and REACH dossier maintenance. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade separates qualified cold chain handlers from commodity terminal operators. Cost compression in bulk intermediates is intensifying because naphtha feedstock volatility erodes storage arbitrage. Automotive OEM paint shops show least price sensitivity due to co-location requirements, while regional wholesalers face maximum pressure from transparent online portals.
Supply Chain Analysis
Reverse logistics for temperature-sensitive pharmaceutical excipients requires qualified cold chain partners to manage return-to-sender protocols for rejected batches without cross-contamination. Supply concentrates in Germany's Rhine-Ruhr corridor for specialty blends, the US Gulf Coast for petrochemical intermediates, and Switzerland's Basel region for high-purity reagents. Feedstock flows draw from naphtha crackers, natural gas liquids fractionation, and biobased fermentation platforms. Single-source vulnerability in pharmaceutical-grade solvents creates structural risk. Distribution runs through regional hub-and-spoke networks with terminal-to-customer direct rail and tanker delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance tracking and digital twin formulation tools are displacing legacy manual documentation and batch-matching processes, compressing development cycles and compliance costs simultaneously.
For Market Incumbents: Hedge against biobased feedstock mandates by securing terminal access for renewable carbon intermediates before EU Green Deal phase-in deadlines. Backward integration into regional blending capacity protects margin pools from commodity traders. Prioritize ERP-to-ERP connectivity investments to lock in automotive OEM vendor-managed inventory contracts. For New Entrants and Emerging Players: Begin with technical service contracts for coatings reformulation cycles in secondary European markets where incumbent coverage remains thin. Indian pharmaceutical clusters in Hyderabad and Ahmedabad offer the most penetrable geography given CDSCO alignment with ICH guidelines. Lead with application laboratory co-location to bypass established terminal infrastructure advantages. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with embedded formulation capabilities and regional regulatory expertise. Long-term viability hinges on capturing reformulation cycle revenue rather than commodity throughput. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for documentation-intensive service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Blending | Captures margin from specialty formulation demand under REACH compliance pressure. |
| Application Laboratory Co-location | Secures just-in-time reformulation contracts with German automotive OEM paint shops. |
| Blockchain Provenance Tracking Deployment | Automates audit trails for pharmaceutical and food-contact chemical batch documentation. |
| Cold Chain Infrastructure Expansion | Qualifies distributors for FDA IPEC-PQG pharmaceutical excipient supply chains. |
| ERP-to-ERP Connectivity Investment | Enables vendor-managed inventory programs with consolidated coatings procurement desks. |
Methodological Framework
Independent corroboration across procurement leads at downstream coatings manufacturers, technical R&D directors at specialty blenders, distribution channel partners in European terminal networks, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with plant managers and cold chain logistics officers combined with secondary validation from customs/trade data, Cefic sector reports, SEC 10-K filings, and ECHA registration databases anchor supply-side assessments. Bottom-up terminal capacity modeling and top-down end-use consumption estimates triangulate volume figures.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window. The analytical framework models segmentation dimensions including grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from weighted average of historical trajectory and forward-looking capacity announcements. Forecast inputs incorporate REACH authorization timelines and biobased mandate phase-in schedules.
Naphtha price volatility, ECHA regulatory acceleration, and pharmaceutical manufacturing cluster migration are the dominant revision risks. Forecasts reflect assumptions about continued VOC regulation tightening and cold chain infrastructure investment pacing. Practitioners should monitor SVHC candidate list expansion and dual carbon goal implementation velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Inorganic Chemicals Market
Chemicals
Amyl Nitrite Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
5 Dinitroaniline Market
Chemicals
Calcium Hydroxide Market
Chemicals
Stimulation Materials Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Cummene Derivatives Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Hydroxyzine Imine Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Hypophosphorous Acid Market