
 Rotating Equipment Market | 2026-2036
Rotating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Rotating Equipment Market Analysis
Market Context
Carbon fiber reinforced polymer is broadening the design envelope for high-speed rotating components, reducing weight while maintaining centrifugal stress tolerance. Siemens leverages its digital twin platform to optimize turbine blade geometries across power generation installations. Baker Hughes anchors its position through in-house production of superalloy castings for downhole drilling motors. General Electric differentiates via integrated predictive maintenance systems that extend mean time between overhauls for aviation-derived gas turbines.
Technical Definition and Segments
Rotating equipment encompasses machinery where kinetic energy transfers through continuous angular motion, typically operating at speeds from hundreds to tens of thousands of revolutions per minute with critical balancing tolerances measured in grams per millimeter. These systems convert mechanical, electrical, or fluid power into process flow, compression, or generation output across continuous-process industries. Compressors command the largest installed base in oil and gas processing, while pumps exhibit the fastest replacement velocity in water treatment infrastructure due to abrasive service conditions. Electric drive technology dominates new installations, though mechanical coupling systems retain margin strength in hazardous environment applications where spark ignition risks persist.
Regulatory Frame and Outlook
The US EPA enforces New Source Performance Standards that mandate leak detection and repair protocols for rotating equipment in hydrocarbon service, while the EU F-Gas Regulation restricts fluorinated refrigerant use in compressor systems, redirecting demand toward ammonia and CO2 architectures. API 617 and ISO 10494 establish baseline design and testing protocols that govern international procurement specifications for centrifugal compressors and gas turbines. Stakeholders must monitor evolving carbon border adjustment mechanisms that will penalize embodied emissions in imported rotating machinery, reshaping supplier qualification criteria and regional sourcing decisions.
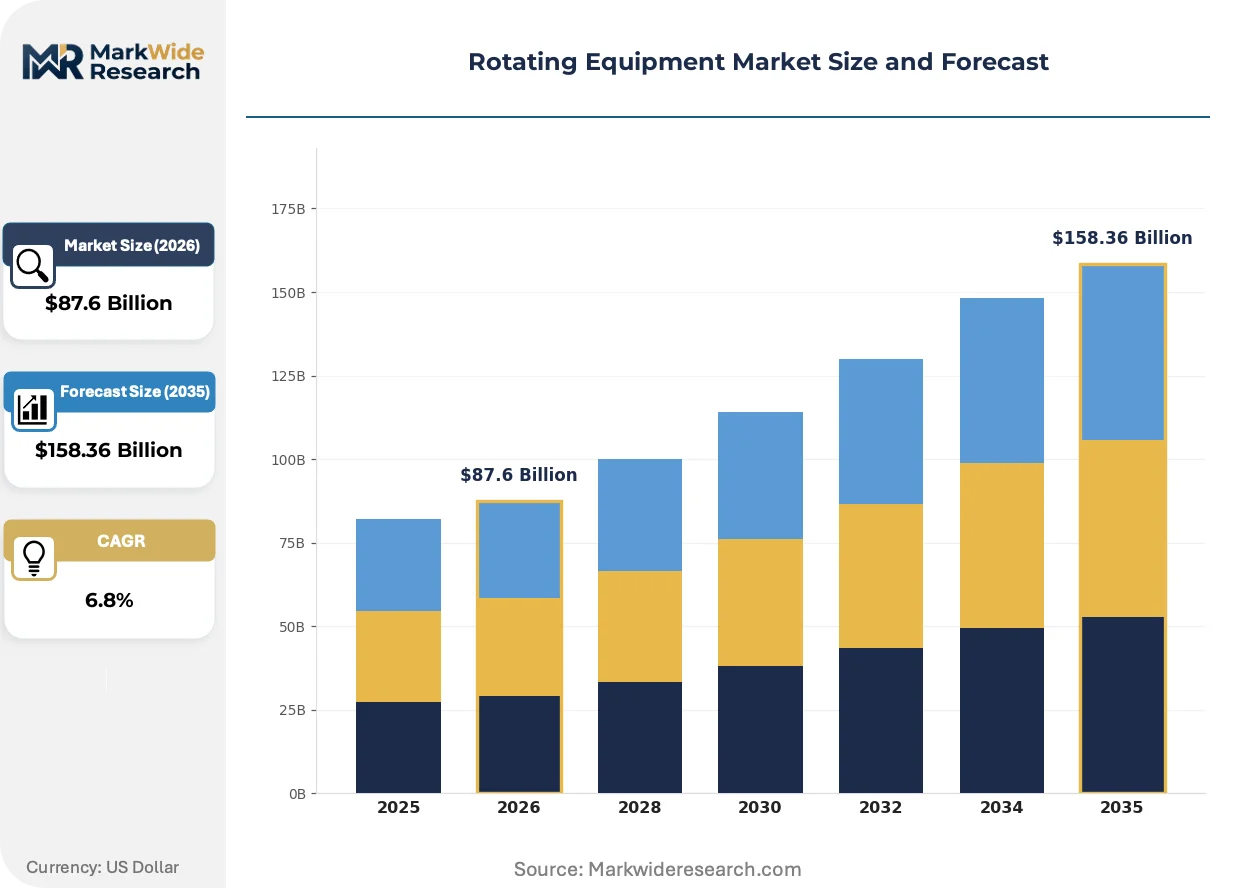
Market Dynamics
EPA methane emission standards are compressing replacement cycles for legacy compressor fleets while carbon fiber reinforced polymer expands the design envelope for high-speed rotating components, creating simultaneous push-pull forces across oil and gas infrastructure.
Growth Catalysts
- Permian Basin modernization:Shale operators in Texas and New Mexico are accelerating turbomachinery deployment to improve extraction efficiency and meet tightening environmental protocols.
- F-Gas Regulation redirection:The EU F-Gas Regulation restricts fluorinated refrigerant use in compressor systems, redirecting demand toward ammonia and CO2 architectures in industrial cooling applications.
- Digital twin integration:Predictive maintenance systems leveraging real-time vibration analysis and thermal monitoring are extending mean time between overhauls for power generation turbines.
Market Restraints
- Superalloy supply concentration:In-house production of nickel-based castings for downhole drilling motors concentrates with a limited supplier base, creating vulnerability to raw material price volatility.
- API 617 compliance friction:Centrifugal compressor procurement specifications governed by API 617 and ISO 10494 impose lengthy testing protocols that extend project timelines.
- Mechanical coupling substitution limits:Electric drive technology dominates new installations, yet hazardous environment applications where spark ignition risks persist retain mechanical systems with higher maintenance burdens.
Strategic Opportunities
- Water treatment pump velocity:Abrasive service conditions in municipal and industrial water infrastructure create fastest replacement velocity for centrifugal and positive displacement pumps.
- Carbon border adjustment preparation:Evolving carbon border adjustment mechanisms will penalize embodied emissions in imported rotating machinery, reshaping supplier qualification criteria toward regional sourcing.
- Ammonia architecture conversion:Industrial refrigeration end-users are retrofitting legacy compressor trains to handle ammonia working fluids ahead of phased fluorocarbon restrictions.
Industry Challenges
- Precision balancing skill scarcity:Critical balancing tolerances measured in grams per millimeter require specialized technicians that outpace current vocational training pipeline output.
- Legacy system integration complexity:Continuous-process industries face friction embedding predictive maintenance sensors into existing turbine and compressor control architectures.
- Leak detection certification timelines:New Source Performance Standards mandate leak detection and repair protocols that require third-party validation, extending commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotating Equipment Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Compressors, Fans, Turbines End User: Oil & Gas, Power Generation, Water Treatment, Mining Technology: Electric, Hydraulic, Pneumatic, Mechanical Market Segment: Industrial, Commercial, Residential, Others |
| Companies Covered | Siemens, General Electric, ABB, Honeywell International, Atlas Copco, Baker Hughes, Flowserve Corporation, Mitsubishi Heavy Industries, Sulzer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotating Equipment Market Emerging Trajectories
Active magnetic bearing systems and solid-state power electronics are converging to eliminate mechanical contact in high-speed rotating assemblies, while regulatory pressure on embodied carbon reshapes material selection across the value chain.
Carbon fiber reinforced polymer is electrifying the design space for turbine blades and impellers by reducing rotating mass while maintaining centrifugal stress tolerance. Power generation operators are adopting these composite architectures for high-speed applications above fifteen thousand revolutions per minute. This material transition is electrifying competitive positioning by enabling smaller bearing systems and reduced foundation requirements.
The EU F-Gas Regulation is compressing the installed base of hydrofluorocarbon-dependent compressor systems across cold chain and industrial process cooling. Equipment manufacturers are accelerating ammonia and transcritical CO2 platform development to maintain market access. Food processing and pharmaceutical cold storage facilities in Germany and the Netherlands face the most immediate retrofit pressure.
After-sales service unbundling is fragmenting traditional OEM maintenance contracts as independent service providers gain certification for API-compliant overhaul work. End-users in oil and gas processing are separating parts procurement from labor services to optimize capital deployment. This pattern is most visible in the US Gulf Coast refinery corridor where specialized repair shops cluster near petrochemical complexes.
Rotating Equipment Market Segmentation
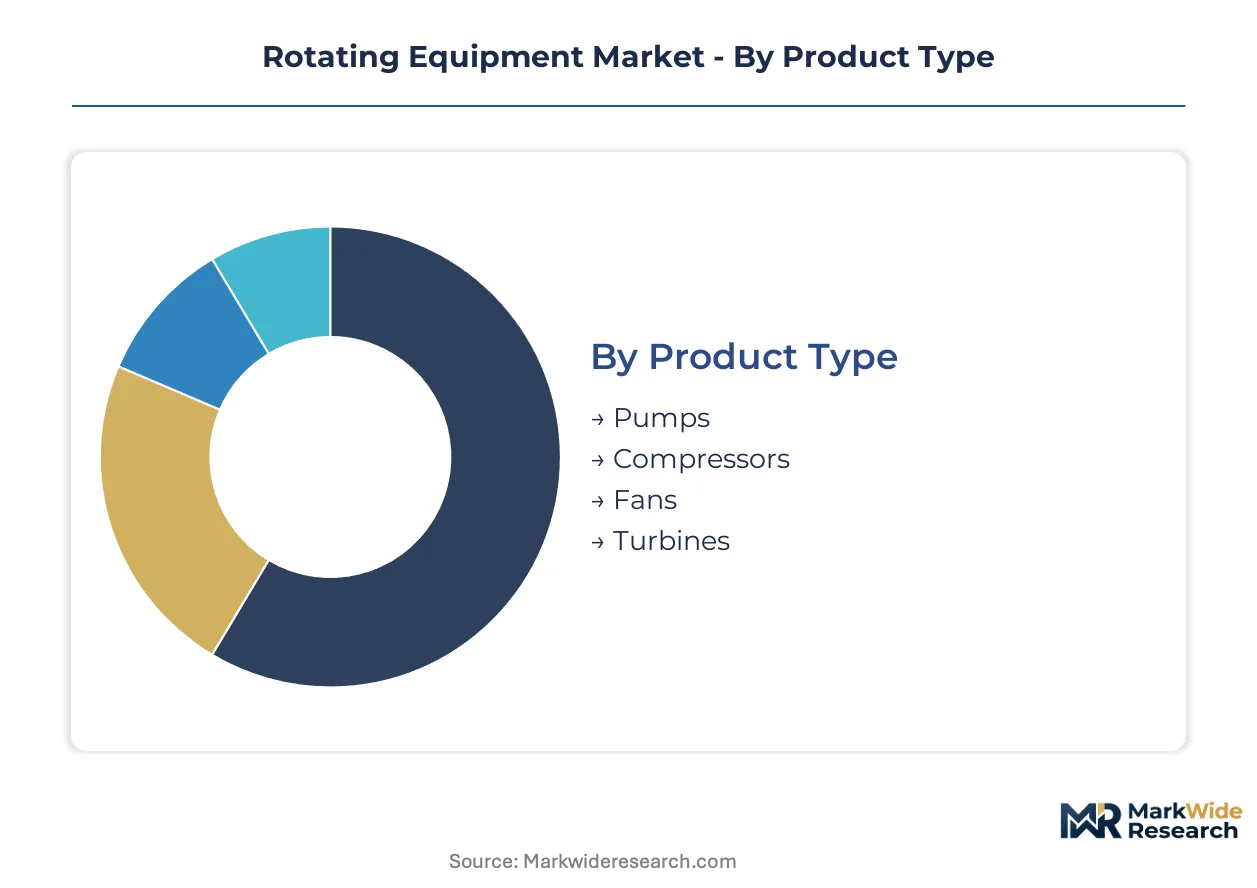
Rotating equipment procurement decisions pivot on duty cycle severity, fluid compatibility, and maintenance accessibility. Buyers segment purchases across product architecture, end-use environment, drive technology, and facility scale to match capital deployment with operational risk profiles.
Product Type:
Capital intensity and service interval predictability drive product selection more than initial unit cost.
- Pumps:Centrifugal and positive displacement architectures dominate water treatment and hydrocarbon transfer applications. Abrasive service conditions in municipal infrastructure create fastest replacement velocity, particularly in the Permian Basin where shale operators modernize produced water handling systems.
- Compressors:Centrifugal and reciprocating systems convert mechanical power into pressurized process flow across continuous-process industries. The US EPA methane emission standards compress replacement cycles for legacy fleets in Texas and New Mexico gas processing facilities.
- Fans:Axial and centrifugal impellers manage airflow in ventilation, combustion, and cooling applications. HVAC and power generation operators specify these for lower pressure-rise requirements where efficiency tolerance permits broader design margins.
- Turbines:Gas and steam expansion engines extract work from high-enthalpy fluid streams. Power generation installations in the US Gulf Coast corridor deploy these for baseload capacity where fuel flexibility and rapid startup capability justify premium capital outlay.
Volume sits with Pumps; growth tilts toward Compressors.
End User:
Regulatory exposure and process criticality determine specification stringency across buyer categories.
- Oil & Gas:Upstream extraction, midstream transport, and downstream refining operations demand API-certified equipment with leak detection integration. The US EPA New Source Performance Standards mandate repair protocols that accelerate turbomachinery deployment in the Permian Basin.
- Power Generation:Combined-cycle and peaking plants require gas turbines with predictive maintenance architectures. Siemens digital twin platforms optimize blade geometries for installations where mean time between overhauls determines economic viability.
- Water Treatment:Municipal and industrial infrastructure operators prioritize corrosion-resistant materials and redundant configurations. Abrasive conditions in filtration and sludge handling drive fastest replacement cycles among all end-use categories.
- Mining:Slurry pumping and ventilation systems operate under extreme load variability and contamination exposure. Remote site accessibility constraints favor modular designs with field-serviceable components over integrated precision assemblies.
Revenue concentrates in Oil & Gas; expansion accelerates most rapidly in Water Treatment.
Technology:
Spark ignition risk and precision control requirements segment drive system selection.
- Electric:Variable frequency drives and high-efficiency motors dominate new installations across power generation and water treatment. Solid-state power electronics enable precise speed control without mechanical coupling losses.
- Hydraulic:Fluid power transmission delivers high torque density for mining and heavy industrial positioning. These systems retain niche strength where overload protection and stall tolerance outweigh efficiency penalties.
- Pneumatic:Compressed air drives suit hazardous environments with strict spark containment requirements. Limited precision and energy density constrain deployment to secondary processes and safety-critical actuation.
- Mechanical:Direct coupling and gear transmission persist in explosive atmosphere applications where electric arc risks prohibit alternative architectures. Higher maintenance burdens and inflexible speed ratios limit growth trajectory.
Deployment share clusters with Electric; substitution pressure builds against Mechanical.
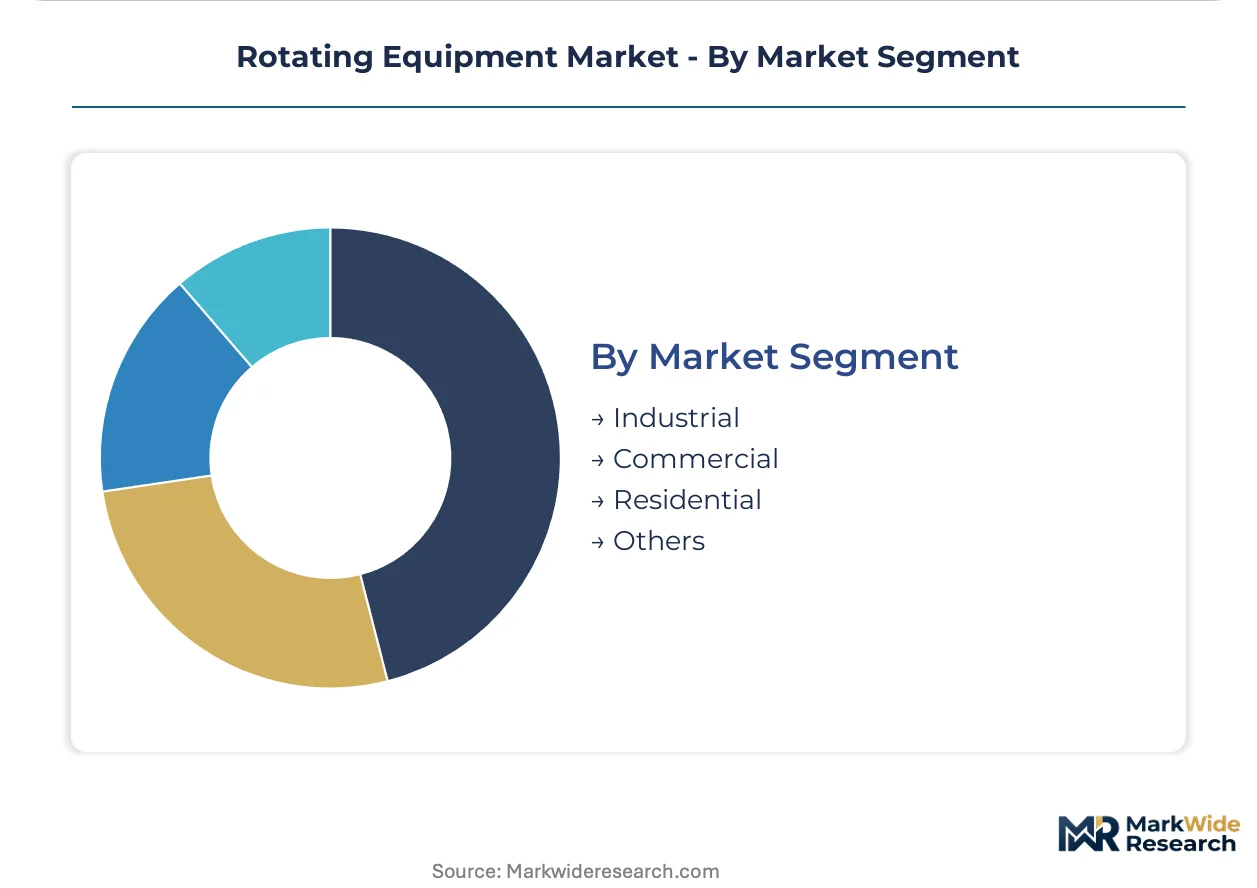
Market Segment:
Scale of operations and technical staffing depth differentiate procurement behavior.
- Industrial:Continuous-process facilities with dedicated maintenance organizations specify premium equipment with predictive monitoring integration. These buyers unbundle after-sales service to optimize capital deployment across multi-unit installations.
- Commercial:Distributed facilities with intermittent duty cycles prioritize first-cost minimization and vendor-managed maintenance contracts. HVAC and refrigeration applications in this segment face immediate EU F-Gas Regulation retrofit pressure.
- Residential:Small-scale pumping and ventilation equipment serves building systems with standardized performance requirements. Price sensitivity and installation simplicity dominate specification criteria.
- Others:Agricultural, marine, and specialized transport applications present fragmented demand with customized engineering requirements. Batch production economics limit supplier participation.
Unit volume accumulates in Industrial; penetration deepens fastest in Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rotating equipment concentrates in hydrocarbon-rich basins and power generation corridors where regulatory pressure and infrastructure age accelerate replacement cycles. National emission standards and industrial cluster development reshape procurement geography across major economies.
United States
Shale operators in Texas and New Mexico deploy advanced turbomachinery to improve extraction efficiency while EPA methane standards compress replacement cycles for legacy compressor fleets. The US Environmental Protection Agency enforces New Source Performance Standards mandating leak detection protocols. The Permian Basin anchors domestic demand as operators modernize produced water handling and gas processing infrastructure.
Germany
Industrial refrigeration end-users retrofit legacy compressor trains to handle ammonia working fluids ahead of phased fluorocarbon restrictions. The EU F-Gas Regulation restricts hydrofluorocarbon use in cooling systems. Food processing and pharmaceutical cold storage facilities in the Rhine-Ruhr corridor face immediate compliance-driven equipment turnover.
China
Power generation operators adopt carbon fiber reinforced polymer turbine architectures for high-speed applications above fifteen thousand revolutions per minute. The Ministry of Ecology and Environment advances dual carbon goals that elevate efficiency requirements for rotating machinery. The Yangtze River Delta cluster drives procurement for combined-cycle gas turbine installations with predictive maintenance integration.
Saudi Arabia
Downstream refining and petrochemical complexes specify API-certified equipment with integrated leak detection systems for hydrocarbon service. The national oil company mandates procurement specifications aligned with international design protocols. The Eastern Province industrial corridor concentrates demand for large-scale centrifugal compressors and gas turbine generator sets.
India
Municipal water treatment infrastructure drives fastest replacement velocity for abrasive-service pumps in filtration and sludge handling applications. The Central Electricity Authority promotes efficiency standards for rotating electrical machinery. Industrial clusters in Gujarat and Maharashtra expand procurement of corrosion-resistant centrifugal pumps for chemical process industries.
Rotating Equipment Market Vendor Landscape
Portfolio diversification dominates the current landscape as established players expand beyond core turbomachinery into integrated predictive maintenance systems. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with digital twin capabilities, specialized oilfield service providers with captive superalloy casting operations, and precision component specialists serving aftermarket overhaul demand. M&A activity and technology licensing agreements represent the primary competitive vectors reshaping market structure.
Among diversified industrial conglomerates, Siemens and General Electric exemplify the integrated platform approach combining hardware manufacturing with software-enabled service architectures. Baker Hughes occupies a position within the oilfield-specialist tier, leveraging in-house production capabilities for downhole drilling motor components. These three anchors illustrate how competitive positioning increasingly depends on vertical control over critical material supply chains and digital service layer integration rather than unit manufacturing scale alone.
| Leading Market Players |
|---|
| Siemens |
| General Electric |
| ABB |
| Honeywell International |
| Atlas Copco |
| Baker Hughes |
| Flowserve Corporation |
| Mitsubishi Heavy Industries |
| Sulzer |
| Others |
Supply Flow & Price Mechanics
Superalloy ingot price indices cascade through three distinct procurement tiers in rotating equipment manufacturing, compressing margins for standard-grade centrifugal compressors while insulating premium turbine suppliers with captive casting operations and long-term offtake agreements.
Pricing Analysis
High-volume pump and fan procurement runs through transactional spot markets with compressed margins, while specialized gas turbine and downhole motor contracts anchor on project-based engineering with embedded service bundles. Price differentiation hinges on API certification tier and after-sales monitoring integration, with unbundled maintenance contracts eroding OEM pricing power. Cost compression in mid-tier compressor segments intensifies as independent service providers gain API-compliant overhaul certification. Municipal water treatment buyers exhibit highest price sensitivity due to budget-constrained procurement cycles, whereas Permian Basin shale operators prioritize mean-time-between-overhauls metrics over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from oil majors and power utilities force qualification of secondary superalloy foundries in Germany, Japan, and the United States, reducing single-source vulnerability for nickel-based castings. Supply chains draw from concentrated rare earth processing in China for high-performance magnet materials, chromium ore from South Africa for corrosion-resistant alloys, and carbon fiber precursor from Japan and the United States for composite blade architectures. Tariff exposure on Chinese rare earth derivatives threatens cost structures for electric drive systems. Distribution runs through authorized distributor networks for aftermarket parts and direct OEM engagement for greenfield project specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
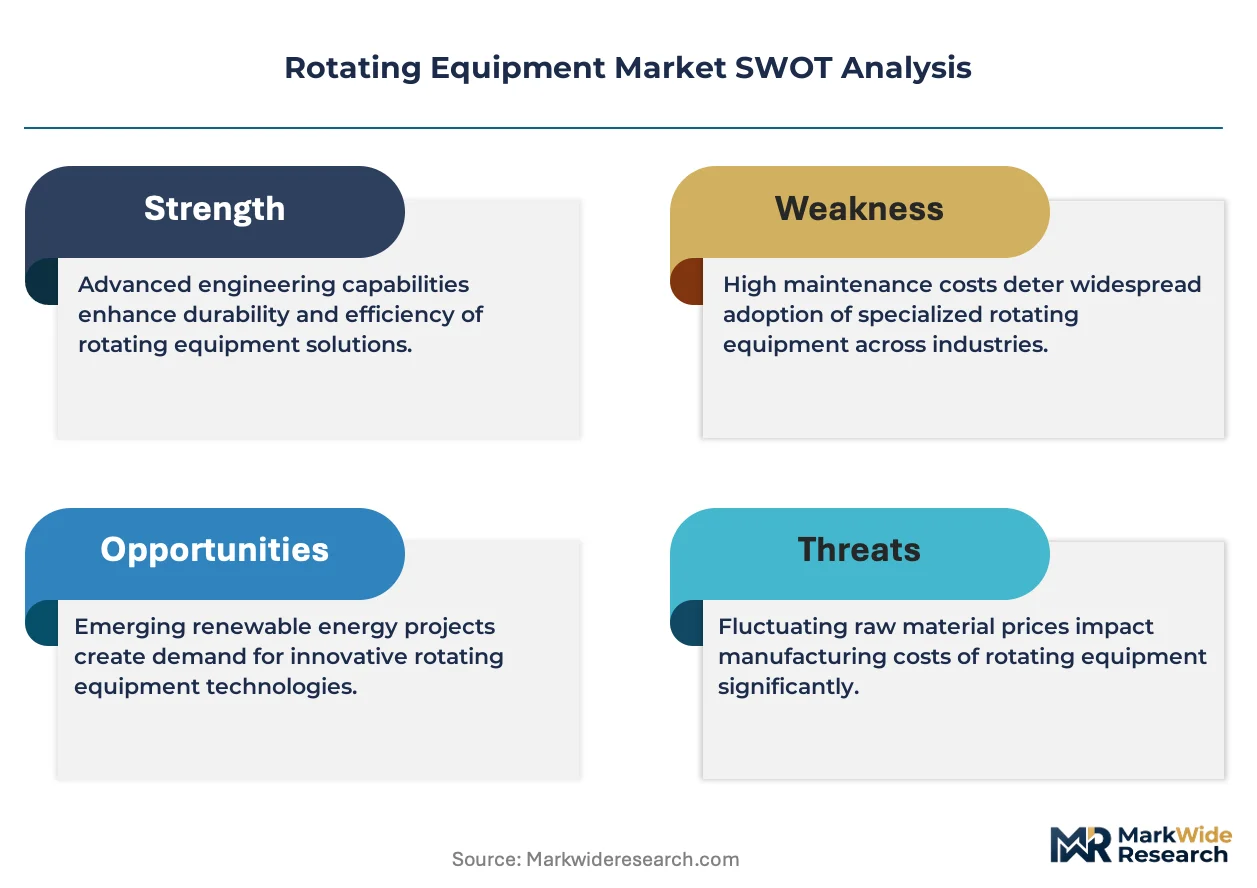
Carbon fiber reinforced polymer architectures are displacing conventional superalloy castings in high-speed rotating components, creating asymmetric transition risk for legacy forging-dependent suppliers and opening margin expansion for composite-integrated platforms.
For Market Incumbents: Cement supply security through backward integration into superalloy casting capacity or binding offtake agreements with qualified foundries, while accelerating digital twin platform deployment to capture predictive maintenance revenue streams threatened by independent service provider certification expansion. For New Entrants and Emerging Players: Enter via abrasive-service pump segments in Indian and Southeast Asian municipal water infrastructure, where fastest replacement velocity and limited incumbent aftermarket presence create white-space opportunity for corrosion-resistant composite impeller architectures sold through regional distributor partnerships. For Investors and Strategic Acquirers: The window for entry favors precision balancing service specialists with vocational training pipelines and API-certified overhaul capabilities, as skill scarcity outstrips replacement demand across Permian Basin and US Gulf Coast installations. Monitor EPA methane enforcement intensity as inflection signal for compressor fleet replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Captive supply of nickel-based components insulates Baker Hughes and Siemens from raw material volatility in turbine blade production. |
| Digital Twin Platform Deployment | Real-time vibration monitoring extends mean time between overhauls for General Electric power generation installations. |
| Ammonia Architecture Conversion | Retrofit capabilities for transcritical CO2 and ammonia systems secure EU market access ahead of F-Gas Regulation deadlines. |
| Independent Service Certification | API-compliant overhaul authorization fragments traditional OEM maintenance contracts across US Gulf Coast refinery corridors. |
| Carbon Fiber Composite Manufacturing Scale-Up | Reduced rotating mass enables fifteen-thousand-plus RPM applications while cutting foundation requirements for high-speed turbines. |
Methodological Framework
Multi-period observation of EPA enforcement actions, EU F-Gas regulatory filings, and Permian Basin capital expenditure announcements anchored the trend analysis, supplemented by interviews with plant maintenance directors at downstream refineries, OEM procurement teams at turbomachinery manufacturers, aftermarket service heads at independent repair shops, and project developers at combined-cycle power installations. Secondary validation drew from SEC 10-K equipment disclosures, API certification registries, customs trade data for superalloy and carbon fiber imports, and FERC filings for gas turbine installation permits. Bottom-up unit economics triangulated against top-down sector spending estimates.
The input-output matrix mapped compressor, pump, turbine, and fan shipments across product architecture, end-use environment, drive technology, and facility scale dimensions throughout the projection horizon. CAGRs derived from segment-level replacement cycle analysis, regulatory compliance-driven upgrade schedules, and efficiency improvement capital allocation patterns. Forecast inputs incorporated superalloy price elasticity coefficients and carbon fiber adoption S-curves for high-speed rotating components.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA methane standard acceleration or rare earth export restriction scenarios. Deviation in EU carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Submersible Pumps for Mining Sector Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Melt & Gear Pump Market