
 Liquid Hydrogen Market | 2026-2036
Liquid Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Hydrogen Market Outlook
Long-term offtake contracting is recalibrating how liquid hydrogen gets monetized, shifting revenue models from spot molecules to guaranteed supply agreements. Linde leverages its integrated production and distribution footprint across multiple continents to secure anchor customers. Air Liquide sustains technology leadership through proprietary large-scale liquefaction process expertise. Nel ASA specializes in electrolyzer-liquefaction coupling for green hydrogen pathways.
Liquid hydrogen consists of hydrogen gas cooled to approximately minus 253 degrees Celsius, achieving a density of 70.8 kilograms per cubic meter that enables efficient bulk transport and storage. Its primary industrial purpose centers on supplying high-purity hydrogen for aerospace propulsion, fuel cell mobility, and semiconductor manufacturing where gaseous delivery proves impractical. Production method segmentation shows electrolysis gaining structural momentum as renewable energy costs decline, while steam methane reforming retains volume dominance due to established infrastructure. Storage type segmentation positions cryogenic tanks as the margin pool where engineering differentiation commands premium pricing.
The US Inflation Reduction Act and the EU Green Deal are accelerating clean hydrogen qualification standards that determine tax credit eligibility and carbon border adjustments. Japan's METI hydrogen roadmap and South Korea's MFDS industrial gas frameworks are shaping import infrastructure requirements and purity specifications. Stakeholders must monitor regulatory stringency divergence between jurisdictions to avoid stranded asset risk in liquefaction capacity investments.
Market Dynamics
The Inflation Reduction Act hydrogen production tax credit is restructuring project economics across the liquid hydrogen value chain, compressing payback periods for liquefaction infrastructure and redirecting capital toward US Gulf Coast export corridors.
Growth Catalysts
- Heavy-duty trucking fleet procurement:Cryogenic fuel system orders from long-haul operators are scaling faster than gaseous hydrogen alternatives due to range-density requirements.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive hydrogen are accelerating clean qualification investments at Rotterdam and Hamburg terminal projects.
- Electrolyzer-liquefaction coupling:Integrated renewable-to-liquid systems are capturing margin pools previously lost to intermediate hydrogen handlers.
Market Restraints
- Cryogenic storage capex intensity:Vacuum-insulated tank fabrication requires specialized stainless steel alloys subject to nickel price volatility.
- Boil-off rate limitations:Physics-bound evaporative losses during maritime transport constrain route economics beyond 21-day sailings.
- SMR infrastructure lock-in:Existing steam methane reforming plants in Texas and Louisiana create path dependency resisting green hydrogen switching.
Strategic Opportunities
- Japan METI import infrastructure:Kobe and Yokohama terminal expansions offer offtake anchors for US exporters securing 15-year supply contracts.
- Semiconductor manufacturing purity demand:99.999% grade requirements from Samsung and TSMC fabs favor liquid over gaseous delivery modes.
- Ammonia cracking reconversion:Hydrogen release from ammonia carriers at destination ports opens arbitrage between hydrogen carriers without liquefaction at origin.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technicians for minus 253°C system maintenance command premium wages exceeding pipeline hydrogen operations by 40%.
- ASME Section VIII certification timelines:Pressure vessel approvals for novel tank designs extend development cycles 18-24 months beyond prototype completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Hydrogen Market |
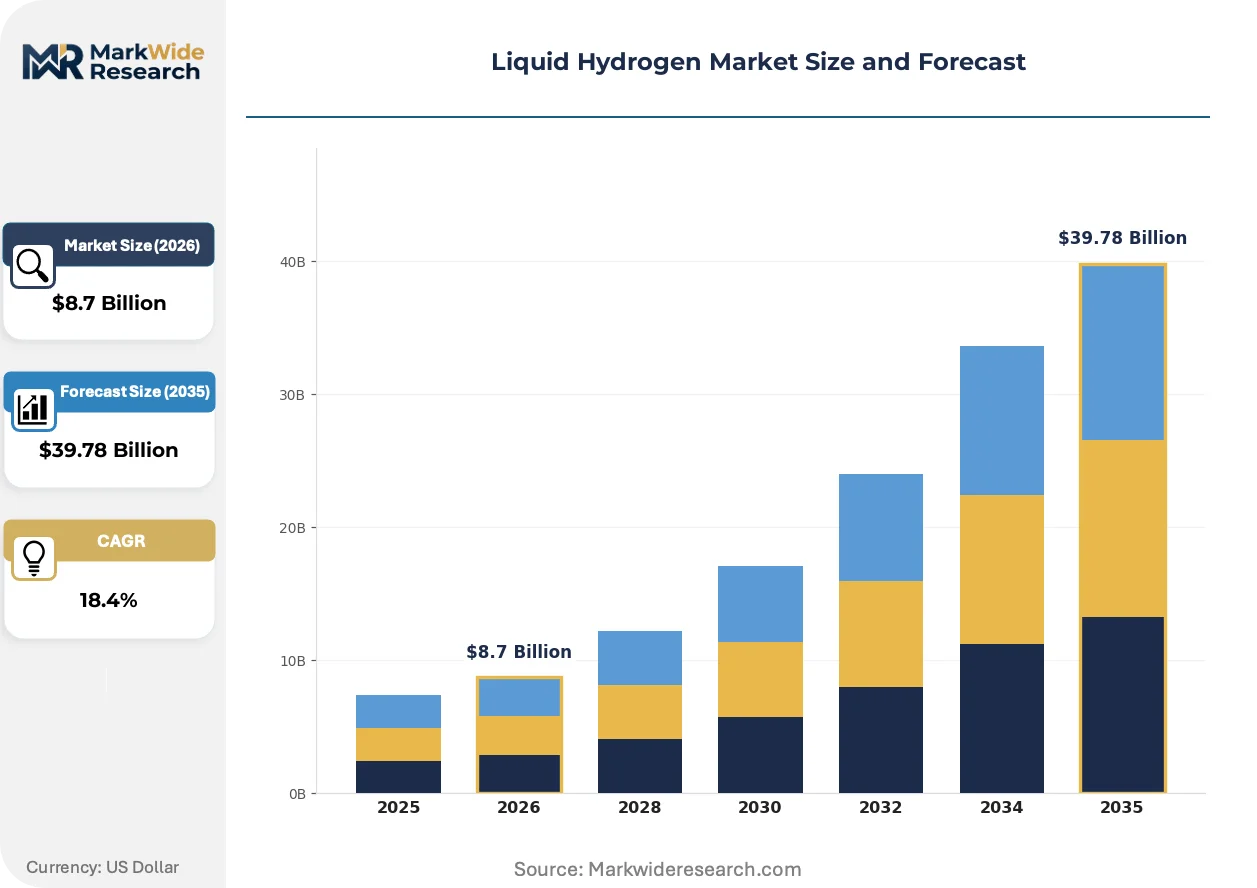
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Electronics, Fuel Cells, Transport Production Method: Steam Methane Reforming, Electrolysis, Coal Gasification, Cryogenic Distillation Storage Type: Cryogenic Tanks, Pressure Vessels, Bulk Storage, Transport Containers Distribution Channel: Pipeline, Truck Delivery, Rail Transport, Marine Shipping |
| Companies Covered | Ballard Power Systems, Cummins, Linde, Westport Fuel Systems, Tidewater Renewables, Air Liquide, Nel ASA, Hazer Group, Plug Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Hydrogen Market Strategic Shifts
Technology convergence between electrolyzer scaling and liquefaction efficiency gains is compressing the cost curve for green hydrogen pathways faster than steam methane reforming can decarbonize.
Magnetic bearing turboexpanders are rewriting liquefaction plant economics by eliminating lubrication systems and cutting maintenance intervals from quarterly to annual cycles. Air Products and Linde are retrofitting existing trains with oil-free expansion technology at their US Gulf Coast facilities. The structural consequence is enabling smaller-scale distributed liquefaction at renewable generation sites previously uneconomical for central plant supply.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration cycles, forcing liquefaction plant designers toward ammonia or helium-based cooling architectures. Industrial gas engineering teams are redesigning cold boxes to accommodate natural refrigerants with higher capital intensity but lower regulatory risk. This shift most affects new European capacity where retrofitting existing hydrogen liquefiers faces stranded asset exposure.
Buyer consortiums are consolidating offtake negotiations for multi-source supply security, displacing bilateral producer-user contracts that dominated early market development. Aerospace primes like Airbus and regional fuel cell bus operators are forming procurement pools to secure volume commitments across competing liquefaction projects. This pattern is most visible in California where the California Air Resources Board clean fleet mandates concentrate demand timing.
Liquid Hydrogen Market Segmentation
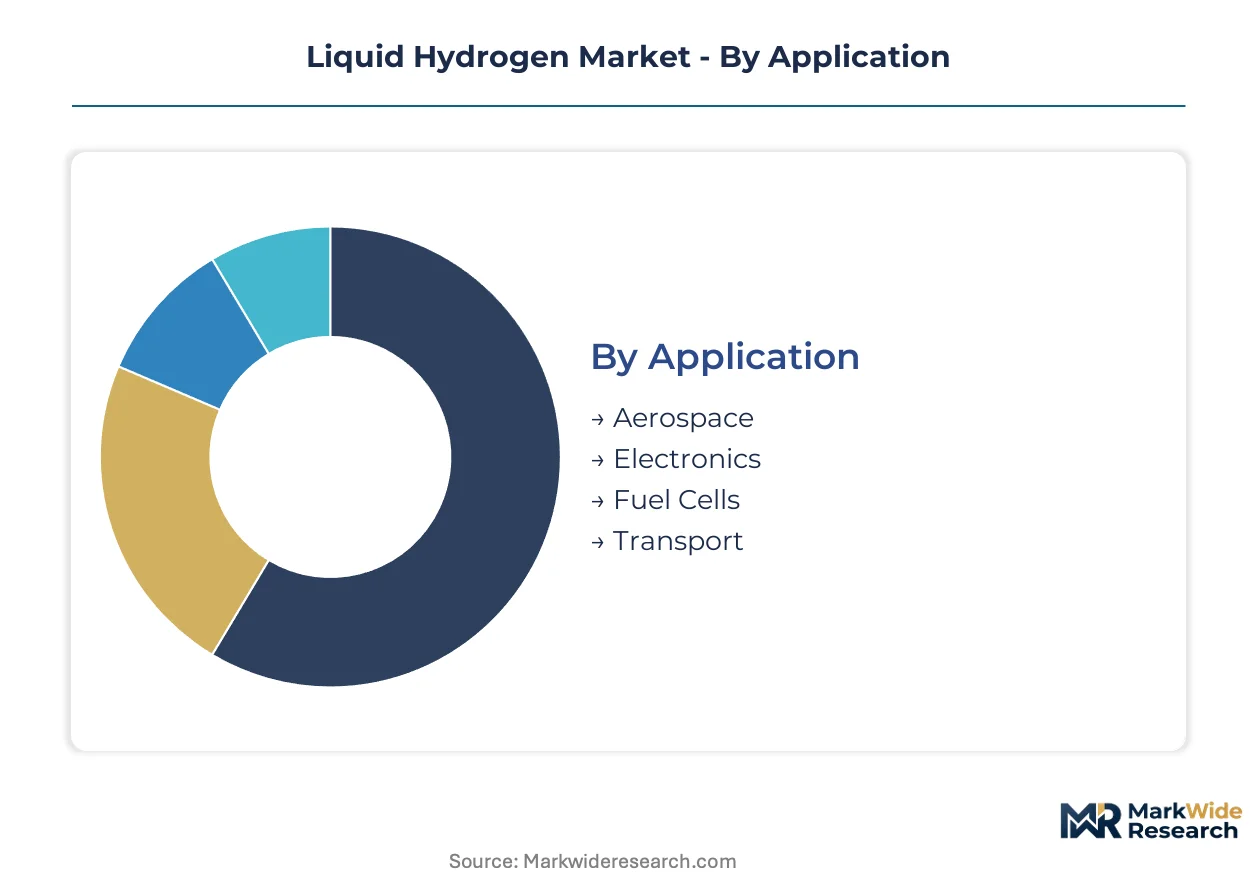
Liquid hydrogen markets fragment across four critical dimensions where production scale, purity requirements, and logistics infrastructure determine margin capture. Each segmentation layer reveals distinct competitive dynamics between incumbent industrial gas operators and emerging renewable-focused entrants.
Application:
Volume concentrates in mature industrial uses while premium pricing accrues to emerging mobility and energy transition segments.
- Aerospace:Rocket propulsion systems from SpaceX, Blue Origin, and national space agencies consume ultra-high-purity liquid hydrogen for booster stages. NASA's Artemis program and commercial launch cadence expansion at Cape Canaveral and Vandenberg anchor North American demand with stringent 99.999% purity specifications that command 40% price premiums over standard industrial grades.
- Electronics:Semiconductor fabrication facilities operated by Samsung, TSMC, and Intel require liquid hydrogen for epitaxial silicon deposition and reducing atmospheres. Taiwan's Hsinchu Science Park and South Korea's Yongin cluster represent the densest demand geography where supply interruptions trigger million-dollar-per-hour production losses.
- Fuel Cells:Stationary power installations and backup systems for data centers and telecommunications infrastructure.
- Transport:Heavy-duty trucking and maritime fuel cell applications with cryogenic onboard storage systems.
Today's leader: Electronics. Tomorrow's challenger: Transport.
Production Method:
Cost structure and carbon intensity separate established thermal processes from emerging electrochemical pathways.
- Steam Methane Reforming:Natural gas-fed reformers with carbon capture retrofits dominate current output volumes along the US Gulf Coast and Rotterdam industrial corridors. Texas and Louisiana facilities leverage existing pipeline methane access and CCS geology for IRA tax credit stacking, though residual emissions constrain qualification under EU carbon border adjustment mechanisms.
- Electrolysis:Proton exchange membrane and alkaline electrolyzers powered by dedicated renewable assets are capturing green hydrogen qualification premiums. Iberian Peninsula projects pairing solar PV with curtailed wind access achieve production costs approaching SMR parity when IRA production tax credits and EU Innovation Fund subsidies combine.
- Coal Gasification:Integrated gasification combined cycle plants with carbon capture in China and India.
- Cryogenic Distillation:Byproduct recovery from petrochemical and refinery off-gas streams.
Established baseload: Steam Methane Reforming. Steepest expansion trajectory: Electrolysis.
Storage Type:
Engineering differentiation and thermal performance define competitive positioning across containment architectures.
- Cryogenic Tanks:Vacuum-insulated double-wall vessels with perlite or aerogel insulation achieve boil-off rates below 0.1% daily for stationary applications. Chart Industries and Linde engineer site-specific tanks for NASA launch pads and semiconductor fabs where thermal cycling durability exceeds 25-year design lives.
- Pressure Vessels:Type III aluminum-lined carbon fiber and Type IV all-composite cylinders enable gaseous buffer storage at liquefaction plants and fueling stations.
- Bulk Storage:Spherical and cylindrical field-erected tanks for terminal-scale inventory management.
- Transport Containers:ISO tank frames and over-the-road cryogenic trailers with active refrigeration systems.
Margin concentration: Cryogenic Tanks. Infrastructure buildout priority: Transport Containers.
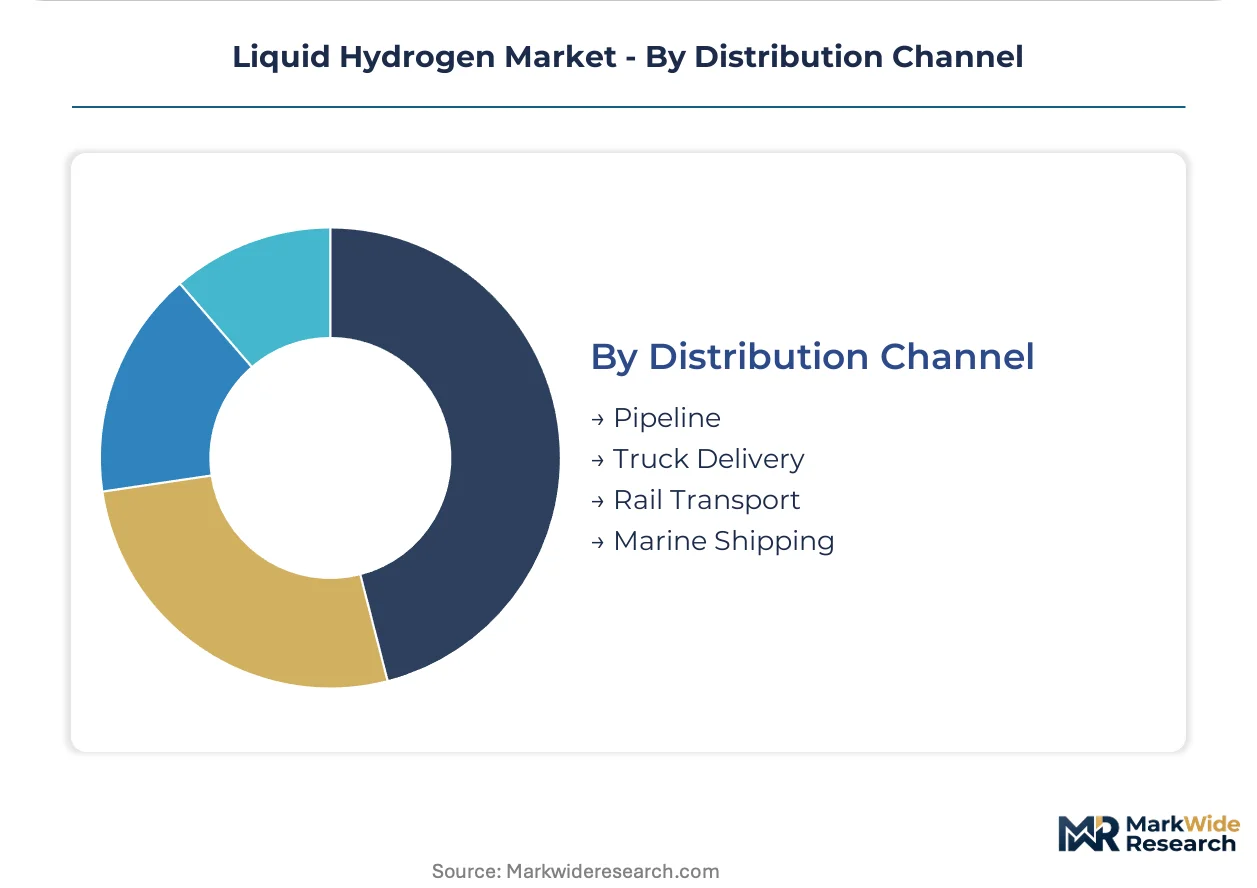
Distribution Channel:
Distance-to-market and delivery urgency shape modal selection across customer segments.
- Truck Delivery:Cryogenic tanker fleets operated by Air Liquide, Linde, and regional industrial gas distributors provide scheduled replenishment within 500-kilometer radii of liquefaction plants. California's hydrogen highway corridor and Germany's H2 Mobility network depend on dedicated trucking assets with 4,000-kilogram payload capacities.
- Pipeline:NASA-operated and Gulf Coast industrial hydrogen pipelines serve high-volume, continuous-demand customers with lowest unit logistics costs.
- Rail Transport:Cryogenic railcars for intercontinental bulk movements where trucking economics fail.
- Marine Shipping:Specialized LH2 carriers with membrane or spherical cargo containment for transoceanic energy trade.
Current backbone: Truck Delivery. Long-distance arbiter: Marine Shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial hydrogen corridor development contrasts with Japan's import terminal focus, revealing divergent pathways for liquid hydrogen market formation. The United States anchors liquefaction capacity expansion through IRA-linked production incentives. China scales coal-gasification baseload while electrolyzer additions accelerate.
United States
Texas and Louisiana host concentrated steam methane reforming with carbon capture retrofits serving Gulf Coast export terminal development. The IRA hydrogen production tax credit compresses project payback periods for liquefaction infrastructure. Houston anchors multiple billion-dollar clean hydrogen hubs linking renewable generation to coastal export facilities.
Germany
Industrial offtake from steel decarbonization and chemical feedstock switching drives demand clustering along the Rhine-Ruhr corridor. The EU Green Deal carbon border adjustment mechanism accelerates clean hydrogen qualification investments at Hamburg and Rotterdam terminal access points. Lower Saxony electrolyzer projects pair North Sea wind access with pipeline distribution to Leuna chemical complexes.
Japan
Kobe and Yokohama terminal expansions anchor Asia-Pacific import infrastructure for Australian and Middle Eastern supply contracts. METI hydrogen roadmap mandates specify purity and delivery modalities shaping procurement standards. Osaka-Kobe industrial zone concentrates fuel cell mobility demonstration fleets with dedicated cryogenic fueling networks.
South Korea
Yongin semiconductor fabrication clusters generate ultra-high-purity hydrogen demand with supply interruption costs exceeding million-dollar-per-hour thresholds. MFDS industrial gas frameworks regulate storage and distribution safety standards. Ulsan petrochemical complexes integrate byproduct hydrogen recovery with liquefaction for mobility sector offtake.
China
Coal gasification with carbon capture retains volume dominance in Inner Mongolia and Shanxi production bases. Dual carbon policy targets accelerate electrolyzer-liquefaction coupling in Sichuan and Yunnan hydropower-rich provinces. Yangtze River Delta cities pilot fuel cell heavy-duty trucking corridors with state-backed hydrogen refueling infrastructure deployment.
Liquid Hydrogen Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated industrial gas operators commanding liquefaction and distribution while equipment fabricators capture cryogenic storage and transport hardware. Market structure consolidates around three strategic archetypes: continental-scale hydrogen merchants with captive production networks, electrolyzer-liquefaction integrators targeting green hydrogen pathways, and cryogenic engineering specialists extracting premium pricing from aerospace and semiconductor purity requirements. Competitive positioning depends on securing long-term offtake anchors and certifying equipment for ASME pressure vessel standards. Capacity expansion and strategic partnerships dominate rival moves, with terminal developers locking in supply agreements before liquefaction trains reach commissioning.
Among integrated industrial gas operators, Linde and Air Liquide exemplify the merchant archetype through continental production and distribution footprints spanning multiple regulatory jurisdictions. Nel ASA occupies a position within the electrolyzer-liquefaction coupling segment, representing renewable pathway specialization. These three companies anchor competitive dynamics without exhausting the vendor landscape, as regional specialists and emerging project developers contest equipment supply and terminal development niches.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Cummins |
| Linde |
| Westport Fuel Systems |
| Tidewater Renewables |
| Air Liquide |
| Nel ASA |
| Hazer Group |
| Plug Power |
| Others |
Value Chain & Pricing Dynamics
Cryogenic engineering talent scarcity in Houston and Rotterdam widens labor-cost differentials between premium aerospace-grade supply and standard industrial delivery, compressing margin spreads at the economy tier while sustaining 40% purity premiums for 99.999% specification hydrogen.
Pricing Analysis
Capacity additions along the US Gulf Coast are reshaping price floors for standard industrial grades as IRA-linked production tax credits compress project economics. Three-tier pricing structure across premium, standard, and economy levels separates NASA Artemis program propulsion contracts from semiconductor fab supply and bulk chemical feedstock offtake. Price differentiation hinges on certification grade and geographic delivery cost, with boil-off rate guarantees commanding premiums for maritime routes exceeding 14 days. Cost compression in standard grades is intensifying because electrolyzer-liquefaction coupling at Iberian solar-wind sites approaches SMR parity. Chemical feedstock buyers exhibit highest price sensitivity, while aerospace primes accept premium positioning for launch window reliability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from SpaceX and Airbus, while distributor networks serve fragmented semiconductor fab procurement. Supply concentrates in the United States, Germany, and Japan, with Texas and Louisiana anchoring SMR-based liquefaction and Hamburg-Leuna corridor developing electrolyzer capacity. Raw material dependencies draw from specialized nickel alloys for vacuum-insulated tanks, high-purity helium for refrigeration cycles, and proton exchange membrane stacks for green hydrogen pathways. Single-source vulnerability in ASME Section VIII certified tank fabrication extends lead times for novel containment designs. Distribution runs through cryogenic tanker fleets within 500-kilometer radii and marine shipping for transoceanic energy trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
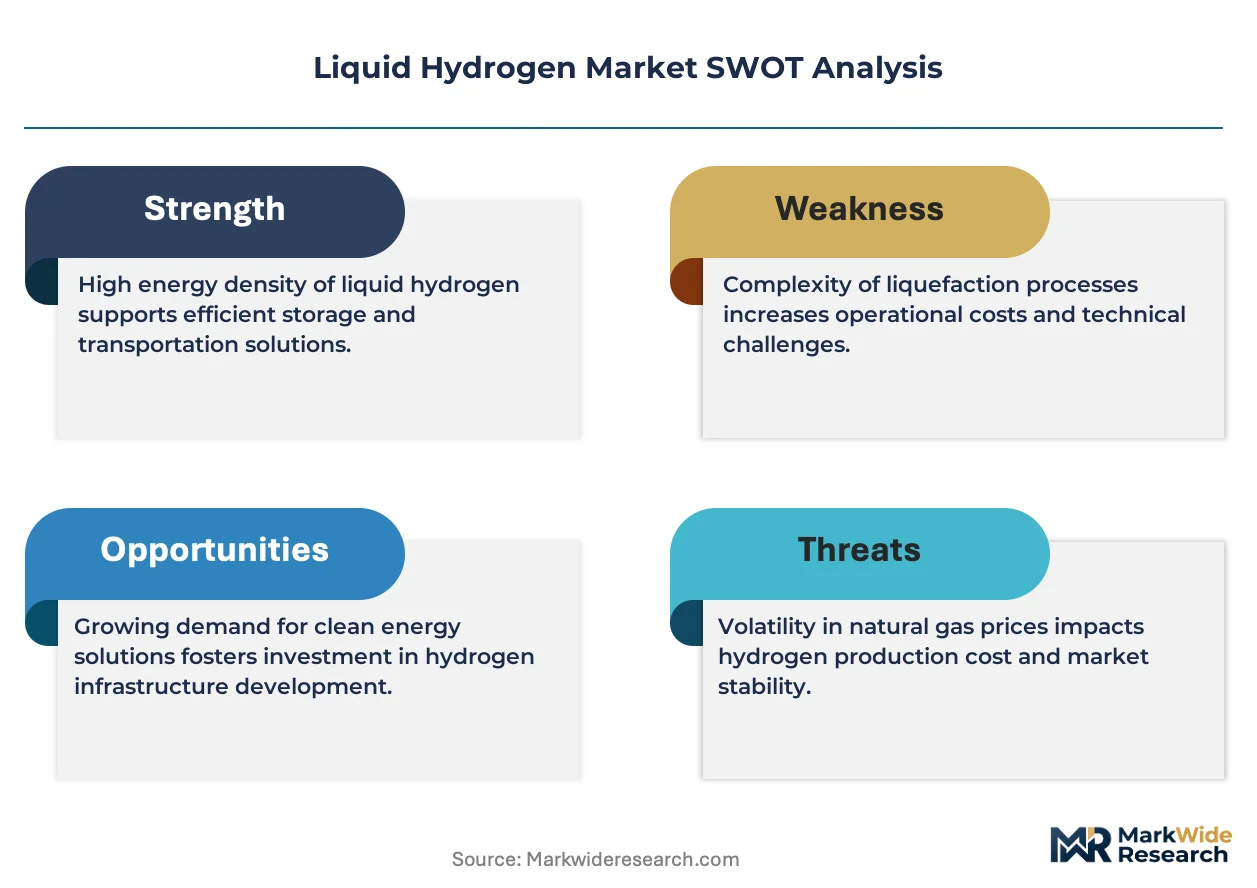
The liquid hydrogen market functions as a regulatory compounder where IRA production tax credits and EU carbon border adjustments accelerate clean qualification investments faster than technology cost curves alone would permit.
For Market Incumbents: Anchor liquefaction capacity along US Gulf Coast export corridors before terminal developers lock in 15-year supply contracts with Japanese importers. Defend margin position by securing ASME Section VIII certification for proprietary tank designs, creating 18-24 month barriers against equipment fabricators. Deepen backward integration into renewable generation assets to capture IRA tax credit stacking and insulate against electrolyzer supply bottlenecks. For New Entrants and Emerging Players: Digital procurement platforms for buyer consortiums offer lower customer acquisition costs than bilateral contract negotiations dominated by Linde and Air Liquide relationships. Target semiconductor manufacturing purity demand in Taiwan's Hsinchu Science Park and South Korea's Yongin cluster, where supply interruption costs exceed million-dollar-per-hour thresholds and incumbent relationships remain underdeveloped. Pursue equipment-as-a-service models for cryogenic storage systems to bypass capital intensity barriers. For Investors and Strategic Acquirers: Industrial gas operators with captive hydrogen networks are the most active acquirer in this space, seeking electrolyzer-liquefaction integrators to green existing production footprints. Five-to-ten year viability hinges on securing offtake anchors before liquefaction trains reach commissioning, not technology differentiation. Watch for F-Gas Regulation compliance deadlines in Europe as inflection indicators for ammonia-based cooling architecture adoption and stranded asset risk in existing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Contracting | Airbus and regional bus operators forming procurement pools secure volume across competing liquefaction projects. |
| Electrolyzer-Liquefaction Coupling | Iberian solar-wind pairing captures margin pools previously lost to intermediate hydrogen handlers. |
| ASME Section VIII Certification | Novel tank designs face 18-24 month approval timelines that protect incumbent equipment fabricators. |
| Backward Integration into Renewables | IRA tax credit stacking requires captive generation assets for maximum production incentive capture. |
| Japan METI Terminal Access | Kobe and Yokohama expansions offer 15-year supply anchors for US Gulf Coast export capacity. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with liquefaction plant engineers, hydrogen procurement managers at aerospace primes, semiconductor fab supply chain directors, and terminal development executives with secondary validation from EIA hydrogen production data, IEA hydrogen project databases, SEC 10-K filings from industrial gas operators, and EU Innovation Fund award announcements. Bottom-up capacity buildout tracking triangulates against top-down demand modeling from end-use segment consumption patterns.
Rate-of-change decomposition separates volume growth from price trajectory shifts across the analysis window. Segmentation dimensions modeled include production method, application purity requirements, storage type engineering specifications, and distribution channel modal selection. CAGRs derive from facility commissioning timelines, offtake contract execution rates, and regulatory incentive phase-in schedules. Electrolyzer cost curves and renewable energy capture prices feed green hydrogen pathway economics; SMR carbon capture retrofit rates inform blue hydrogen competitiveness.
The model assumes a particular technology adoption path; alternative pathways for ammonia cracking reconversion at destination ports would alter the outlook by bypassing liquefaction investments at origin. Forecasts reflect base-case assumptions about IRA credit continuity and EU carbon border adjustment implementation. Regulatory stringency divergence between jurisdictions, nickel alloy price volatility, and cryogenic engineering talent availability constitute primary stress factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Merchant Hydrogen Market