
 Mud Pumps Market | 2026-2036
Mud Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Pumps Market Intelligence
The experienced field technician pool across North American oilfield services is collapsing as veteran crews age out and apprenticeship pipelines fail to replenish specialized hydraulics expertise. Halliburton sustains competitive position through backward integration into fluid end manufacturing and captive supply of forged alloy components. National Oilwell Varco dominates aftermarket parts distribution through proprietary liner and valve inventory networks. Gardner Denver Pumps differentiates via electric-drive retrofit kits that reduce diesel fuel exposure on remote pad sites.
Mud pumps are positive-displacement reciprocating machines engineered to circulate drilling fluid at pressures exceeding 7,500 psi and flow rates above 1,000 gallons per minute through the drillstring and annulus, with fluid ends machined from forged chrome-molybdenum steel to resist abrasive wear and corrosive hydrogen sulfide exposure. Triplex pumps occupy the core volume position across land drilling fleets due to proven reliability in extended-reach horizontal applications, while quintuplex configurations capture premium positioning in ultra-deepwater and high-pressure high-temperature wells where reduced pulsation protects downhole measurement tools. Electric-drive technology is displacing mechanical belt-and-sheave systems as rig electrification mandates intensify and variable-frequency drives enable precise flow control during managed pressure drilling operations.
API 7K and ISO 14693 standards govern material certifications, pressure testing protocols, and quality management systems for pump manufacturing and remanufacturing, while EPA emissions regulations and OSHA silica exposure limits compel operators toward enclosed fluid handling systems and reduced fugitive emissions at the wellsite. The US Department of Transportation's PHMSA rules on gathering line integrity indirectly elevate pump specification requirements for sour service environments. Stakeholders must weigh capital allocation between conventional fleet maintenance and next-generation electric-drive platforms as regulatory compliance costs and carbon intensity disclosures reshape contractor procurement criteria.
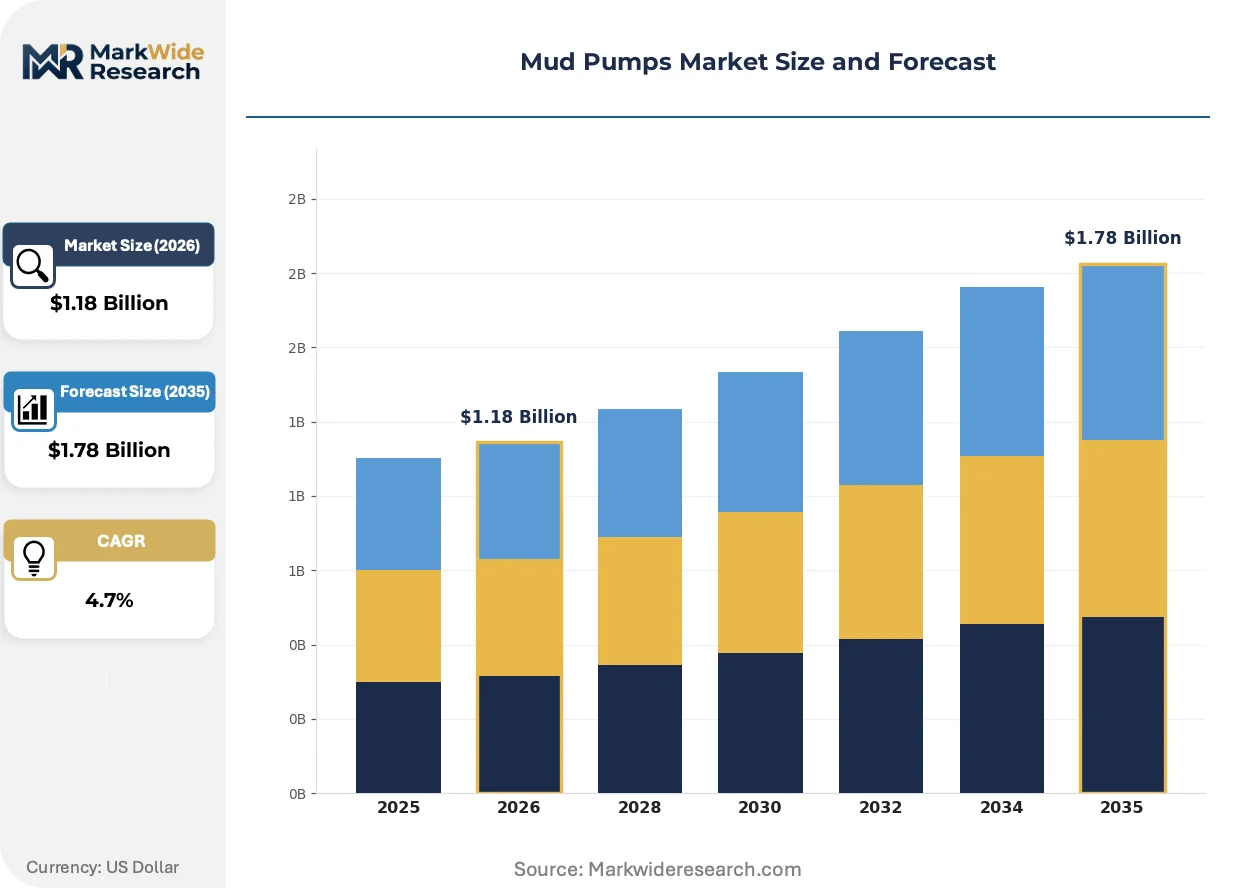
Market Dynamics
Electric-drive mud pump retrofits are compressing replacement cycles across North American land drilling fleets as contractors face simultaneous pressure from EPA emissions mandates and diesel cost volatility. The shift from mechanical belt-drive systems to variable-frequency electric configurations is redrawing capital allocation patterns between incumbent fluid end manufacturers and emerging powertrain specialists.
Growth Catalysts
- API 7K Specification Revisions:Tightened material certification standards for forged alloy components are accelerating fleet renewal decisions among drilling contractors operating high-pressure reciprocating units in unconventional basins.
- Extended-Reach Horizontal Drilling:Permian Basin operators deploying laterals exceeding 15,000 feet require quintuplex pump configurations that deliver reduced pulsation for downhole measurement tool protection.
- Rig Electrification Mandates:OSHA silica exposure limits and EPA regional haze rules are compelling enclosed fluid handling systems that integrate with electric-drive pump architectures.
Market Restraints
- Specialized Labor Collapse:The aging-out of veteran hydraulics technicians across North American oilfield services constrains maintenance capacity and extends pump rebuild timelines.
- Forged Alloy Supply Concentration:Captive supply chains for chrome-molybdenum fluid end components concentrate among vertically integrated OEMs, limiting third-party remanufacturing access.
- High-Pressure Triplex Saturation:Proven reliability in standard land applications slows upgrade velocity to higher-specification quintuplex platforms despite technical advantages.
Strategic Opportunities
- Managed Pressure Drilling Integration:Variable-frequency electric drives enabling precise flow control during MPO operations open retrofit revenue streams among mid-tier drilling contractors.
- Sour Service Environment Upgrades:PHMSA gathering line integrity rules indirectly elevate pump specifications for hydrogen sulfide exposure, creating aftermarket premium tiers.
- Carbon Intensity Disclosure Requirements:Contractor procurement criteria increasingly weight diesel fuel exposure reduction, favoring electric-drive retrofit kit providers with validated emissions data.
Industry Challenges
- Hydraulics Expertise Pipeline Failure:Apprenticeship programs fail to replenish specialized reciprocating pump maintenance skills as experienced field technicians exit the workforce.
- ISO 14693 Certification Complexity:Pressure testing protocol harmonization between remanufacturing facilities and OEM quality management systems extends compliance timelines.
- Legacy Mechanical System Integration:Belt-and-sheave infrastructure retrofit compatibility with variable-frequency electric architectures requires custom engineering for aging rig fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Pumps Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.78 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Pumps, Centrifugal Pumps, Duplex Pumps, Triplex Pumps, Quintuplex Pumps Technology: Hydraulic, Electric, Pneumatic, Mechanical, Magnetic Drive Application: Oil & Gas Exploration, Drilling Rigs, Well Servicing, Water Injection, Mining Operations End User: Drilling Contractors, Well Completion Companies, Oilfield Services Firms, Energy Equipment Providers |
| Companies Covered | Halliburton, Gardner Denver Pumps, National Oilwell Varco, MHWirth, China National Petroleum Corporation, Schlumberger, Flowserve Corporation, American Block, Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Pumps Market Strategic Shifts & Innovations
Powertrain electrification is fragmenting traditional supplier relationships as drilling contractors bypass incumbent pump OEMs to source electric-drive components directly from industrial motor manufacturers. Three convergent developments are compressing technology adoption timelines.
Electric-drive retrofit kits are fragmenting the mud pump value chain by decoupling power transmission from fluid end manufacturing. Independent contractors in the Permian Basin and DJ Basin are sourcing permanent magnet motors and variable-frequency drives from industrial automation suppliers, then integrating with existing triplex fluid ends through third-party engineering shops. This bypass pattern compresses margin capture for traditional full-system OEMs while expanding addressable market access for component specialists.
EPA New Source Performance Standards for oil and gas sector methane emissions are compelling enclosed crankcase ventilation and sealed fluid handling architectures. Drilling contractors operating in EPA Region 6 must demonstrate fugitive emissions containment at the wellsite, driving specification requirements for API 7K-compliant pump packages with integrated vapor recovery. OEMs with pre-certified low-emission configurations capture procurement preference among supermajor-operated drilling programs.
Aftermarket parts procurement is consolidating through proprietary digital inventory platforms that bypass traditional distribution channels. National Oilwell Varco's liner and valve stocking networks and Halliburton's captive forged alloy supply chains are being challenged by independent remanufacturers offering API-certified components with compressed lead times. This channel disintermediation is most visible among Permian Basin independents prioritizing uptime over OEM brand loyalty in high-activity drilling windows.
Mud Pumps Market Segmentation
Mud pump procurement patterns diverge sharply across product architectures and powertrain technologies, with specification requirements varying by drilling environment pressure ratings and emissions compliance zones. Channel access and aftermarket service capabilities often determine segment selection more than upfront equipment cost.
Product Type:
Channel distribution for reciprocating pump configurations splits between OEM-direct fleet sales for newbuild rigs and independent remanufacturers serving replacement cycles in active basins.
- Reciprocating Pumps:Positive-displacement units with plungers or pistons driven through crankshaft mechanisms dominate high-pressure applications above 5,000 psi. Permian Basin contractors specify these for extended-reach laterals where pulsation tolerance is acceptable.
- Centrifugal Pumps:Rotodynamic designs using impeller acceleration handle high-volume, low-pressure circulation below 2,000 psi. Water injection programs in West Texas favor these for continuous-duty surface transfer operations.
- Duplex Pumps:Two-cylinder reciprocating configurations with higher pulsation signatures occupy legacy fleet positions in shallow vertical drilling.
- Triplex Pumps:Three-throw crankshaft designs balance flow continuity against mechanical complexity. Land drilling contractors across the DJ Basin and Bakken standardize on these for 10,000-15,000 foot laterals.
- Quintuplex Pumps:Five-throw configurations reduce pulsation amplitude for downhole measurement tool protection. Ultra-deepwater and HPHT wells in the Gulf of Mexico command premium specification tiers.
Triplex configurations dominate installed base. Quintuplex platforms are where expansion concentrates.
Technology:
Powertrain selection increasingly tracks regulatory pressure zones, with electric architectures gaining procurement preference in EPA Region 6 and other emissions-constrained jurisdictions.
- Hydraulic:Fluid power transmission using pressurized oil circuits delivers precise torque control for managed pressure drilling. Offshore contractors in the Gulf of Mexico specify these where variable-frequency electric infrastructure is unavailable.
- Electric:Permanent magnet motors with variable-frequency drives enable precise flow modulation and eliminate diesel fuel exposure. Permian Basin independents retrofit existing fluid ends with electric powertrains to meet carbon intensity disclosure requirements.
- Pneumatic:Compressed air actuation suits hazardous atmosphere zones where electrical ignition risks are prohibited. Limited to specialized sour gas applications with strict area classification.
- Mechanical:Belt-and-sheave drives from diesel power take-offs remain prevalent in legacy fleets. Rebuild economics slow displacement despite efficiency disadvantages.
- Magnetic Drive:Sealless torque transmission through containment shrouds eliminates fugitive emissions at the stuffing box. Emerging specification for methane containment mandates.
Mechanical belt-drive retains installed base dominance. Electric powertrains are climbing the fastest.
Application:
Application-driven segmentation reflects pressure rating requirements and fluid compatibility constraints, with drilling depth and formation characteristics dictating pump specification tiers.
- Oil & Gas Exploration:Wildcat and appraisal drilling in frontier basins requires portable high-pressure units with rapid mobilization. Bakken operators specify these for exploratory pad testing before production fleet commitment.
- Drilling Rigs:Continuous circulation duty on active production drilling demands API 7K-certified triplex and quintuplex configurations. Permian Basin supermajor programs drive specification standardization.
- Well Servicing:Workover and completion operations utilize lower-duty cycles with emphasis on rapid liner and valve changeout. Independent service firms prioritize aftermarket parts availability over OEM branding.
- Water Injection:Secondary recovery pressure maintenance employs centrifugal and lower-pressure reciprocating designs. West Texas waterflood programs specify these for 24-hour continuous operation.
- Mining Operations:Slurry handling and paste backfill applications adapt oilfield pump architectures for abrasive media. Limited crossover with petroleum-sector procurement channels.
Drilling rig applications dominate capital deployment. Well servicing is gaining share fastest.
End User:
End-user procurement authority varies by contract structure, with drilling contractors making equipment decisions under dayrate arrangements and operators specifying under integrated service contracts.
- Drilling Contractors:Fleet owners under dayrate contracts control pump specification for rig-owned equipment. Nabors and Patterson-UTI standardize across Permian and DJ Basin fleets to compress maintenance training costs.
- Well Completion Companies:Pressure pumping and hydraulic fracturing specialists source high-pressure pumps for stimulation fleets. These firms prioritize fluid end interchangeability across pump types.
- Oilfield Services Firms:Integrated providers bundle pumping services with equipment provision. Halliburton and Baker Hughes leverage captive manufacturing for margin capture.
- Energy Equipment Providers:Rental and leasing companies supply short-term pump needs for intermittent drilling programs. These intermediaries concentrate inventory in the Permian Basin for logistics efficiency.
Drilling contractors dominate specification authority. Well completion companies are expanding procurement influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize quintuplex configurations for extended-reach laterals, while Middle Eastern markets emphasize sour-service durability, and Asian procurement concentrates on cost-optimized triplex platforms for conventional vertical drilling.
United States
Permian Basin activity drives specification intensity, with contractors demanding API 7K-certified quintuplex pumps for laterals exceeding 15,000 feet. EPA New Source Performance Standards for methane emissions compel enclosed fluid handling architectures across Texas and New Mexico. Midland-Odessa anchors aftermarket parts consolidation as independent remanufacturers compress lead times for liner and valve replacements.
Saudi Arabia
Sour gas development in the Ghawar field elevates hydrogen sulfide exposure requirements for fluid end materials. The country's national oil company procurement protocols favor vertically integrated OEMs with captive forged alloy supply chains. Dhahran-based engineering centers coordinate specification standardization across onshore and offshore drilling programs.
China
Shale gas development in Sichuan-Chongqing basin accelerates triplex pump deployment for 8,000-12,000 foot horizontal sections. MIIT industrial equipment standards mandate pressure testing protocols that align with ISO 14693 certification requirements. Chongqing manufacturing clusters produce cost-optimized fluid ends for domestic operators and export markets across Central Asia.
Canada
Montney and Duvernay formation drilling demands high-pressure configurations for deep basin gas extraction. Health Canada silica exposure guidelines parallel OSHA mandates, driving enclosed pump architectures in Alberta and British Columbia. Calgary service company headquarters coordinate fleet standardization across Western Canadian Sedimentary Basin operations.
Norway
North Sea ultra-deepwater projects specify quintuplex platforms with reduced pulsation signatures for downhole measurement tool protection. REACH chemical compliance requirements influence material selection for fluid ends exposed to synthetic drilling fluids. Stavanger subsea engineering clusters integrate pump specifications with managed pressure drilling system architectures.
Mud Pumps Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with fluid end manufacturing and aftermarket distribution capabilities determining competitive position. The structure rewards backward integration into forged alloy component supply and proprietary inventory networks. Three archetypes dominate: full-system OEMs with captive manufacturing, independent remanufacturers with API-certified component lines, and powertrain specialists delivering electric-drive retrofit kits. Competitive moves concentrate on vertical integration into fluid end production and digital platform development for aftermarket parts procurement.
Among integrated North American oilfield service providers, Halliburton and National Oilwell Varco exemplify the full-system archetype through manufacturing depth and distribution scale. Weatherford occupies a position bridging OEM and service integration. Gardner Denver Pumps, now operating within broader industrial automation structures, represents the powertrain specialization vector as electric-drive retrofits fragment traditional supplier relationships.
| Leading Market Players |
|---|
| Halliburton |
| Gardner Denver Pumps |
| National Oilwell Varco |
| MHWirth |
| China National Petroleum Corporation |
| Schlumberger |
| Flowserve Corporation |
| American Block |
| Weatherford |
| Others |
Cost & Logistics Intelligence
API 7K certification requirements gate both supplier qualification and price differentiation in the mud pumps market, compressing margin capture for uncertified remanufacturers while enabling premium positioning for OEMs with captive forged alloy supply chains. Drilling contractors face stark cost trade-offs between certified newbuild units and third-party rebuilds with compressed lead times.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement for supermajor-operated drilling programs, while spot-market transactions concentrate among Permian Basin independents prioritizing uptime over OEM brand loyalty. Price differentiation hinges on API 7K certification tier and volume scale, with quintuplex configurations commanding substantial premiums over triplex platforms despite equivalent fluid end materials. Cost compression in standard-tier equipment is intensifying as independent remanufacturers bypass proprietary distribution channels. Dayrate drilling contractors exhibit highest price sensitivity, whereas integrated service providers under bundled contracts demonstrate lowest sensitivity due to pass-through mechanics.
Supply Chain Analysis
Port congestion on Houston-Galveston trade lanes elevates inbound logistics costs for forged chrome-molybdenum fluid end components sourced from domestic foundries. Manufacturing concentrates in the United States, China, and Germany, with Chongqing clusters producing cost-optimized castings and German specialists supplying high-pressure quintuplex crankshafts. Raw material dependencies center on nickel-alloy steel billets, tungsten carbide valve inserts, and synthetic elastomer seals. Single-source vulnerability in premium forged alloy supply chains constrains third-party remanufacturing access. Distribution runs through OEM-direct channels for newbuild rigs and independent stocking networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapse of specialized hydraulics expertise across North American oilfield services creates durable scarcity rents for firms that retain or rebuild reciprocating pump maintenance capabilities. This capability gap will persist absent material investment in apprenticeship infrastructure.
For Market Incumbents: Secure captive supply of forged alloy fluid end components to defend margin position against independent remanufacturers with API-certified component lines. Invest in electric-drive retrofit certification to preempt powertrain specialists from fragmenting traditional supplier relationships. Lock in long-term offtake contracts with Permian Basin drilling contractors before carbon intensity disclosure requirements reshape procurement criteria.
For New Entrants and Emerging Players: API 7K fast-track certification programs open procurement access among mid-tier drilling contractors excluded from supermajor direct-OEM relationships. Target well servicing applications where rapid liner and valve changeout demands exceed OEM service capacity, particularly in West Texas waterflood programs. Pursue go-to-market partnerships with industrial motor manufacturers to bundle electric-drive powertrains with existing triplex fluid ends.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming oilfield equipment divisions holding API-certified manufacturing assets. Long-term viability favors firms with demonstrated electric-drive integration capabilities and established aftermarket digital inventory platforms. Watch rig electrification mandate acceleration in EPA Region 6 as the primary inflection signal for electric powertrain valuation premia.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric-Drive Retrofit Certification | Enables precise flow control during managed pressure drilling while eliminating diesel fuel exposure. |
| Captive Forged Alloy Supply Chain | Secures fluid end manufacturing capacity against independent remanufacturer encroachment. |
| Digital Aftermarket Platform | Compresses liner and valve lead times for Permian Basin independents prioritizing uptime. |
| API 7K Fast-Track Certification | Opens procurement access among mid-tier contractors excluded from OEM-direct channels. |
| Managed Pressure Drilling Integration | Aligns pump specifications with variable-frequency drive architectures for precise flow modulation. |
Research Approach
A spread of perspectives from drilling contractors, fluid end manufacturing engineers, aftermarket parts distributors, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with Halliburton and National Oilwell Varco procurement leads, independent remanufacturer operations directors, and Permian Basin maintenance supervisors. Secondary validation drew from API certification databases, EPA New Source Performance Standards filings, SEC 10-K equipment segment disclosures, and OSHA silica exposure guideline updates. Bottom-up triangulation across rig fleet deployment data and top-down reconciliation against oilfield services capital expenditure patterns anchored volume estimates.
Segmentation dimensions modeled include pump configuration architecture, powertrain technology type, drilling application pressure rating, and end-user procurement authority structure across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance cost trajectories. Forecast inputs incorporated rig electrification mandate timelines, apprentice pipeline failure rates for specialized hydraulics roles, and PHMSA gathering line integrity rule implementation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained unconventional shale activity and stable API 7K certification timelines; material deviation in oil price environments or regulatory acceleration would warrant model refresh. Specific risk factors include faster-than-anticipated electric-drive adoption collapsing mechanical belt-drive residual values, and acute labor shortages extending pump rebuild timelines beyond contracted uptime guarantees. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
United States Subsea Pumps Market