
 Cone Penetrometer Market | 2026-2036
Cone Penetrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Penetrometer Market Outlook
China is tilting its manufacturing base toward precision geotechnical instrumentation as domestic infrastructure investment prioritizes subsurface characterization accuracy. Humboldt Scientific leverages its long-standing calibration laboratory network to sustain repeat instrument sales across North American university research programs. Geoprobe Systems anchors its competitive position through backward integration into drill rig platforms, capturing bundled procurement decisions among environmental remediation contractors. AMS, Inc. differentiates by specializing in portable hand-pushed penetrometers for confined-access agricultural and small-scale construction sites.
A cone penetrometer measures soil bearing capacity and stratigraphy by driving a standardized conical tip into the ground while recording tip resistance, sleeve friction, and pore water pressure; modern electrical variants transmit data through strain-gauge load cells embedded in the friction sleeve and tip assembly, enabling continuous profiling to depths exceeding 50 meters for foundation design and liquefaction assessment. Static cone penetrometers occupy the largest installed base in mature geotechnical markets where ASTM D3441 and ISO 22476-1 compliance governs commercial project acceptance. Digital penetrometers with automated data acquisition represent the fastest-expanding product category as construction firms replace paper-based field logs with cloud-synced geotechnical databases. Hybrid systems that combine manual deployment with electronic sensing capture margin pools in budget-constrained municipal and agricultural testing programs.
ASTM International and ISO govern mechanical specifications and test procedures for cone penetrometer equipment sold into US and European markets, while China's SAMR enforces GB standards that increasingly reference ISO 22476 for cross-border project eligibility. The US EPA's brownfield redevelopment guidelines and the EU's Construction Products Regulation collectively elevate demand for certified in-situ testing equipment where liability exposure drives specification toward documented calibration traceability. Stakeholders must monitor evolving interoperability standards between proprietary data formats as project owners consolidate geotechnical information into unified subsurface models.
Market Dynamics
Automated digital cone penetrometer systems are compressing project timelines and displacing manual field logging practices across transportation corridor assessments. ASTM D3441 and ISO 22476-1 compliance requirements now govern specification decisions for foundation design contracts exceeding municipal scale.
Growth Catalysts
- Transportation infrastructure mandates:The US EPA's brownfield redevelopment guidelines elevate demand for certified in-situ testing equipment where liability exposure drives specification toward documented calibration traceability.
- Real-time data transmission:Cloud-synced geotechnical databases are replacing paper-based field logs as construction firms prioritize continuous profiling capabilities for liquefaction assessment.
- Coastal flood defense programs:Germany and China are concentrating investment in subsurface characterization accuracy for resilient foundation design along vulnerable shorelines.
Market Restraints
- Calibration laboratory concentration:North American university research programs depend on limited calibration networks, creating supply bottlenecks for precision strain-gauge load cells.
- Steel and electronics input volatility:Embedded sensor assemblies face cost pressure from semiconductor supply fluctuations affecting friction sleeve manufacturing.
- Hybrid system substitution:Budget-constrained municipal testing programs retain manual-electronic hybrid units, slowing full digital system penetration in agricultural segments.
Strategic Opportunities
- Confined-access agricultural verticals:Portable hand-pushed penetrometers remain underdeployed in small-scale construction sites where maneuverability constraints exclude truck-mounted rigs.
- Interoperability standardization:Project owners are consolidating geotechnical information into unified subsurface models, creating demand for format-agnostic data acquisition platforms.
- EU Construction Products Regulation tailwinds:The CPR's certification requirements for commercial project acceptance are elevating specification toward ISO-compliant electrical penetrometer variants.
Industry Challenges
- Geotechnical data scientist scarcity:Field crews lack training in cloud database management and real-time quality control algorithms for continuous pore pressure monitoring.
- Multi-standard certification complexity:Equipment vendors must simultaneously maintain ASTM, ISO, and GB standard compliance for cross-border project eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Penetrometer Market |
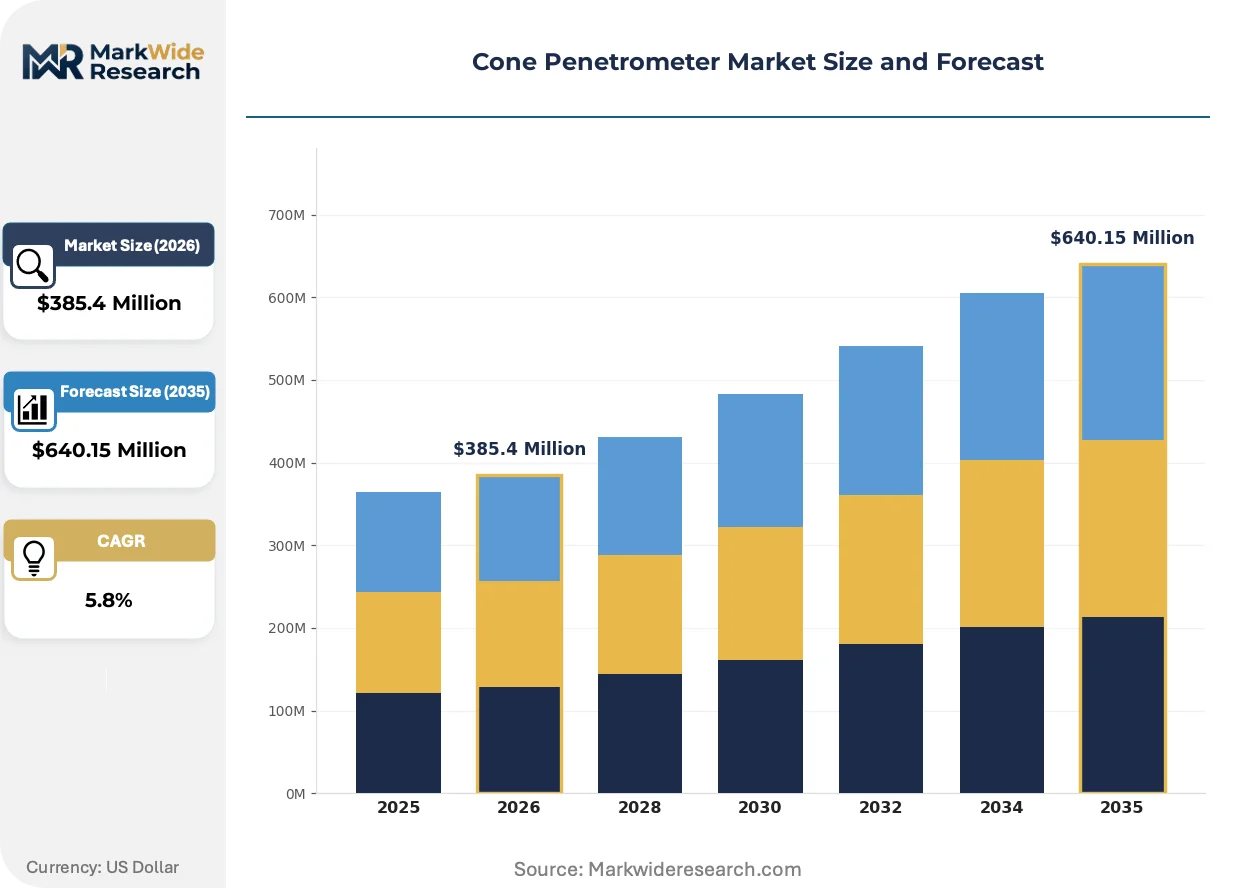
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Cone Penetrometers, Dynamic Cone Penetrometers, Electrical Cone Penetrometers, Digital Cone Penetrometers End User: Construction, Geotechnical Engineering, Environmental Research, Agriculture Application: Soil Testing, Foundation Analysis, Underground Investigation, Soil Classification Technology: Manual Operation, Automated Systems, Remote Sensing, Hybrid Systems |
| Companies Covered | Humboldt Scientific, Geoprobe Systems, Soiltest, AMS, Inc., Durham Geo-Enterprises, Vertek, ConeTec, Gouda-Reinforcements, Pagani Geotechnical Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Penetrometer Market Strategic Shifts
Digital penetrometer architecture is migrating from discrete measurement intervals toward continuous data streams, reshaping competitive requirements for field software integration and cloud connectivity. Three developments are compressing traditional equipment replacement cycles.
Electrical cone penetrometer technology is migrating from analog strain-gauge outputs toward integrated digital load cells with embedded microprocessors. Mid-size geotechnical engineering firms in the United States are adopting these systems at accelerated pace for transportation corridor upgrades. The technology is migrating from laboratory calibration dependencies toward self-diagnostic field verification, compressing maintenance intervals and reducing downtime costs.
The EU's Construction Products Regulation and China's SAMR enforcement of GB standards referencing ISO 22476 are creating dual compliance pressure for equipment vendors. Manufacturers must now document calibration traceability across both regulatory frameworks to maintain cross-border project eligibility. Electrical penetrometer variants with modular certification documentation are capturing preference among multinational infrastructure contractors operating in Germany and China.
Buyers are unbundling after-sales service contracts from initial equipment procurement, demanding à-la-carte calibration and software update subscriptions. Environmental remediation contractors are replacing bundled maintenance agreements with third-party metrology laboratory relationships. This pattern is most visible in North America where Humboldt Scientific's calibration network faces disintermediation pressure from independent ISO 17025-accredited facilities.
Cone Penetrometer Market Segmentation
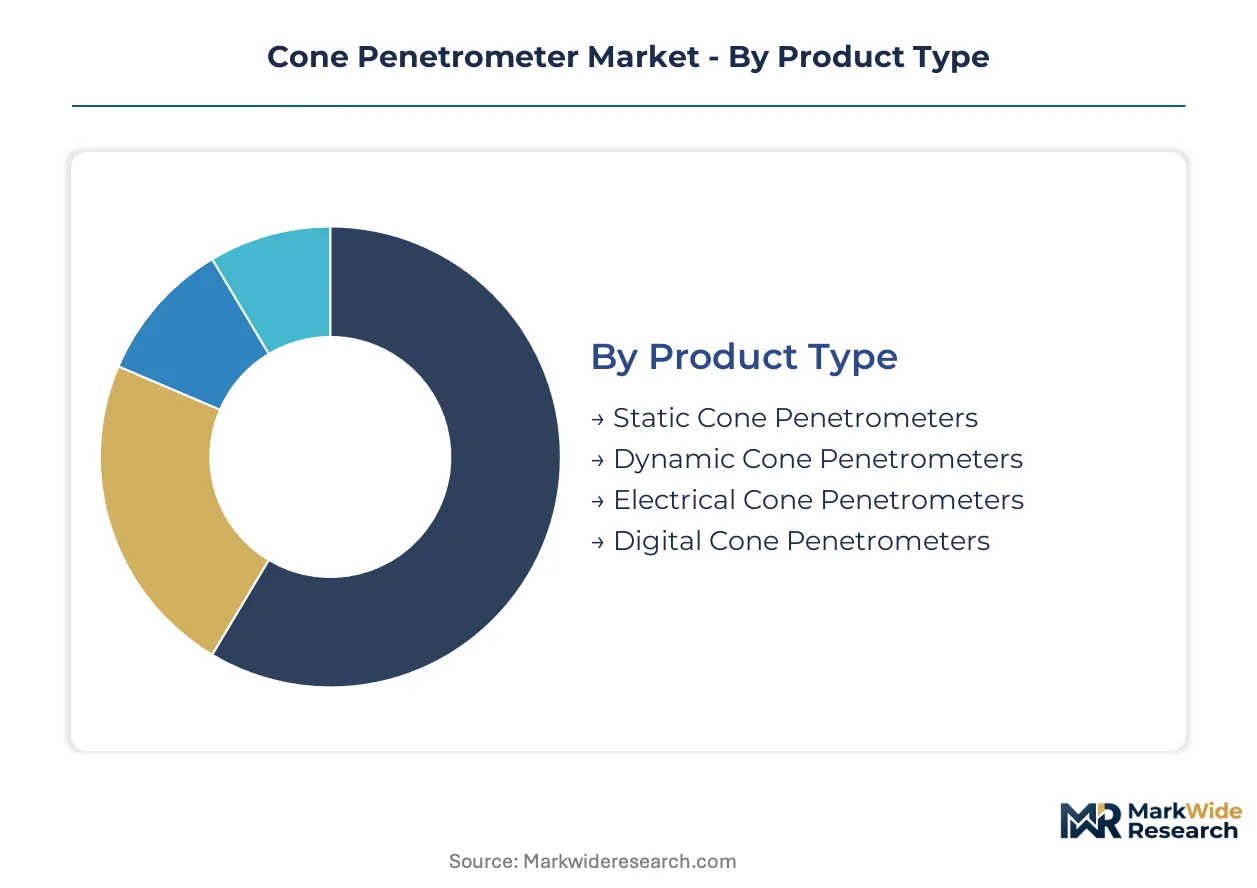
Cone penetrometer procurement patterns diverge sharply by deployment context, with replacement cycles stretching from annual sensor upgrades to decade-long rig investments. Understanding these temporal rhythms clarifies where vendors can capture recurring revenue versus one-time capital sales.
Product Type:
Replacement velocities vary dramatically across product categories, with sensor-laden electrical variants turning over fastest and mechanical static units persisting longest in installed bases.
- Static Cone Penetrometers:Mechanical push systems with analog dial gauges dominate legacy infrastructure assessments where ASTM D3441 compliance suffices. Municipal geotechnical contracts in the United States specify these units for routine bearing capacity verification, though procurement volumes are flattening as agencies defer replacement.
- Electrical Cone Penetrometers:Strain-gauge load cells embedded in the friction sleeve enable continuous pore pressure profiling to depths exceeding 50 meters. Foundation design contracts in Germany and China are concentrating specification here as ISO 22476-1 compliance becomes mandatory for commercial project acceptance.
- Dynamic Cone Penetrometers:Hammer-driven penetration systems serve rapid reconnaissance surveys where approximate stratigraphy suffices.
- Digital Cone Penetrometers:Cloud-synced data acquisition platforms are displacing paper-based field logging in transportation corridor assessments.
Static cone penetrometers anchor the volume base while digital penetrometers gain share at the steepest rate.
End User:
Customer sophistication tiers separate specification-driven engineering consultancies from price-sensitive agricultural operators.
- Geotechnical Engineering:Specialized firms demand calibration traceability documented to ISO 17025 standards for liquefaction assessment contracts. These buyers concentrate in Germany and China where coastal flood defense programs mandate certified in-situ testing equipment.
- Construction:Foundation contractors prioritize real-time data transmission to compress project timelines on transportation corridor upgrades. United States infrastructure resilience standards are tightening procurement specifications toward automated digital systems.
- Environmental Research:University programs depend on repeatable instrument performance across multi-year monitoring campaigns.
- Agriculture:Small-scale operators retain manual-electronic hybrid units for confined-access soil testing.
Construction commands the largest equipment budgets while geotechnical engineering delivers the highest margins through service attachments.
Application:
Technical complexity escalates from routine soil classification to foundation design where liability exposure governs specification.
- Foundation Analysis:Deep penetration profiling for high-rise and bridge pier design requires continuous tip resistance and sleeve friction recording. China's domestic infrastructure investment is prioritizing subsurface characterization accuracy in this segment.
- Soil Testing:Standardized penetration resistance measurement supports agricultural drainage design and roadbed preparation. German transportation agencies specify automated systems here to accelerate quality assurance cycles.
- Underground Investigation:Utility mapping and void detection applications favor portable deployment configurations.
- Soil Classification:Routine stratigraphic logging for environmental site assessment generates steady replacement demand for consumable cone tips.
Soil testing generates the highest shipment volumes while foundation analysis commands premium pricing for certified systems.
Technology:
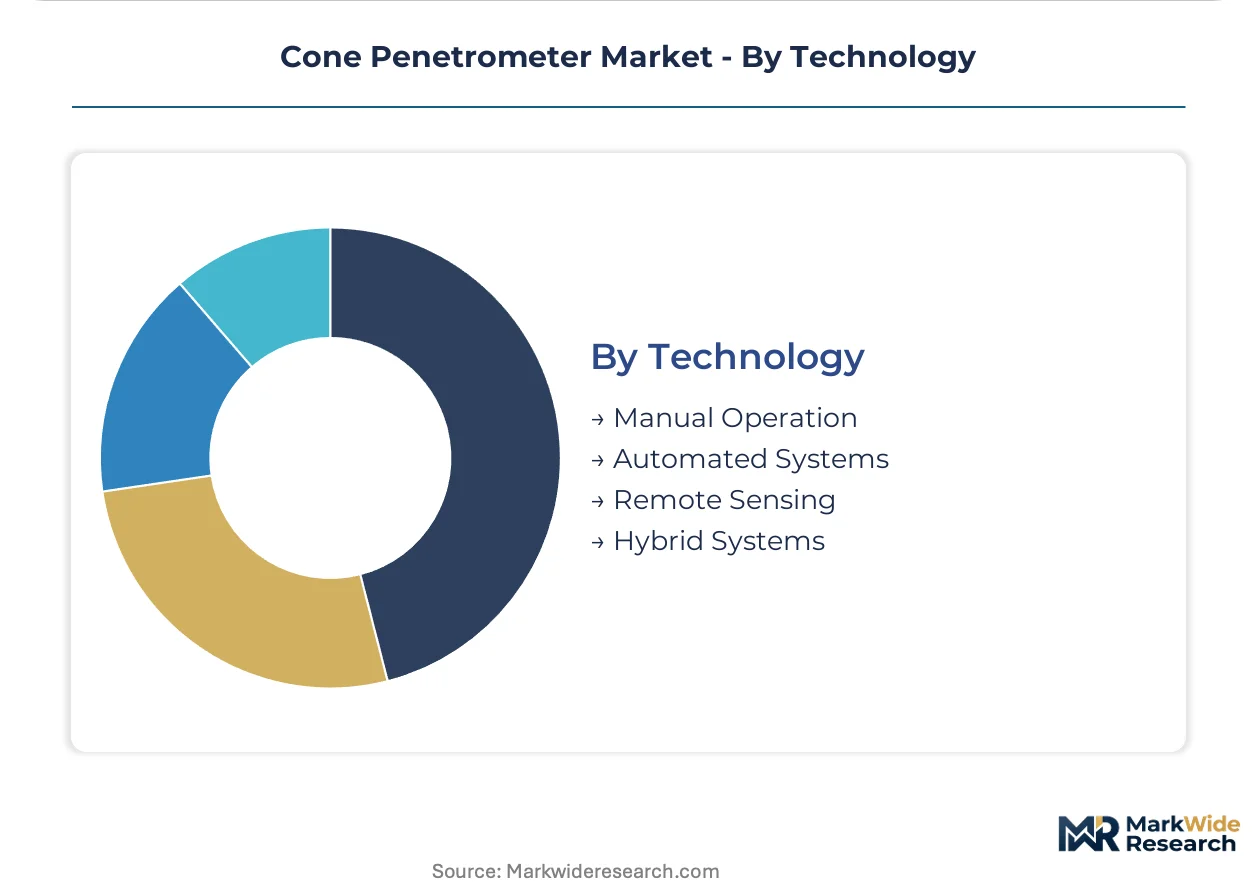
Automation intensity separates capital-intensive platform investments from incremental sensor upgrades.
- Automated Systems:Self-leveling drill rig integration with real-time quality control algorithms compresses field crew requirements. United States environmental remediation contractors are adopting these platforms to meet EPA brownfield redevelopment guidelines.
- Hybrid Systems:Manual deployment with electronic sensing captures municipal and agricultural testing programs where budget constraints exclude full automation. These units dominate in China where SAMR enforcement of GB standards creates dual compliance pressure.
- Manual Operation:Purely mechanical systems persist in developing market segments and backup equipment roles.
- Remote Sensing:Satellite-linked data transmission enables centralized monitoring of distributed testing campaigns.
Hybrid systems retain the largest installed base while automated systems are expanding most quickly in specification-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ASTM International governs the dominant geography where transportation corridor upgrades and brownfield redevelopment programs concentrate equipment procurement. The United States, Germany, and China anchor demand through distinct regulatory frameworks and infrastructure investment cycles.
United States
Foundation contractors along the Gulf Coast prioritize real-time data transmission for liquefaction assessment contracts. The EPA's brownfield redevelopment guidelines mandate documented calibration traceability for environmental remediation projects. Houston and Los Angeles metropolitan areas concentrate procurement of automated digital systems for transportation resilience programs.
Germany
Coastal flood defense initiatives along the North Sea drive specification toward ISO 22476-1 compliant electrical penetrometers. The EU Construction Products Regulation elevates certification requirements for commercial project acceptance. The Ruhr industrial corridor and Hamburg port region host dense clusters of geotechnical engineering consultancies demanding continuous profiling capabilities.
China
Domestic infrastructure investment prioritizes subsurface characterization accuracy for high-rise foundation design in coastal megacities. SAMR enforcement of GB standards referencing ISO 22476 creates dual compliance pressure for equipment vendors. The Yangtze River Delta and Pearl River Delta concentrate manufacturing of precision geotechnical instrumentation for domestic and export markets.
Japan
Seismic resilience standards for urban redevelopment require deep penetration profiling to depths exceeding 50 meters. METI guidelines for construction quality assurance emphasize documented instrument performance across multi-year monitoring campaigns. The Kanto region surrounding Tokyo anchors demand for automated systems in liquefaction-prone zones.
Australia
Mining corridor expansions in Western Australia and Queensland generate demand for rapid reconnaissance surveys in remote terrain. The country's national infrastructure regulator emphasizes certified in-situ testing for transport link upgrades. Perth and Brisbane host specialized geotechnical contractors serving resource extraction and coastal development projects.
Cone Penetrometer Market Competitive Environment
Capability concentration sits with precision instrumentation specialists; scale advantage sits with integrated drilling platform manufacturers. The vendor base stratifies across three tiers: calibration-network-dependent laboratories, drill-rig-integrated platform providers, and portable equipment specialists. Strategic archetypes include backward-integrated system bundlers, university research program anchors, and confined-access maneuverability providers. Dominant competitive moves encompass bundled procurement packaging and third-party metrology laboratory partnerships.
Among North American laboratory-anchored providers, Humboldt Scientific occupies a position exemplifying calibration-network-dependent repeat instrument sales. Geoprobe Systems represents the backward-integrated archetype through captive drill rig platform control. AMS, Inc. sits within the portable specialist tier serving agricultural and small-scale construction constraints. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive positioning vectors.
| Leading Market Players |
|---|
| Humboldt Scientific |
| Geoprobe Systems |
| Soiltest |
| AMS, Inc. |
| Durham Geo-Enterprises |
| Vertek |
| ConeTec |
| Gouda-Reinforcements |
| Pagani Geotechnical Equipment |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific freight corridors from Shanghai to Long Beach anchor cost dynamics for strain-gauge load cells and embedded sensor assemblies, compressing margins for calibration-dependent vendors while amplifying price differentiation between ISO-certified and non-certified equipment tiers.
Pricing Analysis
Price spreads between German-manufactured electrical penetrometers and Chinese hybrid units exceed forty percent on delivered basis, reflecting certification documentation burdens and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates ASTM/ISO dual-compliant systems from single-standard units and manual mechanical alternatives. Cost compression in the mid-tier segment is intensifying because semiconductor input volatility feeds through friction sleeve manufacturing. Municipal agricultural buyers exhibit highest price sensitivity, while geotechnical engineering consultancies in coastal flood defense programs demonstrate lowest sensitivity due to liability-driven specification requirements.
Supply Chain Analysis
Extended payment terms from sixty to ninety days now characterize procurement relationships for embedded microprocessors and precision load cells, stretching working capital for mid-tier equipment assemblers. Manufacturing concentrates in China, Germany, and the United States, with strain-gauge sensors drawing from Japanese and German component specialists. Steel billet and semiconductor wafer dependencies create single-source vulnerability for friction sleeve assemblies. Distribution runs through authorized dealer networks for automated systems and direct-to-contractor channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as project owners consolidate geotechnical information into unified subsurface models, rewarding vendors with format-agnostic data architectures and punishing proprietary data lock-in.
For Market Incumbents: Pre-empt disintermediation of calibration networks by acquiring ISO 17025-accredited laboratories in the United States and Germany, while embedding self-diagnostic field verification to compress maintenance intervals. Defend against portable specialist encroachment by bundling cloud-synced data acquisition with drill rig platform procurement. For New Entrants and Emerging Players: Establish a beachhead in confined-access agricultural verticals where maneuverability constraints exclude truck-mounted rigs and incumbent portable offerings remain underdeployed. Target small-scale construction sites in Australia's mining corridor expansions with hand-pushed penetrometers featuring simplified electronic sensing. For Investors and Strategic Acquirers: Carve-out targets emerge from university research program anchors seeking to monetize calibration laboratory assets amid unbundling of after-sales service contracts. Long-term viability hinges on interoperability standardization completion; watch for SAMR acceleration of GB standards referencing ISO 22476 as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Acquisition | ISO 17025-accredited laboratory control secures recurring revenue from university research programs. |
| Self-Diagnostic Field Verification | Embedded microprocessors in digital load cells reduce downtime costs for transportation corridor contractors. |
| Format-Agnostic Data Platform | Interoperability with unified subsurface models captures specification preference from multinational infrastructure contractors. |
| Confined-Access Product Line | Portable hand-pushed penetrometers penetrate agricultural segments where truck-mounted rigs face maneuverability constraints. |
| Dual-Compliance Certification Documentation | Modular ASTM and ISO 22476 compliance maintains cross-border project eligibility for Germany and China contracts. |
Study Parameters
A spread of perspectives from geotechnical engineering consultants, foundation contractors, environmental remediation procurement managers, and calibration laboratory directors converged on the working assumptions for penetration depth requirements and replacement cycle timing. Primary interview insights combined with secondary validation from ASTM International standards documentation, ISO 22476 technical committee releases, EPA brownfield redevelopment guidelines, and SAMR GB standards enforcement records. Bottom-up equipment shipment analysis and top-down infrastructure investment flow triangulation anchored volume estimates.
Demand-supply balance framing shaped the analytical framework across the analysis window, with segmentation modeled by product type, end user sophistication tier, application complexity, and automation intensity. CAGRs derived from replacement velocity differentials between sensor-laden electrical variants and mechanical static units, cross-referenced with transportation infrastructure mandate timing and coastal flood defense program procurement cycles.
Sensitivities concentrate around semiconductor supply stabilization, steel input cost trajectories, and interoperability standardization adoption rates by major project owners. Forecasts reflect assumptions on calibration network expansion pace and university research program funding continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Chemical Injection Pump Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Fluid Transfer System Market