
 Food and Beverages Industry Pumps Market | 2026-2036
Food and Beverages Industry Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Industry Pumps Market Analysis
Buyer concentration among packaged food manufacturers is hardening as multinational processors consolidate supplier lists to reduce compliance overhead. KSB SE & Co. KGaA leverages its hygienic pump portfolio to anchor long-term service contracts with European dairy cooperatives. SPX Flow competes through integrated process systems that bundle pumps with heat exchangers and homogenizers. Alfa Laval specializes in aseptic pump designs that sustain premium positioning in high-viscosity applications like yogurt and sauces.
Food and beverages industry pumps are mechanical devices engineered to transfer, meter, or mix fluids in processing environments, typically constructed from stainless steel grades 316L or 304 with surface finishes below 0.8 micrometers Ra to prevent bacterial adhesion and enable clean-in-place protocols. These pumps operate across temperature ranges from -10°C to 140°C and pressure ratings up to 40 bar, serving the primary purpose of maintaining product integrity while meeting stringent hygiene benchmarks in continuous-flow production. Centrifugal pumps dominate volume sales in liquid transfer applications where low-shear handling of milk and juices preserves organoleptic properties, while peristaltic pumps capture expanding share in ingredient dosing as pharmaceutical-grade precision migrates into food formulation. Diaphragm pumps occupy niche positions in viscous confectionery and sauce processing where positive displacement prevents phase separation.
The FDA enforces 21 CFR Part 110 sanitary standards that dictate pump material compatibility and cleanability, while the EU's Machinery Directive 2006/42/EC mandates CE-marked equipment with documented risk assessments for food-contact surfaces. USDA's 3-A Sanitary Standards provide voluntary but market-access-critical benchmarks adopted by North American dairy processors. Stakeholders must monitor how evolving PFAS restrictions in Europe and state-level packaging regulations in California reshape material specifications for seals and gaskets.
Market Dynamics
Automated clean-in-place systems are compressing maintenance windows and forcing pump architecture redesigns across dairy and beverage processing lines, as manufacturers eliminate manual disassembly protocols to satisfy 3-A Sanitary Standards validation requirements.
Growth Catalysts
- EU Hygienic Equipment Design Group guidelines:Mandated surface finish specifications below 0.8 micrometers Ra are accelerating stainless steel 316L pump replacements across continental European dairy cooperatives.
- Precision dosing migration:Pharmaceutical-grade peristaltic pump technology is absorbing share from diaphragm systems in probiotic and functional beverage formulation lines.
- Stuttgart-Düsseldorf manufacturing corridor:Engineering-intensive pump clusters in Germany are capturing continental European beverage chain demand through localized technical service networks.
Market Restraints
- Nickel alloy cost volatility:Stainless steel 316L feedstock price swings are compressing margin stability for mid-tier pump fabricators serving price-sensitive sauce processors.
- Seal material transition friction:Evolving PFAS restrictions in Europe are forcing premature gasket inventory obsolescence and qualification timeline extensions.
- Positive displacement shear limits:Diaphragm pump technology faces technical ceilings in high-viscosity yogurt applications where aseptic centrifugal designs dominate.
Strategic Opportunities
- India FSSAI enforcement expansion:Stricter food safety audits in Indian dairy processing are creating first-mover advantage for CE-marked pump suppliers with documented risk assessments.
- Heat exchanger-pump bundling:Integrated process system architectures are opening service contract expansion paths beyond standalone equipment sales.
- California state-level packaging regulations:Material specification shifts for seals and gaskets are enabling specification influence through early compliance positioning.
Industry Challenges
- Sanitary welding certification scarcity:Qualified orbital welders for 316L pump fabrication command premium wages and extended recruitment cycles in Midwest US dairy equipment hubs.
- Legacy control system integration:Retrofitting smart pump monitoring into existing SCADA architectures requires custom protocol bridging and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Industry Pumps Market |
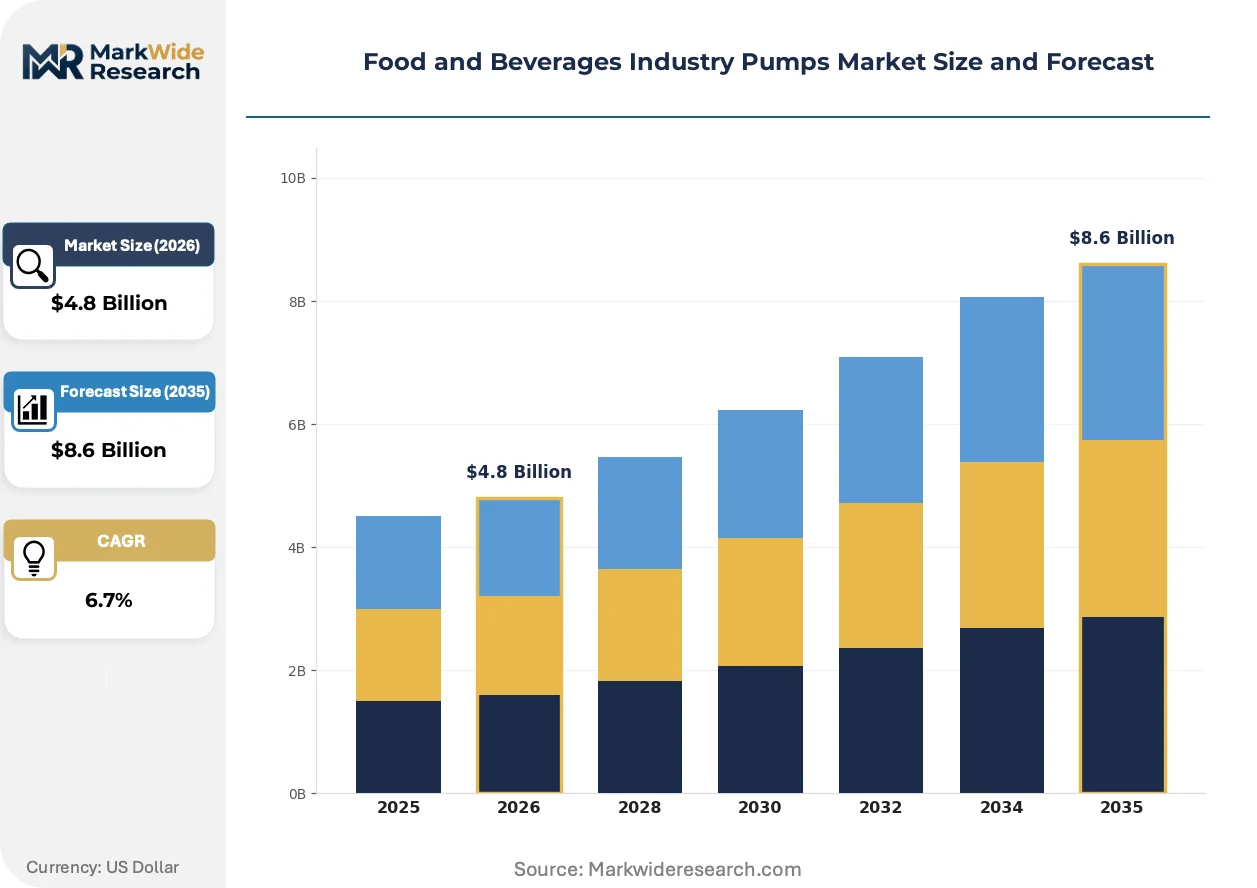
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Pumps, Diaphragm Pumps, Centrifugal Pumps, Screw Pumps Application: Liquid Transfer, Ingredient Dosing, Mixing, Spray Applications End User: Beverage Makers, Dairy Producers, Packaged Food Manufacturers, Confectionery Companies Technology: Manual Pumps, Electric Pumps, Pneumatic Pumps, Automated Systems |
| Companies Covered | KSB SE & Co. KGaA, SPX Flow, Alfa Laval, Verder Liquids, JBT, GEA Group, Grundfos Holding A/S, Graco Inc., Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Industry Pumps Market Emerging Trajectories
Digital twin architectures and predictive maintenance algorithms are restructuring how pump lifecycle value is captured, shifting revenue models from equipment transactions toward performance-guaranteed service agreements.
Magnetic drive sealless pump technology is absorbing contamination risk in aseptic high-viscosity applications, displacing traditional mechanical seal configurations. Premium yogurt and sauce processors in Germany and Switzerland are adopting these systems at accelerated replacement cycles. The technology is absorbing maintenance budget allocations previously directed toward seal inventory and changeout labor.
REACH chemical authorization procedures are tightening material compliance documentation requirements for elastomer components in food-contact pumps. European pump fabricators must now maintain substance of very high concern tracking across supply tiers. Dairy equipment suppliers in the Netherlands and Denmark are responding by consolidating qualified material suppliers and accelerating in-house compound testing capabilities.
After-sales service unbundling is fragmenting traditional full-service contracts into modular offerings covering spare parts, remote monitoring, and field technician dispatch. Beverage multinationals in North America are selecting component-level service providers through competitive tender rather than accepting captive maintenance agreements. This pattern is most visible in carbonated soft drink bottling operations where line uptime guarantees now drive pump vendor selection criteria.
Food and Beverages Industry Pumps Market Segmentation
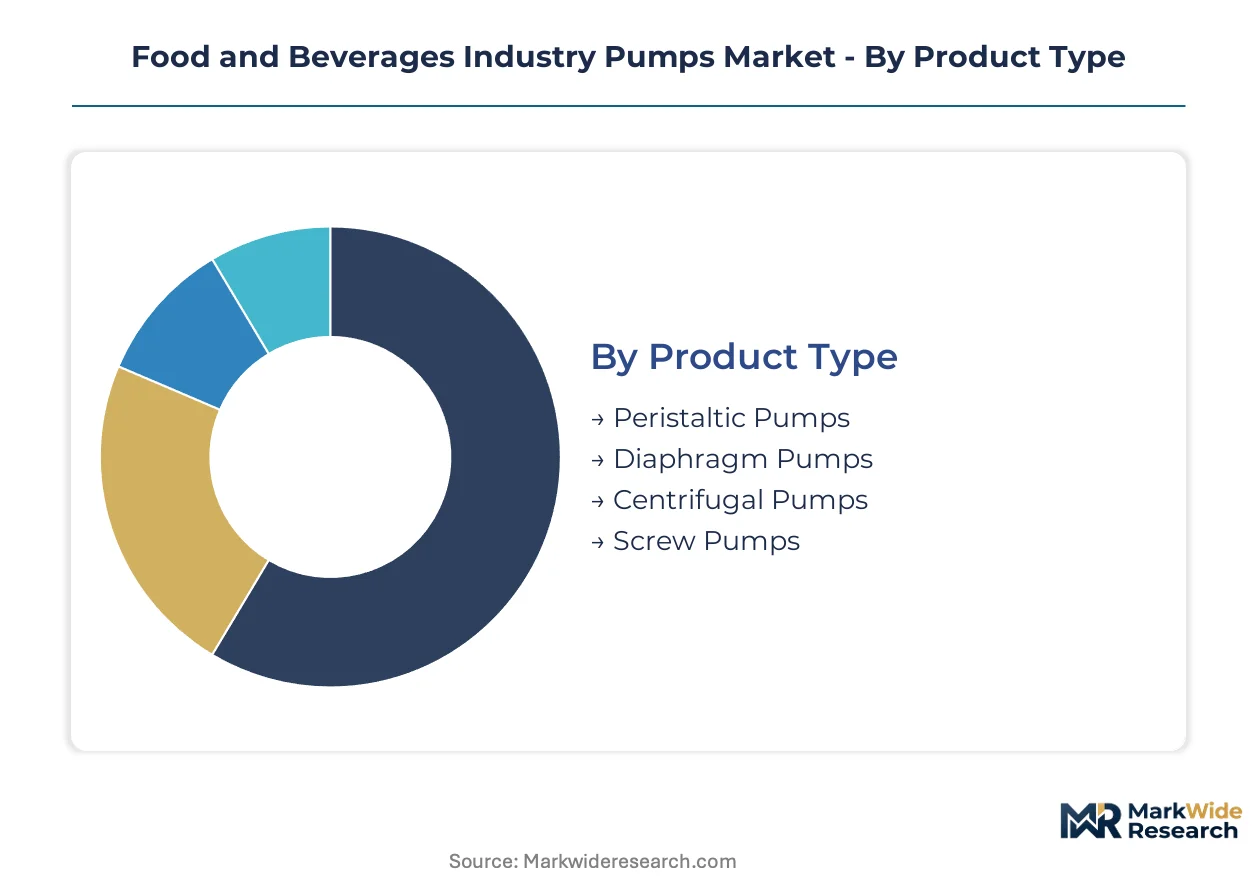
Pump selection in food and beverage processing hinges on viscosity profiles, sanitary requirements, and integration depth within continuous production lines. Segmentation reveals where standalone equipment sales persist versus bundled system architectures.
Product Type:
Standalone pumps dominate replacement cycles and small-batch operations, while embedded pump modules anchor integrated process skids for greenfield dairy and beverage installations.
- Centrifugal Pumps:Stainless steel 316L housings with surface finishes below 0.8 micrometers Ra enable clean-in-place protocols without disassembly. German dairy cooperatives around Stuttgart specify these for low-shear milk transfer to preserve protein structures and organoleptic properties.
- Peristaltic Pumps:Pharmaceutical-grade tubing technology delivers precision dosing within ±1% accuracy for probiotic and functional beverage formulations. Demand concentrates in Swiss and Danish pharmaceutical-to-food crossover facilities where aseptic validation protocols migrate downstream.
- Diaphragm Pumps:Positive displacement architecture prevents phase separation in viscous confectionery applications.
- Screw Pumps:Progressive cavity designs handle high-viscosity sauces with minimal shear degradation.
Centrifugal pumps lead volumes today; peristaltic pumps are gaining share fastest.
Application:
High-volume liquid transfer commands the largest equipment footprint, though precision dosing applications carry superior margin profiles due to validation documentation requirements.
- Liquid Transfer:Continuous-flow milk and juice handling in automated dairy lines. German engineering-intensive clusters capture continental European beverage chain procurement through localized technical service networks.
- Ingredient Dosing:Probiotic culture and flavor additive metering demands pharmaceutical-grade precision. Swiss yogurt processors specify peristaltic systems with FDA 21 CFR Part 110 compliance documentation.
- Mixing:In-line blending of emulsions and suspensions for sauce production.
- Spray Applications:Coating and surface treatment in confectionery manufacturing.
Liquid transfer anchors installed base; ingredient dosing shows steepest expansion trajectory.
End User:
Consolidation among multinational processors is hardening buyer concentration and compressing supplier lists to reduce compliance overhead.
- Dairy Producers:Automated pump installations expand to meet EU Hygienic Equipment Design Group surface finish mandates. Netherlands and Denmark equipment suppliers consolidate qualified material suppliers to address REACH chemical authorization documentation.
- Beverage Makers:Carbonated soft drink bottlers in North America select component-level service providers through competitive tender rather than captive maintenance agreements.
- Packaged Food Manufacturers:Sauce and dressing processors face nickel alloy cost volatility in stainless steel 316L feedstock.
- Confectionery Companies:Viscous product handling requires positive displacement architectures with aseptic validation.
Dairy producers dominate current procurement; beverage makers are expanding specification influence fastest.
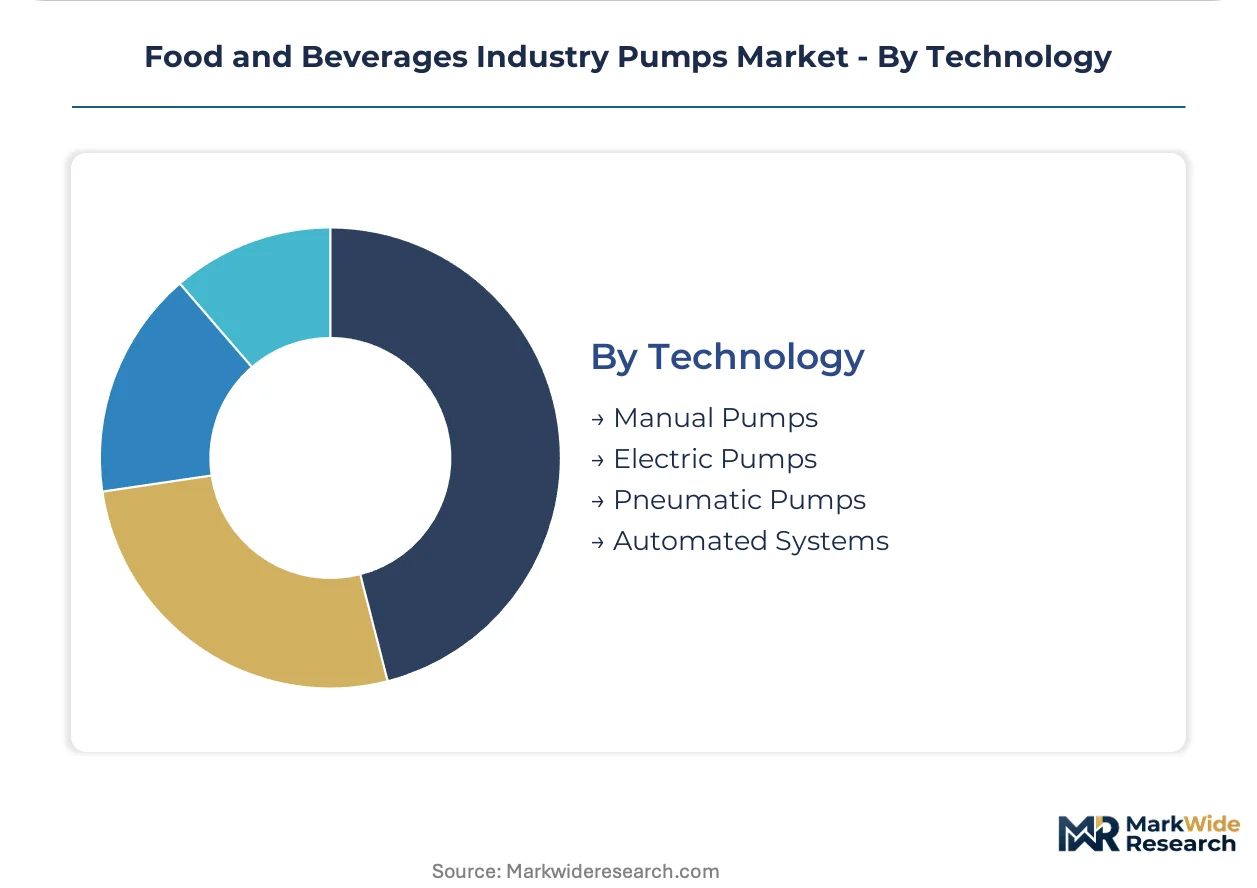
Technology:
Control system sophistication determines maintenance economics and line uptime guarantees that drive vendor selection criteria.
- Automated Systems:Digital twin architectures and predictive maintenance algorithms restructure lifecycle value capture toward performance-guaranteed service agreements. Magnetic drive sealless configurations absorb contamination risk in German and Swiss premium yogurt processing.
- Electric Pumps:Variable frequency drives enable energy optimization across duty cycles. Retrofitting smart monitoring into existing SCADA architectures requires custom protocol bridging.
- Pneumatic Pumps:Explosion-safe operation in solvent-adjacent flavor extraction facilities.
- Manual Pumps:Limited to small-batch artisanal operations and emergency backup roles.
Electric pumps maintain installed base leadership; automated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital welding specialists and sanitary equipment engineers concentrate in Germany's Stuttgart-Düsseldorf corridor, anchoring continental Europe's engineering-intensive pump fabrication capacity.
United States
Dairy cooperatives in Wisconsin and California expand automated pump installations to satisfy USDA 3-A Sanitary Standards validation requirements. FDA 21 CFR Part 110 enforcement drives material documentation burdens across Midwest processing hubs. Qualified orbital welders for 316L fabrication command premium wages in Wisconsin's dairy equipment manufacturing belt.
Germany
Stuttgart and Düsseldorf engineering clusters serve continental European beverage and dairy chains through localized technical service networks. EU Hygienic Equipment Design Group surface finish mandates below 0.8 micrometers Ra accelerate stainless steel 316L replacements. REACH chemical authorization procedures tighten elastomer compliance documentation for Dutch and Danish dairy equipment suppliers sourcing through German fabricators.
Switzerland
Premium yogurt processors adopt magnetic drive sealless pump configurations at accelerated replacement cycles. Swissmedic pharmaceutical-grade validation protocols migrate into food-contact equipment specifications. Basel-Zurich pharmaceutical-to-food crossover facilities concentrate peristaltic pump demand for probiotic culture metering.
India
FSSAI enforcement expansion in dairy processing creates first-mover advantage for CE-marked pump suppliers with documented risk assessments. Maharashtra and Gujarat dairy cooperatives upgrade processing lines to meet stricter national food safety audit protocols. Pune and Ahmedabad industrial corridors attract European pump vendors establishing localized technical service presences.
Netherlands
Dairy equipment suppliers consolidate qualified material suppliers to address REACH substance of very high concern tracking requirements. Rotterdam-Antwerp port logistics clusters facilitate stainless steel 316L feedstock distribution to continental fabricators. Eindhoven region pump component specialists accelerate in-house compound testing capabilities for elastomer compliance.
Food and Beverages Industry Pumps Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Engineering-intensive fabricators anchor long-term service contracts through technical proximity to dairy cooperatives. Three archetypes dominate: integrated process system bundlers, aseptic design specialists, and precision dosing technology crossovers from pharmaceutical applications. Competitive moves concentrate on heat exchanger-pump bundling architectures and predictive maintenance algorithm development for performance-guaranteed service agreements.
Within the diversified industrial conglomerate tier, KSB SE & Co. KGaA and GEA Group exemplify engineering-intensive fabricators leveraging geographic proximity to European dairy processing clusters. SPX Flow occupies a position among integrated process system providers bundling pumps with adjacent thermal and mixing equipment. Alfa Laval represents the aseptic design specialist archetype, with Verder Liquids and Graco Inc. anchoring the precision dosing technology segment. Grundfos Holding A/S and Atlas Copco sit within the scale-driven pump manufacturing tier serving beverage multinational procurement consolidation.
| Leading Market Players |
|---|
| KSB SE & Co. KGaA |
| SPX Flow |
| Alfa Laval |
| Verder Liquids |
| JBT |
| GEA Group |
| Grundfos Holding A/S |
| Graco Inc. |
| Atlas Copco |
| Others |
Supply Flow & Price Mechanics
Magnetic drive sealless pump technology is compressing maintenance budgets and redistributing procurement power toward premium-tier fabricators in Germany and Switzerland. This engineering transition simultaneously elevates upfront capital requirements and consolidates supplier relationships around technical service networks.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting traditional full-service contracts into modular offerings covering spare parts, remote monitoring, and field technician dispatch. Three-tier pricing structure across premium, standard, and economy levels separates magnetic drive sealless configurations from electric pump baselines and manual backup systems. Cost compression in mid-tier stainless steel 316L pumps is intensifying because nickel alloy feedstock volatility erodes fabricator margins. Packaged food manufacturers exhibit highest price sensitivity due to consolidated procurement lists, while Swiss premium yogurt processors show lowest sensitivity given aseptic validation requirements.
Supply Chain Analysis
Freight cost escalation from Rotterdam-Antwerp port logistics clusters is feeding into stainless steel 316L feedstock distribution economics across continental fabricators. Supply concentrates in Germany, Netherlands, and Denmark for engineering-intensive pump fabrication. Component sourcing draws from Italian elastomer specialists for REACH-compliant gaskets, Swedish steel mills for 316L billet, and Swiss magnetic drive component suppliers. Single-source vulnerability concentrates in qualified orbital welders for sanitary 316L fabrication. Distribution runs through technical service networks anchored in Stuttgart-Düsseldorf corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food and Beverages Industry Pumps Market functions as a stable compounder where regulatory hygiene mandates generate replacement-driven demand regardless of macroeconomic cycles. Equipment upgrade timelines are hardening as FDA and EU enforcement tightens.
For Market Incumbents: Deploy predictive maintenance algorithm development to capture performance-guaranteed service agreement revenue streams. Incumbents should anchor backward integration into elastomer compound testing to preempt REACH authorization disruptions. KSB SE and GEA Group exemplify defensive positioning through localized technical service networks in German dairy clusters. For New Entrants and Emerging Players: Capture first-mover positioning in Indian FSSAI enforcement expansion where CE-marked pump demand outstrips qualified supplier presence. White-space concentrates in Maharashtra and Gujarat dairy cooperative upgrades. Go-to-market should leverage Pune and Ahmedabad industrial corridor technical service presences rather than equipment-only sales. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fabricators lacking integrated process system bundling capabilities. Long-term viability hinges on recurring service revenue attachment rates rather than transactional equipment margins. Acquisition targets should demonstrate documented risk assessment capabilities for CE marking. The signal to watch is consolidation of qualified material suppliers in Netherlands and Denmark addressing REACH substance tracking.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Exchanger-Pump Bundling | SPX Flow captures service contract expansion through integrated process skid architectures. |
| Predictive Maintenance Algorithm Development | Digital twin architectures restructure lifecycle value toward performance-guaranteed agreements. |
| Magnetic Drive Sealless Configuration Expansion | Premium yogurt processors in Germany absorb contamination risk and compress replacement cycles. |
| REACH-Compliant Elastomer Supplier Consolidation | Dutch and Danish equipment suppliers accelerate in-house compound testing capabilities. |
| India Technical Service Localization | European vendors establish Pune and Ahmedabad presences to capture FSSAI-driven upgrade cycles. |
Methodological Framework
Multiple input streams — plant engineer interviews, procurement lead discussions, maintenance director surveys, and aftermarket service head consultations — were reconciled against regulatory filing databases and customs trade records. Secondary validation drew from FDA 21 CFR Part 110 enforcement documentation, EU Hygienic Equipment Design Group guidelines, FSSAI audit protocols, and SEC equipment supplier filings. Bottom-up triangulation across dairy cooperative procurement patterns and top-down cross-reference against beverage multinational capital expenditure disclosures anchored volume estimates.
Historical shipment data was cross-referenced against panel input from German engineering clusters and Swiss pharmaceutical-to-food crossover facilities. Segmentation modeling spanned pump type, application viscosity profile, automation technology tier, and end-user consolidation level. CAGRs were derived from replacement cycle compression analysis and regulatory mandate timeline alignment. Forecast inputs incorporated REACH chemical authorization trajectory and 3-A Sanitary Standards validation requirement diffusion.
Underlying measurement precision varies by segment; automated system and magnetic drive sealless categories carry tighter precision than manual pump estimates. Forecasts reflect assumptions about regulatory enforcement consistency and nickel alloy price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market