
 Digital Levels Market | 2026-2036
Digital Levels Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Levels Market Insights
IP65-rated and MIL-SPEC durability tiers is reorganizing procurement priorities across the digital levels sector. Bosch leverages its captive sensor manufacturing to control cost structures in the mid-market. Leica Geosystems anchors premium positioning through geodetic-grade calibration protocols. Stabila Messgeräte Gustav Ullrich GmbH specializes in European trade-channel distribution for professional framers.
A digital level is an electronic inclinometer equipped with liquid-crystal or OLED readouts, MEMS accelerometers, and angular resolution typically between 0.05° and 0.1°, designed to replace bubble vials in construction alignment and structural surveying. Laser Technology products dominate volume shipments due to established contractor familiarity, while Bluetooth Enabled units capture expanding margin pools as connected jobsite ecosystems mature. Site Surveying applications lead absolute dollar contribution, though Interior Design represents an accelerating specification channel among residential architects.
ISO 17123-2 governs electronic level testing protocols, while CE marking under the EU Machinery Directive shapes market access for European-bound products. OSHA fall-protection and excavation standards in the United States indirectly elevate demand for grade-verification tools on commercial sites. Stakeholders must weigh sensor-modularity roadmaps against the risk of stranded inventory as wireless calibration and cloud-logging capabilities redefine replacement cycles.
Market Dynamics
Bluetooth-enabled connectivity is compressing replacement cycles across the digital levels sector as contractors integrate inclinometers into cloud-based jobsite management platforms. MEMS accelerometer miniaturization simultaneously lowers unit costs while raising precision thresholds, forcing incumbents to recalibrate tiered product portfolios.
Growth Catalysts
- OSHA excavation standards:Fall-protection mandates on US commercial sites elevate specification rates for grade-verification tools among general contractors.
- Residential architects:Interior design applications accelerate as open-plan layouts demand sub-degree angular precision for visual alignment.
- MEMS sensor cost curves:Semiconductor process improvements reduce bill-of-materials pressure for mid-market digital level manufacturers.
Market Restraints
- Geographic supply concentration:Captive sensor fabrication clusters in East Asia expose downstream assemblers to single-source disruption risk.
- Smartphone inclinometer substitution:Free gyroscope apps on contractor phones erode demand for entry-level digital levels below 0.1° resolution.
- REACH substance restrictions:EU chemical compliance adds certification overhead for OLED display and battery component suppliers.
Strategic Opportunities
- Cloud-logging integration:Wireless calibration data streams enable subscription-based firmware update revenue from fleet operators.
- EU Machinery Directive alignment:CE marking harmonization opens cross-border trade for modular sensor platforms across Germany, France, and Benelux.
- Geodetic-grade calibration:Surveying contractors in Japan seek ISO 17123-2 certified units for structural monitoring contracts.
Industry Challenges
- MEMS calibration technician scarcity:Precision accelerometer alignment requires specialized metrology skills concentrated in German and Japanese industrial clusters.
- Wireless protocol fragmentation:Competing Bluetooth mesh, LoRa, and proprietary RF standards force multi-stack engineering investments.
- Cloud data residency compliance:German construction firms demand EU-sovereign server infrastructure for logged measurement records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Levels Market |
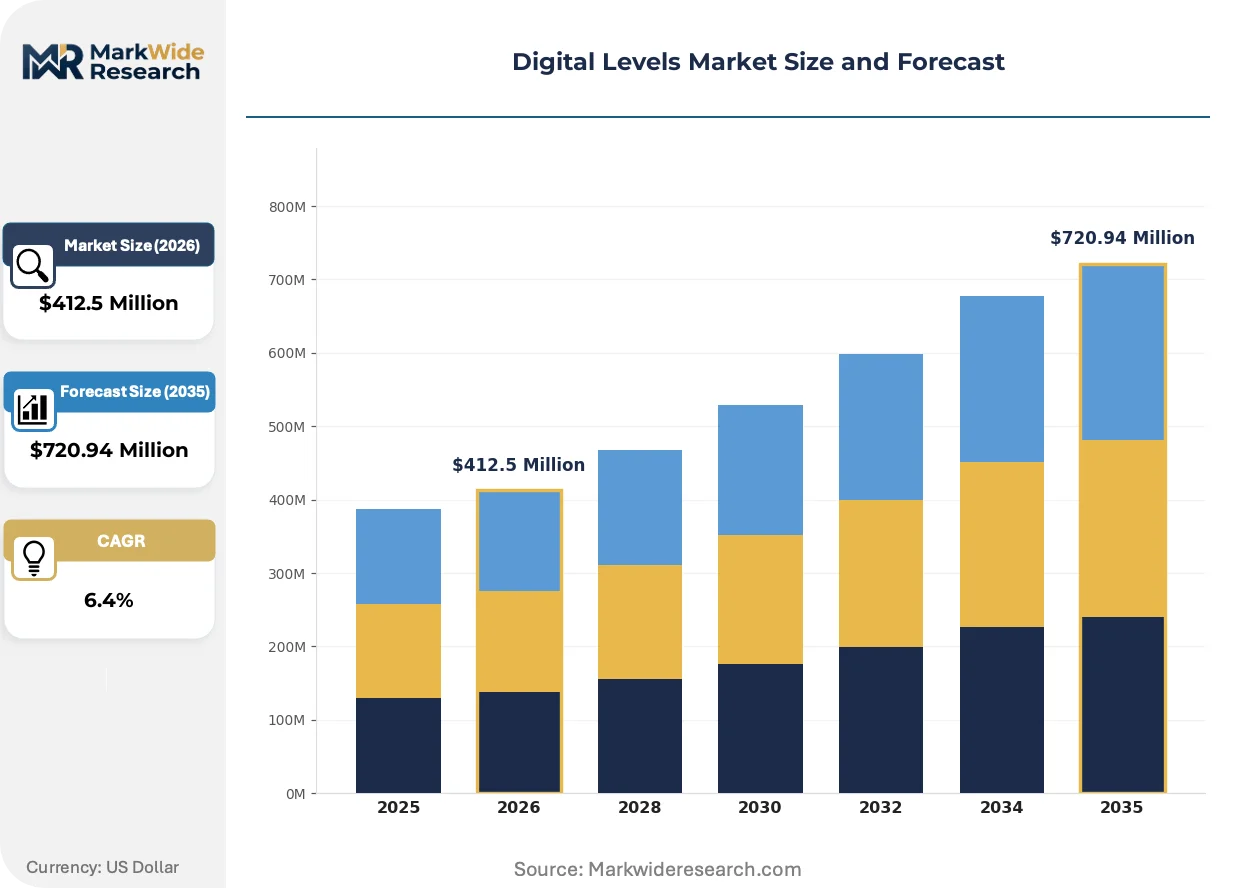
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Levels, Digital Inclinometers, Electronic Levels, Smart Levels End User: Construction Professionals, Homeowners, Engineers, Contractors Technology: Bluetooth Enabled, Laser Technology, Digital Display, GPS Assisted Application: Site Surveying, Interior Design, Framing, Alignment Tasks |
| Companies Covered | Leica Geosystems, Topcon Corporation, Bosch, Stabila Messgeräte Gustav Ullrich GmbH, Johnson Level & Tool, Hilti Corporation, Trimble Inc., Craftsman, Husky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Levels Market Trends and Innovations
OLED readouts and laser line projection are converging to redefine contractor workflows. Equipment specification now prioritizes connectivity ecosystems over standalone accuracy metrics.
MEMS-based digital inclinometers with 0.05° resolution are displacing traditional spirit levels in commercial framing crews. Large-scale residential developers in the United States specify connected units for real-time grade verification across multi-building portfolios. This displacement compresses the addressable market for bubble-vial manufacturers while expanding recurring revenue potential for firmware-enabled tool vendors.
CE marking under the EU Machinery Directive now mandates electromagnetic compatibility testing for battery-powered measurement devices. German importers reject non-compliant shipments at Rotterdam and Hamburg ports, forcing Asian contract manufacturers to add shielding and filtering components. Premium positioning now correlates directly with notified body certification depth rather than raw sensor specifications.
Equipment rental channels now bundle digital levels with cloud calibration subscriptions, unbundling the traditional purchase-own-depreciate model. National rental chains in Japan and the United States pilot usage-based pricing for geodetic-grade units. This shift concentrates procurement authority with fleet managers rather than individual jobsite supervisors, raising minimum order quantities and squeezing smaller distributors.
Digital Levels Market Segmentation
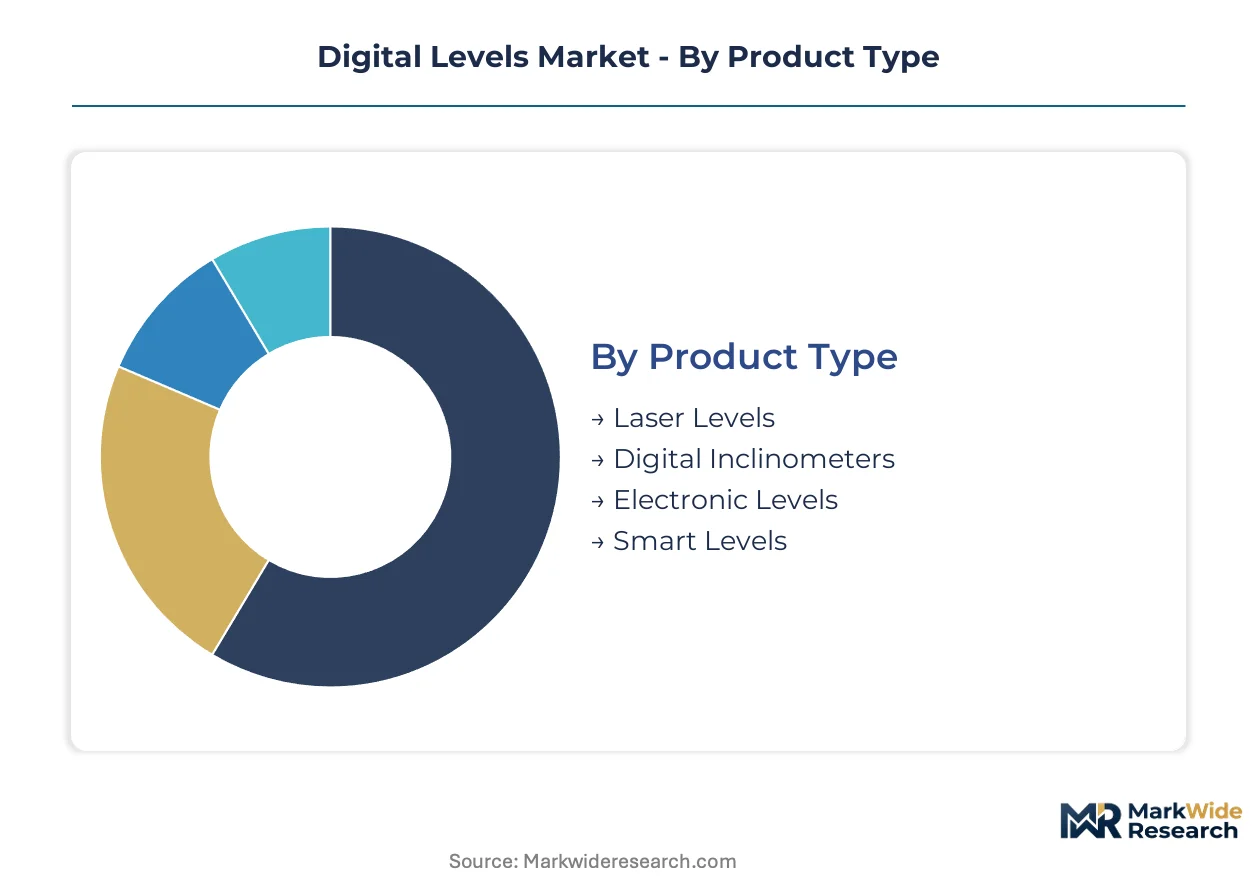
Digital levels fragment across four intersecting dimensions that reshape procurement authority and margin capture. Product architecture determines hardware cost structures while connectivity protocols redefine recurring revenue potential across contractor workflows.
Product Type:
Laser-equipped variants command premium positioning through optical subsystem complexity, while MEMS-based inclinometers dominate unit economics in price-sensitive channels.
- Laser Levels:Diode-pumped solid-state emitters project visible reference lines across 30-50 meter ranges with ±0.2mm/m accuracy. German commercial framing contractors specify these for foundation layout where OSHA excavation standards mandate grade verification.
- Digital Inclinometers:MEMS accelerometer cores deliver 0.05° angular resolution in handheld form factors. Japanese structural monitoring contracts favor these for ISO 17123-2 certified tilt measurements on earthquake-resistant buildings.
- Electronic Levels:Bubble-vial replacements with LCD readouts target residential renovation markets. These units sacrifice connectivity for battery longevity and physical durability.
- Smart Levels:Integrated IMU arrays with cloud-logging firmware enable real-time data streaming to jobsite management platforms. US multi-building developers pilot these for portfolio-wide grade standardization.
The dominant share belongs to Laser Levels, while Smart Levels is closing the gap fastest.
End User:
Procurement authority concentrates with fleet operators and specification engineers rather than individual tradespeople.
- Construction Professionals:General contractors on US commercial sites drive specification for IP65-rated units under OSHA fall-protection mandates. Their purchasing decisions prioritize calibration traceability and warranty terms over unit price.
- Engineers:Geodetic surveyors in Japan demand ISO 17123-2 certified devices with documented measurement uncertainty budgets. Their procurement requires notified body certification depth that filters out mid-market alternatives.
- Contractors:Specialty trades—electrical, HVAC, and finish carpentry—represent volume demand for 0.1° resolution units. Japanese equipment rental channels bundle these with cloud subscriptions.
- Homeowners:DIY renovation activity in Germany sustains entry-level demand despite smartphone inclinometer substitution. CE marking compliance remains the threshold barrier for retail distribution.
Construction Professionals capture the largest addressable spend, though Engineers deliver the steepest expansion trajectory through precision-tier upgrades.
Technology:
Wireless protocol selection determines ecosystem lock-in and firmware monetization potential.
- Bluetooth Enabled:Low-energy stacks enable cloud calibration data streams and over-the-air firmware updates. US national rental chains pilot usage-based pricing models through these connectivity layers.
- Laser Technology:Established contractor familiarity sustains volume shipments despite higher bill-of-materials costs. German importers require electromagnetic compatibility testing under EU Machinery Directive for battery-powered variants.
- Digital Display:OLED readouts displace LCD panels in premium tiers, though REACH substance restrictions add certification overhead for EU-bound products.
- GPS Assisted:Multi-constellation receivers enable georeferenced tilt logging for large-scale earthworks. These units concentrate in Japanese civil engineering applications requiring JIS-standard position accuracy.
Bluetooth Enabled units are gaining share fastest as connected jobsite ecosystems mature, while Laser Technology retains absolute volume leadership.
Application:
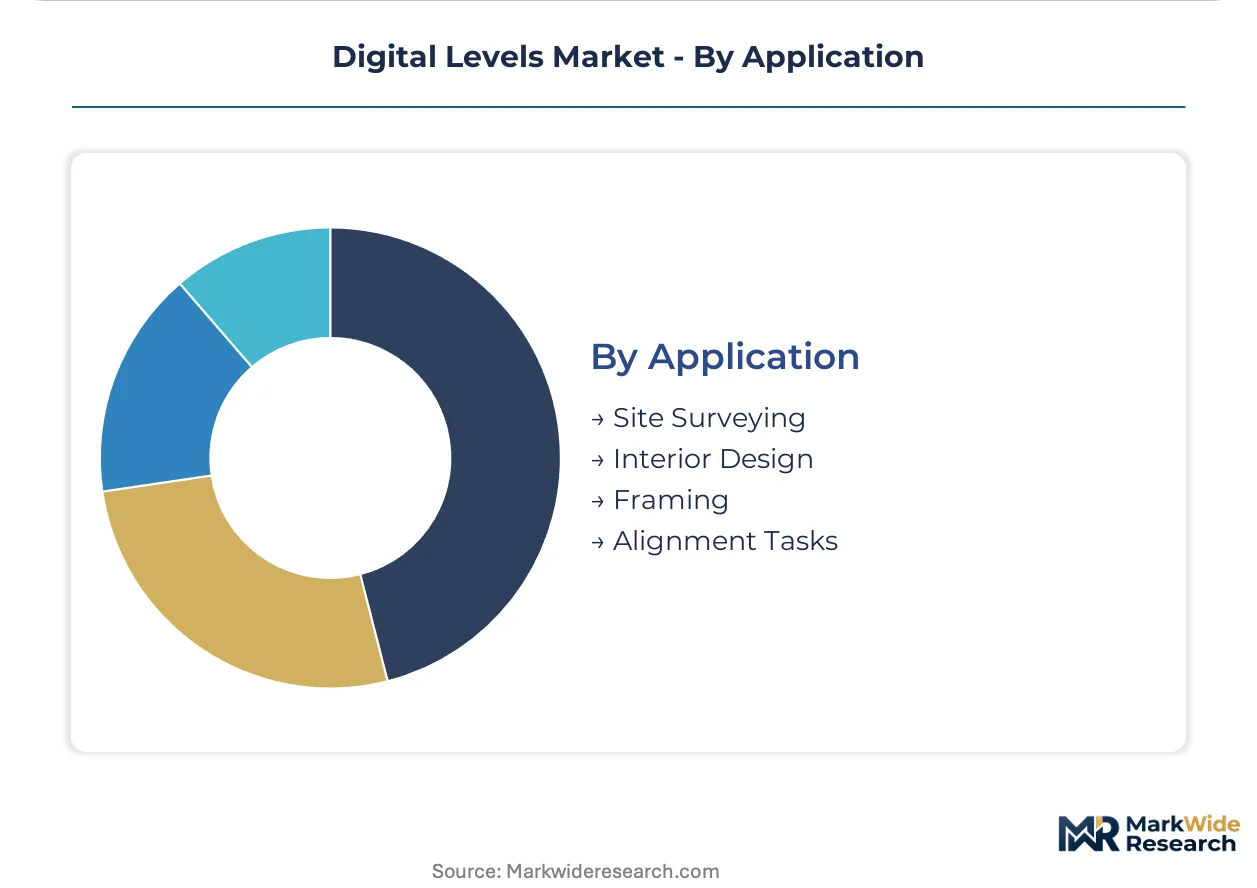
Use-case specificity dictates accuracy thresholds and durability requirements.
- Site Surveying:Geodetic-grade calibration protocols support structural monitoring and deformation analysis. Japanese contractors specify these for ISO 17123-2 compliance on infrastructure contracts.
- Interior Design:Open-plan residential layouts demand sub-degree angular precision for visual alignment of fixtures and finishes. German architects drive specification acceleration in this channel.
- Framing:Commercial crews in the United States specify connected units for real-time grade verification across multi-building portfolios. MEMS-based inclinometers displace traditional spirit levels here.
- Alignment Tasks:Machinery installation and industrial maintenance require repeatability rather than absolute accuracy. These applications sustain demand for mid-tier electronic levels.
Site Surveying contributes the largest absolute dollar value, while Interior Design climbs fastest as residential architecture specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor fabrication clusters concentrate in East Asia, yet specification authority and fleet procurement decisions concentrate in Germany, Japan, and the United States. This geographic split shapes trade flows, certification requirements, and distributor margins across the sector.
United States
OSHA excavation and fall-protection mandates on commercial sites elevate specification rates for grade-verification tools. General contractors prioritize IP65-rated units with documented calibration traceability. Fleet operators in Texas and California pilot usage-based pricing models for connected inclinometers.
Germany
CE marking under the EU Machinery Directive mandates electromagnetic compatibility testing for battery-powered measurement devices. Importers at Rotterdam and Hamburg ports reject non-compliant shipments. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate notified body certification expertise for geodetic-grade calibration protocols.
Japan
Structural monitoring contracts for earthquake-resistant buildings require ISO 17123-2 certified tilt measurements. METI procurement guidelines favor JIS-standard position accuracy for civil engineering applications. Equipment rental channels in Tokyo and Osaka bundle digital levels with cloud calibration subscriptions.
China
Domestic MEMS accelerometer production scales through semiconductor process improvements. MIIT standards govern wireless protocol compatibility for connected jobsite devices. Manufacturing clusters in the Yangtze River Delta supply downstream assemblers with cost-optimized sensor modules.
United Kingdom
Residential renovation activity sustains entry-level demand despite smartphone inclinometer substitution. REACH substance restrictions add certification overhead for OLED display components. Distribution networks in the Southeast and Midlands prioritize CE-marked products for cross-border trade alignment.
Digital Levels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure with limited overlap between premium calibration specialists and volume-driven sensor integrators. The market fragments across three strategic archetypes: geodetic-grade calibration houses, captive sensor manufacturers with backward integration into accelerometer fabrication, and trade-channel distributors with European framing specialization. Dominant competitive moves include strategic partnerships for cloud-logging platform integration and portfolio diversification into connected jobsite ecosystems.
Among German-based precision instrument specialists, Leica Geosystems and Stabila Messgeräte Gustav Ullrich GmbH occupy positions on the premium-tier vector, representing archetypes of geodetic-grade calibration depth and European trade-channel dominance respectively. Bosch exemplifies the captive manufacturing archetype through in-house sensor production that controls mid-market cost structures. These three anchors illustrate how geographic origin and corporate structure correlate with competitive positioning in a market where certification depth increasingly outweighs raw sensor specifications.
| Leading Market Players |
|---|
| Leica Geosystems |
| Topcon Corporation |
| Bosch |
| Stabila Messgeräte Gustav Ullrich GmbH |
| Johnson Level & Tool |
| Hilti Corporation |
| Trimble Inc. |
| Craftsman |
| Husky |
| Others |
Pricing and Supply Chain Analysis
MEMS accelerometer substitution for traditional mechanical inclinometers redraws manufacturing geography toward East Asian semiconductor clusters while compressing bill-of-materials costs across all pricing tiers. This input transition simultaneously elevates calibration expertise premiums in German and Japanese industrial centers and intensifies margin pressure on assemblers lacking captive sensor fabrication.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European-bound shipments, separating ISO 17123-2 certified geodetic units from uncertified economy alternatives. Price differentiation rests on calibration traceability depth and IP65 durability ratings rather than raw angular resolution. Pricing pressure stems from smartphone inclinometer substitution eroding entry-level demand below 0.1° resolution. Fleet operators exhibit lowest price sensitivity due to usage-based subscription models, while German DIY retailers face highest sensitivity from REACH compliance cost pass-through.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Rotterdam trade lane expose downstream assemblers to inbound logistics volatility for MEMS sensor modules. Geographic supply concentration centers on China, Taiwan, and South Korea for accelerometer fabrication, with German and Japanese clusters dominating calibration equipment. Raw material dependencies include silicon wafers, rare-earth magnets for laser diodes, and lithium-ion cells. Single-source vulnerability persists for geodetic-grade calibration reference standards. Distribution runs through national equipment rental chains in Japan and the United States, bypassing traditional trade-channel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent digital level manufacturers face substitution defense against free smartphone gyroscope applications and cloud-integrated jobsite platforms. The imperative is to embed connectivity layers that render standalone measurement insufficient.
For Market Incumbents: Compound defensive moats through backward integration into MEMS sensor fabrication and exclusive cloud-platform partnerships with construction management software vendors. Smartphone inclinometer substitution threatens entry-tier volumes; counter by bundling firmware subscriptions with hardware to lock fleet operators into recurring revenue streams. Certification investment in ISO 17123-2 protocols preserves premium positioning against Asian cost competitors. For New Entrants and Emerging Players: Anchor in the Interior Design specification channel where German residential architects demand sub-degree precision without requiring geodetic-grade calibration overhead. This segment shows fastest specification acceleration with lowest incumbent lock-in. Target Bluetooth-enabled units for connected jobsite pilot programs among US multi-building developers. Go-to-market angle: usage-based pricing partnerships with equipment rental channels in Tokyo and Osaka. For Investors and Strategic Acquirers: The market sits at a connectivity inflection phase that favors modular sensor platform specialists over standalone hardware manufacturers. Long-term viability hinges on firmware monetization and cloud-logging subscription attach rates rather than unit shipment volumes. Acquisition target archetype: European trade-channel distributors with captive calibration technician networks. Signal to watch: Japanese METI procurement guideline revisions favoring JIS-standard position accuracy mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Logging Platform Integration | Enables subscription revenue from US fleet operators adopting usage-based pricing models. |
| ISO 17123-2 Certification Investment | Opens Japanese structural monitoring contracts requiring documented measurement uncertainty budgets. |
| MEMS Sensor Backward Integration | Controls cost structures against East Asian supply concentration and tariff exposure risks. |
| Equipment Rental Channel Partnership | Concentrates procurement authority with fleet managers in Texas and California pilot markets. |
| CE Marking Harmonization | Secures port access at Rotterdam and Hamburg for battery-powered measurement devices. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU customs records, and construction equipment trade databases to validate market sizing and competitive positioning. Primary interviews engaged product managers at precision instrument manufacturers, procurement leads at national equipment rental chains, calibration technicians in German industrial clusters, and specification engineers at Japanese civil engineering contractors. Secondary sources included OSHA regulatory filings, METI procurement guidelines, ISO standard documentation, and semiconductor industry bill-of-materials analyses. Bottom-up unit shipment estimates triangulate against top-down addressable construction spend allocations.
Segmentation dimensions modeled span product architecture, connectivity protocol, end-user procurement authority, and application-specific accuracy requirements across the projection horizon. The analytical framework derives CAGRs from substitution curve analysis of MEMS accelerometer displacement against traditional spirit levels, calibrated against construction equipment replacement cycle data. Industry-specific forecast inputs include Bluetooth adoption rates in connected jobsite ecosystems and cloud-subscription attach rates among fleet operators.
Material uncertainties — MEMS sensor cost curve acceleration, wireless protocol standardization outcomes, and EU REACH substance restriction expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding calibration technician availability and rental channel consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Power Tools Market
Tools
Multi Spindle Machines Market
Tools
Brushcutter Market
Tools
Orbital Recip Saw Market
Tools
Global Tool Holder Adapters Market
Tools
Europe Woodworking Power Tools Market
Tools
Bar Clamp Market
Tools
Yard Scraper Market
Tools
Rivet Busters Market
Tools
Drill Bit Market
Tools
Floor Saw Market
Tools
Pipe Alignment Clamps Market
Tools
Diamond Hole Saw Market
Tools
Spray Gun Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Workholding Tools Market