
 Global Elastic Rail Fasteners Market | 2026-2036
Global Elastic Rail Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastic Rail Fasteners Market Foresight
High-speed rail operators are rotating procurement priority toward integrated fastening kits over discrete component sourcing. Vossloh Fastening Systems dominates European supply through captive forging capacity and direct rail operator relationships. Pandrol anchors North American and Commonwealth markets with specification-grade elastic clip systems. Shanghai Honge Fastener Industry competes on cost-optimized cold-forged clip production for Asia-Pacific infrastructure contractors.
Elastic rail fasteners are mechanical clamping devices manufactured from spring steel or polymer composites that maintain rail gauge and dampen dynamic loads through controlled toe load deflection. Hot-forged elastic clips and cast insulated sleeper plates constitute the mature volume base, while powder metallurgy rail pads are gaining share in heavy-haul applications for extended fatigue life. Cold-forged fastening kits lead urban transit segments where installation speed and total cost drive contractor selection. High-speed rail applications command premium specification tiers due to EN 13481 and AREMA compliance requirements for clip fatigue resistance.
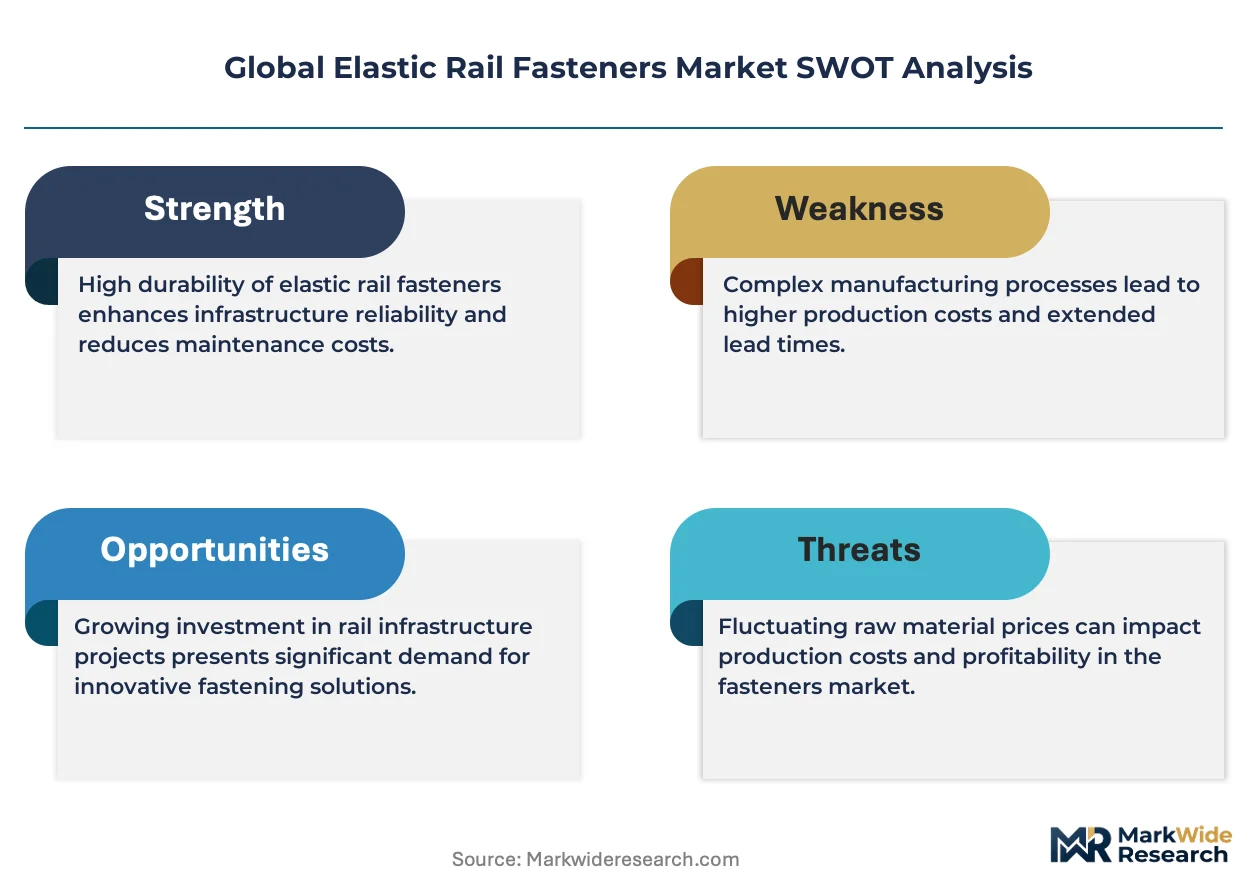
Federal Railroad Administration track safety standards and European Union TSIs govern product qualification for North American and EU deployments, while China's NMPA-aligned GB/T rail standards enforce domestic content ratios for state-funded lines. India's BIS certification and RDSO specifications create parallel compliance pathways for fastening system suppliers targeting Dedicated Freight Corridor contracts. Stakeholders must monitor evolving interoperability mandates between national rail networks and assess backward integration into specialty steel forging to defend margin structures against alloy price volatility.
Market Dynamics
Hot-forged elastic clip production is consolidating around captive forging capacity in Germany and China, squeezing mid-tier suppliers dependent on outsourced specialty steel processing as alloy price volatility compresses margin structures.
Growth Catalysts
- China's GB/T rail standards:Domestic content mandates for state-funded high-speed corridors are channeling procurement toward certified local fastening system manufacturers.
- Heavy-haul freight corridors:Powder metallurgy rail pads are penetrating bulk commodity transport routes for extended fatigue life under extreme axle loads.
- Urban transit expansion:Cold-forged fastening kits are displacing hot-forged alternatives in metro construction where contractor schedules prioritize installation velocity.
Market Restraints
- Specialty steel input volatility:Spring steel alloy prices fluctuate with nickel and chromium spot markets, destabilizing cost structures for non-integrated forge operators.
- European supply concentration:EN 13481 certification pathways favor incumbent forging houses with established rail operator relationships, raising barriers for new entrants.
- Polymer composite substitution:Glass-reinforced nylon sleeper plates are capturing share in light-rail and tram applications where dynamic loads permit reduced material specification.
Strategic Opportunities
- India's Dedicated Freight Corridor:BIS certification and RDSO specifications are opening parallel compliance pathways for fastening suppliers targeting 3,800 kilometers of new track.
- Integrated sensor-embedded clips:Convergence of mechanical fastening with IoT load-monitoring hardware is creating premium specification tiers for predictive maintenance contracts.
- AREMA specification alignment:North American freight railroads are consolidating procurement around standardized clip systems, favoring suppliers with dual EN/AREMA certification capacity.
Industry Challenges
- EN 13481 fatigue testing timelines:European qualification protocols require 18-24 months for clip validation, compressing product development cycles against infrastructure tender deadlines.
- Legacy track gauge interoperability:Mixed-gauge corridors in Commonwealth networks demand fastening system variants that complicate inventory and field support logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastic Rail Fasteners Market |
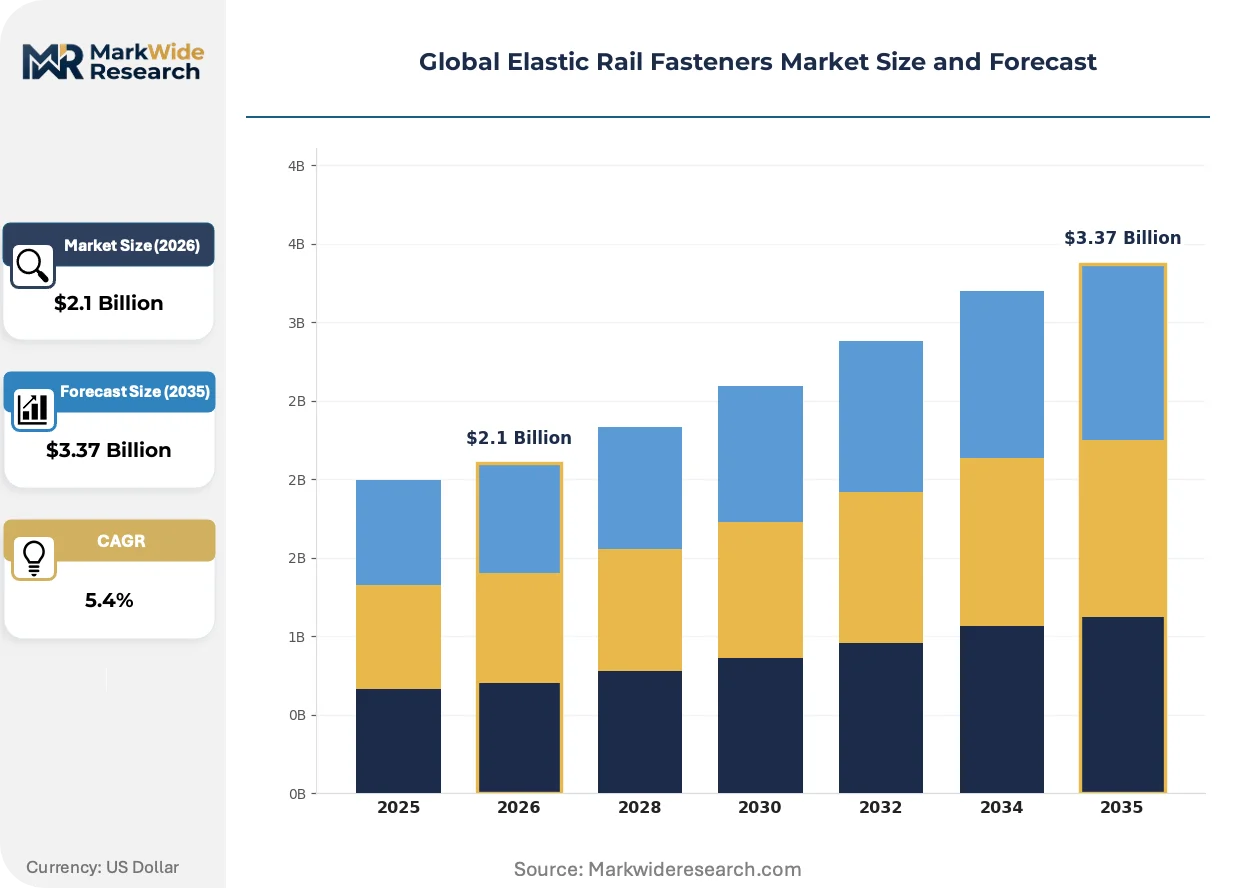
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Clips, Rail Pads, Insulated Sleeper Plates, Fastening Kits Technology: Hot Forging, Cold Forging, Casting, Powder Metallurgy Application: High-Speed Rail, Freight Transport, Urban Transit, Heavy Haul End User: Rail Operators, Infrastructure Contractors, Maintenance Providers, Equipment Manufacturers |
| Companies Covered | Plastwil, Shanghai Honge Fastener Industry, Vossloh Fastening Systems, Suyu, KVT, Pandrol, Tianjin Luda, Taicang Zhongbo, Lederer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastic Rail Fasteners Market Shifts & Advancements
Powder metallurgy manufacturing is compressing traditional forging economics while regulatory pressure on embodied carbon is reshaping material specification pathways across continental rail networks.
Additive manufacturing of rail pad inserts is decomposing conventional casting and machining cost structures for low-volume, geometrically complex components. European maintenance contractors are piloting topology-optimized polymer-composite pads for curved track sections where uniform pressure distribution is critical. This fabrication shift is enabling rapid prototyping of customer-specific pad geometries without hard-tooling investment, compressing supplier response times from months to weeks.
REACH restrictions on chromium VI compounds in surface treatments are forcing conversion to trivalent chrome and zinc-nickel plating across European supply chains. The regulation's industrial consequence is elevated processing cost for corrosion-resistant clip finishes, with compliance investments concentrated among mid-tier forge operators lacking captive plating capacity. German and French rail infrastructure managers are now specifying REACH-compliant coatings as mandatory bid prerequisites, accelerating supplier consolidation.
Specification-grade procurement is displacing component-level sourcing as high-speed rail operators consolidate vendor accountability through integrated fastening kit contracts. Asian infrastructure contractors are bundling clip, pad, and insulator procurement under single-source agreements that transfer installation liability to system suppliers. This pattern is most visible in China's state-funded corridor projects, where turnkey fastening packages now dominate tenders for new 350 km/h lines.
Global Elastic Rail Fasteners Market Segmentation
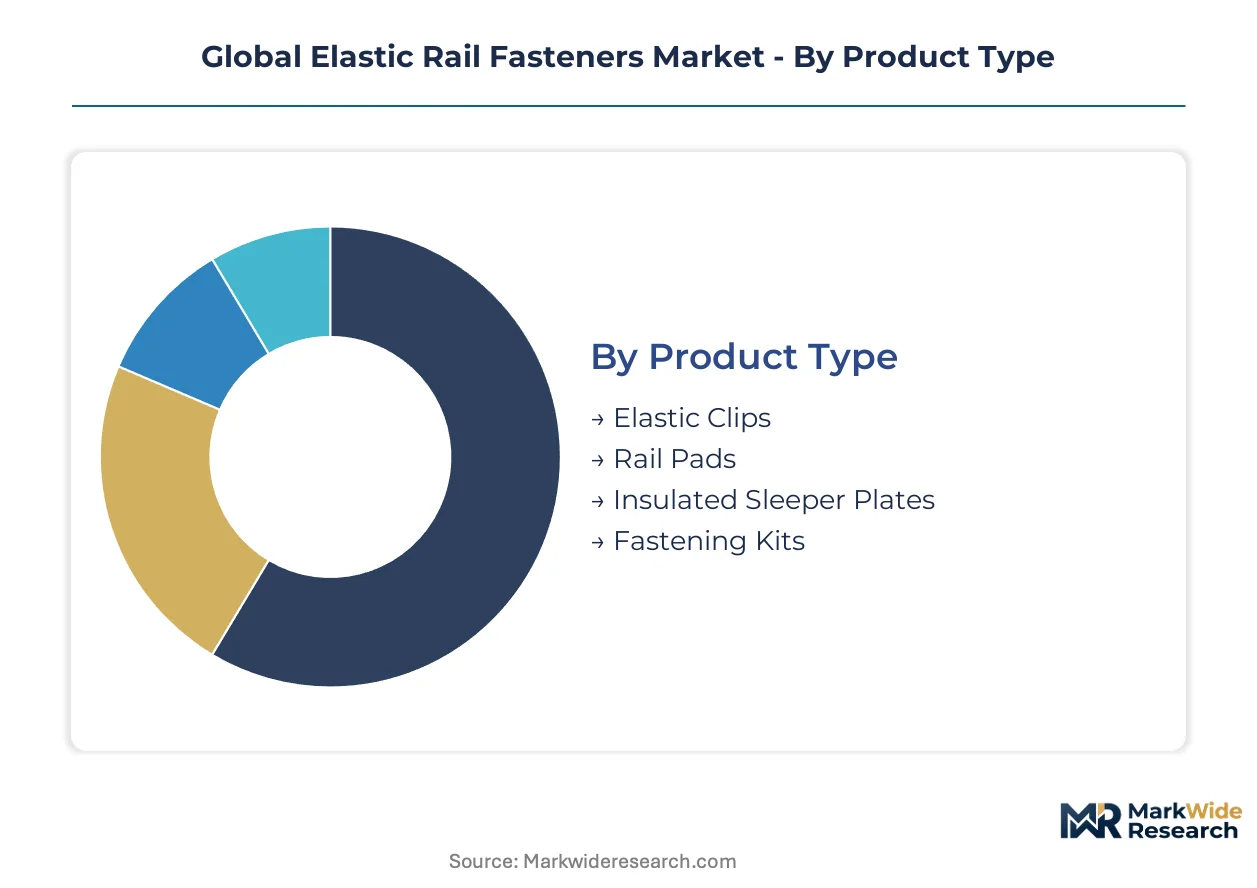
Elastic rail fastener procurement fragments across technical specifications, manufacturing methods, and contract structures that reshape supplier economics. Each segmentation axis reveals distinct margin profiles and certification barriers that determine competitive positioning in state-funded corridors versus commercial freight lines.
Product Type:
Domestic production dominates elastic clips and fastening kits in China and India through GB and BIS certification mandates, while rail pads and insulated sleeper plates flow through specialized European and Japanese suppliers serving export markets.
- Elastic Clips:Spring steel clamping devices manufactured through hot or cold forging processes maintain rail gauge under dynamic wheel loads. Procurement concentrates among German and Chinese rail operators modernizing legacy track, with EN 13481 and GB standards tightening fatigue resistance specifications for high-speed deployments.
- Fastening Kits:Integrated assemblies bundling clips, pads, insulators, and torque-controlled bolting systems transfer installation liability to system suppliers. Asian infrastructure contractors favor these packages for urban transit and high-speed corridor tenders where single-source accountability compresses project risk.
- Rail Pads:Polymer composite or steel-reinforced cushioning elements dampen vertical loads between rail foot and sleeper.
- Insulated Sleeper Plates:Cast or fabricated baseplates maintain electrical isolation in track circuits while distributing rail loads.
Elastic clips hold the largest share; momentum sits with fastening kits.
Technology:
Cost tier differentiation separates captive forging operations from outsourced processing, with powder metallurgy commanding premium positioning in fatigue-critical applications.
- Hot Forging:High-temperature forming of spring steel alloys produces specification-grade clips with controlled grain structure for heavy-haul and high-speed rail. German and Chinese operators with captive forging capacity dominate this tier, leveraging backward integration into specialty steel supply to buffer alloy price volatility.
- Powder Metallurgy:Sintered metal processing enables complex geometries with uniform density distribution, extending fatigue life under extreme axle loads. Heavy-haul freight corridors in Australia and Brazil specify these pads for bulk commodity routes where maintenance access is limited.
- Cold Forging:Room-temperature forming reduces energy input and cycle times for high-volume clip production serving cost-sensitive urban transit markets.
- Casting:Molten metal pouring of insulated sleeper plates and baseplates serves lower-load applications with simpler geometric requirements.
Hot forging anchors volume production; powder metallurgy is climbing the fastest.
Application:
Customer type and project scale determine specification grade, with state-funded high-speed rail demanding certified premium tiers while freight operators prioritize lifecycle cost optimization.
- High-Speed Rail:Track systems operating above 200 km/h require EN 13481 or AREMA-compliant fastening with validated clip fatigue resistance and precise toe load retention. China's state-funded 350 km/h corridors and India's upcoming dedicated passenger routes concentrate procurement among certified system suppliers.
- Urban Transit:Metro and light-rail installations prioritize installation velocity and total project cost over extreme fatigue specifications. Cold-forged fastening kits displace hot-forged alternatives in these segments where contractor schedules drive material selection.
- Freight Transport:General cargo rail lines balance initial capital cost against maintenance cycle predictability.
- Heavy Haul:Extreme axle load corridors serving mining and bulk commodity flows demand extended component life under punishing duty cycles.
High-speed rail commands premium pricing; urban transit shows steepest expansion trajectory.
End User:
Supply concentration varies sharply between direct rail operator procurement and contractor-mediated sourcing, with maintenance providers emerging as a distinct channel for retrofit and renewal applications.
- Rail Operators:State-owned and privatized railway companies in Germany, China, and India specify fastening systems directly for new track and major renewals, leveraging long-term supplier relationships and captive technical standards.
- Infrastructure Contractors:Engineering-procurement-construction firms bundling track installation services drive specification in Asia-Pacific urban transit and corridor projects, favoring integrated fastening kits that transfer performance risk.
- Maintenance Providers:Specialized renewal contractors and rail maintenance firms source replacement clips and pads for existing track.
- Equipment Manufacturers:Rolling stock and track machinery OEMs procure fastening components for integrated system offerings or maintenance vehicle provisioning.
Rail operators hold the largest share; infrastructure contractors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai High-Speed Railway anchors China's procurement dominance, while Germany's Rhine-Alpine freight corridor and India's Dedicated Freight Corridor network concentrate demand across three continents. State-funded modernization programs in each geography are tightening certification requirements and reshaping supplier qualification pathways.
China
State-funded 350 km/h corridors drive specification-grade fastening procurement under GB/T rail standards with mandatory domestic content ratios. NMPA-aligned certification pathways channel contracts toward certified local manufacturers. Yangtze River Delta infrastructure contractors in Shanghai and Jiangsu province consolidate procurement through integrated fastening kit tenders.
Germany
Rhine-Alpine freight corridors and ICE network renewals sustain demand for EN 13481-compliant hot-forged clips with validated fatigue resistance. ECHA REACH restrictions on chromium VI surface treatments force coating conversions among forge operators. Ruhr Valley forging clusters leverage captive specialty steel capacity to buffer alloy price volatility.
India
Dedicated Freight Corridor construction spanning 3,800 kilometers opens procurement for BIS-certified fastening systems under RDSO specifications. CEA rail electrification mandates accelerate track modernization spending. Gujarat and Maharashtra industrial corridors concentrate contractor activity for western route segments.
United States
Class I freight railroads consolidate procurement around AREMA-standardized clip systems for heavy-haul routes. FRA track safety standards govern product qualification for new installations and renewals. Midwest rail manufacturing clusters in Illinois and Ohio anchor domestic supply chain coordination.
Japan
Shinkansen network maintenance and Hokkaido freight upgrades sustain demand for precision-engineered fastening components. METI industrial standards and JIS specifications enforce quality benchmarks for rail infrastructure materials. Kansai region manufacturers around Osaka supply domestic operators and export markets.
Global Elastic Rail Fasteners Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and captive forging capacity. The vendor base stratifies between integrated system suppliers with rail operator relationships and component fabricators serving contractor procurement. Two archetypes dominate: forge operators with backward integration into specialty steel supply, and fastening kit assemblers bundling outsourced components. Capacity expansion and certification portfolio diversification constitute the primary competitive moves.
Among European forging houses, Vossloh Fastening Systems exemplifies the integrated tier with direct rail operator relationships. Shanghai Honge Fastener Industry anchors Chinese cost-optimized production for Asia-Pacific infrastructure contractors. Pandrol occupies a position bridging specification-grade supply across Commonwealth and North American markets.
| Leading Market Players |
|---|
| Plastwil |
| Shanghai Honge Fastener Industry |
| Vossloh Fastening Systems |
| Suyu |
| KVT |
| Pandrol |
| Tianjin Luda |
| Taicang Zhongbo |
| Lederer |
| Others |
Supply & Pricing Matrix
EN 13481 certification pathways gate both supplier qualification and price differentiation in European procurement, compressing mid-tier forge operators between premium-tier incumbents and cost-optimized Asian imports while channeling contract value toward integrated kit providers with validated fatigue resistance.
Pricing Analysis
Volume-discount tiering structures stratify procurement across specification grades, with hot-forged clips commanding premium positioning against cold-forged alternatives. Price differentiation hinges on EN 13481 fatigue certification tier and captive specialty steel forging capacity. Pricing pressure stems from nickel and chromium alloy volatility destabilizing non-integrated operators. Infrastructure contractors show highest price sensitivity, while state-funded high-speed rail operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Ruhr Valley specialty steel forging clusters anchor European supply, with Yangtze River Delta manufacturers and Indian BIS-certified producers completing the tripartite sourcing base. Raw material flows draw from spring steel alloy mills, polymer composite feedstock processors, and surface treatment chemical suppliers. Supply chain risk centers on REACH-compliant coating conversion costs elevating mid-tier forge operator exit rates. Distribution runs through direct rail operator contracts in Germany and China, contractor-mediated procurement in India, and AREMA-aligned distributor networks in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fastening system procurement is shifting toward predictive maintenance service contracts, with IoT-embedded clip monitoring and lifecycle performance guarantees expanding faster than discrete hardware sales across state-funded corridor projects.
For Market Incumbents: Consolidate captive forging capacity in Germany and China to buffer alloy price volatility, while extending certification portfolios to capture India's Dedicated Freight Corridor BIS pathways. Polymer composite substitution in light-rail segments threatens traditional cast plate margins, demanding R&D pivot toward sensor-integrated mechanical fastening. For New Entrants and Emerging Players: Predictive maintenance analytics for existing track infrastructure represents an underserved service layer where incumbents lack digital capabilities. India's western corridor segments offer lowest certification barrier entry, with RDSO specification alignment enabling contractor channel access through integrated kit assembly rather than forge investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cold-forged urban transit segments as powder metallurgy pad production scales. Five-to-ten-year viability favors acquiring mid-tier forge operators with EN 13481 certification backlog but lacking REACH-compliant plating capacity, with coating conversion cost absorption serving as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Forging | Ruhr Valley and Yangtze Delta operators buffer margin compression from nickel-chromium volatility through captive alloy supply. |
| REACH-Compliant Surface Treatment Conversion | German and French rail infrastructure managers mandate trivalent chrome coatings, accelerating supplier consolidation among plating-capable forges. |
| Integrated Sensor-Embedded Clip Development | Predictive maintenance contracts for China's 350 km/h corridors require mechanical-IoT convergence validated under GB/T standards. |
| BIS Certification Portfolio Expansion | Dedicated Freight Corridor awards favor suppliers with parallel EN 13481 and RDSO qualification pathways. |
| Powder Metallurgy Rail Pad Scale-Up | Australian and Brazilian heavy-haul routes specify sintered metal pads for extended fatigue life under extreme axle loads. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and industry association disclosures, combining structured interviews with rail operator procurement directors, infrastructure contractor project managers, forge operator plant engineers, and maintenance provider fleet directors with validation against BIS certification records, ECHA REACH compliance registries, and AREMA specification updates, applying bottom-up contract aggregation and top-down market sizing triangulation.
Segmentation dimensions modeled span manufacturing technology tier, application specification grade, end-user procurement channel, and regional regulatory cluster across the projection horizon, with CAGRs derived from elasticity-adjusted demand curves and input cost trajectory modeling, incorporating specialty steel alloy price forecasting and certification timeline lag effects as rail-specific forecast inputs.
Forecasts assume regulatory continuity in ECHA REACH enforcement, BIS certification mandates, and FRA track safety standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as India's RDSO specification evolution and China's domestic content ratio adjustments unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Global Anchors and Grouts Market