
 Gouging Torch Market | 2026-2036
Gouging Torch Market Size, Share, and Industry Trends Forecast 2026-2036
Gouging Torch Market Analytics
Shipbuilding is realigning gouging torch procurement toward high-amperage air carbon arc systems for thick-plate hull work. Lincoln Electric Holdings dominates North American distribution through captive welding supply channels. ESAB Corporation anchors European maritime demand with specialized torch configurations for shipyard automation. Illinois Tool Works Inc. differentiates via R&D intensity in consumable electrode alloys that extend torch tip longevity.
A gouging torch is a thermal cutting tool that removes metal by directing an intense arc or flame onto a workpiece, typically operating at 600–1,000 amperes for carbon arc variants to melt and blast away material in preparation for welding or defect removal. The process employs a copper-clad carbon electrode and compressed air stream to eject molten metal from the kerf, serving primary industrial purposes in weld groove preparation, crack elimination, and structural repair across ferrous alloys. Air carbon arc systems lead product type demand in heavy fabrication due to lower equipment cost and portability, while plasma arc configurations capture margin pools in precision aerospace applications where heat-affected zone control is critical. Metal fabrication and shipbuilding applications currently absorb the majority of unit volume, though repair services represent the fastest-growing application segment as aging infrastructure maintenance cycles shorten across industrial economies.
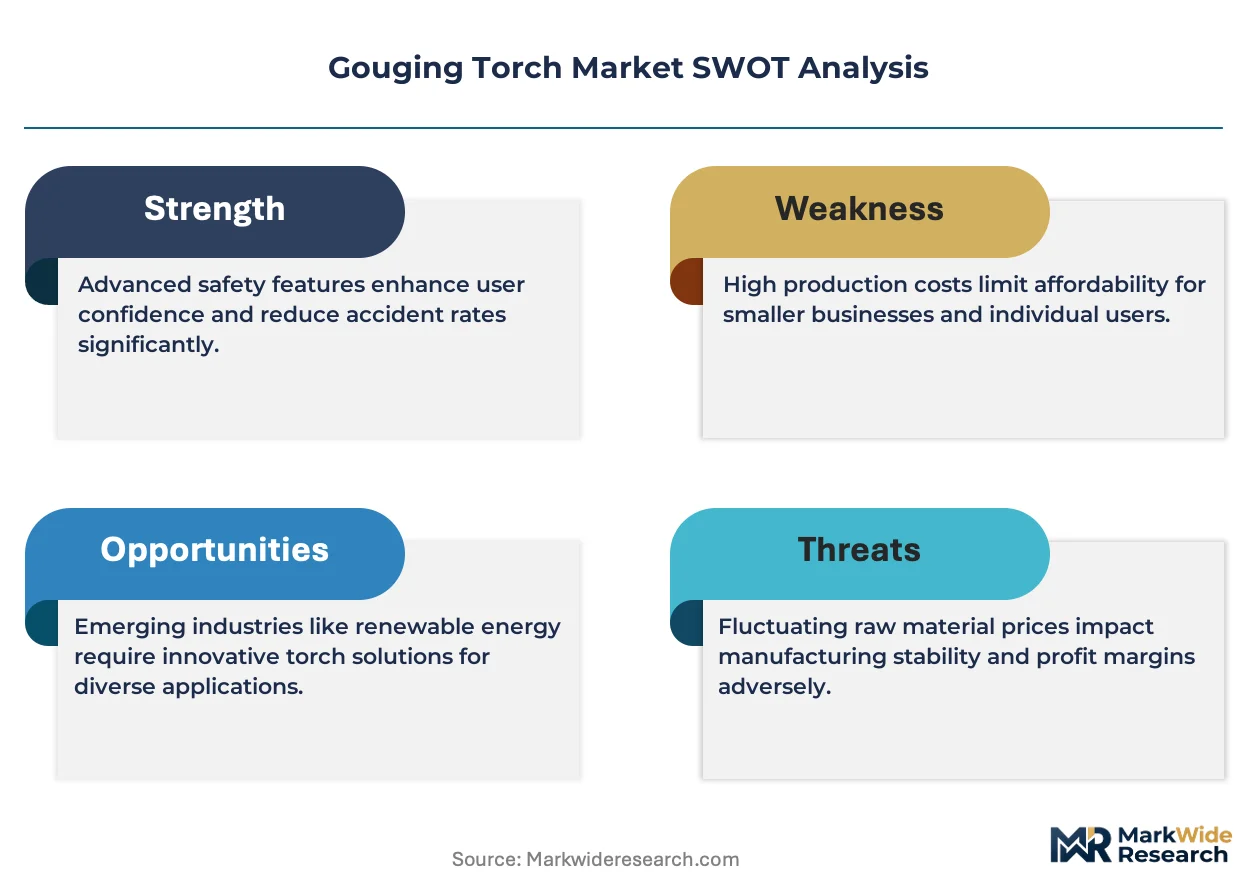
OSHA ventilation standards and EPA particulate emissions rules govern American gouging torch operation, compelling fabricators to invest in fume extraction integration. The EU F-Gas Regulation and REACH chemical restrictions shape European product design, limiting certain gas mixtures and mandating cleaner process alternatives. Japan's METI industrial efficiency guidelines promote plasma arc adoption to reduce energy intensity in metalworking. Stakeholders must monitor evolving electrode material compliance costs and power source efficiency thresholds as regulatory divergence between jurisdictions complicates cross-border equipment standardization.
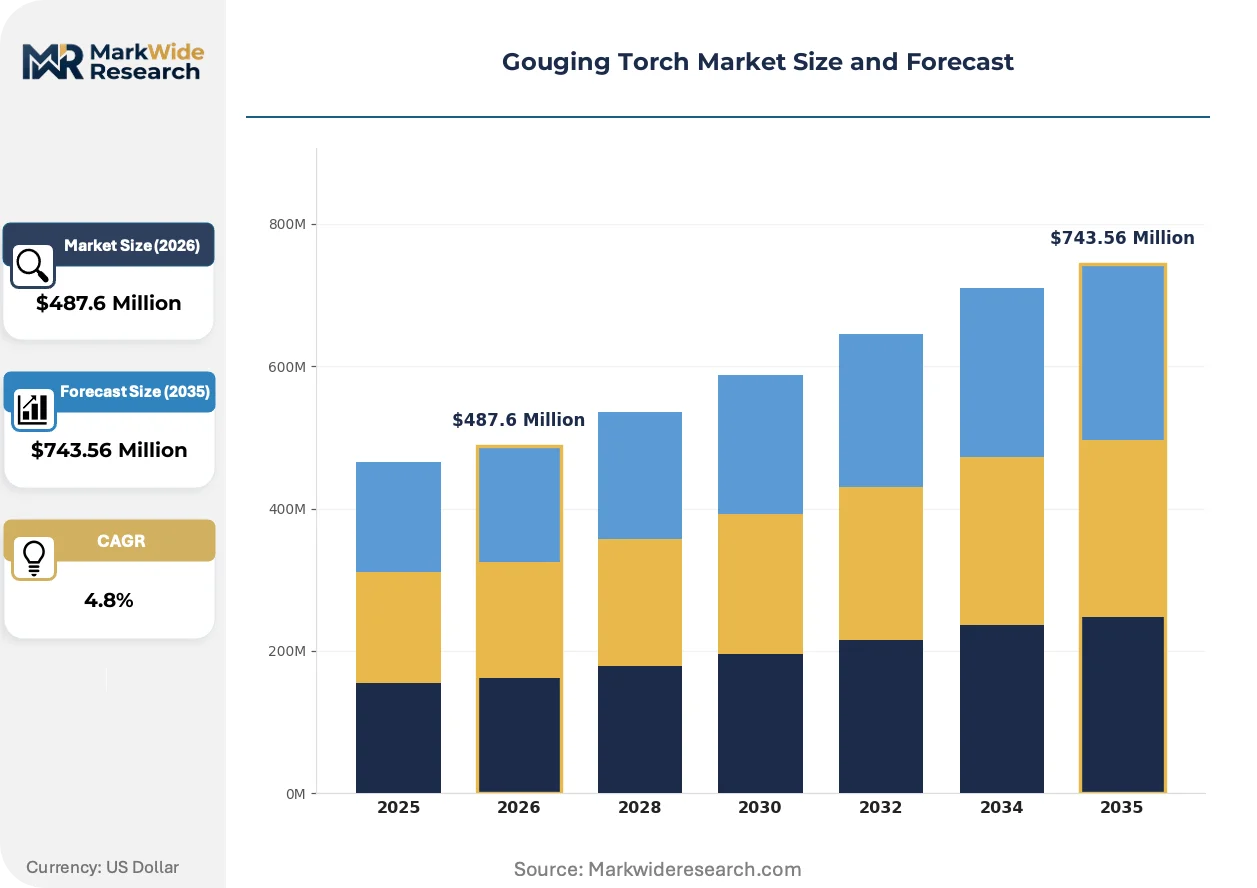
Market Dynamics
Shipbuilding yards in South Korea and Japan are accelerating carbon arc gouging adoption for hull repair, while EU emissions rules compress gas-based cutting alternatives. This regulatory-technology tension is redistributing equipment demand toward electric plasma systems and high-amperage air carbon arc configurations.
Growth Catalysts
- EU F-Gas Regulation:Tightening emissions standards for gas-based cutting processes are pushing European shipyards toward electric plasma gouging systems, expanding addressable equipment demand.
- East Asian maritime clusters:Naval and commercial vessel output remains elevated in South Korean and Japanese manufacturing hubs, concentrating procurement of thick-plate gouging equipment.
- Compressed air integration:Advances in portable compressor systems are extending carbon arc gouging mobility across remote repair sites and aging infrastructure projects.
Market Restraints
- Copper-clad electrode supply concentration:Electrode manufacturing concentrates in select Asian suppliers, exposing fabricators to input cost volatility and logistics bottlenecks.
- Plasma arc capital intensity:Precision plasma systems require substantially higher upfront investment than air carbon arc alternatives, limiting adoption among small-scale metal fabricators.
- OSHA ventilation compliance:American fume extraction mandates add operational overhead, compressing margins for contract repair services operating on thin project economics.
Strategic Opportunities
- India shipyard modernization:The country's PLI scheme for domestic manufacturing is creating procurement windows for automated gouging torch configurations in emerging maritime facilities.
- Aerospace precision applications:Heat-affected zone control requirements in titanium and nickel alloy work are opening margin pools for specialized plasma arc torch variants.
- Japan METI efficiency guidelines:Industrial energy intensity mandates are accelerating plasma arc replacement of oxy-fuel systems, creating regulatory tailwinds for equipment vendors.
Industry Challenges
- Certified operator scarcity:Qualified carbon arc gouging technicians remain concentrated in legacy shipbuilding regions, constraining expansion into emerging repair markets.
- Cross-border standardization friction:Divergent electrode material compliance requirements between EPA particulate rules and REACH chemical restrictions complicate equipment platform standardization for multinational fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gouging Torch Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Carbon Arc, Plasma Arc, Gas Welding, Flame Gouging Application: Metal Fabrication, Construction, Shipbuilding, Repair Services End User: Automotive Industry, Aerospace Sector, Manufacturing Plants, Workshops Power Source: Acetylene, Propane, Electricity, Mixed Gas |
| Companies Covered | Lincoln Electric Holdings, ESAB Corporation, Illinois Tool Works Inc., Fronius International GmbH, Arcair, Parweld, Castolin Eutectic, Wilhelmsen, Weldmark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gouging Torch Market Evolving Landscape
Process electrification and automation are converging to reshape gouging torch specifications, with regulatory pressure on emissions and labor costs accelerating technology substitution cycles across heavy fabrication verticals.
Automated plasma arc gouging systems with integrated CNC positioning are overtaking manual carbon arc methods in precision hull preparation workflows. South Korean shipbuilders are deploying these configurations at scale for double-hull tanker construction. The technology is overtaking conventional manual torch setups by compressing weld preparation time and reducing rework rates in thick-plate applications.
The EU F-Gas Regulation is systematically restricting fluorinated gas use in thermal cutting processes, compelling equipment redesign toward all-electric plasma alternatives. Shipyards in Germany and the Netherlands are retrofitting existing stations to comply with phasedown schedules. Marine fabrication clusters are responding by consolidating procurement specifications around electrode-compatible plasma systems that bypass gas chemistry constraints entirely.
Buying committees at major shipyards are unbundling after-sales service contracts from equipment purchases, forcing torch vendors to compete on consumables and maintenance separately. This pattern disrupts traditional captive distribution channels anchored by welding supply houses. The shift is most visible in Japanese maritime manufacturing, where yards are directly negotiating electrode supply agreements with specialty alloy producers.
Gouging Torch Market Segmentation
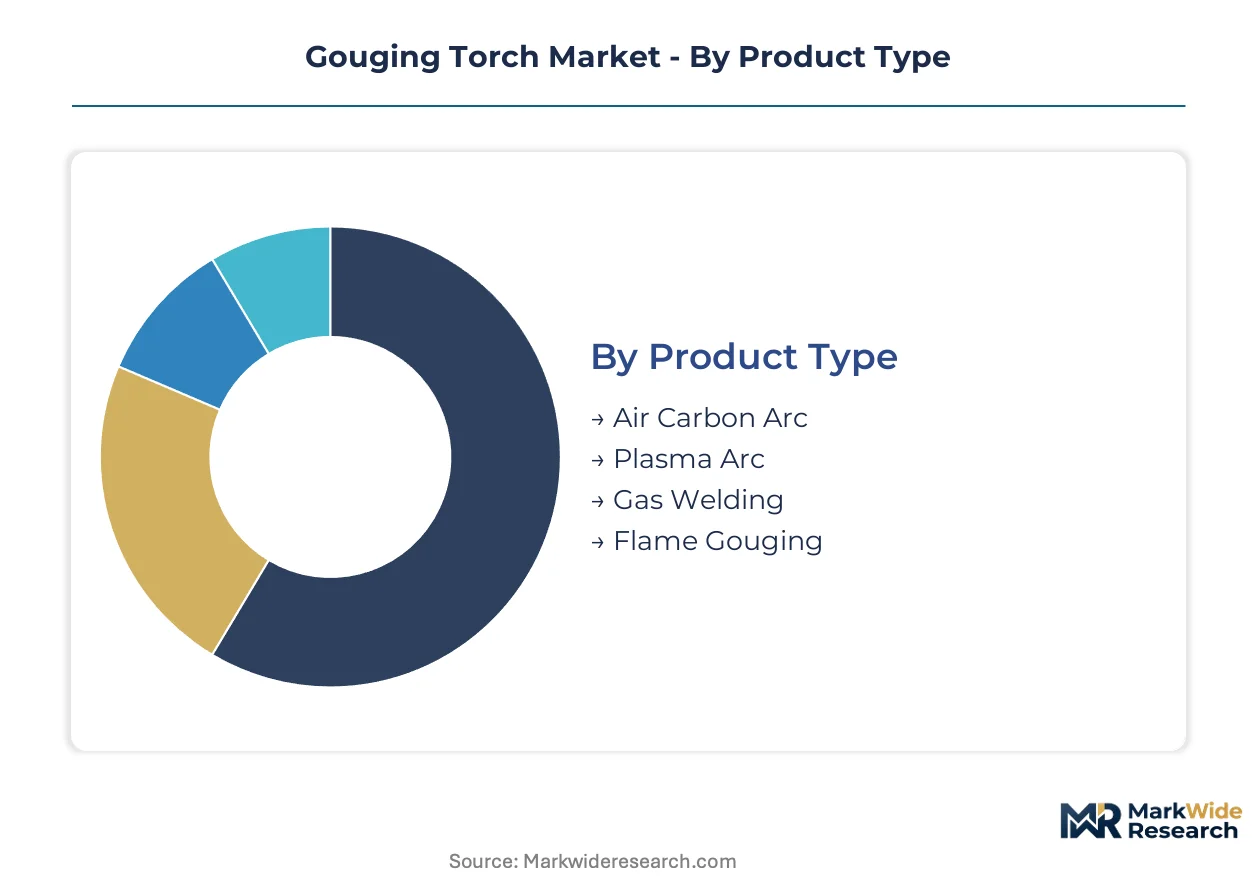
Gouging torch procurement patterns diverge sharply across product configurations and end-use environments. Certification requirements for electrode materials and fume extraction systems create compliance moats that reshape competitive positioning within each segment tier.
Product Type:
OSHA ventilation standards and EPA particulate rules govern air carbon arc systems, while plasma arc configurations face additional FCC electromagnetic compatibility scrutiny for automated CNC integration.
- Air Carbon Arc:Copper-clad carbon electrodes operating at 600–1,000 amperes dominate thick-plate hull work in South Korean and Japanese shipyards. Compressed air integration advances are extending mobility across remote repair sites where infrastructure remains limited.
- Plasma Arc:Precision systems with heat-affected zone control capture aerospace margin pools in titanium and nickel alloy applications. EU F-Gas Regulation compliance is accelerating displacement of gas-based alternatives in German and Dutch marine fabrication clusters.
- Gas Welding:Oxy-fuel configurations face tightening emissions constraints under REACH chemical restrictions.
- Flame Gouging:Thermal cutting methods concentrate in legacy infrastructure maintenance with lower capital barriers.
Air Carbon Arc sits at the top of the volume ranking, with Plasma Arc climbing the fastest.
Application:
Cost tier stratification separates automated shipyard installations from portable contract repair equipment, with capital intensity dictating procurement committee composition and vendor selection criteria.
- Shipbuilding:Automated plasma arc systems with CNC positioning compress weld preparation time in double-hull tanker construction at South Korean yards. Direct electrode supply negotiations with specialty alloy producers are disrupting traditional welding house distribution channels.
- Repair Services:Aging infrastructure maintenance cycles are shortening across industrial economies, accelerating demand for portable carbon arc configurations. OSHA fume extraction mandates add operational overhead that compresses margins for thin-project-economics operators.
- Metal Fabrication:High-volume ferrous alloy processing absorbs majority unit volume with standardized torch specifications.
- Construction:Structural steel preparation drives seasonal procurement patterns tied to infrastructure spending cycles.
Shipbuilding commands the premium pricing tier, while Repair Services expands most quickly as maintenance backlogs accumulate.
End User:
Customer type segmentation aligns with in-house maintenance capability versus outsourced contract service models, determining whether procurement flows through captive welding supply channels or direct vendor relationships.
- Manufacturing Plants:Integrated fabrication facilities deploy high-amperage systems for continuous production environments. Japan's METI industrial efficiency guidelines are accelerating plasma arc replacement of oxy-fuel systems to reduce energy intensity.
- Aerospace Sector:Precision heat-affected zone requirements in titanium work mandate specialized plasma torch variants with integrated fume extraction. Component traceability standards exceed those in general metal fabrication by substantial margins.
- Automotive Industry:High-volume production lines favor standardized consumable specifications across multiple facility locations.
- Workshops:Independent repair operators concentrate in legacy shipbuilding regions with certified technician scarcity constraining geographic expansion.
Manufacturing Plants anchor procurement volume, with Aerospace Sector gaining share fastest on precision premiumization.
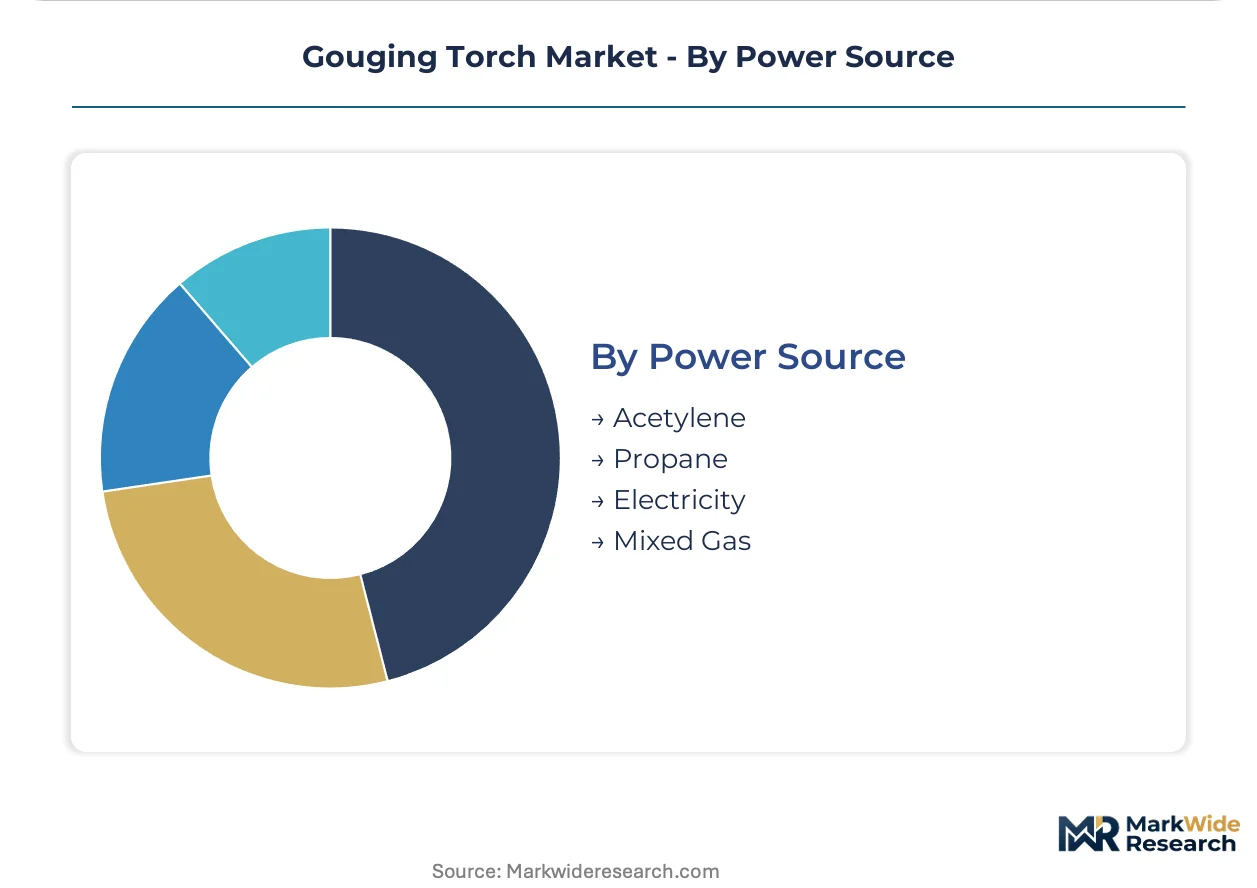
Power Source:
Supply concentration in Asian electrode manufacturers creates input cost volatility that reshapes margin structures across electric versus combustion-based system categories.
- Electricity:All-electric plasma systems bypass EU F-Gas Regulation gas chemistry constraints entirely. Power source efficiency thresholds are diverging between EPA particulate rules and REACH chemical restrictions, complicating cross-border equipment standardization.
- Acetylene:High-temperature flame cutting retains position in remote sites lacking electrical infrastructure. Emissions compliance costs are accelerating substitution toward electric alternatives in regulated jurisdictions.
- Propane:Lower-cost fuel alternative concentrates in cost-sensitive emerging market applications.
- Mixed Gas:Specialized thermal profiles serve niche precision applications with limited scale.
Electricity dominates forward procurement specifications, with Acetylene retreating fastest under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian maritime manufacturing clusters concentrate the heaviest procurement volumes for thick-plate gouging equipment. South Korean and Japanese shipyards drive carbon arc adoption for hull repair and weld preparation workflows. Regulatory divergence between EPA particulate rules and EU F-Gas restrictions is fragmenting equipment standardization across jurisdictions.
United States
OSHA ventilation standards and EPA particulate emissions rules govern American gouging torch operation, compelling fabricators to invest in fume extraction integration. The regulatory framework adds operational overhead for contract repair services. Gulf Coast petrochemical facilities and Great Lakes shipyards absorb the majority of domestic equipment demand.
Germany
The EU F-Gas Regulation is tightening emissions standards for gas-based cutting processes, pushing German shipyards toward electric plasma systems. Hamburg and Bremen maritime clusters are retrofitting existing stations to comply with phasedown schedules. German marine fabrication is consolidating procurement specifications around electrode-compatible plasma configurations.
South Korea
Naval and commercial vessel output remains elevated in South Korean manufacturing hubs, concentrating procurement of high-amperage air carbon arc systems. Ulsan and Geoje shipbuilding complexes deploy automated plasma arc gouging with CNC positioning for double-hull tanker construction. Direct electrode supply negotiations with specialty alloy producers are disrupting traditional welding house distribution channels.
Japan
Japan's METI industrial efficiency guidelines promote plasma arc adoption to reduce energy intensity in metalworking. Nagoya and Kobe maritime facilities are accelerating plasma arc replacement of oxy-fuel systems. Japanese shipyards are unbundling after-sales service contracts from equipment purchases, forcing torch vendors to compete on consumables separately.
India
The country's PLI scheme for domestic manufacturing is creating procurement windows for automated gouging torch configurations in emerging maritime facilities. Mumbai and Visakhapatnam shipyards are modernizing with carbon arc systems for thick-plate hull work. India's central electricity authority standards are shaping power source specifications for electric plasma alternatives.
Gouging Torch Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors respond to East Asian maritime demand concentration. The vendor base organizes around three tiers: integrated welding equipment conglomerates with captive distribution channels, specialized torch manufacturers with alloy expertise, and regional fabricators serving localized repair markets. Two strategic archetypes have emerged: diversified industrial conglomerates leveraging backward integration into consumable electrode production, and precision specialists targeting aerospace heat-affected zone applications. Geographic expansion and portfolio diversification represent the dominant competitive moves, with vendors establishing direct supply relationships with shipyard procurement committees.
Among diversified industrial conglomerates, Lincoln Electric Holdings, Illinois Tool Works Inc., and ESAB Corporation occupy positions defined by welding supply channel control and consumable alloy development. These entities exemplify the integrated archetype where electrode manufacturing and distribution infrastructure reinforce equipment placement. Lincoln Electric Holdings represents North American market presence through welding supply house networks. Illinois Tool Works Inc. anchors R&D intensity in consumable formulations. ESAB Corporation exemplifies European maritime specialization with automated torch configurations. Fronius International GmbH and Arcair sit within the precision technology tier, reflecting Austrian and American origins respectively in advanced power source engineering.
| Leading Market Players |
|---|
| Lincoln Electric Holdings |
| ESAB Corporation |
| Illinois Tool Works Inc. |
| Fronius International GmbH |
| Arcair |
| Parweld |
| Castolin Eutectic |
| Wilhelmsen |
| Weldmark |
| Others |
Value Network & Pricing Analysis
Direct electrode supply negotiations by South Korean shipyards are forcing torch vendors to unbundle after-sales service contracts and compete separately on consumables, compressing margin pools for traditional welding house distribution channels and accelerating price transparency across procurement committees.
Pricing Analysis
Copper-clad carbon electrode cost pass-through dominates air carbon arc system pricing, with electrode-compatible plasma configurations commanding premium positioning based on EU F-Gas Regulation compliance certification. Three-tier pricing structure across premium automated CNC systems, standard shipyard configurations, and economy portable units separates procurement tiers by heat-affected zone control capability and fume extraction integration level. Pricing pressure stems from compressed after-sales margins as Japanese yards negotiate direct alloy producer relationships. Small-scale metal fabricators exhibit highest price sensitivity due to thin project economics, while aerospace precision applications show lowest sensitivity on heat-affected zone performance.
Supply Chain Analysis
Freight cost volatility from Asian electrode manufacturing centers to European and North American fabrication hubs is reshaping inventory positioning strategies among distributors. Electrode production concentrates in China, Japan, and South Korea, with torch assembly drawing from copper cladding facilities and carbon rod extrusion plants. Raw material dependencies center on copper cathodes, petroleum needle coke, and compressed air system components. Single-source vulnerability in specialty alloy formulations for aerospace-grade electrodes creates supply chain risk. Distribution runs through captive welding supply channels anchored by Lincoln Electric and ESAB networks, though direct shipyard procurement is disrupting traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phasedown schedule compounds equipment replacement demand across European marine fabrication, creating regulatory-driven procurement windows that favor electric plasma system vendors over gas-based alternatives.
For Market Incumbents: Deepen backward integration into consumable electrode production to defend margin position against direct alloy producer encroachment. Anchor capacity expansion in South Korean and Japanese maritime clusters where naval and commercial vessel output sustains thick-plate equipment demand. Invest in automated plasma arc configurations with CNC positioning to capture double-hull tanker construction workflows displacing manual carbon arc methods. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and the Netherlands opens a window for electrode-compatible plasma system specialists to penetrate retrofitting shipyard stations. Target India's PLI scheme procurement windows for automated configurations in emerging Mumbai and Visakhapatnam maritime facilities. Pursue direct supply relationships with specialty alloy producers as a go-to-market angle bypassing incumbent welding house channels. For Investors and Strategic Acquirers: Asymmetric upside sits with precision plasma arc specialists holding aerospace heat-affected zone control capabilities and METI efficiency guideline compliance positioning. Five-to-ten year viability hinges on regulatory divergence between EPA particulate rules and REACH chemical restrictions sustaining equipment platform fragmentation. Monitor Japan's unbundling of after-sales service contracts as an inflection signal for distribution model disruption spreading to South Korean yards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Production | Captive supply of copper-clad carbon electrodes insulates margin pressure from Asian supplier concentration. |
| Automated Plasma Arc System Development | CNC positioning integration captures South Korean double-hull tanker construction procurement specifications. |
| Direct Shipyard Supply Agreements | Bypassing welding house channels responds to Japanese procurement committee unbundling trends. |
| EU F-Gas Regulation Compliance Certification | Electrode-compatible plasma configurations access German and Dutch marine fabrication retrofit demand. |
| India PLI Scheme Market Entry | Automated torch configurations align with Mumbai and Visakhapatnam shipyard modernization programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with shipyard procurement managers, welding supply channel heads, electrode manufacturing technical directors, and aftermarket service specialists with secondary validation. Primary sources included equipment utilization surveys across Ulsan, Geoje, Nagoya, and Kobe maritime facilities. Secondary data drew from customs trade records for electrode imports, SEC filings of integrated welding equipment conglomerates, and METI industrial efficiency guideline documentation. Bottom-up unit shipment estimates and top-down market value reconstructions were triangulated against each other.
Comparable-period anchoring tied projection assumptions to historical procurement patterns observed across East Asian maritime manufacturing clusters over the analysis window. Segmentation modeling spanned product type tiers, application environments, end-user categories, and power source specifications. CAGRs were derived from regression analysis against naval vessel output forecasts and commercial shipbuilding order backlogs. Industry-specific inputs included shipyard automation adoption curves and regulatory compliance cost trajectories under EPA, REACH, and F-Gas frameworks.
Revisions become necessary when electrode material compliance requirements diverge further between jurisdictions, copper supply disruptions concentrate in Asian manufacturing centers, or shipyard automation adoption accelerates beyond modeled penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Punch and Die Storage Cabinet Market
Tools
Fixed Cutter Bits Market
Tools
Machine Tools Market
Tools
Water Pump Pliers Market
Tools
Fatigue Testing Machine Market
Tools
Grinding Machines Market
Tools
Flooring Tools Market
Tools
Hydraulic Torque Wrench Market
Tools
Europe Woodworking Power Tools Market
Tools
Dumpy Level Market
Tools
Garden Digging Tools Market
Tools
Extensometer Market
Tools
Metal Cutting Machine Market
Tools
Portable Pressure Washer Market
Tools
Floor Saw Market
Tools
Jade Engraving Machines Market