
 Vinyl Bending Machine Market | 2026-2036
Vinyl Bending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Bending Machine Market Insights
REACH compliance is recalibrating the cost-of-entry calculus for vinyl bending equipment sold into European fabrication shops. Aslan Machine leverages its thermal engineering heritage to sustain competitive positioning in infrared heating architectures. ATechMachinery anchors its portfolio around pneumatic automation systems for high-throughput sign shops. CA Design competes through specialized manual and semi-automatic configurations serving design studios with batch-size flexibility.
A vinyl bending machine is industrial thermoforming equipment that applies controlled heat, typically through infrared or hot air systems reaching temperatures between 150°C and 300°C, to soften thermoplastic sheets before mechanical forming around jigs or molds for permanent angular profiles. Its primary commercial purpose centers on producing dimensional signage, display fixtures, and architectural mockups from acrylic, PVC, and PETG substrates. Fully automatic systems capture the dominant margin pool due to labor cost arbitrage in volume fabrication environments, while infrared heating technology leads installed capacity because of energy precision and reduced thermal degradation versus legacy hot air methods. Manual configurations retain durable demand among design studios and prototyping workshops where setup changeover frequency outweighs cycle time optimization.
The EPA regulates volatile organic compound emissions from heated plastic processing under Clean Air Act provisions, pushing fabricators toward enclosed heating chambers with extraction systems. OSHA workplace exposure limits for heated thermoplastic fumes further shape equipment ventilation specifications and operator station design. BIS certification requirements in India mandate electrical safety and thermal insulation standards for imported and domestically manufactured bending equipment. Stakeholders must monitor how evolving refrigerant regulations and energy efficiency standards across multiple jurisdictions reshape heating subsystem sourcing and total cost of ownership calculations for fleet replacement decisions.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-dependent thermal architectures and forcing equipment redesigns across European fabrication networks. Fabricators now face accelerated obsolescence cycles for heating subsystems as phase-down protocols tighten.
Growth Catalysts
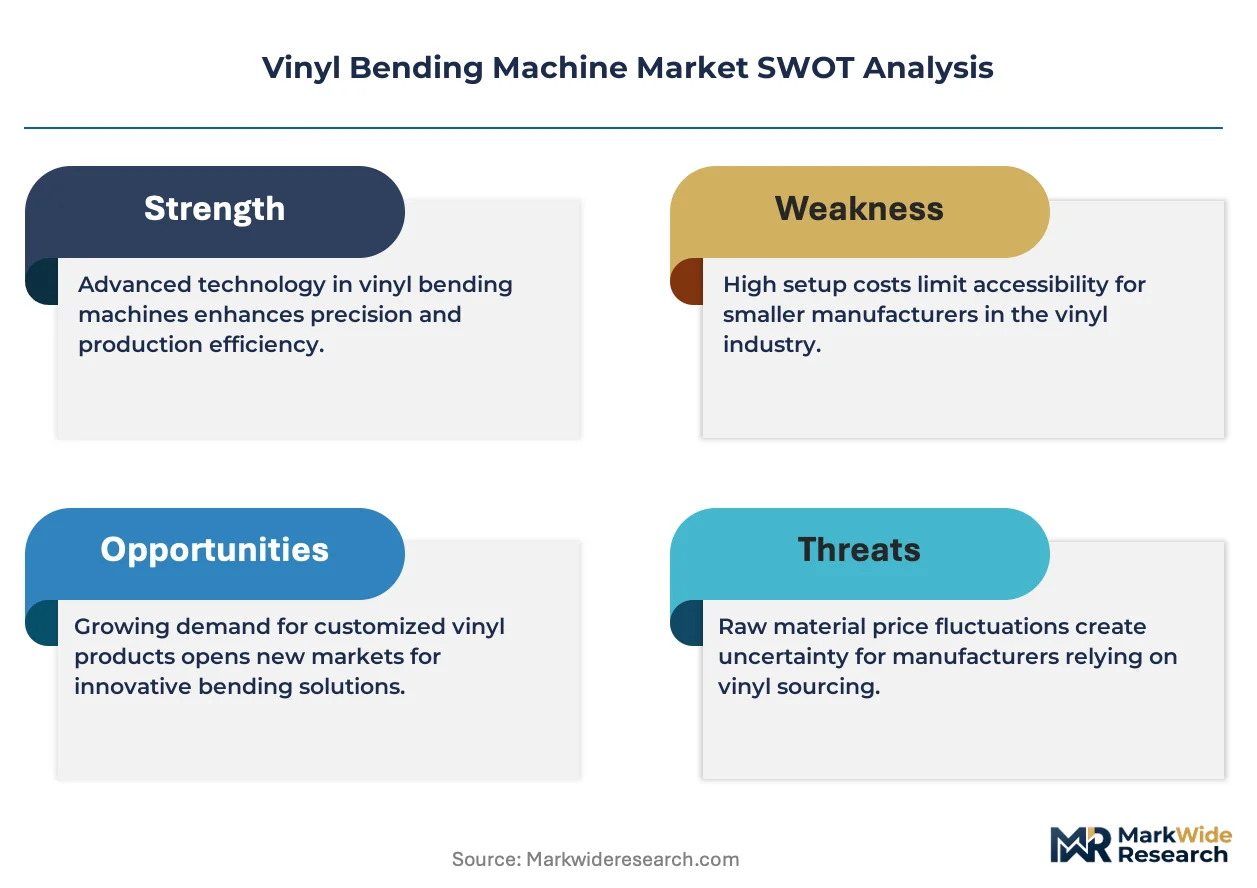
- Commercial signage networks:Retail chains and hospitality brands expand dimensional branding programs, requiring channel letter production at volume. Sign shops upgrade from manual benches to semi-automatic systems to meet contract specifications.
- REACH compliance:Chemical safety protocols in European fabrication shops drive replacement of legacy equipment with enclosed-chamber systems featuring fume extraction. This regulatory pressure sustains replacement demand even in saturated markets.
- Infrared heating precision:Energy efficiency mandates favor radiant thermal systems over convective hot-air methods. Fabricators report reduced substrate degradation and faster cycle times with quartz-halogen architectures.
Market Restraints
- Refrigerant input volatility:Hydrofluorocarbon supply constraints under Montreal Protocol amendments destabilize thermal system costs. Equipment manufacturers face margin compression as R-134a and R-410A prices fluctuate.
- German supply concentration:Precision engineering capabilities for pneumatic automation cluster in Baden-Württemberg and Bavaria. Disruption risks from this geographic concentration constrain equipment availability during demand spikes.
- Manual system substitution:Low-volume design studios and prototyping workshops continue favoring hand-operated benches for batch flexibility. This limits addressable market expansion for automatic system vendors.
Strategic Opportunities
- Indian fabrication growth:BIS certification requirements create compliance barriers for imported equipment, favoring domestic assembly partnerships. Local production avoids import duty structures and reduces lead times for sign shop customers.
- Architectural mockup applications:Design-build firms require thermoformed acrylic for scale models and facade testing. This adjacent application expands beyond traditional signage into construction visualization workflows.
- Dual carbon convergence:China's GB standards for energy efficiency align with EU F-Gas timelines, creating harmonized product platforms. Manufacturers can engineer single thermal architectures certifiable across both jurisdictions.
Industry Challenges
- Thermal engineering talent scarcity:Infrared system design requires specialized expertise in radiant heat transfer and control electronics. Fabrication shops struggle to recruit technicians capable of diagnosing quartz-halogen circuit failures.
- Legacy pneumatic integration:Semi-automatic upgrades must interface with existing shop air infrastructure. Compressor capacity mismatches and hose routing complexity delay installation timelines and inflate commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Bending Machine Market |
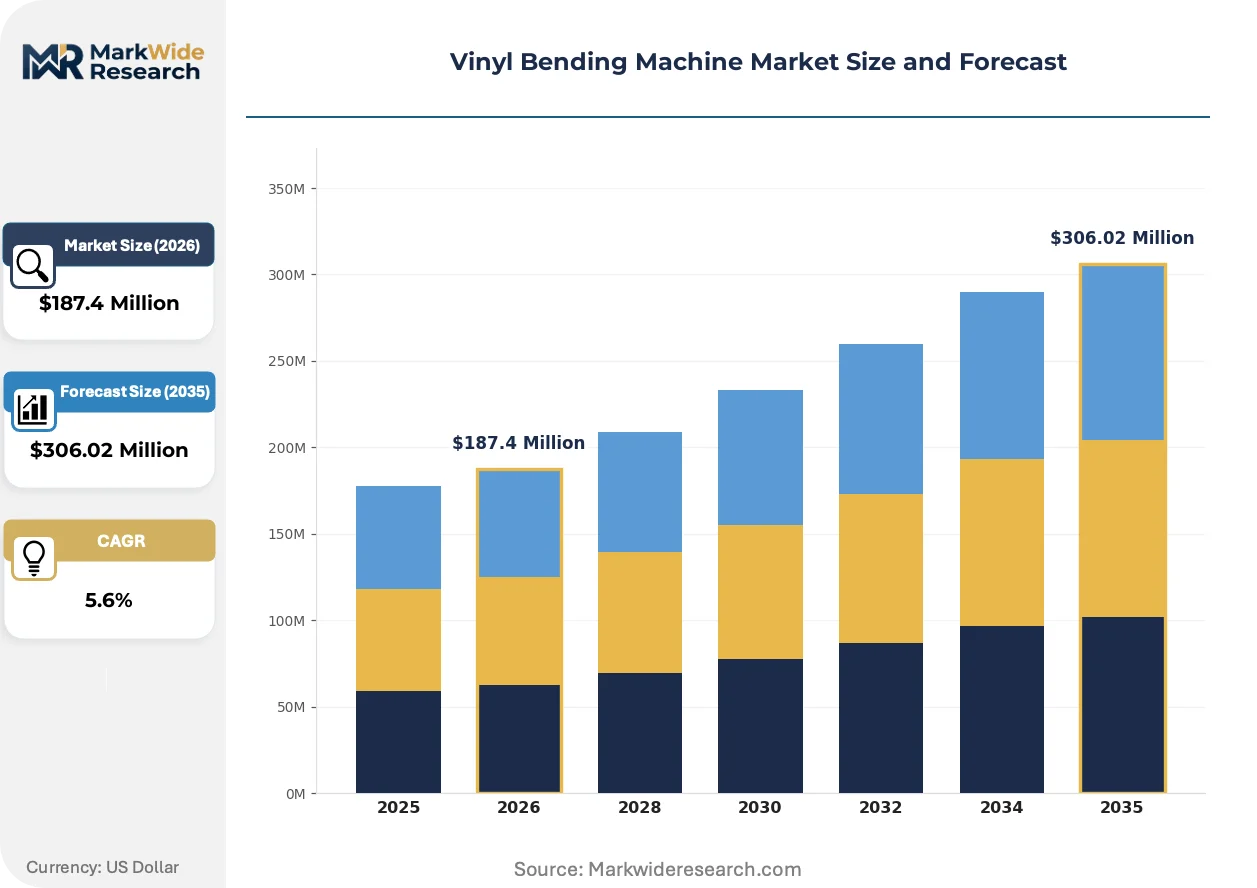
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $306.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, Pneumatic Technology: Hot Air, Infrared Heating, Electrical Heating, Ultrasonic Application: Sign Making, Automotive Interiors, Architectural Models, Packaging End User: Fabricators, Design Studios, Construction Firms, Advertising Agencies |
| Companies Covered | Aslan Machine, ATechMachinery, CA Design, Syn Tec, INT Machinery, FUX, Shangdong Glasino Glass Technology, Beiguang Jingyi, Shandong Glasino Glass Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Bending Machine Market Trends and Innovations
Equipment architectures are bifurcating between energy-optimized infrared platforms for volume production and modular manual systems for prototyping flexibility. This technological divergence reflects diverging buyer requirements across commercial and creative end-uses.
Quartz-halogen infrared arrays are absorbing market share from convective hot-air systems in high-throughput sign shops. Large-format fabricators operating 24-hour production schedules prioritize radiant heating for its rapid thermal response and precise zone control. The technology is absorbing margin pressure from energy costs by reducing cycle times and substrate waste rates.
REACH chemical safety protocols are mandating enclosed heating chambers with integrated fume extraction across European fabrication networks. Equipment vendors must redesign operator stations to meet ECHA exposure limit guidelines for heated thermoplastic emissions. German precision engineering corridors lead compliance adaptation, with fabricators in Stuttgart and Munich demanding certified extraction systems as standard configuration.
Sign shop procurement patterns are fragmenting between capital purchase and equipment-as-service arrangements. Mid-size fabricators in North American urban markets increasingly lease automatic systems with bundled maintenance to preserve working capital. This financing innovation is compressing sales cycles and shifting vendor relationships from transactional to ongoing service partnerships.
Vinyl Bending Machine Market Segmentation
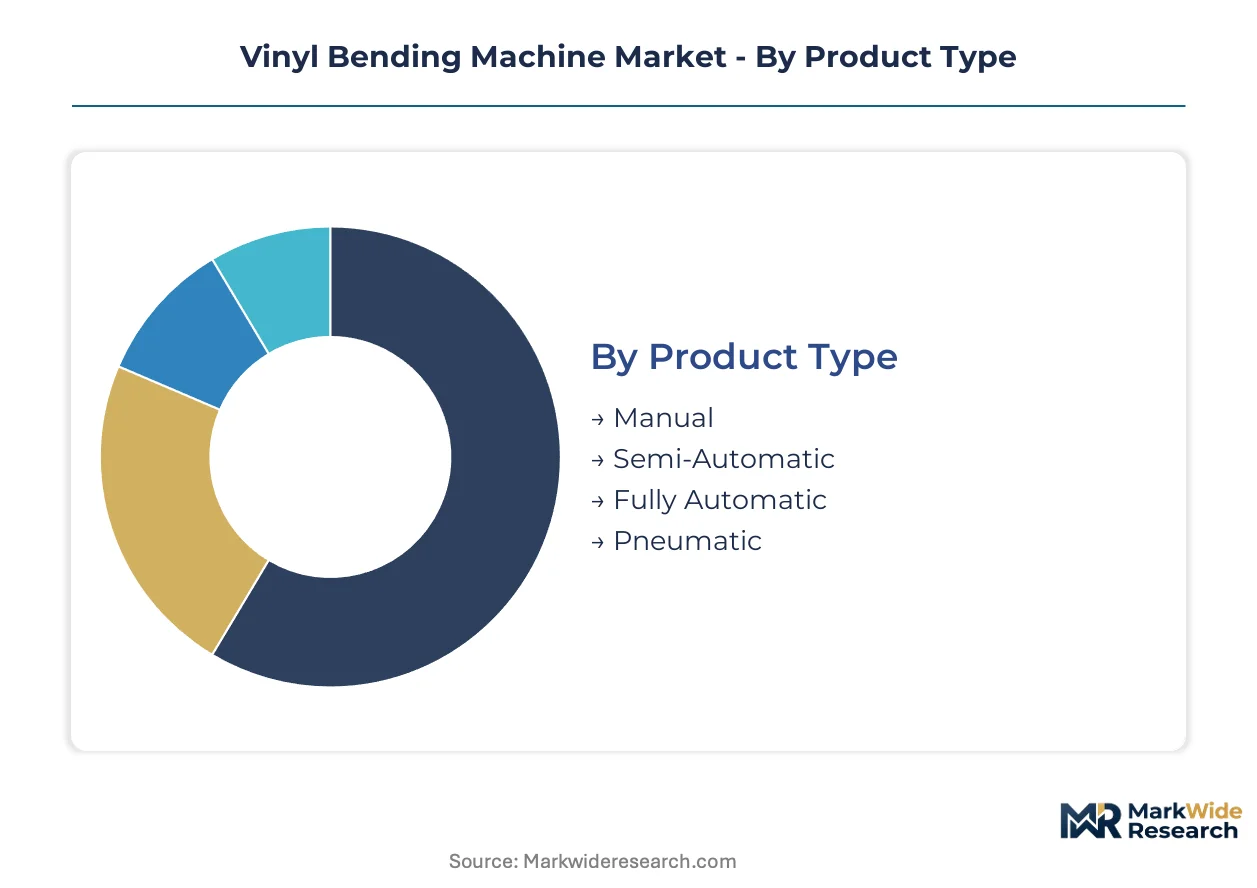
Vinyl bending machine segmentation reveals how equipment specifications align with distinct production economics across fabrication networks. Each dimension—automation level, thermal technology, application focus, and buyer type—creates divergent margin structures and replacement cycles.
Product Type:
Supply concentration for pneumatic automation systems clusters in German precision engineering corridors, while manual bench manufacturing disperses across lower-cost assembly regions.
- Fully Automatic:These systems integrate programmable logic controllers with multi-zone thermal management for continuous production environments. Large-format sign shops in Germany's Stuttgart corridor deploy these configurations to meet retail chain contract volumes while minimizing labor arbitration costs.
- Semi-Automatic:Pneumatic actuation combines with operator-controlled heating cycles for mid-volume batch production. Fabricators across Baden-Württemberg upgrade to these systems when transitioning from manual benches to meet REACH-compliant enclosed chamber requirements.
- Manual:Hand-operated benches with simple jig arrangements serve prototyping workshops and design studios requiring frequent setup changes.
- Pneumatic:Compressed air-driven forming mechanisms dominate high-throughput environments with existing shop air infrastructure.
Fully automatic systems absorb the bulk of installed capacity in volume fabrication environments; semi-automatic configurations are expanding most quickly among compliance-driven European fabricators.
Technology:
Cost tier differentiation separates premium infrared architectures from economy hot-air systems, with energy efficiency mandates accelerating technology substitution.
- Infrared Heating:Quartz-halogen arrays deliver radiant thermal energy with precise zone control and rapid response times. German fabricators operating 24-hour schedules favor this technology for reduced substrate degradation and faster cycle times under EU energy efficiency directives.
- Hot Air:Convective heating through forced air circulation represents legacy thermal architecture with higher energy intensity and less precise temperature distribution.
- Electrical Heating:Resistance-element systems provide intermediate cost positioning for fabricators balancing capital constraints against production consistency requirements.
- Ultrasonic:High-frequency mechanical vibration generates localized thermal energy for specialized thin-gauge applications in packaging and delicate architectural mockups.
Infrared heating absorbs the bulk of new capacity additions in European and North American markets; ultrasonic systems are gaining share fastest in packaging applications requiring minimal thermal distortion.
Application:
Volume concentration in sign making creates procurement scale economies that adjacent applications struggle to replicate.
- Sign Making:Channel letter production and dimensional branding elements drive equipment standardization. Retail chains and hospitality brands across commercial signage networks require consistent angular profiles in acrylic and PVC substrates.
- Automotive Interiors:Thermoformed trim panels and prototype dashboard elements demand precise radius control and surface finish quality.
- Architectural Models:Scale facades and construction visualization mockups utilize thin-gauge acrylic for design-build presentation workflows.
- Packaging:Custom blister formations and display inserts require rapid changeover capabilities for short production runs.
Sign making commands the dominant share of equipment utilization hours; architectural models are climbing the fastest as design-build firms expand visualization service offerings.
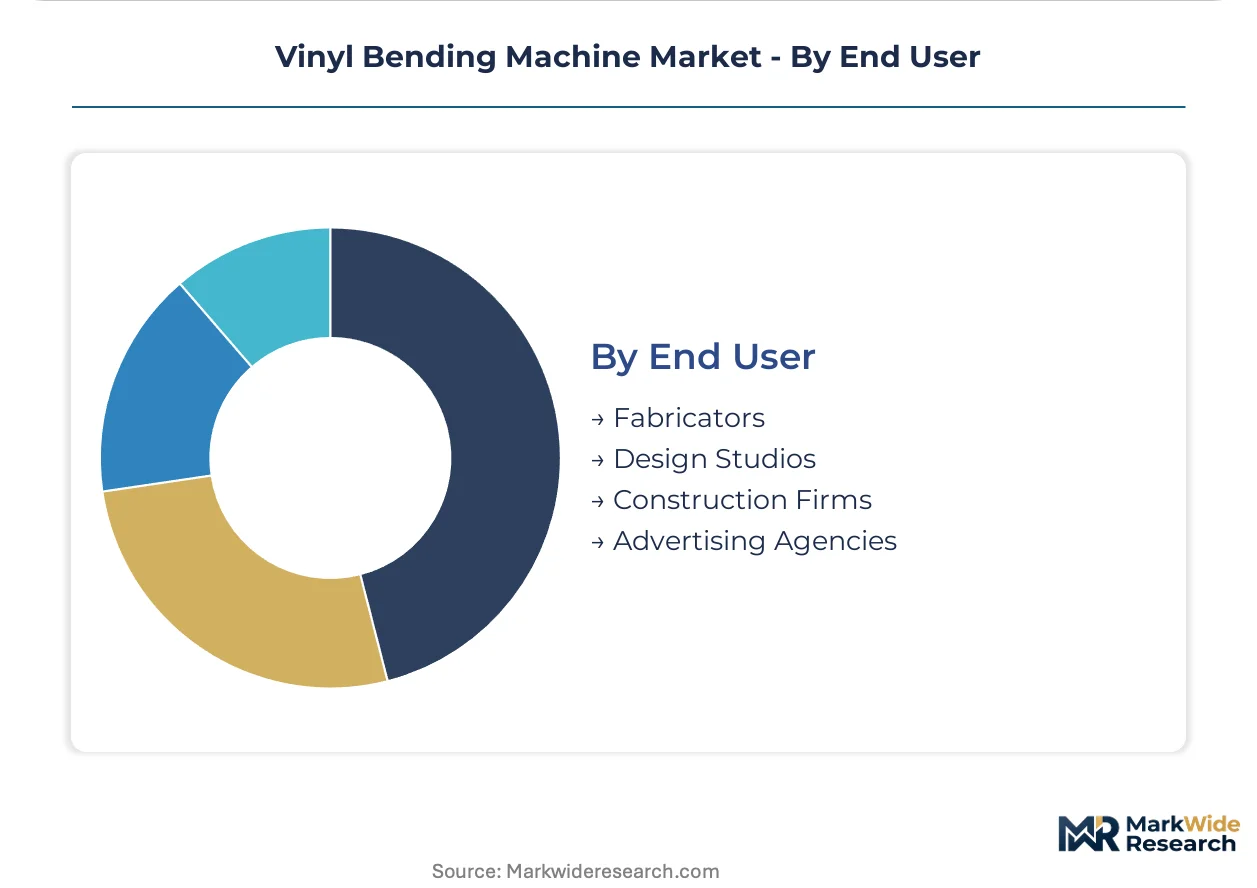
End User:
Customer type segmentation determines financing preferences and service bundling requirements, with capital availability shaping automation adoption trajectories.
- Fabricators:Dedicated production facilities with established thermal processing expertise prioritize throughput optimization and regulatory compliance integration.
- Design Studios:Creative workshops value batch flexibility and rapid setup changeover over cycle time minimization, sustaining manual system demand.
- Construction Firms:Design-build contractors entering architectural mockup production represent emerging equipment demand with specialized training requirements.
- Advertising Agencies:In-house production capabilities for client presentation materials drive small-format equipment procurement with service-inclusive financing.
Fabricators account for the predominant share of equipment installed base; advertising agencies are expanding most quickly as vertical integration into production capabilities accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial signage networks in Germany absorb the dominant share of precision-engineered vinyl bending equipment, with fabricators across Baden-Württemberg and Bavaria driving procurement volumes for channel letter production.
Germany
Retail chains and hospitality brands expand dimensional branding programs across Stuttgart and Munich corridors. The EU F-Gas Regulation accelerates replacement cycles for refrigerant-dependent thermal subsystems. Fabricators in Baden-Württemberg upgrade from manual benches to semi-automatic systems with REACH-compliant enclosed chambers.
United States
Mid-size sign shops in Chicago and Dallas metropolitan areas lease automatic systems through equipment-as-service arrangements. EPA Clean Air Act provisions push fabricators toward enclosed heating chambers with volatile organic compound extraction. OSHA workplace exposure limits reshape ventilation specifications in Los Angeles fabrication clusters.
China
GB standards for energy efficiency align production platforms with EU thermal architecture requirements. MIIT industrial upgrading programs subsidize automation adoption in Yangtze River Delta fabrication zones. Zhejiang and Jiangsu province manufacturers expand quartz-halogen infrared capacity for export certification.
India
BIS certification requirements create compliance barriers for imported bending equipment, favoring domestic assembly partnerships. Sign shop demand concentrates in Maharashtra and Gujarat industrial corridors. Fabricators in Pune and Ahmedabad prioritize local production to avoid import duty structures and reduce lead times.
United Kingdom
Design studios in London and Manchester sustain manual system demand for prototyping flexibility. ECHA exposure limit guidelines mandate fume extraction integration in new equipment procurements. Birmingham fabrication networks transition to semi-automatic configurations for mid-volume batch production.
Vinyl Bending Machine Market Competitive Landscape
German producers anchor the premium automation tier; Chinese fabricators hold volume-positioned manufacturing. The vendor base distributes across three capability strata: precision engineering specialists, pneumatic automation integrators, and manual bench assemblers. Strategic moves center on thermal subsystem redesign for F-Gas compliance and domestic assembly partnerships for Indian market access.
Within the precision engineering tier, Aslan Machine and ATechMachinery exemplify divergent thermal architecture approaches. CA Design occupies a position among configuration-flexible specialists serving design studio workflows. Chinese limited liability companies including Shandong Glasino Glass Technology and Beiguang Jingyi represent scale-oriented manufacturing archetypes. Syn Tec and INT Machinery sit within the European automation integrator cluster. FUX and Shangdong Glasino Glass Technology anchor geographic diversification strategies across multiple production corridors.
| Leading Market Players |
|---|
| Aslan Machine |
| ATechMachinery |
| CA Design |
| Syn Tec |
| INT Machinery |
| FUX |
| Shangdong Glasino Glass Technology |
| Beiguang Jingyi |
| Shandong Glasino Glass Technology |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates qualified supply for infrared thermal subsystems and commands premium-tier pricing access for certified European manufacturers. Fabricators seeking REACH-compliant enclosed chambers with integrated fume extraction face extended lead times and elevated procurement costs, compressing margin pools for uncertified competitors.
Pricing Analysis
Short lead-time premiums distinguish German-manufactured pneumatic systems from spot-inventory Asian alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Price differentiation hinges on CE marking tier and quartz-halogen thermal precision. Cost compression in economy-tier hot-air systems is intensifying because of refrigerant input volatility. Design studios exhibit highest price sensitivity; large-format sign shops prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Baden-Württemberg precision engineering corridors for pneumatic automation components. Manufacturing capacity clusters in Germany, China, and India for finished equipment assembly. Component sourcing draws from Taiwan for control electronics, Japan for quartz-halogen elements, and Italy for compressor systems. Tariff exposure on steel framing and aluminum jigs constrains margin flexibility. Distribution runs through direct OEM sales for automatic systems and regional distributor networks for manual benches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering talent scarcity props pricing for qualified equipment, sustaining incumbent margin structures despite competitive pressure from Asian assembly.
For Market Incumbents: Extend infrared platform certification across EU and Chinese GB standards to capture harmonized product demand. Deepen captive supply of quartz-halogen arrays through backward integration into Taiwanese component partnerships. Consolidate service bundling capabilities to offset margin pressure from refrigerant-dependent subsystem obsolescence. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian fabrication corridors offers white-space entry through domestic assembly partnerships. Target Maharashtra and Gujarat sign shop clusters with BIS-certified manual-to-semi-automatic upgrade paths. Pursue equipment-as-service financing to bypass capital constraints among mid-volume fabricators. For Investors and Strategic Acquirers: MIIT subsidy announcements for Yangtze River Delta automation adoption are the leading indicator that Chinese infrared capacity will consolidate within the decade. Position for platform acquisition of European automation integrators with dual EU-China certification capabilities. Monitor German fabricator replacement cycle acceleration as F-Gas phase-down tightens.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | REACH and GB standard alignment unlocks cross-jurisdictional equipment sales for German manufacturers. |
| Domestic Assembly Partnership | BIS-compliant Indian production avoids import duties and compresses lead times for Pune fabricators. |
| Infrared Platform Migration | Quartz-halogen adoption reduces energy intensity and substrate waste for Stuttgart corridor sign shops. |
| Equipment-as-Service Launch | Leasing models with bundled maintenance preserve working capital for Chicago metropolitan fabricators. |
| Thermal Engineering Talent Acquisition | Control electronics expertise secures diagnostic capabilities for 24-hour production environments. |
Research Methodology
Document review covered customs databases, EU regulatory filings, and MIIT industrial policy announcements, complemented by interviews with sign shop owners, pneumatic systems engineers, and thermal subsystem procurement leads. Secondary validation drew from ECHA exposure limit guidelines, BIS certification registries, and EPA Clean Air Act enforcement records. Bottom-up equipment shipment data triangulated against top-down fabrication capacity estimates across German, Chinese, and Indian production corridors.
Cross-referencing historical replacement cycle patterns with panel input from OEM sales directors and distributor channel managers shaped the projection framework. Segmentation modeling spanned automation level, thermal technology architecture, application focus, and end-user type across the analysis window. CAGR derivation incorporated energy efficiency mandate timelines, refrigerant phase-down schedules, and sign shop capital expenditure sentiment indices.
Inputs from German precision engineering associations and Chinese MIIT regional offices were available through the study window; gaps in Indian domestic production cost structures introduce uncertainty bands around local assembly partnership viability. Forecasts reflect assumptions about F-Gas Regulation enforcement consistency and BIS certification processing timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Adjustable Gripping Hand Tools Market
Tools
Rocket Wrench Market
Tools
DIY Ball Mill Market
Tools
Manual Cutting Equipment Market
Tools
Asia Pacific Power Tools Market
Tools
Diamond Hole Saw Market
Tools
Europe Machine Tools Market
Tools
Power Tools Market
Tools
Edge Banding Machine Market
Tools
Measuring Wheels Market
Tools
Tool Boxes Market
Tools
Riveting Tools Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Gouging Torch Market
Tools
Fastening Power Tools Market
Tools
Chainsaw Market