
 Automotive Hydraulic Lash Adjuster Market | 2026-2036
Automotive Hydraulic Lash Adjuster Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hydraulic Lash Adjuster Market Outlook
Steel alloy substitution is hardening cost structures across the Automotive Hydraulic Lash Adjuster supply chain as manufacturers shift from conventional carbon grades to high-chromium formulations for wear resistance. Cummins Inc. leverages captive metallurgy expertise to secure upstream material consistency across its heavy-duty engine programs. Schaeffler Technologies AG & Co. KG anchors European supply through integrated forging-to-assembly operations in its German production network. Tenneco Inc. competes on scale, sustaining high-volume contracts with Detroit-based vehicle assemblers through automated lash adjuster lines.
An automotive hydraulic lash adjuster is a self-contained, spring-biased hydraulic cylinder that maintains zero valve clearance by compensating for thermal expansion and component wear in internal combustion engine valve trains, typically operating at oil pressures between 15 and 60 psi. Its primary commercial purpose is to eliminate valve train noise, reduce mechanical losses, and extend service intervals in passenger and commercial vehicle engines. Hydraulic adjusters dominate OEM fitment for light-duty gasoline engines where noise-vibration-harshness targets are most stringent, while electro-hydraulic variants are gaining share in hybrid powertrains requiring precise cam phasing integration. Aftermarket Providers represent a mature, price-competitive channel with lower growth velocity compared to direct OEM and Tier-1 Supplier contracts, where margin pools concentrate in long-term volume agreements.
EPA tailpipe standards and Euro 7 proposals from the European Commission are tightening permissible particulate and nitrogen oxide emissions, forcing engine builders to specify tighter valve-train tolerances that only precision hydraulic adjusters can sustain. China's MIIT enforces GB fuel consumption limits that incentivize friction reduction technologies, including low-leakage lash adjuster designs. NHTSA corporate average fuel economy rules in the United States similarly reward engine efficiency gains achievable through optimized valve timing systems. Stakeholders must monitor how powertrain electrification timelines in major automotive markets reshape the addressable volume for internal combustion valve-train components.
Market Dynamics
Powertrain electrification timelines are compressing the addressable window for internal combustion valve-train components, forcing lash adjuster suppliers to extract maximum value from remaining gasoline engine programs while hedging into hybrid-compatible electro-hydraulic architectures.
Growth Catalysts
- Euro 7 Proposals:The European Commission's tightening nitrogen oxide and particulate limits mandate tighter valve-train tolerances that precision hydraulic adjusters uniquely sustain, expanding specification rates among German and Italian engine builders.
- China NEV Credit System:MIIT enforcement of GB fuel consumption limits rewards friction reduction technologies, accelerating adoption of low-leakage lash adjuster designs in domestic passenger vehicle platforms.
- High-Chromium Steel Alloys:Material upgrades in adjuster bodies extend component lifecycles under elevated thermal loads, creating replacement pull in commercial vehicle segments operating severe-duty cycles.
Market Restraints
- Input Cost Volatility:Specialty chromium and nickel grades face price pressure from energy-intensive smelting requirements, squeezing margin structures for forged adjuster manufacturers without captive metallurgy.
- Supply Concentration Risk:Precision machining capacity clusters disproportionately in Japan's Aichi and Shizuoka prefectures, exposing procurement continuity to seismic and logistics disruptions.
- Powertrain Substitution:Battery-electric platforms eliminate valve trains entirely, eroding long-term volume visibility for hydraulic adjuster suppliers dependent on ICE program renewals.
Strategic Opportunities
- Hybrid Powertrain Integration:Electro-hydraulic lash adjusters enabling precise cam phasing synchronization present unpenetrated white space as Toyota, Honda, and BYD expand parallel hybrid architectures.
- Aftermarket Service Unbundling:Independent repair networks in North America are consolidating procurement through specialized distributors, creating channel restructuring opportunities beyond legacy OEM-Tier-1 direct contracts.
- US NHTSA CAFE Rules:Corporate average fuel economy incentives reward engine efficiency gains from optimized valve timing systems, sustaining specification pull in light-truck and SUV segments.
Industry Challenges
- Precision Grinding Talent Scarcity:Master machinists capable of maintaining sub-micron tolerances in high-volume production are retiring faster than apprenticeship pipelines replenish, constraining capacity expansion.
- Electro-Hydraulic Integration Complexity:Merging traditional hydraulic compensation with electronic cam phasing control demands software-hardware co-development capabilities foreign to legacy mechanical component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hydraulic Lash Adjuster Market |
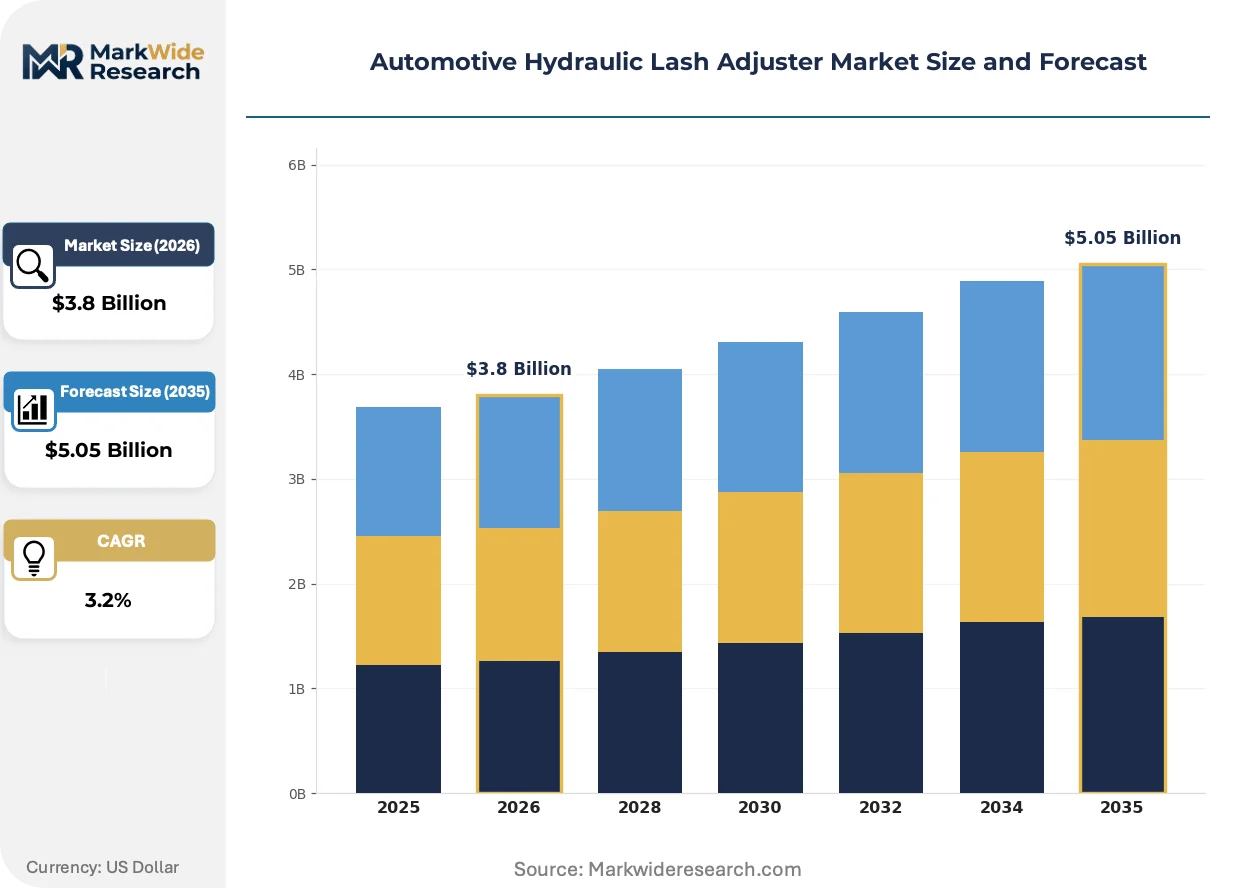
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electro-Hydraulic, Pneumatic, Hydraulic End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Component: Engine Block, Cylinder Head, Camshaft, Crankshaft Installation: Onshore, Offsite, Mobile, Stationary |
| Companies Covered | Cummins Inc., Tenneco Inc., Schaeffler Technologies AG & Co. KG, Johnson Lifters LLC, Elgin Industries, Eaton Corporation plc, Mahle GmbH, GT Technologies Inc., Nittan Valve Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hydraulic Lash Adjuster Market Strategic Shifts
Valve-train component architecture is bifurcating between evolutionary refinements for conventional engines and convergent designs serving hybrid powertrains, with material science and control electronics as the primary innovation vectors.
Electro-hydraulic lash adjusters are integrating solenoid-actuated oil control valves to enable real-time clearance modulation synchronized with variable cam timing systems. Hybrid powertrain engineers at Toyota and BYD specify these units for Atkinson-cycle engines requiring precise valve event phasing. The technology is integrating camshaft and adjuster control into unified mechatronic modules that compress supplier tiering and shift value capture toward electronics-integrated subsystem providers.
REACH authorization processes for chromium trioxide in hard-chrome plating are tightening material compliance timelines for European-sourced adjuster bodies. ECHA sunset date pressures are forcing suppliers to qualify trivalent chromium alternatives or ceramic coatings before 2025 authorization expiries. German powertrain suppliers bear the heaviest requalification burden, with BMW and Volkswagen engine programs demanding concurrent engineering validation of substitute surface treatments.
Long-term service agreements are displacing transactional component procurement in commercial vehicle segments. Fleet operators at Schneider National and J.B. Hunt are unbundling valve-train maintenance from powertrain warranties, creating pull for predictive replacement programs based on telematics-derived duty cycle data. North American heavy-duty distributors are responding with inventory positioning tied to route-specific wear models rather than mileage-based intervals.
Automotive Hydraulic Lash Adjuster Market Segmentation
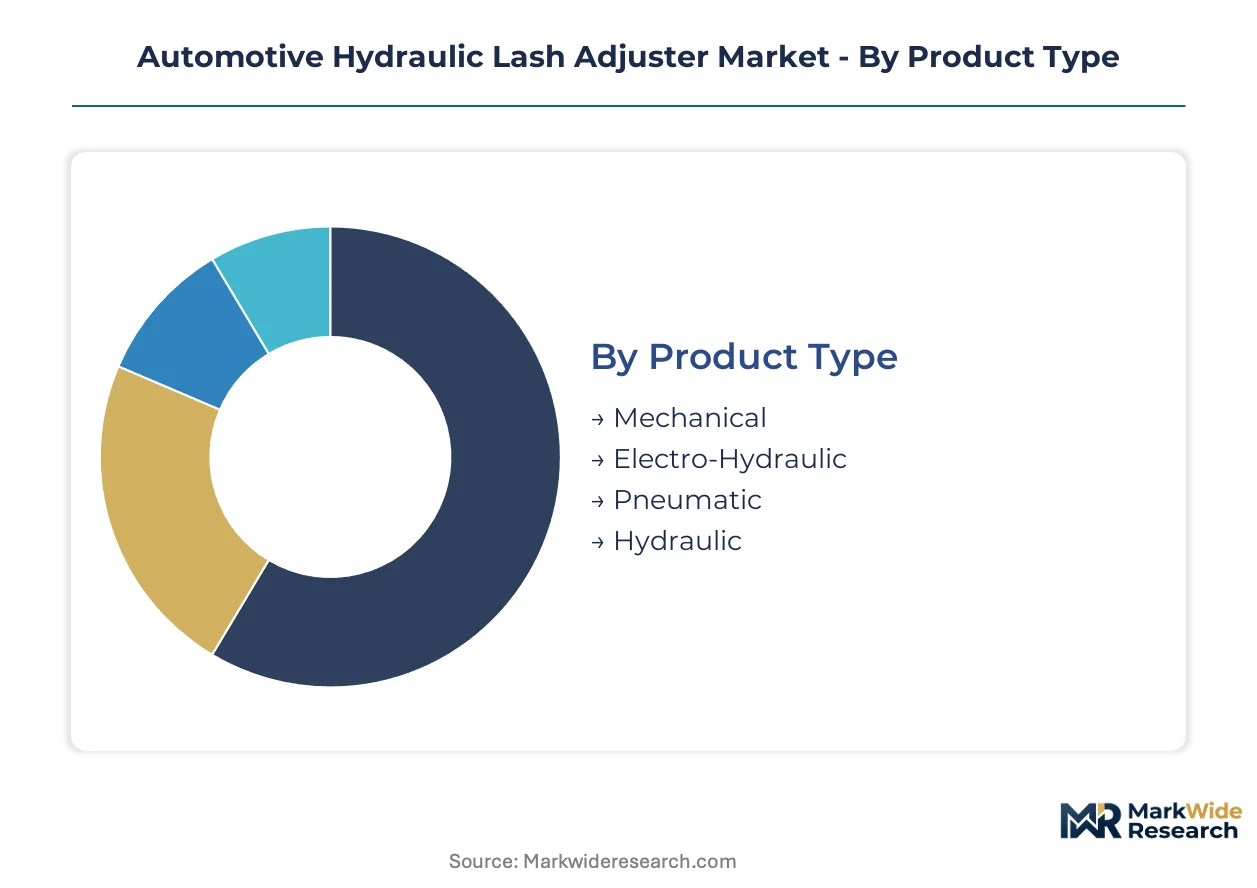
Automotive hydraulic lash adjuster procurement patterns diverge sharply across product architectures and supply chain tiers. Capital allocation, technical validation cycles, and margin structures vary by segment in ways that reshape supplier competitiveness.
Product Type:
Electro-hydraulic variants demand the heaviest upfront tooling investment due to solenoid integration and software validation requirements.
- Hydraulic:Self-contained spring-biased cylinders operating at 15-60 psi oil pressure dominate light-duty gasoline engine fitment. Passenger vehicle OEMs in Germany and Japan specify these units for noise-vibration-harshness compliance under Euro 7 and domestic emissions mandates.
- Electro-Hydraulic:Solenoid-actuated designs enabling real-time clearance modulation synchronize with variable cam timing systems. Toyota and BYD procurement for hybrid Atkinson-cycle engines is accelerating specification rates despite higher per-unit costs.
- Mechanical:Solid lifter designs persist in cost-sensitive commercial vehicle segments where manual lash adjustment intervals remain acceptable.
- Pneumatic:Compressed-air compensation systems serve niche industrial engine applications outside mainstream automotive volumes.
Hydraulic adjusters absorb the bulk of installed capacity; electro-hydraulic variants are expanding most quickly.
End User:
Direct OEM contracts concentrate the highest value-per-unit transactions and longest validation horizons.
- OEMs:Volkswagen, BMW, and Ford powertrain divisions specify precision adjusters through 5-7 year platform agreements. Euro 7 tolerance requirements are tightening qualification standards for direct supplier relationships.
- Tier-1 Suppliers:Schaeffler and Cummins component divisions bundle lash adjusters into camshaft module assemblies. Integrated forging-to-assembly operations in Germany and captive metallurgy expertise defend margin structures against material volatility.
- Vehicle Assemblers:Detroit-based light-truck manufacturers sustain high-volume contracts through automated adjuster lines with Tenneco.
- Aftermarket Providers:Independent repair networks and specialized distributors serve replacement demand with price-competitive sourcing, though growth velocity trails OEM-Tier-1 channels.
OEMs lock in the majority of premium capacity; Tier-1 Suppliers are gaining share fastest through subsystem integration.
Component:
Cylinder head integration requires the most complex machining coordination due to multi-component valve train assembly.
- Cylinder Head:Lash adjuster bores machined directly into aluminum castings demand sub-micron tolerance alignment with camshaft journals. German and Japanese precision machining clusters concentrate this high-value work.
- Camshaft:Adjuster-to-lobe proximity in overhead cam designs enables compact packaging but intensifies thermal management requirements under elevated engine loads.
- Engine Block:Pushrod V-engine architectures locate adjusters in block-mounted lifter bores, typical of North American heavy-duty applications.
- Crankshaft:Indirect adjuster mounting via timing chain tensioners serves secondary valve train synchronization in specific diesel configurations.
Cylinder head placement commands the deepest supplier integration; camshaft mounting is climbing the fastest with overhead cam proliferation.
Installation:
Stationary assembly lines absorb the greatest capital equipment allocation for automated adjuster insertion and leak testing.
- Stationary:Dedicated engine plant lines in Stuttgart, Aichi, and Detroit execute high-volume adjuster installation with robotic precision. EPA and NHTSA traceability requirements mandate serialized component tracking.
- Onshore:Regional engine assembly within vehicle markets reduces logistics exposure for just-in-time valve train delivery.
- Offsite:Modular powertrain pre-assembly at Tier-1 facilities permits quality gate consolidation before final vehicle integration.
- Mobile:Field service replacement protocols support commercial vehicle fleet maintenance with portable adjuster installation tooling.
Stationary installation retains the dominant footprint; onshore configuration is gaining share fastest with regional supply chain restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate the highest-value precision machining capacity for valve-train components, while China and the United States absorb the largest absolute procurement volumes for passenger and commercial vehicle programs.
Germany
Volkswagen and BMW powertrain divisions source precision adjusters through multi-year platform agreements with integrated Tier-1 suppliers. ECHA sunset dates for chromium trioxide hard-chrome plating force accelerated qualification of trivalent chromium alternatives by 2025. Baden-Württemberg's Stuttgart engineering corridor hosts Schaeffler's forging-to-assembly operations defending margin structures against specialty steel volatility.
China
BYD and domestic OEMs expand parallel hybrid architectures requiring electro-hydraulic adjusters for Atkinson-cycle valve phasing. MIIT enforces GB fuel consumption limits that reward friction reduction through low-leakage lash adjuster designs. Yangtze River Delta machining clusters in Shanghai and Jiangsu province concentrate domestic supplier capacity for NEV credit system compliance.
Japan
Toyota procurement for hybrid powertrains sustains specification rates for solenoid-integrated adjusters despite higher per-unit costs. METI industrial standards govern precision tolerance validation for sub-micron valve-train components. Aichi and Shizuoka prefectures host concentrated machining capacity exposing procurement continuity to seismic disruption risks.
United States
Detroit-based light-truck manufacturers sustain high-volume contracts through automated adjuster lines serving SUV and pickup segments. NHTSA corporate average fuel economy rules reward engine efficiency gains from optimized valve timing systems. Midwest engine plants in Michigan and Ohio execute serialized component tracking for EPA traceability mandates.
South Korea
Hyundai and Kia powertrain engineering centers specify precision adjusters for turbocharged gasoline direct injection engines. MFDS-equivalent industrial quality frameworks align with export market requirements for European and North American vehicle programs. Seoul Capital Area suppliers integrate camshaft and adjuster control into unified mechatronic modules for hybrid platform export.
Automotive Hydraulic Lash Adjuster Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with direct OEM relationships concentrating premium capacity and Tier-1 subsystem bundling capturing integration value. The supplier base organizes around three archetypes: integrated forging-to-assembly operators with captive metallurgy, high-volume automated producers serving Detroit and Stuttgart programs, and precision machining specialists clustered in Japanese industrial prefectures. Dominant competitive moves include backward integration into specialty steel supply and electro-hydraulic architecture development for hybrid powertrain penetration.
Among Germany-based integrated suppliers, Schaeffler Technologies AG & Co. KG exemplifies the forging-to-assembly archetype with upstream material control. Cummins Inc. represents North American heavy-duty engine program concentration with metallurgy expertise defending input cost structures. Tenneco Inc. occupies the high-volume automated production position serving light-truck OEM contracts. These three anchors illustrate how geographic specialization and supply chain configuration shape competitive positioning across passenger and commercial vehicle segments.
| Leading Market Players |
|---|
| Cummins Inc. |
| Tenneco Inc. |
| Schaeffler Technologies AG & Co. KG |
| Johnson Lifters LLC |
| Elgin Industries |
| Eaton Corporation plc |
| Mahle GmbH |
| GT Technologies Inc. |
| Nittan Valve Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Passenger vehicle OEMs in Germany and Japan concentrate procurement authority through multi-year platform agreements, locking in contract-based long-term offtake pricing that insulates Tier-1 suppliers from spot volatility while compressing margins for non-integrated competitors. This buyer concentration enables volume-tiered negotiations where electro-hydraulic architectures command premium positioning against conventional hydraulic units.
Pricing Analysis
Volume-margins split sharply between high-unit OEM contracts and aftermarket replacement channels. Three-tier pricing structure across premium electro-hydraulic, standard hydraulic, and economy mechanical levels reflects certification grade differentiation under Euro 7 and GB fuel consumption mandates. Cost compression in conventional hydraulic tiers is intensifying because specialty chromium and nickel alloy inputs face energy-intensive smelting price pressure. Aftermarket distributors exhibit highest price sensitivity, while hybrid powertrain engineering divisions at Toyota and BYD accept premium positioning for cam-phasing precision.
Supply Chain Analysis
Single-source vulnerability sits with Japan's Aichi and Shizuoka prefectures, where master machinist capacity for sub-micron grinding concentrates without geographic diversification. Forged adjuster bodies draw from German and Chinese specialty steel networks, with high-chromium formulations resting on captive metallurgy at Cummins and Schaeffler. Tariff exposure on precision-machined components threatens procurement continuity for Detroit-based assemblers. Distribution runs through Tier-1 subsystem bundlers who consolidate valve-train modules before final engine plant delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive hydraulic lash adjuster procurement is transitioning from mechanical legacy architectures toward electro-hydraulic integration, with solenoid-actuated designs displacing conventional spring-biased cylinders in hybrid powertrain applications.
For Market Incumbents: Anchor defensive positioning through backward integration into specialty chromium steel supply and electro-hydraulic R&D capacity expansion in Germany's Stuttgart corridor. Battery-electric platform substitution threatens long-term ICE program volumes, making hybrid-compatible architecture development the critical margin defense lever. Schaeffler-style forging-to-assembly operations demonstrate how upstream material control insulates against input cost volatility. For New Entrants and Emerging Players: Euro 7 proposals in Europe open a window for trivalent chromium and ceramic coating qualification services ahead of ECHA sunset deadlines. White space concentrates in predictive aftermarket replacement programs for North American heavy-duty fleets unbundling valve-train maintenance from powertrain warranties. A distributor-partnership go-to-market model bypasses entrenched OEM-Tier-1 direct contracting barriers. For Investors and Strategic Acquirers: The window for entry favors precision machining specialists with electro-hydraulic software-hardware co-development capabilities. Long-term viability hinges on hybrid powertrain penetration rates over the next decade. Watch Toyota and BYD procurement acceleration for Atkinson-cycle adjuster specifications as the inflection signal for technology-transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Architecture Development | Enables cam phasing synchronization for Toyota and BYD hybrid platforms. |
| Specialty Steel Backward Integration | Secures upstream material consistency against chromium price volatility. |
| Trivalent Chromium Qualification | Meets ECHA REACH compliance deadlines for BMW and Volkswagen programs. |
| Predictive Aftermarket Programs | Aligns inventory with Schneider National telematics-derived duty cycles. |
| Regional Machining Capacity Expansion | Reduces seismic exposure from Japan's Aichi and Shizuoka concentration. |
Study Parameters
Vehicle production databases, IHS Markit registration data, and SEC filings from Tier-1 suppliers formed the secondary backbone for volume and value estimation. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and precision machining specialists combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated segment-level volumes across vehicle class, propulsion architecture, and content per vehicle dimensions, while top-down cross-checks validated aggregate market scale against OEM production schedules. CAGRs were derived from fitted trend extrapolation incorporating MIIT GB fuel consumption limit enforcement trajectories and NHTSA CAFE rule incentive structures across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for battery-electric platform penetration would alter the outlook for ICE valve-train component demand. Forecasts reflect assumptions about hybrid powertrain mix, regulatory enforcement timing, and specialty steel supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Engine Actuators Market
Powertrain
Engine Flush Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Europe Turbocharger Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Brazil Automotive Actuators Market