
 Automotive Engine Oil Coolers Market | 2026-2036
Automotive Engine Oil Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Oil Coolers Market Outlook
Chinese aluminum foundry capacity is broadening the supplier base for heat exchanger cores. MAHLE GmbH leverages captive die-casting operations to control alloy sourcing costs. Denso Corporation anchors its position through integrated thermal systems design. Dana Incorporated competes on modular cooler architectures that slot into electrified powertrain packages.
An automotive engine oil cooler is a heat exchanger that maintains lubricant viscosity within operational bands by transferring thermal energy to ambient air, engine coolant, or secondary oil circuits; typical units employ aluminum brazed cores with turbulated tube designs to achieve heat rejection rates between 5 and 25 kW depending on duty cycle. Water-cooled variants command the dominant share in passenger car applications where packaging density and precise temperature control matter most. Aluminum as a material category leads on weight-driven OEM specifications, though copper-nickel alloys retain niche positions in heavy-duty and performance installations where corrosion resistance and thermal conductivity trade-offs favor longevity over mass reduction.
EPA fuel economy mandates and Euro 7 emissions frameworks from the European Commission are tightening thermal management requirements across combustion and hybrid architectures. NHTSA safety standards in the United States govern cooler integrity under crash loads and pressure cycling. Stakeholders must monitor how powertrain electrification splits thermal budgets between battery, inverter, and residual engine oil loops as vehicle architectures diverge.
Market Dynamics
Powertrain electrification is fragmenting thermal budgets across battery, inverter, and residual combustion loops, forcing cooler suppliers to engineer modular architectures that span hybrid and full-electric platforms without platform-specific redesign.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent thermal efficiency mandates in the United States are compelling OEMs to specify precision oil temperature control in downsized turbocharged engines.
- Aluminum brazed core technology:Advances in turbulated tube designs are expanding heat rejection capacity while maintaining packaging density for passenger car applications.
- Germany's automotive engineering corridor:Concentrated R&D activity around Stuttgart and Munich is accelerating validation cycles for next-generation cooler architectures.
Market Restraints
- Primary aluminum price volatility:Smelter energy costs and LME pricing swings compress margin predictability for heat exchanger manufacturers.
- Chinese foundry concentration:Geographic clustering of aluminum casting capacity creates supply vulnerability during regional energy rationing or export policy shifts.
- Copper-nickel alloy substitution ceiling:Weight-driven OEM specifications block corrosion-resistant materials from penetrating mass-market passenger segments despite superior longevity.
Strategic Opportunities
- Euro 7 emissions framework:The European Commission's pending thermal management requirements create specification windows for integrated oil-coolant-battery systems.
- Electrified powertrain packaging:Convergence of inverter cooling and residual engine oil loops enables multi-fluid heat exchanger designs.
- Performance vehicle builders:Aftermarket thermal upgrade demand from track-day and motorsport segments supports premium pricing for specialized cores.
Industry Challenges
- Multi-physics simulation talent scarcity:CFD and thermal-mechanical co-design expertise sits concentrated within tier-one suppliers and specialized consultancies.
- NHTSA crash-load certification:Pressure cycling and structural integrity validation timelines extend product development cycles by 8-14 months.
- Legacy combustion-thermal legacy integration:Existing oil circuit architectures resist seamless retrofit into electrified platforms without substantial plumbing redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Oil Coolers Market |
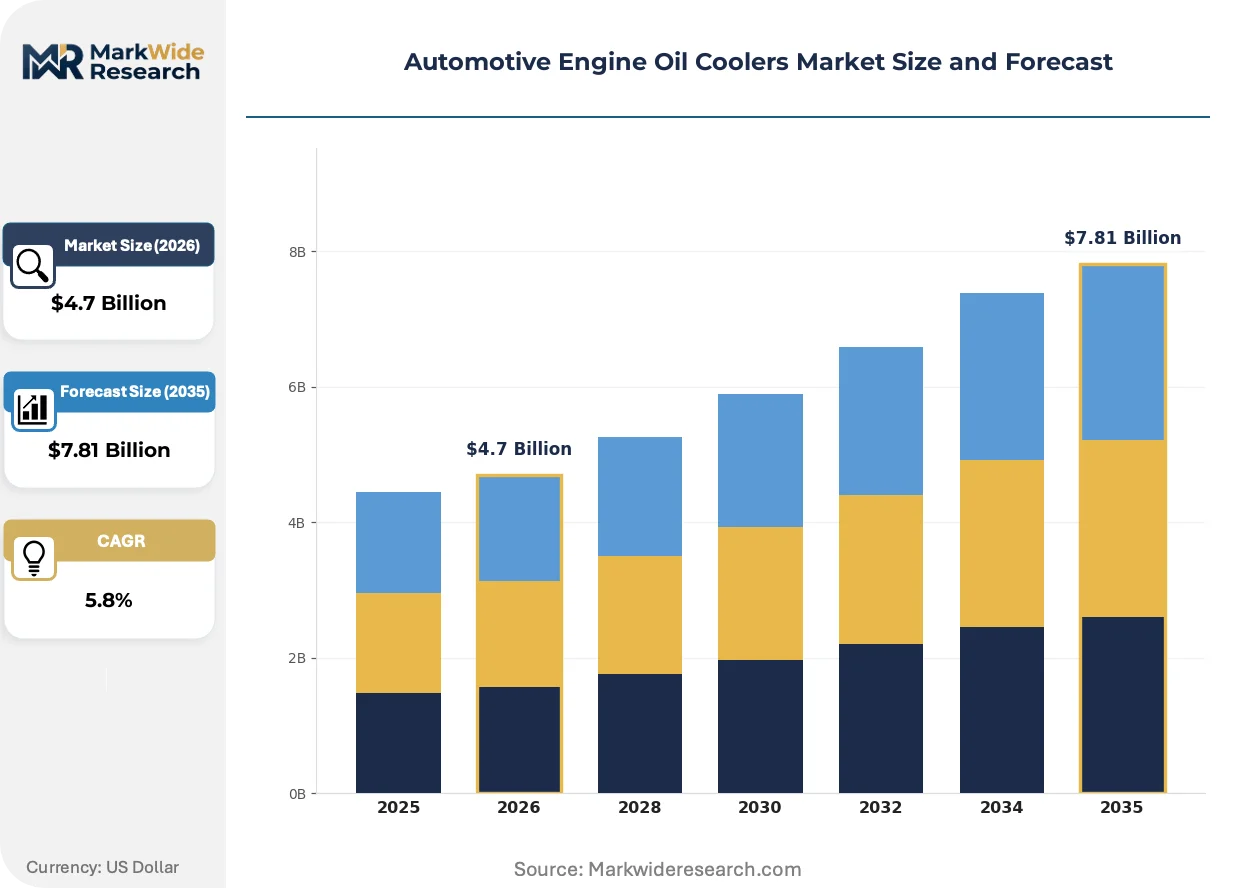
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Oil-Cooled, Hybrid Material: Aluminum, Copper, Stainless Steel, Plastic End User: OEMs, Aftermarket Providers, Auto Repair Shops, Fleet Operators Installation Type: On-Road, Off-Road, Performance Vehicles, Heavy-Duty Machinery |
| Companies Covered | MAHLE GmbH, Denso Corporation, Dana Incorporated, Modine Manufacturing Company, Hanon Systems, Valeo SA, Setrab AB, PWR Advanced Cooling Technology, TitanX Engine Cooling Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Oil Coolers Market Strategic Shifts
Additive manufacturing is infiltrating heat exchanger prototyping, compressing iteration cycles from months to weeks. Brazing process automation and real-time quality monitoring are simultaneously tightening joint integrity. These forces are converging to redefine supplier capability thresholds.
Printed aluminum lattice structures for turbulator inserts are rewriting core thermal performance limits. Performance vehicle builders and prototype shops are adopting these geometries for validation units. The technology is compressing the traditional trade-off between pressure drop and heat transfer coefficient.
REACH substance restrictions on hexavalent chromium coatings are forcing conversion to trivalent alternatives or laser-welded joint architectures. European suppliers bear the steepest compliance costs during qualification transitions. Water-cooled variants for hybrid applications face the tightest reformulation timelines.
Fleet procurement consolidation among commercial vehicle operators is compressing supplier negotiation cycles and unbundling after-sales service contracts. Direct sourcing from foundries is displacing traditional tiered distribution in North American heavy-duty segments. This pattern is most visible in long-haul trucking fleets operating across the US Midwest corridor.
Automotive Engine Oil Coolers Market Segmentation
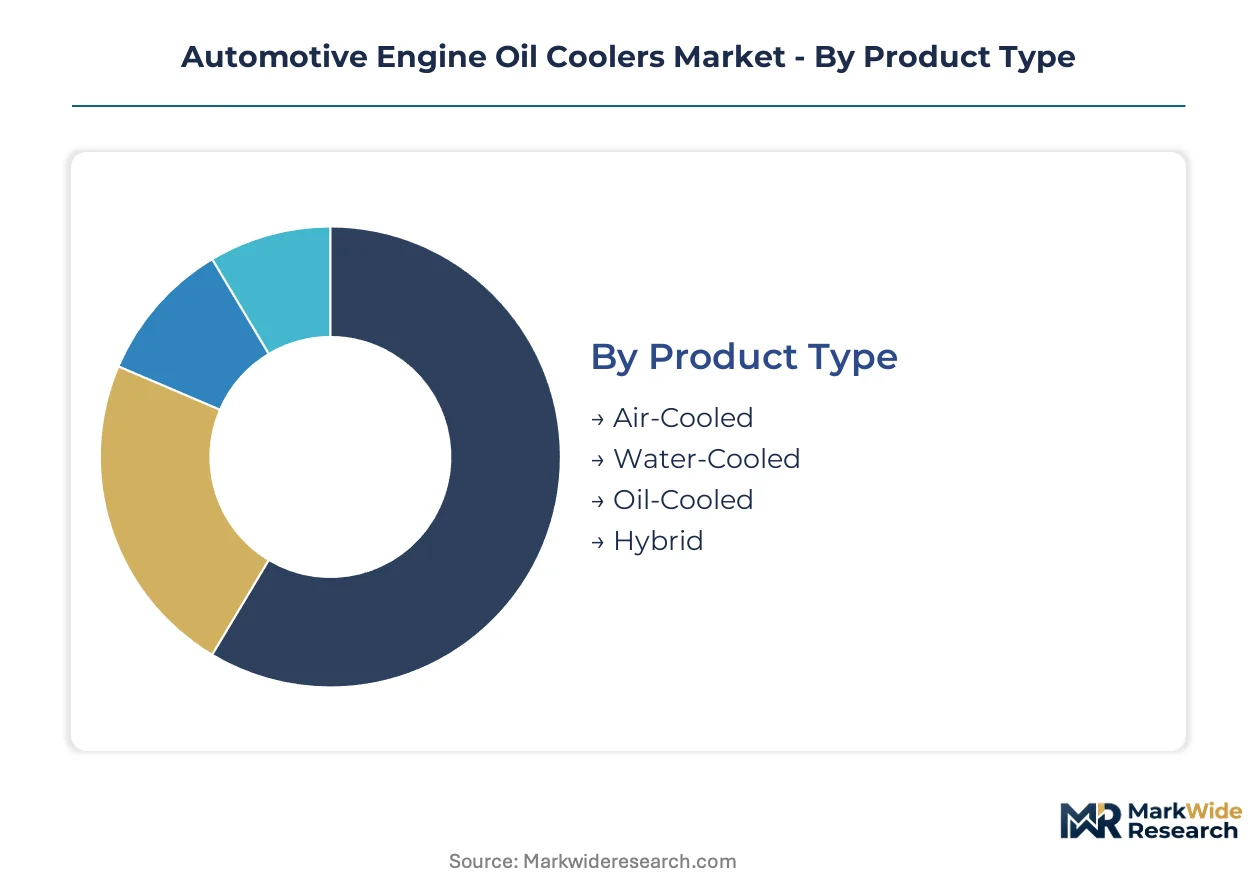
Segmentation in automotive engine oil coolers reveals how thermal management architectures diverge across powertrain types, material specifications, and channel economics. Suppliers must align production footprints with distinct margin profiles and certification requirements.
Product Type:
Supply concentration in water-cooled cores has concentrated foundry capacity around Stuttgart and Munich engineering corridors, while air-cooled production disperses across lower-cost manufacturing zones.
- Water-Cooled:Aluminum brazed cores with turbulated tube designs achieve precise temperature control in passenger car applications where packaging density constrains form factor. Demand concentrates in Germany's automotive engineering corridor as Euro 7 thermal efficiency mandates tighten specifications for downsized turbocharged engines.
- Air-Cooled:Fin-and-tube architectures reject thermal energy directly to ambient airflow, eliminating coolant circuit complexity. Heavy-duty machinery installations across the US Midwest corridor favor these units for field serviceability and crash-load durability under NHTSA safety standards.
- Oil-Cooled:Secondary oil loop designs serve high-performance powertrains requiring thermal isolation from engine coolant circuits.
- Hybrid:Multi-fluid architectures integrate residual combustion oil loops with inverter cooling for electrified platforms.
Today's leader: Water-Cooled. Tomorrow's challenger: Hybrid.
Material:
Cost tiers separate aluminum brazed cores from premium copper-nickel alloys, with stainless steel and plastic occupying intermediate positions in specialized applications.
- Aluminum:Weight-driven OEM specifications dominate passenger car volume, though primary aluminum price volatility compresses margin predictability for heat exchanger manufacturers dependent on LME pricing swings.
- Copper:Superior thermal conductivity and corrosion resistance command premium positioning in heavy-duty and performance installations where longevity outweighs mass reduction priorities.
- Stainless Steel:Niche deployment in extreme-duty environments requiring pressure cycling resistance beyond aluminum capability limits.
- Plastic:Emerging in low-pressure auxiliary cooling circuits for cost-sensitive aftermarket replacements.
Aluminum commands current volume. Copper defends premium positioning.
End User:
Procurement patterns diverge sharply between OEM specification engineering and aftermarket price sensitivity, with fleet operators unbundling service contracts to source direct from foundries.
- OEMs:Integrated thermal systems design requires multi-physics simulation talent concentrated within tier-one suppliers, extending validation cycles by 8-14 months under NHTSA crash-load certification timelines.
- Aftermarket Providers:Performance vehicle builders scaling thermal management purchases support premium pricing for specialized cores in track-day and motorsport segments.
- Auto Repair Shops:Service bay economics favor standardized replacement architectures with minimal plumbing redesign requirements.
- Fleet Operators:Commercial vehicle procurement consolidation across long-haul trucking corridors compresses supplier negotiation cycles and displaces traditional tiered distribution.
OEMs anchor specification control. Fleet operators are gaining procurement leverage fastest.
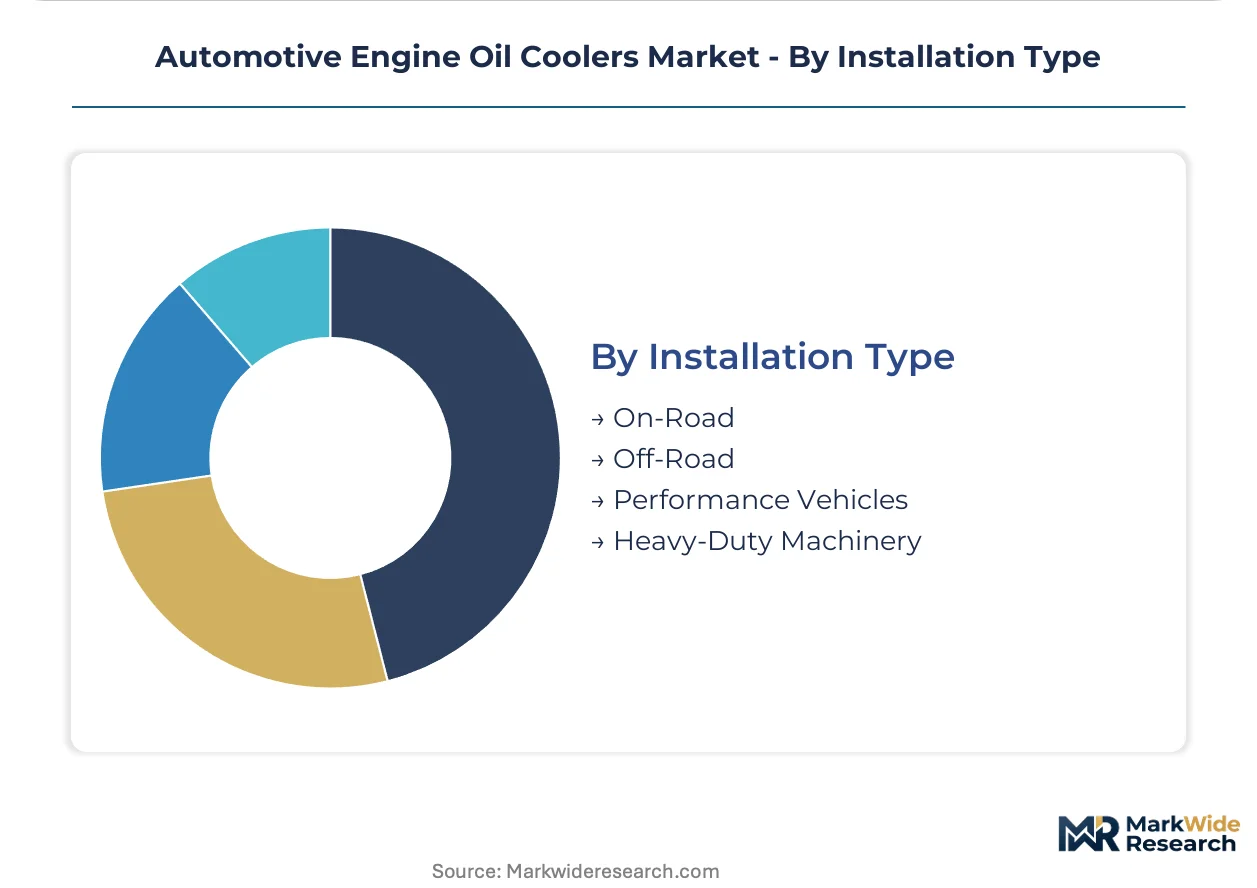
Installation Type:
Application maturity separates on-road passenger volume from specialized off-road and performance segments with divergent thermal duty cycles and margin structures.
- On-Road:Passenger car applications demand water-cooled variants for precise temperature control within constrained engine bay packaging, with EPA Corporate Average Fuel Economy standards compelling precision oil temperature specifications.
- Off-Road:Construction and agricultural machinery prioritize field serviceability and debris tolerance over thermal optimization, favoring air-cooled architectures with robust mechanical joint integrity.
- Performance Vehicles:Track-day thermal loads require additive-manufactured turbulator inserts and printed aluminum lattice structures rewriting core thermal performance limits.
- Heavy-Duty Machinery:Mining and logging equipment specifications prioritize pressure cycling durability and corrosion resistance over weight minimization.
On-Road maintains volume dominance. Performance Vehicles command steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor concentrates precision thermal management R&D, while China's aluminum foundry expansion reshapes upstream material economics for heat exchanger producers worldwide.
United States
EPA Corporate Average Fuel Economy standards compel OEMs to specify precision oil temperature control in downsized turbocharged engines across passenger car fleets. NHTSA crash-load certification governs cooler integrity under pressure cycling and structural stress validation. The US Midwest corridor anchors heavy-duty machinery installations where air-cooled architectures dominate field serviceability requirements.
Germany
Euro 7 emissions frameworks from the European Commission tighten thermal efficiency mandates across hybrid and combustion powertrains. REACH substance restrictions on hexavalent chromium coatings force conversion to trivalent alternatives or laser-welded joint architectures. Stuttgart and Munich engineering clusters accelerate validation cycles for next-generation cooler architectures through concentrated tier-one supplier presence.
China
Domestic aluminum foundry capacity expansion broadens the supplier base for heat exchanger cores serving both local OEMs and export markets. MIIT fuel consumption regulations and dual carbon goals pressure thermal management efficiency in vehicle production. Yangtze River Delta manufacturing zones concentrate die-casting operations that feed into integrated thermal systems supply chains.
Japan
METI energy efficiency standards and JIS certification requirements shape precision engineering specifications for compact water-cooled variants. Automotive OEMs source integrated thermal systems design from tier-one suppliers with captive multi-physics simulation capabilities. Kanto and Chubu industrial regions host concentrated R&D activity for turbulated tube design advances.
South Korea
Domestic OEM electrification roadmaps fragment thermal budgets across battery, inverter, and residual engine oil loops. MFDS automotive component standards and national carbon neutrality targets pressure supplier adaptation to hybrid platform architectures. Seoul Capital Area engineering centers drive specification engineering for multi-fluid heat exchanger integration.
Automotive Engine Oil Coolers Market Competitive Environment
German producers anchor one tier; Japanese and Korean specialists hold integrated thermal systems capabilities; Chinese fabricators compete on aluminum core economics. The supplier base organizes around three strategic archetypes: captive die-casting operators controlling alloy sourcing costs, modular architecture designers slotting into electrified powertrain packages, and aftermarket specialists serving performance vehicle builders. Dominant competitive moves include backward integration into aluminum smelting and capacity expansion near OEM assembly plants.
Within the integrated systems tier, MAHLE GmbH and Denso Corporation exemplify archetypes of captive supply chain control and multi-fluid thermal design respectively. Dana Incorporated occupies a position among modular architecture specialists. These three anchors represent distinct strategic postures: German engineering depth, Japanese precision manufacturing scale, and North American electrification platform adaptation.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Denso Corporation |
| Dana Incorporated |
| Modine Manufacturing Company |
| Hanon Systems |
| Valeo SA |
| Setrab AB |
| PWR Advanced Cooling Technology |
| TitanX Engine Cooling Inc |
| Others |
Value Chain & Pricing Dynamics
Captive die-casting operations at tier-one suppliers anchor both supply security and pricing power in automotive engine oil coolers, with MAHLE GmbH's in-house alloy sourcing insulating margin positions against LME aluminum volatility while compressing cost pass-through to OEM procurement teams.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for aluminum brazed cores, with domestic foundry expansion enabling contract-based long-term offtake structures that undercut spot-market exposure. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified water-cooled variants from aftermarket air-cooled replacements and fleet-direct heavy-duty units. Pricing pressure stems from primary aluminum energy costs and Chinese export policy uncertainty. Fleet operators exhibit highest price sensitivity through direct foundry sourcing, while performance vehicle builders accept premium positioning for additive-manufactured cores.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and the US Midwest corridor anchor hub-and-spoke patterns for water-cooled and air-cooled variants respectively. Geographic supply concentration clusters in Germany, China, and Japan for precision die-casting and turbulated tube fabrication. Raw material dependencies draw from primary aluminum smelters, copper-nickel alloy processors, and brazing flux chemical suppliers. Single-source vulnerability concentrates in Chinese foundry energy rationing exposure. Distribution runs through tier-one supplier direct-to-OEM channels for original equipment, with aftermarket flowing through specialized thermal management distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive engine oil coolers function as a stable compounder, with EPA and Euro 7 thermal efficiency mandates embedding recurring specification upgrades that sustain replacement demand across combustion and hybrid platform generations.
For Market Incumbents: Anchor defensive positions through backward integration into aluminum smelting partnerships that lock in alloy cost predictability against LME volatility. Deepen captive die-casting capabilities near Stuttgart and Munich engineering clusters to compress validation cycle timelines. Counter Chinese foundry price competition with NHTSA crash-load certification barriers that extend newcomer development cycles. For New Entrants and Emerging Players: Aftermarket distributors represent the most penetrable channel partner type for bypassing OEM specification lock-in held by MAHLE and Denso. Target performance vehicle builders scaling thermal management purchases with additive-manufactured turbulator inserts that rewrite heat transfer limits. Pursue white-space in hybrid multi-fluid architectures where integrated oil-coolant-battery system design expertise remains scarce. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket specialists with captive distribution networks because fleet procurement consolidation is displacing traditional tiered distribution. Long-term viability centers on electrification platform adaptation capability. Acquisition target archetype: mid-cap fabricators with NHTSA certification and additive manufacturing prototyping capacity. Signal to watch: OEM announcements of dedicated hybrid thermal system integration contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive alloy sourcing insulates margin positions against LME price volatility and Chinese energy rationing. |
| Additive Manufacturing Prototyping Capacity | Printed lattice turbulator inserts compress heat transfer validation cycles from months to weeks for performance segments. |
| NHTSA Crash-Load Certification Investment | Pressure cycling validation timelines create 8-14 month barriers against low-cost import competition. |
| Multi-Fluid Heat Exchanger Platform Development | Converged oil-coolant-battery architectures capture Euro 7 specification windows for hybrid powertrains. |
| Regional Distribution Center Expansion | Hub-and-spoke proximity to Stuttgart and Munich engineering corridors accelerates OEM validation cycle participation. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and South Korea, with primary inputs from each market combining interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, aluminum foundry operations managers, and thermal systems R&D directors. Secondary validation draws from EPA fuel economy filings, NHTSA safety standard documentation, European Commission Euro 7 framework proposals, MIIT fuel consumption regulations, and vehicle production databases. Bottom-up segment sizing triangulates against top-down OEM thermal budget allocations.
Rate-of-change decomposition separates volume drivers from value mix shifts across the projection horizon. Segmentation dimensions modeled include product type, material specification, end-user channel, and installation application. CAGRs derive from powertrain electrification penetration curves, thermal content per vehicle trajectories, and regional regulatory compliance timelines. Industry-specific forecast inputs incorporate EPA Corporate Average Fuel Economy standard stringency schedules and Euro 7 emissions framework implementation pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to powertrain electrification speed, primary aluminum price volatility, and Chinese export policy shifts. Forecasts reflect documented assumptions around regulatory implementation schedules and OEM platform architecture decisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Global Automotive Engine Valves Market