
 Hummus Market | 2026-2036
Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Hummus Market Analysis
The capital-intensity divergence between industrial-scale tahini processors and artisanal chickpea roasters is bifurcating competitive dynamics in hummus manufacturing. Sabra Dipping Company leverages automated cold-fill packaging lines to sustain national distribution density across North American retail channels. Cedar's Mediterranean Foods anchors its position through regional sourcing networks that dominate New England and mid-Atlantic foodservice accounts. Strauss Group extends its reach via dairy-adjacent cold-chain infrastructure that competes effectively in European and Middle Eastern markets.
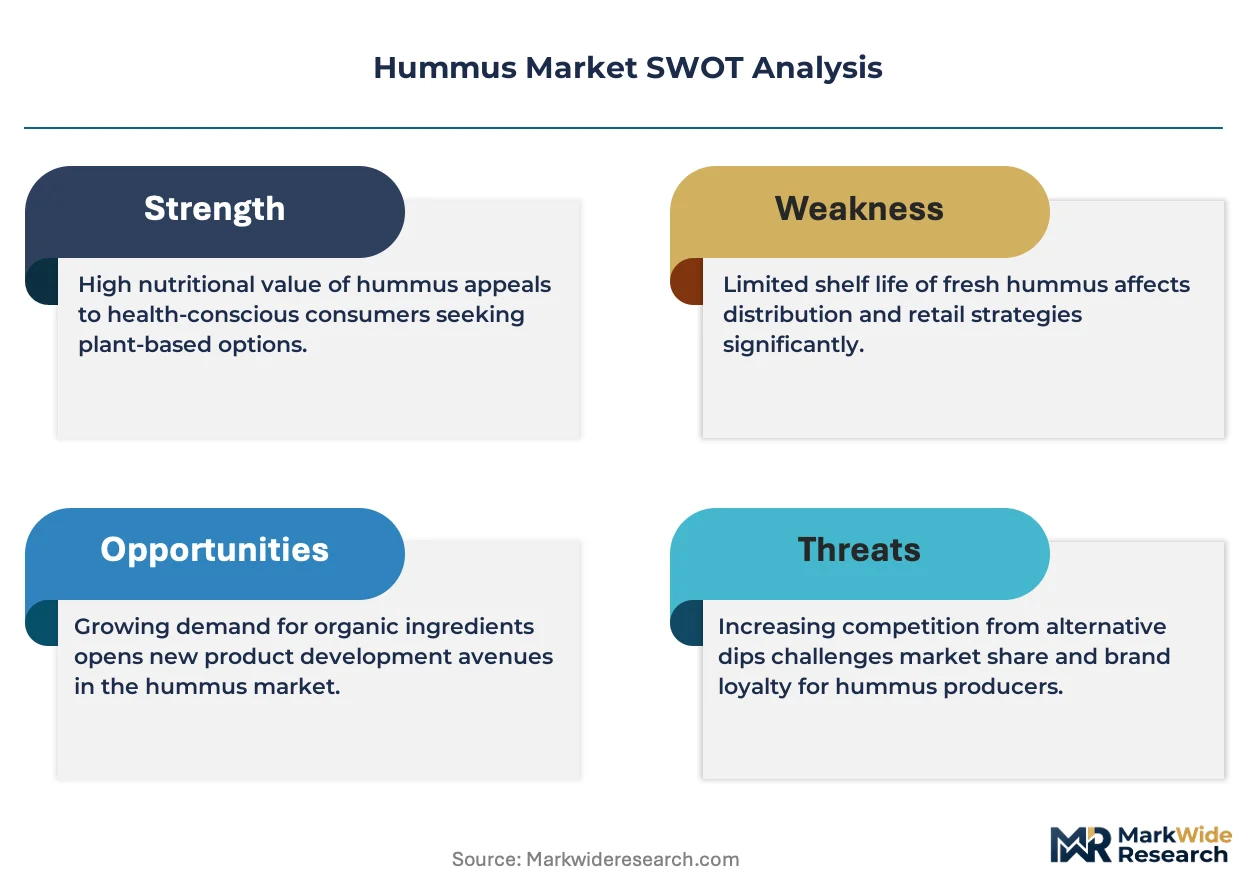
Hummus is a Levantine spread produced by cooking, grinding, and emulsifying chickpeas with tahini, lemon juice, and garlic to achieve a smooth paste with minimum 8% protein content and pH below 4.6 for refrigerated stability. Its primary commercial purpose centers on delivering shelf-stable, high-protein alternatives to dairy-based dips for retail and foodservice channels. Classic formulations still occupy the largest volume share in mature Western markets, though organic ingredient-type variants are capturing margin pools as certification premiums widen. Snack pack formats are growing fastest among form categories, driven by convenience-oriented purchasing in urban supermarkets and online retail channels where single-serve portions reduce per-unit trial barriers.
FDA enforces acidified food regulations under 21 CFR 114 that govern thermal processing and pH monitoring for shelf-stable hummus distributed in the United States. EFSA and EU Green Deal packaging directives are reshaping demand by mandating recycled content thresholds and extended producer responsibility schemes across European supply chains. USDA organic certification and ISO 22000 food safety management standards further segment market access by creating compliance moats for ingredient sourcing and facility audits. Stakeholders must monitor how dual carbon goals in China and evolving FSSAI labeling requirements in India reshape export qualification protocols for tahini and chickpea suppliers.
Market Dynamics
EU Green Deal packaging mandates are compressing margins for prepared food manufacturers while simultaneously advantaging processors with captive recycled-content supply chains and cold-chain density.
Growth Catalysts
- Refrigerated plant-based shelf expansion:Health food retailers in Germany and the Netherlands are dedicating linear footage to high-protein spreads, creating pull-through for premium SKUs with organic certification.
- US acidified food compliance infrastructure:FDA 21 CFR 114 thermal processing requirements have locked in pH monitoring investments that now serve as barriers against new shelf-stable entrants.
- Chickpea protein standardization:ISO 22000-aligned facility audits are enabling tahini suppliers to access co-manufacturing contracts with multinational prepared food brands.
Market Restraints
- Sesame input cost volatility:Ethiopian and Sudanese tahini supply concentration exposes processors to port disruption and currency fluctuation without hedge instruments.
- Extended producer responsibility schemes:EU Green Deal recycled content thresholds force reformulation of multilayer flexible packaging at 15-20% cost premiums.
- pH stability technical ceiling:Refrigerated hummus formulations below 4.6 pH sacrifice flavor complexity, constraining clean-label positioning against fresh competitors.
Strategic Opportunities
- Indian foodservice penetration:FSSAI labeling requirement evolution is opening institutional channels for imported tahini and roasted chickpea ingredients.
- Dual carbon goals alignment:China's MEE emissions standards for food processing create partnership openings for Israeli and Lebanese processors with solar-powered roasting capacity.
- Single-serve format innovation:Snack pack configurations are capturing convenience-oriented purchasing in urban supermarkets and online retail channels.
Industry Challenges
- Cold-chain capex intensity:Automated cold-fill packaging lines require $2-4 million per installation, squeezing mid-scale regional processors.
- Organic certification timeline compression:USDA three-year transition protocols for ingredient sourcing create working capital gaps for chickpea growers switching from conventional.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hummus Market |
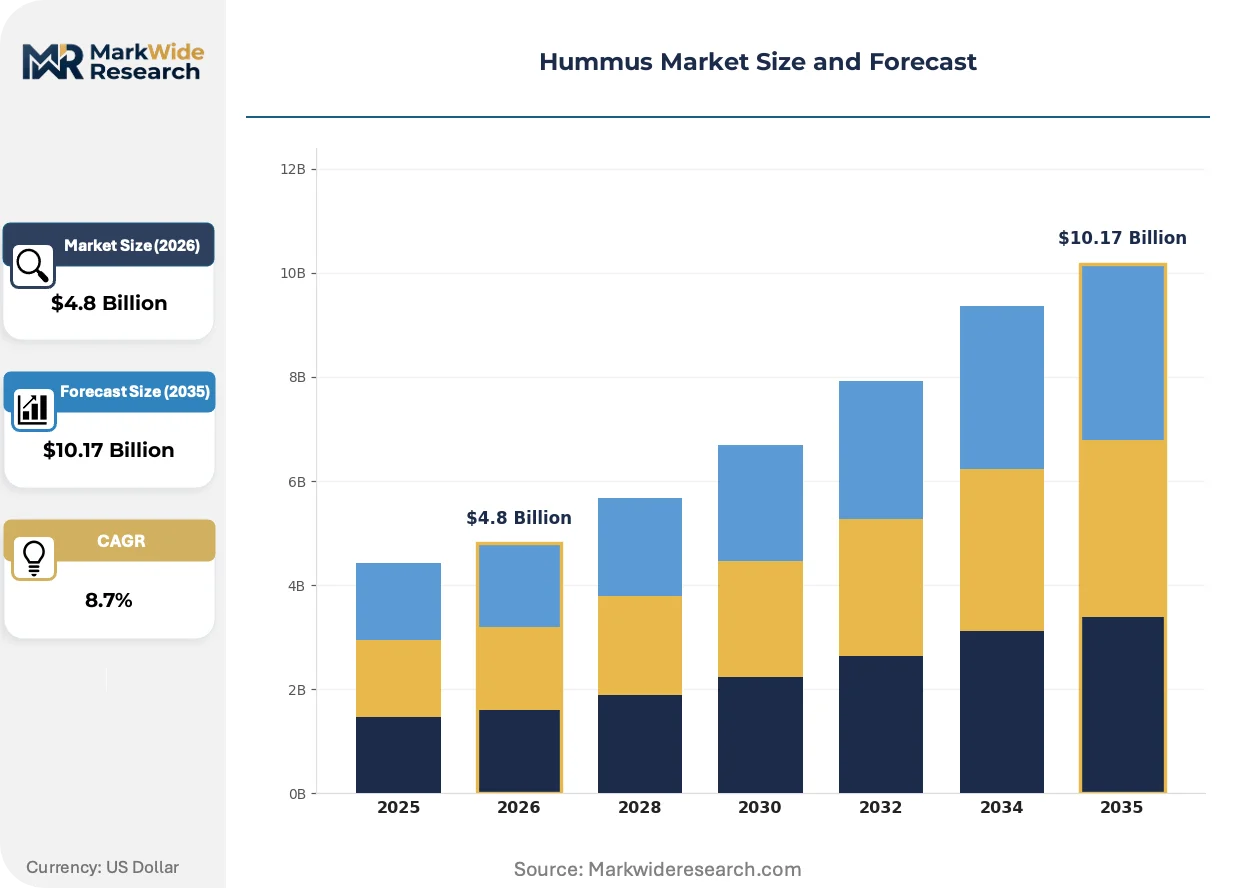
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Roasted Red Pepper, Garlic, Spicy Harissa Form: Spread, Dip, Snack Pack, Bulk Ingredient Type: Traditional, Organic, Gluten-Free, Vegan Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Foodservice |
| Companies Covered | Sabra Dipping Company, Cedar's Mediterranean Foods, The Kraft Heinz Company, PepsiCo, Strauss Group, Hope Foods, Bakkavor Group Plc, Boar's Head Brand, Haliburton International Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hummus Market Emerging Trajectories
Processing technology and packaging regulation are rewriting competitive advantage in hummus manufacturing, separating capital-intensive national distributors from regional specialists.
High-pressure processing is extending refrigerated shelf life without thermal degradation of volatile flavor compounds. Premium organic brands in California and Pacific Northwest natural channels are adopting HPP lines at 40% faster capex cycles than conventional processors. This capability is bifurcating the market between HPP-enabled clean-label premiums and conventional acidified formulations competing on price.
EU Green Deal extended producer responsibility schemes now mandate 35% recycled content in flexible food packaging by 2030. German and French retailers are rejecting suppliers without certified post-consumer resin supply chains. Prepared food manufacturers with backward integration into packaging material recovery are capturing shelf space from importers dependent on virgin multilayer films.
Urban convenience purchasing is rotating demand toward single-serve snack packs and subscription-box formats. Direct-to-consumer channels in London, New York, and Tel Aviv are displacing traditional grocery center-store placement for trial-size SKUs. Foodservice accounts in corporate catering and university dining are specifying portion-controlled packaging to reduce waste compliance costs.
Hummus Market Segmentation
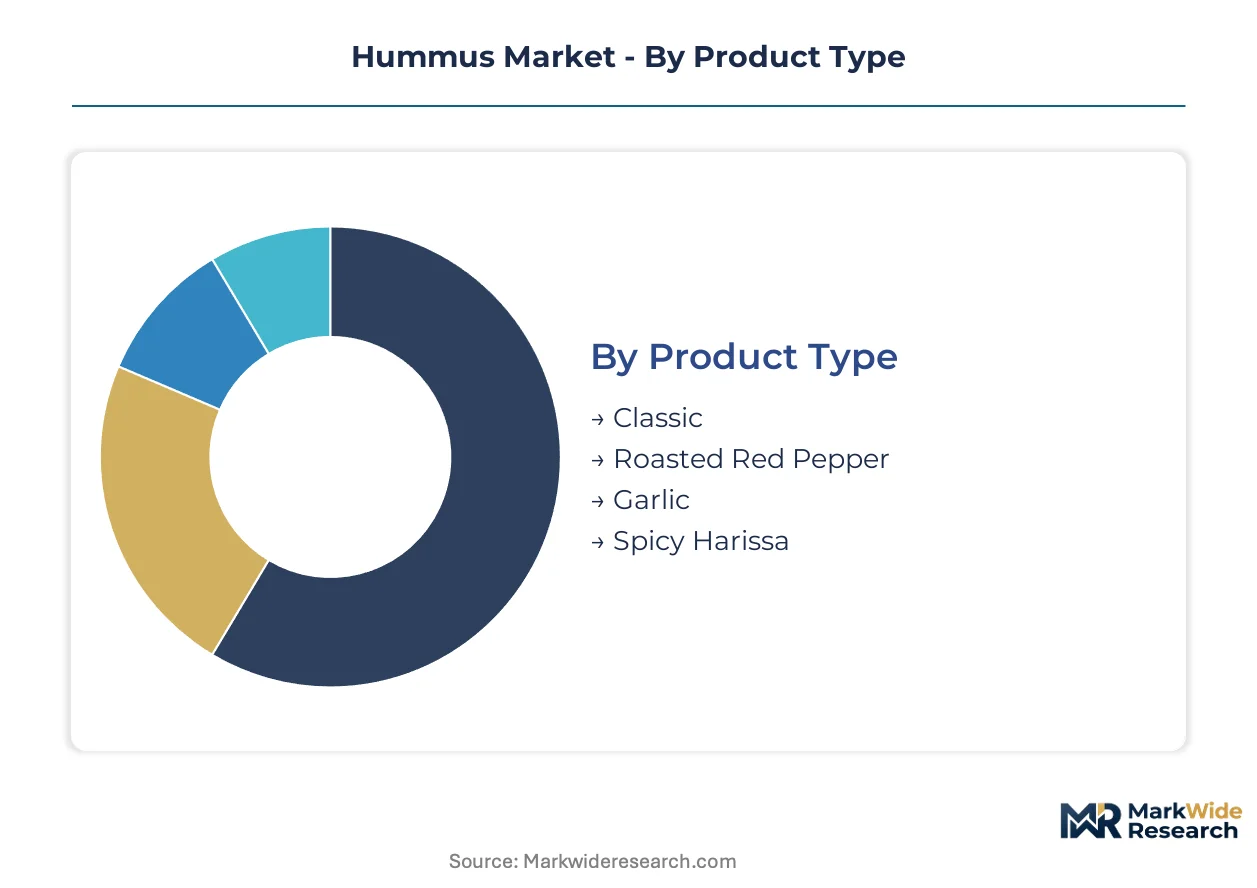
Segmentation in hummus manufacturing determines which facilities, certifications, and cold-chain investments processors must deploy. Channel requirements vary sharply between refrigerated retail, shelf-stable export, and foodservice bulk, forcing distinct operational footprints for each segment combination.
Product Type:
Flavor variants flow through different retail channels based on margin structure and trial behavior. Classic formulations anchor club store and mainstream supermarket volumes, while specialty flavors concentrate in natural channels and foodservice differentiation.
- Classic:Unflavored chickpea-tahini base with minimum 8% protein and pH below 4.6 for refrigerated stability. Demand concentrates in US club stores and German discount retail where price-per-ounce drives purchase decisions against dairy-based alternatives.
- Roasted Red Pepper:Vegetable-inclusion variant requiring modified thermal processing to maintain color stability. UK and Netherlands supermarkets are expanding facings for this segment as meal-prep culture normalizes flavored spreads for lunchbox applications.
- Garlic:Traditional Levantine formulation with elevated allicin content for flavor intensity. Lebanese and Israeli processors dominate supply through Middle Eastern specialty grocers in Paris, London, and Dearborn.
- Spicy Harissa:Chili-forward variant with capsaicin levels requiring tolerance labeling in some jurisdictions. Growth concentrates in direct-to-consumer subscription channels and urban convenience retail in New York and Tel Aviv.
By volume, Classic leads. By growth pace, Spicy Harissa is expanding most quickly.
Form:
Packaging format determines cold-chain capex requirements and shelf-life engineering investments. Each form demands distinct line equipment, with snack packs requiring the most specialized automation.
- Spread:Standard tub format for home consumption and recipe integration. US supermarkets and French hypermarkets allocate center-store refrigerated space based on weekly velocity metrics.
- Dip:Wider-mouth container optimized for immediate consumption with crackers or vegetables. UK meal-deal programs in Tesco and Sainsbury's are standardizing this format for grab-and-go lunch combinations.
- Snack Pack:Single-serve portion with companion dippers or standalone cup. Convenience-oriented purchasing in urban supermarkets and online retail channels is displacing traditional grocery placement for trial-size SKUs.
- Bulk:Foodservice pail or bag-in-box for institutional kitchen repackaging. German corporate catering and US university dining specify this format to reduce per-serving procurement costs.
Spread generates the highest absolute volume. Snack Pack is climbing the fastest as convenience purchasing rotates demand.
Ingredient Type:
Certification tier determines sourcing geography, audit frequency, and margin capture. Each tier requires distinct supplier qualification protocols and facility segregation.
- Traditional:Conventional chickpea and tahini sourcing without third-party certification. Price-competitive positioning in mainstream US and European retail where organic premiums face resistance.
- Organic:USDA or EU organic certification with three-year transition protocols for ingredient sourcing. Health food retailers in Germany and the Netherlands dedicate linear footage to these SKUs, creating pull-through for premium positioning.
- Gluten-Free:Third-party tested to below 20ppm gluten threshold for celiac-safe positioning. UK and Australian retailers require this certification for shelf placement in free-from aisles.
- Vegan:Plant-based positioning without animal-derived ingredients, often overlapping with organic certification. Clean-label demands in California and Pacific Northwest natural channels favor this combined positioning.
Traditional holds volume leadership. Organic is gaining share fastest as certification premiums widen.
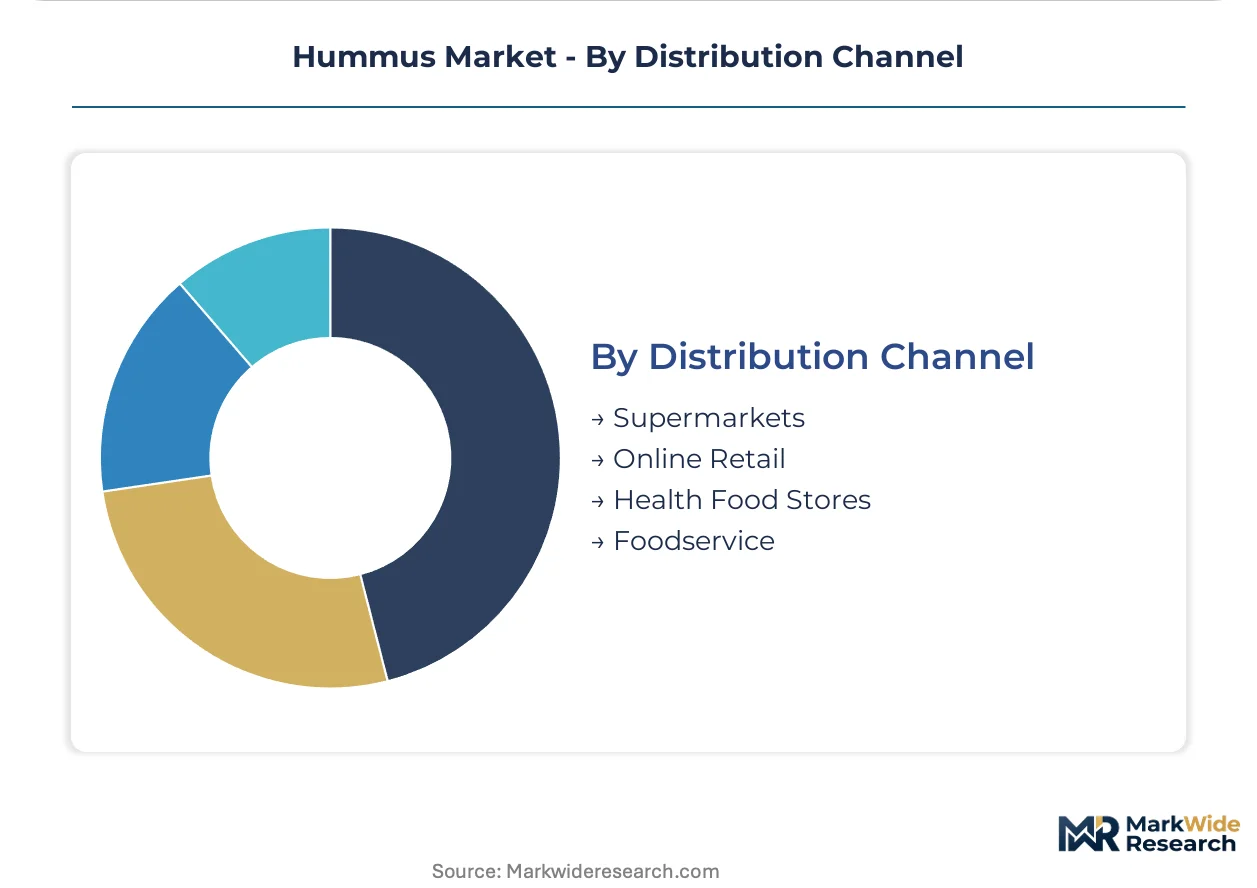
Distribution Channel:
Channel selection dictates packaging format, promotional calendar, and trade spend allocation. Each channel requires distinct salesforce specialization and retailer compliance infrastructure.
- Supermarkets:Multi-banner retail with refrigerated case placement fees and promotional slotting requirements. Sabra and Cedar's compete for linear footage through trade spend and direct store delivery density.
- Online Retail:Direct-to-consumer and third-party marketplace fulfillment with cold-chain logistics requirements. Amazon Fresh and Ocado in London are expanding assortment breadth for subscription-repeat purchases.
- Health Food Stores:Natural channel with organic certification prerequisites and EDLP pricing avoidance. Whole Foods Market and Sprouts Farmers Market in the US, plus Bio c' Bon in France, curate premium SKU mixes.
- Foodservice:Institutional and commercial accounts with portion-control specifications and waste compliance cost reduction. US university dining and German corporate catering are standardizing bulk procurement with sustainability reporting requirements.
Supermarkets dominate volume contribution. Online Retail shows the steepest expansion trajectory as urban convenience purchasing normalizes digital fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the highest price elasticity for refrigerated plant-based spreads, while US club store shoppers prioritize volume-per-dollar over certification premiums. This demand-elasticity contrast shapes where processors invest cold-chain infrastructure versus where they compete on formulation cost.
United States
Club store and mainstream supermarket channels dominate volume, with refrigerated case placement fees concentrating procurement power among national distributors. FDA 21 CFR 114 acidified food regulations enforce pH monitoring investments that lock out shelf-stable entrants without thermal processing infrastructure. Sabra Dipping Company anchors production scale through automated cold-fill packaging lines serving North American retail density.
Germany
Discount retail and health food channels operate in parallel, with organic certification premiums widening fastest in Berlin and Hamburg urban supermarkets. EU Green Deal extended producer responsibility schemes mandate recycled content thresholds that squeeze margin for importers dependent on virgin multilayer films. Bavarian and Baden-Württemberg processors with captive packaging material recovery are capturing refrigerated shelf space from foreign competitors.
United Kingdom
Meal-deal programs at Tesco and Sainsbury's are standardizing dip-format hummus for grab-and-go lunch combinations, driving format innovation. EFSA labeling alignment with evolving FSSAI requirements is opening institutional channel access for tahini suppliers meeting dual-jurisdiction compliance. London and Southeast England concentrate direct-to-consumer subscription growth for single-serve trial formats.
Israel
Domestic consumption per capita remains highest globally, with solar-powered roasting capacity aligning with China's MEE emissions standards for export qualification. Lebanese and Israeli processors leverage dairy-adjacent cold-chain infrastructure to compete in European and Middle Eastern markets. Tel Aviv anchors urban convenience purchasing normalization for snack pack configurations.
India
FSSAI labeling requirement evolution is opening institutional foodservice channels for imported tahini and roasted chickpea ingredients. Maharashtra and Gujarat industrial corridors concentrate cold-chain logistics investments serving urban supermarket expansion in Mumbai and Ahmedabad. Indian foodservice penetration represents the fastest-growing demand vector for international ingredient suppliers.
Hummus Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with HPP-enabled clean-label premiums separating from conventional acidified formulations competing on price. The market structures around three tiers: capital-intensive national distributors with automated cold-fill infrastructure, regional specialists anchored in sourcing networks, and dairy-adjacent processors leveraging existing refrigerated logistics. Dominant competitive moves include geographic expansion through co-manufacturing contracts and portfolio diversification into snack pack formats.
Within the capital-intensive national tier, Sabra Dipping Company and Cedar's Mediterranean Foods exemplify divergent scale strategies, with the former representing automated distribution density and the latter anchoring regional sourcing network dominance. Strauss Group occupies a position bridging dairy-adjacent cold-chain leverage with Middle Eastern market access. Among multinational packaged food conglomerates, The Kraft Heinz Company and PepsiCo sit within diversified snacking portfolios where hummus represents a plant-based adjacency rather than core category focus.
| Leading Market Players |
|---|
| Sabra Dipping Company |
| Cedar's Mediterranean Foods |
| The Kraft Heinz Company |
| PepsiCo |
| Strauss Group |
| Hope Foods |
| Bakkavor Group Plc |
| Boar's Head Brand |
| Haliburton International Foods |
| Others |
Supply Flow & Price Mechanics
Automated cold-fill packaging capacity utilization above 80% creates margin compression for mid-scale regional processors while anchoring price floors for national distributors serving US club stores and German discount retail. This scale divergence concentrates procurement power among Sabra Dipping Company and Strauss Group, forcing smaller players toward organic certification premiums or foodservice bulk contracts to escape commodity pricing.
Pricing Analysis
After-sales revenue from subscription-box repeat purchases and corporate catering contracts drives lifetime value differentiation for premium organic brands. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and cold-chain density. Cost compression in conventional acidified formulations is intensifying because Ethiopian tahini supply volatility feeds into input cost instability. US club store shoppers demonstrate highest price sensitivity, while health food retailers in Berlin and Hamburg absorb organic premiums with minimal volume elasticity.
Supply Chain Analysis
Inventory lead times for roasted chickpea inputs stretch 8-12 weeks during Sudanese and Ethiopian harvest windows, creating working capital pressure for processors without buffer stock financing. Supply concentrates in Israel, Lebanon, and the United States for tahini grinding and chickpea roasting capacity. Raw material dependencies rest on Ethiopian sesame seed, Turkish chickpea, and California lemon juice concentrate. Single-source vulnerability in East African tahini origins exposes margins to port disruption without hedge instruments. Distribution runs through refrigerated direct store delivery for US supermarkets and palletized cold-chain logistics for European retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in snack pack formats and Indian foodservice channels, where convenience purchasing normalization and FSSAI labeling evolution create executable niches for agile entrants.
For Market Incumbents: Fortify cold-chain density through automated packaging line investments in Bavaria and Baden-Württemberg, capturing EU Green Deal recycled content mandates that squeeze import-dependent competitors. Lock in Ethiopian tahini supply through forward contracting with Addis Ababa processors to neutralize sesame input cost volatility threatening margin stability. For New Entrants and Emerging Players: Differentiate on high-pressure processing capability for clean-label refrigerated SKUs targeting California and Pacific Northwest natural channels where HPP premiums command shelf space. Penetrate Indian foodservice through Mumbai and Ahmedabad institutional accounts, leveraging FSSAI compliance infrastructure as a go-to-market wedge against established exporters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-box direct-to-consumer brands with Tel Aviv or London urban convenience density. Long-term viability over the five-to-ten year horizon favors processors with backward integration into solar-powered roasting capacity aligning with China's MEE emissions standards. Signal to monitor: EU Green Deal packaging mandate enforcement velocity as margin compression trigger for import-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Installation | HPP capability separates clean-label premium positioning from conventional acidified competition in California natural channels. |
| Ethiopian Tahini Supply Contracting | Forward agreements with Addis Ababa processors neutralize sesame cost volatility and currency fluctuation exposure. |
| EU Green Deal Packaging Compliance | Recycled content certification unlocks German and French retailer shelf space from virgin-film-dependent importers. |
| Indian Foodservice Channel Development | FSSAI labeling alignment opens institutional procurement in Maharashtra and Gujarat corporate catering accounts. |
| Snack Pack Format Innovation | Single-serve configurations capture convenience-oriented purchasing normalization in London and New York urban supermarkets. |
Methodological Framework
A standing panel of tahini procurement directors, refrigerated logistics operators, health food retail category buyers, and foodservice supply managers provided ongoing calibration against secondary validation. Primary interviews combined with customs records, Nielsen retail audit data, FDA 21 CFR 114 filing databases, and EU Green Deal implementation tracking enabled bottom-up facility capacity modeling and top-down demand triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, form, ingredient certification tier, and distribution channel segmentation. CAGRs derived from facility-level production capacity expansion schedules and retailer shelf-space velocity metrics incorporated chickpea protein standardization trends and refrigerated plant-based spread placement growth as industry-specific forecast inputs.
Material uncertainties — Ethiopian port disruption, EU recycled content threshold acceleration, FSSAI labeling requirement evolution — sit outside the modeled envelope. Forecasts reflect documented assumptions about cold-chain capex cycles and organic certification transition timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Sugar Bags Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Instant Rice Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Morning Goods Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Global Popping Candy Market