
 Instant Rice Market | 2026-2036
Instant Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Rice Market Analysis
Market Context
Premium aromatic instant rice is shifting away from commodity white rice on pricing, packaging, and channel placement. Mars Incorporated leverages its retail distribution depth to sustain volume leadership in North American grocery. Tilda specializes in basmati-derived instant formats that command shelf space in European and Middle Eastern markets. LT Foods anchors its competitive position through backward integration into Indian paddy procurement and milling.
Product Definition and Segment Structure
Instant rice comprises dehydrated or parboiled grain that rehydrates within one to five minutes of boiling water contact, with moisture content typically below fourteen percent for ambient shelf stability. The product serves commercial kitchens and retail consumers seeking carbohydrate bases without conventional cooking duration. Quick cook rice and flavored rice occupy the fastest-expanding margin pools as households trade up from regular instant rice. Supermarkets dominate distribution channel throughput, though online retailers are capturing incremental share among subscription-oriented buyers in urban clusters.
Regulatory Environment and Outlook
The FDA governs instant rice under acidified and low-acid food regulations, while the USDA oversees grade standards and import quotas that shape competitive access. BIS certification requirements in India and EFSA labeling directives in Europe create divergent compliance costs for exporters. Stakeholders must monitor evolving mycotoxin thresholds and sustainability disclosure mandates that will determine which suppliers retain retail authorization.
Market Dynamics
Parboiling infrastructure concentration across Thailand and Vietnam is compressing supply lead times while FDA's updated Food Safety Modernization Act requirements force North American processors to upgrade dehydration and packaging lines.
Growth Catalysts
- Quick cook format adoption:Working households in the United States seek carbohydrate bases that rehydrate within one to five minutes, pulling volume from conventional instant rice.
- EFSA labeling alignment:European distributors now demand shelf-stable grain products with full supply chain traceability, opening premium placement for certified exporters.
- Parboiling technology diffusion:Southeast Asian export hubs leverage existing infrastructure to support volume output for commercial kitchen procurement.
Market Restraints
- Paddy price volatility:Input cost swings for raw grain constrain margin predictability for processors lacking backward integration into Indian procurement networks.
- Supply concentration risk:Processing gravity centers on Thai and Vietnamese parboiling facilities, creating vulnerability to regional climate disruptions or port congestion.
- USDA import quota friction:Grade standards and volume restrictions limit competitive access for new entrants seeking North American grocery authorization.
Strategic Opportunities
- Subscription channel expansion:Online retailers capture incremental share among urban household clusters seeking recurring delivery of quick cook formats.
- FSSAI harmonization:India's food safety certification alignment with export standards reduces compliance duplication for processors targeting Middle Eastern markets.
- Flavored rice white space:Households trading up from commodity instant rice create margin pools for aromatic basmati-derived formats in European retail.
Industry Challenges
- Mycotoxin testing capacity:Evolving FDA thresholds for aflatoxin and fumonisin require processors to expand in-house laboratory infrastructure or absorb third-party validation costs.
- Legacy equipment retrofitting:Dehydration lines designed for fourteen percent moisture targets must upgrade to meet stricter ambient shelf stability specifications under modernized food safety rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Rice Market |
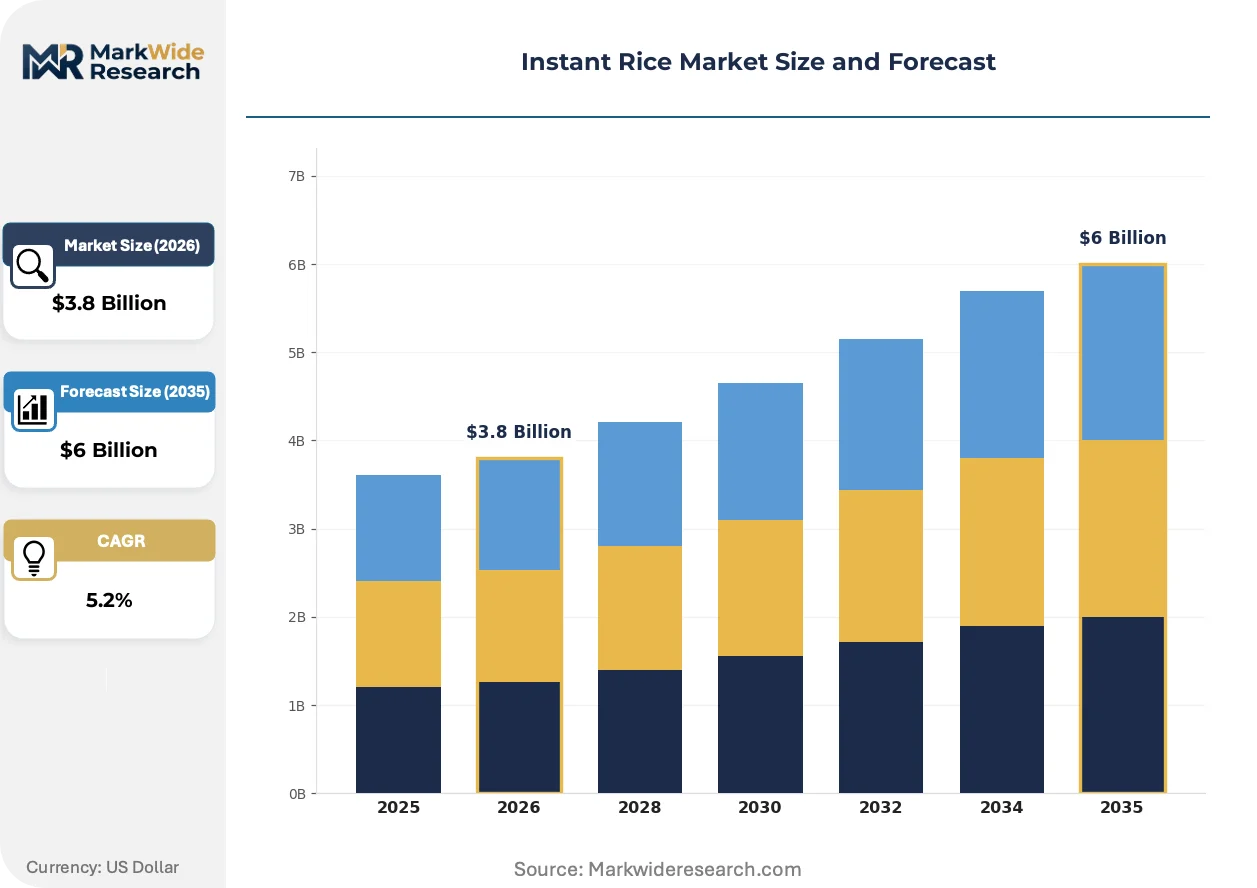
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Instant Rice, Quick Cook Rice, Flavored Rice, Organic Rice End User: Households, Food Service, Institutional, Restaurants Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Application: Ready-to-Eat Meals, Side Dishes, Meal Kits, Snacks |
| Companies Covered | Riviana Foods, Mars Incorporated, Tilda, LT Foods, Conagra Brands, Olam International, Riceland Foods, SunRice, Veetee Rice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Rice Market Emerging Trajectories
Processing automation and regulatory disclosure mandates are compressing the gap between commodity and premium instant rice, while demand signals from working households reshape product format priorities.
Advanced parboiling systems with real-time moisture monitoring are consolidating quality consistency across export-grade facilities. Commercial kitchen buyers in the United States adopt these formats at accelerating pace for back-of-house efficiency. The technology is consolidating mid-tier processors into fewer, higher-capability suppliers capable of meeting simultaneous FDA and EFSA requirements.
CSRD sustainability disclosure mandates in Europe now extend to imported grain products, requiring instant rice suppliers to document water usage and carbon intensity across Thai and Vietnamese processing facilities. Industrial consequence includes mandatory third-party verification for shelf-stable grain categories. Premium aromatic formats face the steepest compliance burden, with several exporters restructuring supply chains to retain European retail authorization.
Urban household purchasing has compressed switching cycles between instant rice brands as subscription models reduce price sensitivity. North American online retailers displace traditional supermarket bulk purchasing for time-constrained working families. This pattern is most visible in coastal United States cities where delivery density supports free-shipping thresholds for quick cook and flavored rice varieties.
Instant Rice Market Segmentation
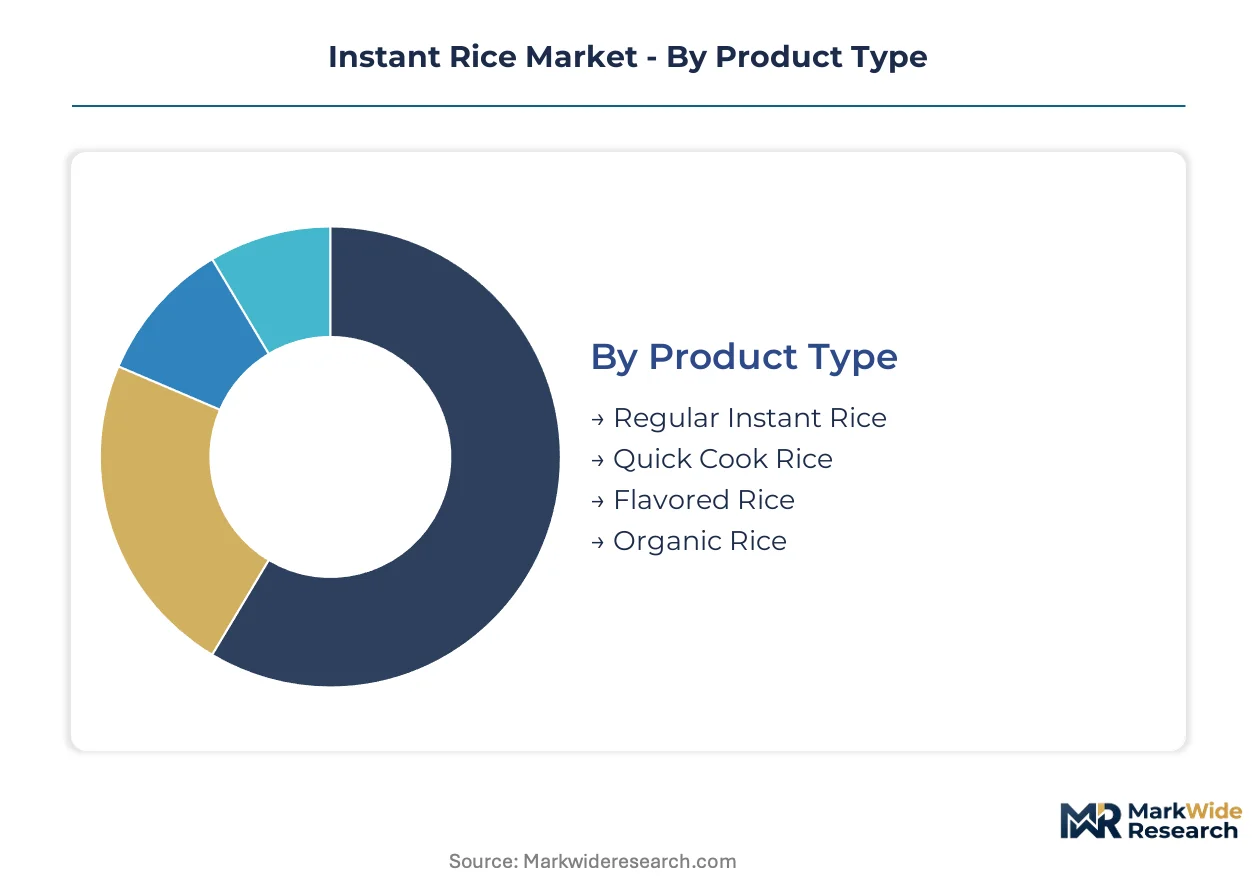
Instant rice segmentation reveals how processing technology, procurement patterns, and channel economics partition value capture across the supply chain. Manufacturers configure production lines around moisture targets and rehydration speeds that align with distinct end-use requirements and price thresholds.
Product Type:
Customization intensity varies sharply across this category, from commodity bulk formats to precision-engineered aromatic derivatives with controlled starch gelatinization profiles.
- Regular Instant Rice:Parboiled or dehydrated white rice with standard rehydration windows of three to five minutes serves price-sensitive institutional procurement in Southeast Asian export corridors. USDA grade standards and moisture specifications below fourteen percent dominate contract terms for North American import volumes.
- Quick Cook Rice:Pre-cooked and flash-dried grains achieve one-minute rehydration through modified starch structures. Working households in United States coastal cities pull disproportionate volume through subscription channels, displacing conventional formats in urban grocery.
- Flavored Rice:Seasoning integration during dehydration creates ambient-stable meal bases targeting European retail authorization under EFSA labeling directives.
- Organic Rice:Certified paddy sourcing with full traceability documentation commands premium placement in specialty retail channels.
Most installed capacity flows through Regular Instant Rice. Expansion is steepest in Quick Cook Rice.
End User:
Volume concentration shifts toward procurement entities with back-of-house efficiency mandates and inventory turnover requirements.
- Households:Time-constrained consumers in United States metropolitan clusters prioritize rehydration speed over per-unit cost, driving subscription adoption and online retailer share capture.
- Food Service:Commercial kitchen operators across institutional cafeterias and chain restaurants specify quick cook formats to reduce holding equipment requirements and labor allocation.
- Institutional:School districts and healthcare facilities in Thailand and Vietnam source parboiled bulk formats through centralized tender processes with BIS or FSSAI certification requirements.
- Restaurants:Independent operators and regional chains balance portion consistency against storage constraints, favoring flavored rice for menu differentiation.
Food Service channels the largest procurement volumes. Households are climbing the fastest as subscription density reshapes purchasing patterns.
Distribution Channel:
Physical retail throughput still dominates, though digital infrastructure is compressing delivery lead times for recurring purchase models.
- Supermarkets:Grocery authorization remains the primary path to household penetration, with shelf placement fees and promotional calendars shaping manufacturer margin structures across North American retail.
- Online Retailers:Urban delivery density in United States coastal markets supports free-shipping thresholds that accelerate quick cook and flavored rice adoption among working families.
- Convenience Stores:Single-serve and small-format packaging targets immediate consumption occasions with limited storage requirements.
- Specialty Stores:Ethnic grocery and organic retail channels in European cities capture aromatic basmati-derived formats with full supply chain traceability.
Supermarkets maintain the broadest geographic coverage. Online Retailers are gaining share fastest in subscription-oriented urban clusters.
Application:
Formulation requirements diverge based on whether rice serves as a neutral substrate or a complete flavor-delivery vehicle.
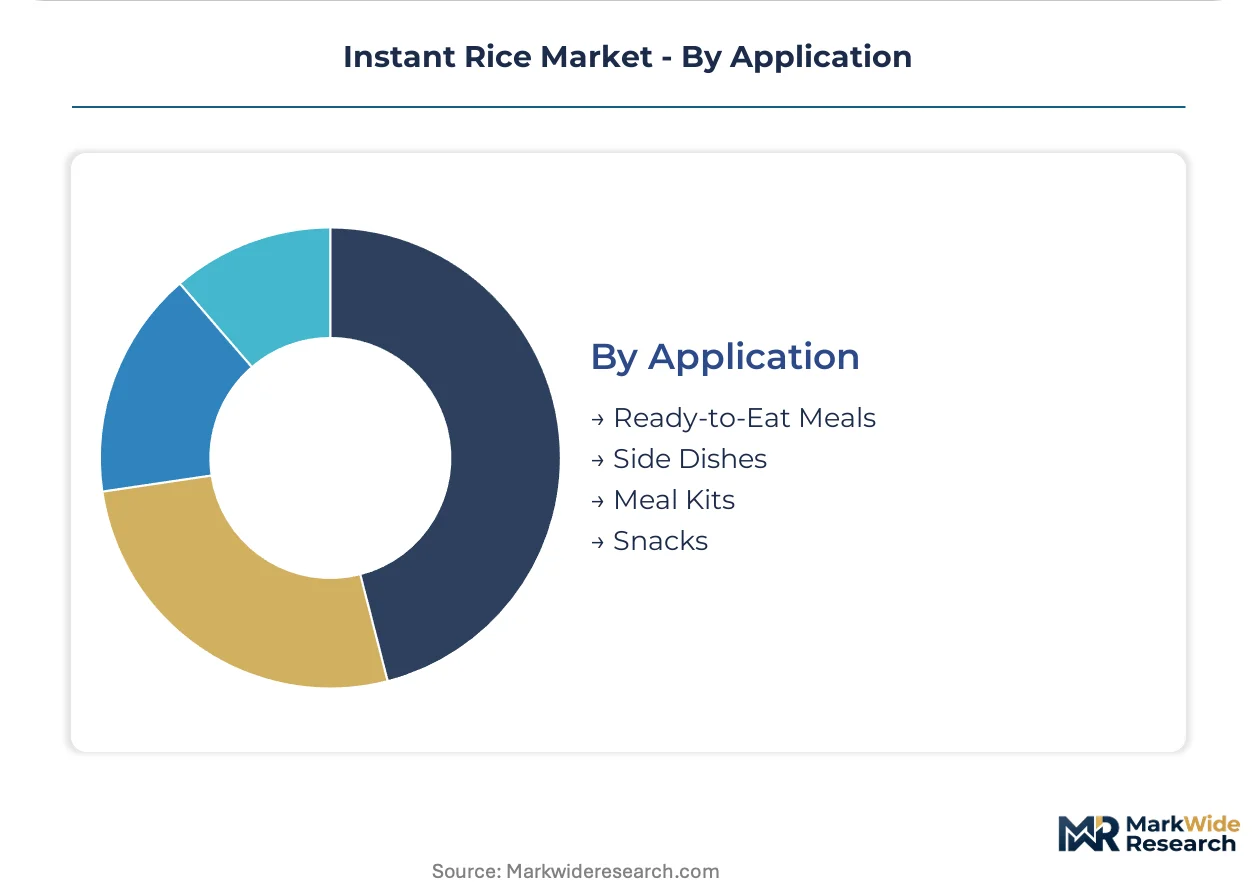
- Ready-to-Eat Meals:Shelf-stable rice bowls and microwaveable trays require precise moisture control and retort compatibility, with FDA acidified food regulations governing formulation.
- Side Dishes:Plain and lightly seasoned formats dominate institutional and food service procurement, with volume contracts tied to USDA grade specifications.
- Meal Kits:Component rice sachets with synchronized cook times represent the fastest-expanding placement for quick cook technology in United States subscription commerce.
- Snacks:Puffed and extruded rice formats leverage dehydration infrastructure for crispy texture profiles in Asian convenience retail.
Side Dishes anchor the largest production volumes. Meal Kits are expanding most quickly as kit assembly platforms scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Vietnamese parboiling technicians anchor the largest processing workforce concentration, while FDA-certified dehydration specialists cluster in Arkansas and California facilities serving North American grocery authorization.
United States
Working households in coastal metropolitan areas drive quick cook format adoption through subscription channels. The FDA's updated Food Safety Modernization Act forces dehydration line upgrades for ambient shelf stability compliance. Arkansas processing facilities concentrate parboiling infrastructure serving institutional procurement contracts.
Thailand
Export-oriented parboiling facilities supply volume contracts to European distributors seeking EFSA-aligned traceability documentation. The country's national food safety regulator enforces mycotoxin thresholds that determine retail authorization eligibility. Bangkok-adjacent processing clusters leverage real-time moisture monitoring systems for quality consistency.
Vietnam
Mekong Delta paddy procurement networks feed concentrated parboiling capacity targeting commercial kitchen buyers. BIS certification alignment for Indian export standards reduces compliance duplication for Middle Eastern market access. Ho Chi Minh City logistics hubs compress supply lead times for bulk institutional tenders.
India
Backward integration into paddy procurement and milling supports competitive positioning for aromatic basmati-derived formats. FSSAI harmonization with export standards streamlines certification for processors targeting Gulf Cooperation Council markets. Punjab and Haryana agricultural belts concentrate organic rice cultivation for specialty retail channels.
United Kingdom
Urban household clusters in London and Southeast England accelerate online retailer share capture for flavored rice varieties. EFSA labeling directives and CSRD sustainability disclosure mandates reshape supplier qualification requirements. Manchester distribution centers handle import volumes from Southeast Asian parboiling facilities.
Instant Rice Market Vendor Landscape
Capital-heavy producers compete with asset-light brand architects across tiered market positions. Mars Incorporated anchors retail distribution depth in North American grocery, while LT Foods exemplifies backward integration into Indian paddy procurement networks. The vendor base fragments across commodity bulk suppliers, premium aromatic specialists, and quick cook technology licensors. Dominant competitive moves include dehydration line automation investments and EFSA certification acquisition for European retail authorization.
Within the premium aromatic tier, Tilda occupies a position exemplifying basmati-derived format specialization for European and Middle Eastern markets. Riviana Foods and Conagra Brands represent scale-driven North American grocery authorization strategies, while SunRice anchors Asia-Pacific export corridor positioning. Olam International and Riceland Foods sit within diversified agricultural commodity portfolios that include parboiled grain processing capabilities.
| Leading Market Players |
|---|
| Riviana Foods |
| Mars Incorporated |
| Tilda |
| LT Foods |
| Conagra Brands |
| Olam International |
| Riceland Foods |
| SunRice |
| Veetee Rice |
| Others |
Supply Flow & Price Mechanics
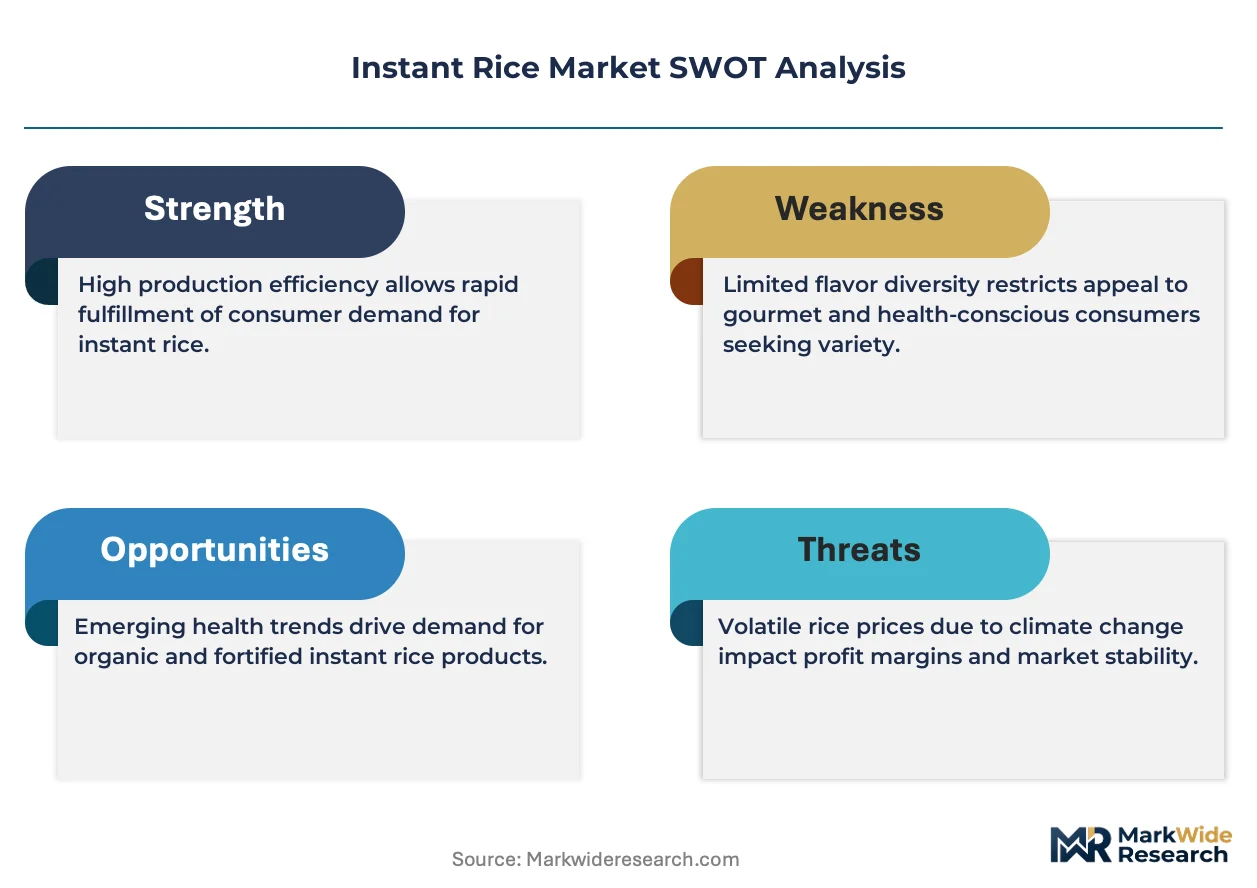
CSRD sustainability disclosure mandates gate qualified supply and premium-tier pricing access, forcing instant rice exporters to absorb third-party verification costs or surrender European retail authorization to certified competitors.
Pricing Analysis
Subscription bundling versus transactional unbundling splits the pricing architecture. Three-tier pricing structure across premium aromatic, standard parboiled, and economy bulk levels dominates contract negotiations. Price differentiation hinges on EFSA certification tier and backward integration into Indian paddy procurement. Pricing pressure stems from paddy cost volatility squeezing processors lacking captive supply. Institutional buyers exhibit highest price sensitivity; subscription-oriented urban households show lowest.
Supply Chain Analysis
Paddy supply rests on Thai and Vietnamese Mekong Delta procurement networks, with Indian Punjab and Haryana belts feeding aromatic basmati streams. Parboiling infrastructure draws from Thailand, Vietnam, and Arkansas processing clusters. Mycotoxin testing capacity constraints and climate disruption exposure concentrate risk. Distribution runs through supermarket grocery authorization with online retailers capturing incremental subscription volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in quick cook format premiums and dehydration automation cost-down, rewarding processors that consolidate parboiling scale.
For Market Incumbents: To counter subscription channel displacement by online retailers, Mars Incorporated and LT Foods should deepen backward integration into Indian paddy procurement and accelerate FDA-certified dehydration line automation. EFSA certification acquisition for European retail authorization remains essential for premium-tier defense. For New Entrants and Emerging Players: Quick cook technology licensing offers entry wedge into United States coastal urban clusters where subscription density supports free-shipping economics. White-space targets include flavored rice meal kit component supply and BIS-aligned export corridors into Middle Eastern procurement. Direct-to-foodservice positioning bypasses supermarket shelf placement fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier parboiling specialists with unexploited EFSA certification potential. Five-to-ten year viability favors processors with Thai or Vietnamese infrastructure plus Indian aromatic sourcing integration. Watch FDA mycotoxin threshold tightening as margin compression trigger for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dehydration Line Automation | Arkansas and California facilities reduce labor allocation while meeting FDA Food Safety Modernization Act moisture targets. |
| EFSA Certification Acquisition | European retail authorization requires full supply chain traceability documentation from Thai and Vietnamese processing facilities. |
| Backward Integration into Paddy Procurement | Indian Punjab and Haryana belt control insulates margin from raw grain price volatility. |
| Subscription Channel Expansion | United States coastal urban delivery density supports recurring revenue models for quick cook formats. |
| Quick Cook Technology Licensing | Flash-dried grain intellectual property unlocks food service procurement contracts with back-of-house efficiency mandates. |
Methodological Framework
Bottom-up household and food service procurement modeling reconciled against top-down parboiling capacity tracking forms the analytical core. Primary interviews with category buyers at North American grocery chains, procurement leads at institutional cafeteria operators, plant managers at Thai and Vietnamese export facilities, and regulatory affairs specialists at FDA-certified dehydration sites combined with secondary validation from USDA grade standard filings, EFSA guidance documents, customs import records, and BIS certification registries.
Input-output matrices map paddy procurement volumes through parboiling and dehydration stages to end-use consumption across product type, end user, distribution channel, and application dimensions. CAGRs derive from segment-level volume trajectories calibrated against macroeconomic indicators and regulatory compliance cost assumptions. Forecast inputs include working household time-constraint indices and commercial kitchen labor cost trends.
The model holds under stable FDA and EFSA regulatory thresholds; deviation in mycotoxin limits or sustainability disclosure mandates would shift competitive positioning. Forecasts reflect documented assumptions about parboiling technology diffusion and subscription commerce penetration. Paddy price volatility, climate disruption in Southeast Asian export corridors, and import quota friction warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Pasta Market
Packaged Foods
Canned Soup Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Peanut Butter Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Cookie Butter Spread Market