
 Low Calorie Noodles Market | 2026-2036
Low Calorie Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Noodles Market Foresight
Plant-based protein fortification is fragmenting traditional noodle formulation architectures. Nissin Foods leverages its R&D infrastructure to develop reduced-calorie platforms that retain texture parity with conventional wheat noodles. Nongshim anchors its competitive stance through Korean domestic market dominance in instant-format health-positioned products. Nestle competes via global distribution scale that extends low-calorie SKUs into mainstream retail channels previously reserved for standard offerings.
Low calorie noodles denote carbohydrate-reduced or calorie-diluted pasta substitutes typically manufactured from konjac glucomannan, vegetable extrusions, or modified starch matrices with caloric densities below 50 kcal per 100 gram serving, designed to replicate the sensory properties of wheat-based noodles while supporting dietary restriction protocols. Shirataki variants sustain the largest volume position due to established Asian supply chains and minimal ingredient complexity, though zucchini-based fresh formats represent the fastest-growing structural segment as cold-chain distribution expands. Online Retail channels concentrate margin pools through subscription models and direct-to-consumer nutrition branding that bypasses conventional slotting fee structures.
FDA nutrition labeling requirements and USDA organic certification standards shape product claim substantiation and market access thresholds for US-bound manufacturers. EFSA health claim regulations and EU Green Deal sustainability reporting obligations under CSRD impose parallel compliance burdens on European market participants. Stakeholders must monitor evolving front-of-pack labeling mandates and carbon-accounting disclosures that will determine which formulation technologies achieve scalable commercial authorization.
Market Dynamics
Protein fortification technology and konjac-root supply chain concentration are restructuring competitive positioning across formulation tiers, forcing manufacturers to rebuild textural parity at scale while navigating divergent regulatory claim substantiation requirements.
Growth Catalysts
- Fitness Enthusiast Segment Expansion:Protein-fortified shirataki variants attract performance-oriented consumers seeking carbohydrate restriction without sacrificing amino acid density in post-workout meal windows.
- EU F-Gas Regulation Compliance:Industrial processing standard upgrades across European manufacturing facilities accelerate capital deployment into energy-efficient extrusion and drying technologies.
- Konjac Supply Chain Maturation:Japanese agricultural cooperatives and processing clusters anchor raw material availability, reducing input volatility for glucomannan-based formulations.
Market Restraints
- Input Cost Volatility:Konjac root harvest fluctuations in Gunma and Nagano prefectures create price instability for glucomannan concentrate, compressing margin predictability.
- Technical Texture Limitations:Current enzymatic modification protocols fail to replicate wheat noodle elasticity in hot broth applications, restricting format versatility.
- Regulatory Claim Friction:EFSA health claim authorization delays and FDA substantiation requirements block rapid front-of-pack positioning for weight management benefits.
Strategic Opportunities
- Subscription Channel Penetration:Direct-to-consumer nutrition branding bypasses conventional retail slotting fees, capturing recurring revenue pools through personalized meal plan integration.
- Zucchini-Based Fresh Format Expansion:Cold-chain distribution infrastructure improvements unlock refrigerated vegetable noodle segments in North American and European urban markets.
- USDA Organic Certification Tailwinds:Premium positioning through organic credentialing attracts clean-label consumers willing to absorb price premiums for verified ingredient sourcing.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise bridging hydrocolloid chemistry and sensory science remains concentrated in Japanese and Korean research institutes, limiting Western R&D velocity.
- Dual Certification Timeline Compression:Simultaneous FDA nutrition label compliance and EU organic equivalence negotiations extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Noodles Market |
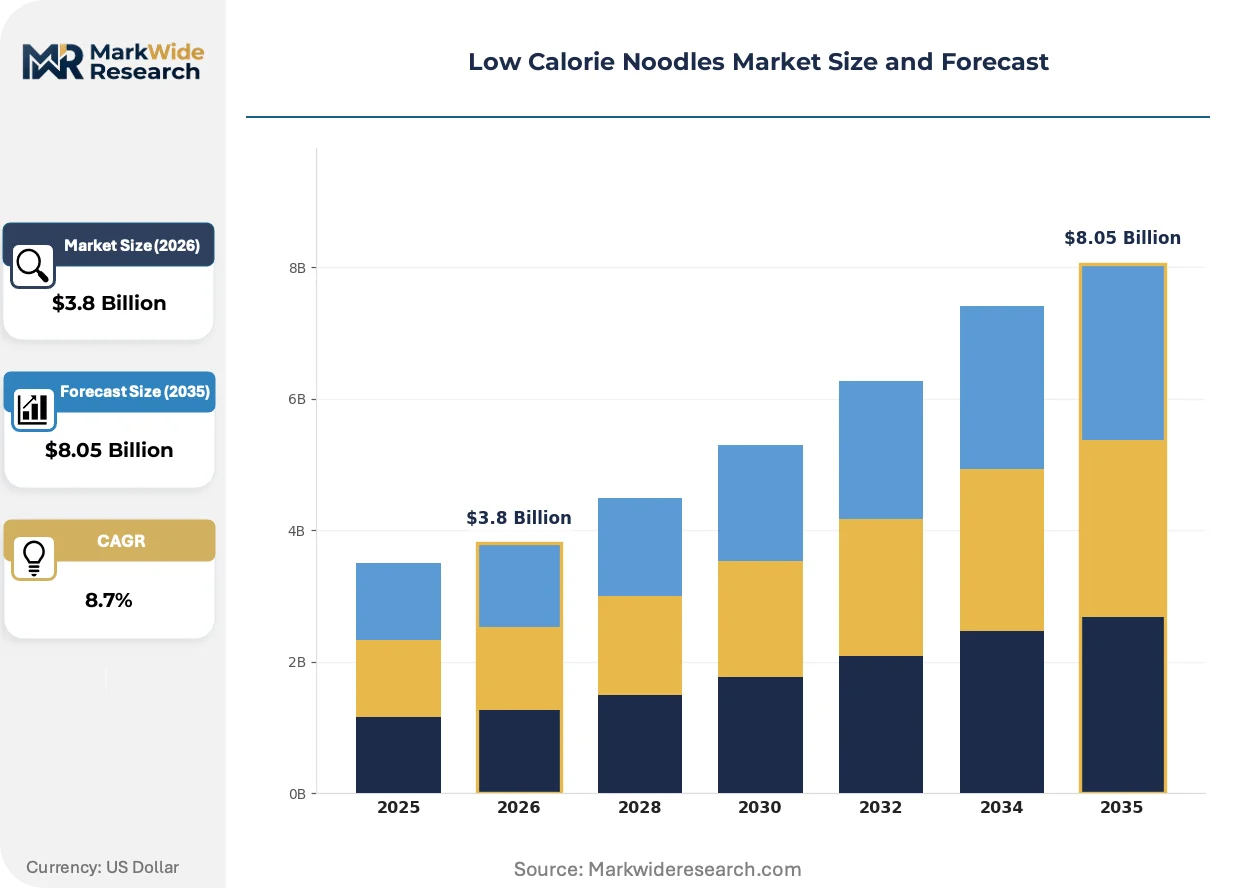
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirataki, Zucchini, Soba, Rice End User: Health-Conscious Consumers, Fitness Enthusiasts, Weight Watchers, Vegans Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Packaging Type: Plastic Bags, Boxes, Single-Serve Cups, Vacuum-Sealed Packs |
| Companies Covered | Nissin Foods, Nongshim, Samyang Foods, Nestle, Indofood Sukses Makmur, Shanghai Lamowang Food Co. Ltd., Beijing Shipuller Co., Ltd., Genki USA, Inc., Wonder Noodles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Noodles Market Shifts & Advancements
Extrusion technology advances and regulatory disclosure mandates are compressing traditional formulation-development timelines while opening white space in personalized nutrition and sustainability-verified product tiers.
Enzymatic hydrolysis of konjac glucomannan is rendering obsolete conventional alkali-processing methods that required extended soaking periods and produced characteristic odor compounds. Fitness-oriented meal kit providers in California and Texas are adopting these modified starches at accelerated procurement cycles. The structural consequence is collapsing minimum order quantities for texture-optimized shirataki, enabling smaller brand entry.
CSRD carbon-accounting disclosures under the EU Green Deal are forcing manufacturing facility upgrades across Italian and German production sites. Scope 3 emission tracking requirements now extend to agricultural input sourcing from Japanese konjac cooperatives. European retail buyers are prioritizing suppliers with verified supply chain transparency documentation.
Gym chains and corporate wellness programs are consolidating procurement through centralized nutrition coordinators rather than individual consumer retail purchases. This buyer concentration is compressing switching cycles and demanding volume-tiered pricing structures with guaranteed texture consistency specifications. The shift is most visible in Australian and UK metropolitan markets where employer-subsidized healthy meal programs expand.
Low Calorie Noodles Market Segmentation
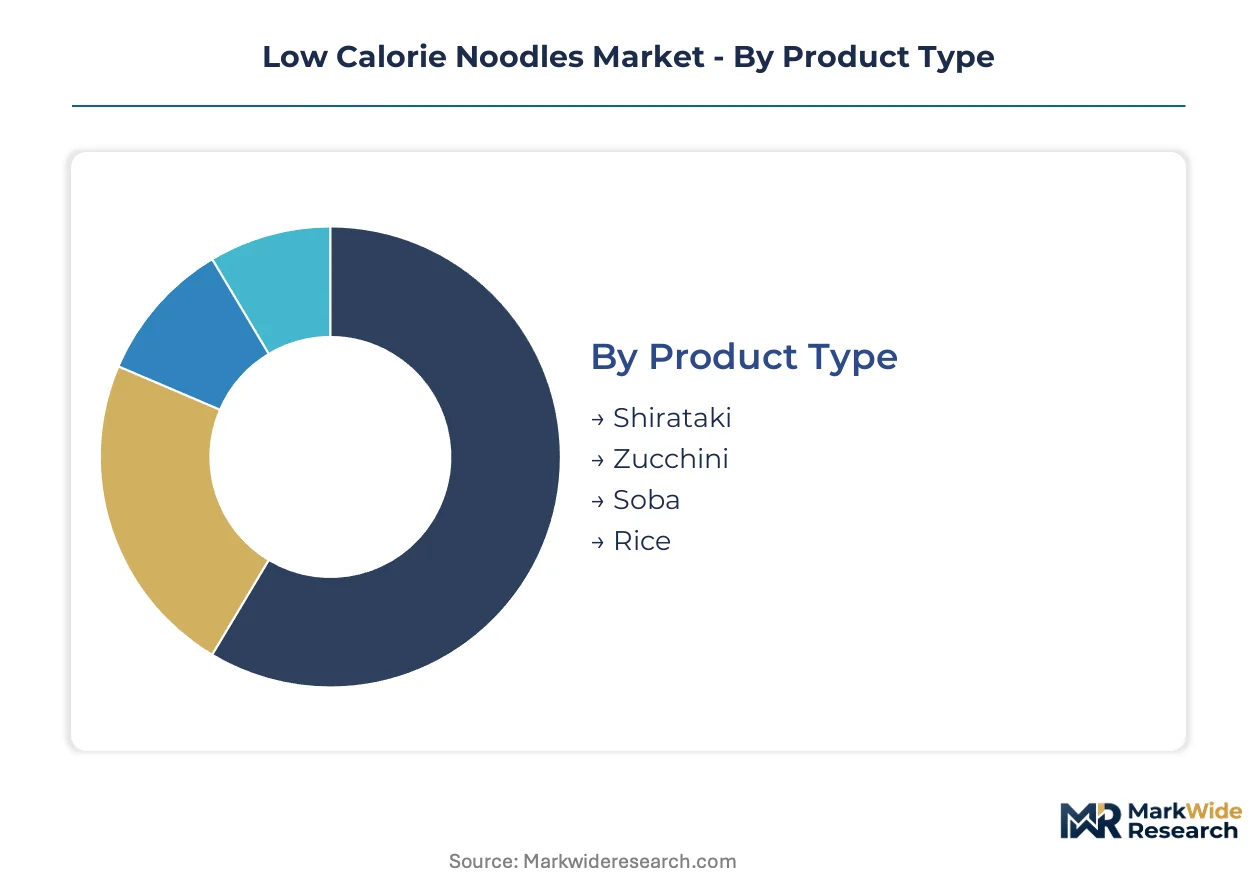
Segmentation in low calorie noodles determines formulation priorities, channel investment, and regulatory compliance pathways. Each dimension reveals distinct margin structures and buyer concentration patterns that shape competitive resource allocation.
Product Type:
After-sales intensity varies sharply across formats, with fresh variants demanding cold-chain service infrastructure while shelf-stable formats minimize post-purchase touchpoints.
- Shirataki:Konjac glucomannan-based noodles with near-zero caloric density require alkaline pre-treatment to neutralize characteristic odors. Japanese agricultural cooperatives in Gunma and Nagano prefectures anchor supply, though enzymatic hydrolysis advances are collapsing traditional processing timelines. Demand concentrates in Japanese domestic markets and diaspora communities seeking authentic texture profiles.
- Zucchini:Fresh vegetable extrusions deliver moisture-rich alternatives with 15-35 kcal per 100 gram serving. Cold-chain distribution expansion in California and Texas metro corridors drives procurement acceleration among meal kit providers. The format's perishability creates service intensity through temperature-controlled last-mile logistics.
- Soba:Buckwheat-based formulations with moderate caloric reduction retain traditional Japanese culinary applications.
- Rice:Modified starch matrices from konjac or vegetable bases replicate rice noodle sensory properties for Southeast Asian recipe adaptation.
Shirataki holds the largest share; momentum sits with zucchini as refrigerated distribution infrastructure matures.
End User:
Cost tier stratification separates premium-positioned nutrition coaching integrations from mass-market self-directed purchases.
- Health-Conscious Consumers:Broad demographic seeking general wellness optimization through carbohydrate reduction without strict dietary protocols. Supermarket placement and familiar flavor profiles drive trial conversion in suburban retail corridors.
- Fitness Enthusiasts:Performance-oriented buyers prioritizing protein density and post-workout glycemic control. California and Texas gym chains consolidate procurement through centralized nutrition coordinators, compressing vendor switching cycles and demanding batch consistency guarantees.
- Weight Watchers:Calorie-tracking adherents requiring precise portion control and transparent nutritional labeling.
- Vegans:Plant-based credential seekers verifying ingredient matrices exclude animal derivatives across processing aids and fortification inputs.
Fitness enthusiasts command premium pricing tiers; health-conscious consumers deliver volume scale through mainstream retail penetration.
Distribution Channel:
Application context determines margin capture, with institutional wellness programs extracting service-level agreements distinct from individual consumer transactions.
- Online Retail:Direct-to-consumer subscription models bypass conventional slotting fees while capturing recurring revenue through personalized meal plan integration. Australian and UK corporate wellness programs increasingly route procurement through centralized nutrition coordinators rather than individual retail purchases.
- Supermarkets:Mass-market access requires trade spend allocation and shelf placement negotiation, with texture consistency specifications enforced through supplier quality audits.
- Health Food Stores:Curated assortment environments favor organic certification and clean-label positioning with educated staff recommendation influence.
- Specialty Stores:Asian grocery channels sustain authentic shirataki demand through established importer relationships and culturally specific preparation guidance.
Online retail captures margin expansion; supermarkets anchor volume throughput for format standardization.
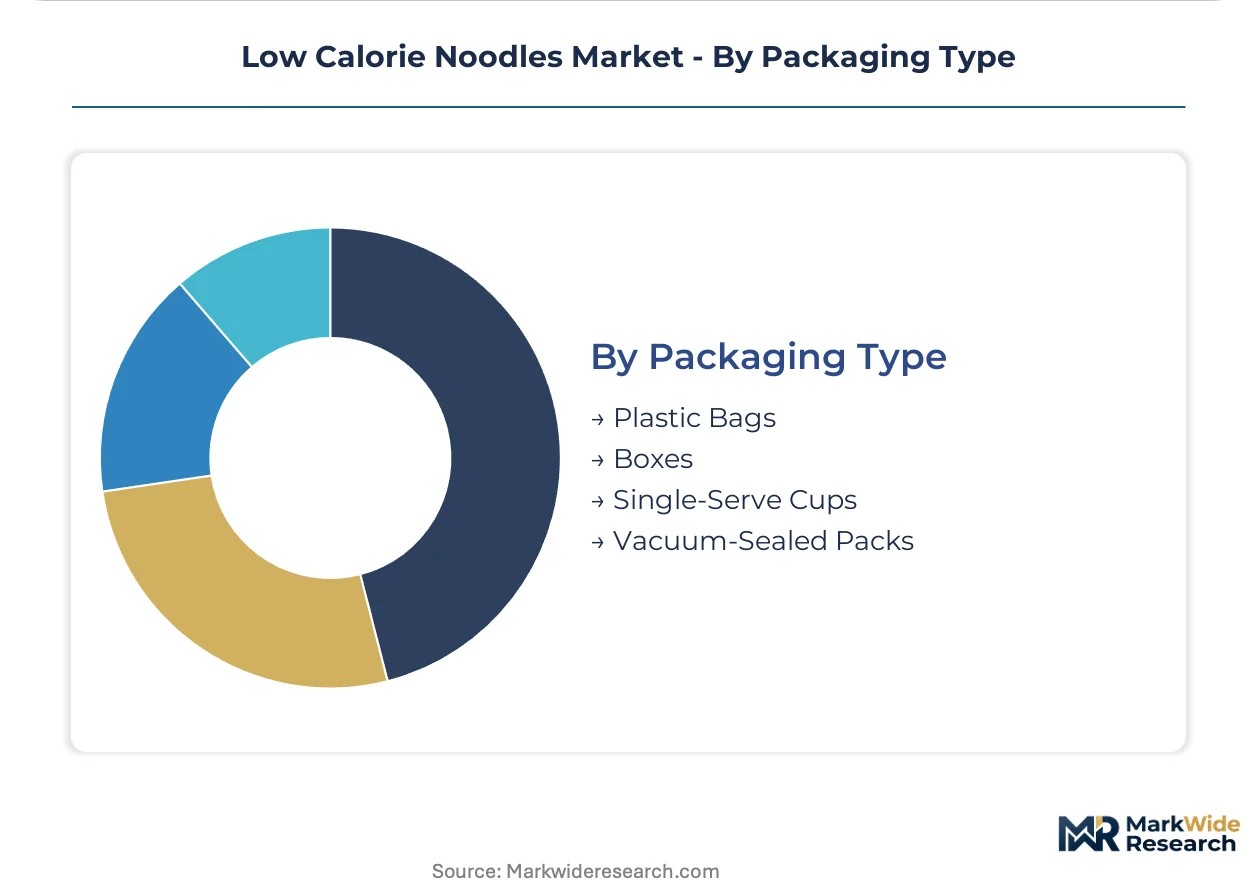
Packaging Type:
Supply concentration in Japanese and Korean converter facilities shapes format availability and minimum order thresholds for Western brand entrants.
- Plastic Bags:Flexible primary packaging for shelf-stable shirataki variants enables cost-efficient ocean freight consolidation from Japanese processing clusters.
- Boxes:Rigid secondary protection for multi-serve formats supports retail shelf presentation and stacking logistics in supermarket environments.
- Single-Serve Cups:Convenience-oriented portions target foodservice and workplace meal replacement contexts with minimal preparation infrastructure.
- Vacuum-Sealed Packs:Extended shelf-life preservation for fresh zucchini and vegetable noodles through oxygen exclusion, demanding precise seal integrity specifications.
Plastic bags dominate current volume; vacuum-sealed formats are climbing fastest as fresh segment expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese konjac-root exporters supply manufacturing clusters across California, Texas, and European processing facilities. Trade corridors from Gunma and Nagano prefectures feed glucomannan concentrate to North American and European formulation plants. Australian and UK corporate wellness programs now consolidate procurement through centralized nutrition coordinators rather than individual retail channels.
United States
California and Texas metro corridors drive zucchini-based fresh noodle adoption through meal kit provider procurement acceleration. FDA nutrition labeling requirements and USDA organic certification standards shape product claim substantiation for US-bound manufacturers. Los Angeles and Austin cold-chain distribution hubs enable refrigerated vegetable noodle segments to reach urban health-conscious consumers.
Japan
Domestic shirataki consumption anchors category development through established konjac-root supply chains in Gunma and Nagano prefectures. METI industrial standards govern processing facility compliance for glucomannan extraction and enzymatic hydrolysis advances. Tokyo and Osaka metropolitan clusters sustain authentic texture profile demand while agricultural cooperatives reduce input volatility for concentrate supply.
Germany
EU F-Gas Regulation compliance accelerates capital deployment into energy-efficient extrusion and drying technologies across manufacturing facilities. EFSA health claim regulations and CSRD carbon-accounting disclosures impose parallel compliance burdens on European market participants. Bavarian and North Rhine-Westphalian processing sites upgrade industrial standards to meet Scope 3 emission tracking requirements extending to Japanese agricultural inputs.
Australia
Employer-subsidized healthy meal programs expand across metropolitan markets, consolidating procurement through centralized nutrition coordinators. TGA food standards govern nutritional labeling and health claim substantiation for low-calorie noodle imports. Sydney and Melbourne gym chains demand volume-tiered pricing structures with guaranteed texture consistency specifications for protein-fortified variants.
South Korea
Korean domestic market dominance in instant-format health-positioned products anchors competitive positioning for reduced-calorie platforms. MFDS food safety standards regulate konjac-based formulation claims and fortification ingredient approvals. Seoul and Busan manufacturing clusters develop protein-fortified shirataki variants targeting performance-oriented consumers in post-workout meal windows.
Low Calorie Noodles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Supermarket slotting fee negotiations favor scale-driven incumbents with trade spend allocation capacity, while direct-to-consumer subscription models enable smaller brands to bypass conventional retail gatekeeping. Three archetypes dominate: multinational food conglomerates leveraging global distribution infrastructure, Asian instant noodle specialists with R&D-intensive formulation platforms, and regional vegetable noodle specialists exploiting cold-chain proximity. Competitive moves concentrate on portfolio diversification into protein-fortified variants and strategic partnerships with corporate wellness program coordinators.
Within the multinational tier, Nestle occupies a position exemplifying global distribution scale that extends low-calorie SKUs into mainstream retail channels. Nissin Foods and Nongshim represent the Asian specialist archetype, with the former anchoring R&D infrastructure for texture parity development and the latter exemplifying domestic market dominance in health-positioned instant formats. These three companies illustrate how competitive positioning fragments across scale-driven channel control versus formulation-driven product specialization.
| Leading Market Players |
|---|
| Nissin Foods |
| Nongshim |
| Samyang Foods |
| Nestle |
| Indofood Sukses Makmur |
| Shanghai Lamowang Food Co. Ltd. |
| Beijing Shipuller Co., Ltd. |
| Genki USA, Inc. |
| Wonder Noodles |
| Others |
Supply & Pricing Matrix
Overcapacity in European extrusion facilities following EU F-Gas Regulation compliance investments is compressing contract pricing for glucomannan-based formulations while simultaneously elevating premiums for enzymatically modified texture-optimized variants. Japanese agricultural cooperatives in Gunma and Nagano prefectures exploit this utilization divergence to tier konjac root concentrate pricing by processing technology generation.
Pricing Analysis
Alkali-processing methods command economy-tier positioning as enzymatic hydrolysis advances render them obsolete, while next-generation protein-fortified variants capture premium positioning through fitness enthusiast procurement consolidation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Cost compression in conventional shirataki is intensifying because California meal kit providers are collapsing minimum order quantities. Health-conscious supermarket consumers exhibit highest price sensitivity; corporate wellness program coordinators demonstrate lowest sensitivity due to batch consistency guarantees.
Supply Chain Analysis
No export-control regimes currently restrict konjac glucomannan flows, though METI industrial standards and FDA nutrition labeling requirements create de facto regulatory friction for cross-border concentrate movement. Supply concentrates in Japan, South Korea, and China, with Japanese agricultural cooperatives anchoring raw material availability. Formulation draws from konjac root harvests, modified starch matrices, and protein fortification inputs. Single-source vulnerability concentrates in Gunma and Nagano prefecture harvest fluctuations. Distribution runs through direct-to-consumer subscription channels and refrigerated cold-chain logistics for fresh formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based meal plan integration represents the fastest-expanding recurring-revenue layer, outpacing hardware-equivalent shelf-stable format sales as Australian and UK corporate wellness programs consolidate procurement through centralized nutrition coordinators.
For Market Incumbents: Insulate texture-optimized formulation expertise through exclusive partnerships with Japanese enzymatic hydrolysis research institutes before emerging vegetable-noodle specialists achieve parity. Prioritize backward integration into konjac root cultivation in Nagano prefecture to neutralize harvest volatility threats. Secure USDA organic certification for premium-tier positioning against clean-label competitors. For New Entrants and Emerging Players: Zucchini-based fresh formats in Texas and California metro corridors represent the most penetrable entry point given cold-chain infrastructure maturation and meal kit provider procurement acceleration. Protein-fortified shirataki variants for gym chain corporate accounts offer secondary white-space access. Pursue direct-to-consumer subscription launch with personalized nutrition coaching attach to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic modification processing facilities as EU F-Gas Regulation compliance mandates energy-efficient extrusion upgrades. Acquisition targets should exhibit captive konjac supply relationships or proprietary texture-optimization IP. Monitor EFSA health claim authorization timelines as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Platform Development | Nissin Foods and Korean research institutes anchor proprietary texture parity advances that collapse traditional processing timelines. |
| Direct-to-Consumer Subscription Launch | Wonder Noodles and Genki USA bypass supermarket slotting fees through personalized meal plan integration with recurring revenue capture. |
| USDA Organic Certification Investment | Clean-label positioning attracts premium absorption from health-conscious consumers verifying ingredient sourcing protocols. |
| Cold-Chain Distribution Partnership | California and Texas refrigerated logistics expansion enables zucchini-based fresh format penetration into urban metro corridors. |
| Corporate Wellness Program Integration | Australian and UK employer-subsidized healthy meal programs consolidate procurement through centralized nutrition coordinators demanding volume-tiered pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance, EFSA health claim databases, METI industrial standards filings, and Japanese agricultural cooperative harvest reports. Interviews with food technology R&D directors, corporate wellness program procurement coordinators, cold-chain logistics operators, and konjac root processing facility managers informed formulation and distribution dynamics. Secondary validation drew from customs trade data, supermarket scanner databases, and meal kit provider procurement disclosures. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs incorporate product type segmentation across shirataki, zucchini, soba, and rice variants; end-user stratification by fitness enthusiasts, health-conscious consumers, weight watchers, and vegans; and distribution channel dynamics spanning online retail, supermarkets, health food stores, and specialty Asian grocery channels. CAGRs derive from elasticity modeling against protein fortification adoption curves and cold-chain infrastructure expansion rates. Konjac root harvest yield volatility and enzymatic hydrolysis technology penetration serve as category-specific forecast modifiers.
Practitioners should monitor EU F-Gas Regulation enforcement intensity, FDA front-of-pack labeling mandate evolution, and Japanese agricultural cooperative harvest yield reports for early signals. Forecasts reflect assumptions regarding texture optimization technology diffusion and corporate wellness program procurement consolidation. Material shifts in EFSA health claim authorization timelines or konjac root supply chain disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Salad Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Tortilla Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Eco Bowls Market
Packaged Foods
Canned Beans Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Quinoa Pasta Market