
 Sugar Bags Market | 2026-2036
Sugar Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Bags Market Analytics
Brazil's Center-South cane belt is reshaping regional supply dynamics for industrial sugar packaging. Berry Global Inc. leverages its film extrusion footprint to serve Brazilian mill clusters with high-durability laminated structures. Mondi Group anchors European demand through kraft-paper based solutions that align with circular packaging directives. Uflex Limited competes on cost-optimized flexographic printing for emerging market bulk orders.
Sugar bags are multi-layer flexible containers engineered from polyethylene, polypropylene, or paper-laminate substrates, typically rated for 25 kg to 50 kg payloads and designed to resist moisture ingress, puncture, and caking during tropical storage and palletized transport. Their primary purpose is to preserve refined sucrose quality from mill gate through industrial food processing. Granulated sugar commands the dominant volume share due to standardized bulk handling protocols across beverage and confectionery plants. Organic sugar represents the fastest-expanding category as certification-driven buyers in North America and Western Europe command premium packaging with traceability coding and compostable film layers.
India's BIS food-contact material standards and the EU's Packaging and Packaging Waste Regulation (PPWR) are tightening substrate compliance thresholds, forcing converters toward verified recyclable or bio-based laminates. The US FDA's food additive regulations for polyethylene terephthalate copolymers influence multilayer film approvals for direct sugar contact. Stakeholders must monitor evolving extended producer responsibility schemes and substrate substitution timelines to align capital allocation with compliance windows.
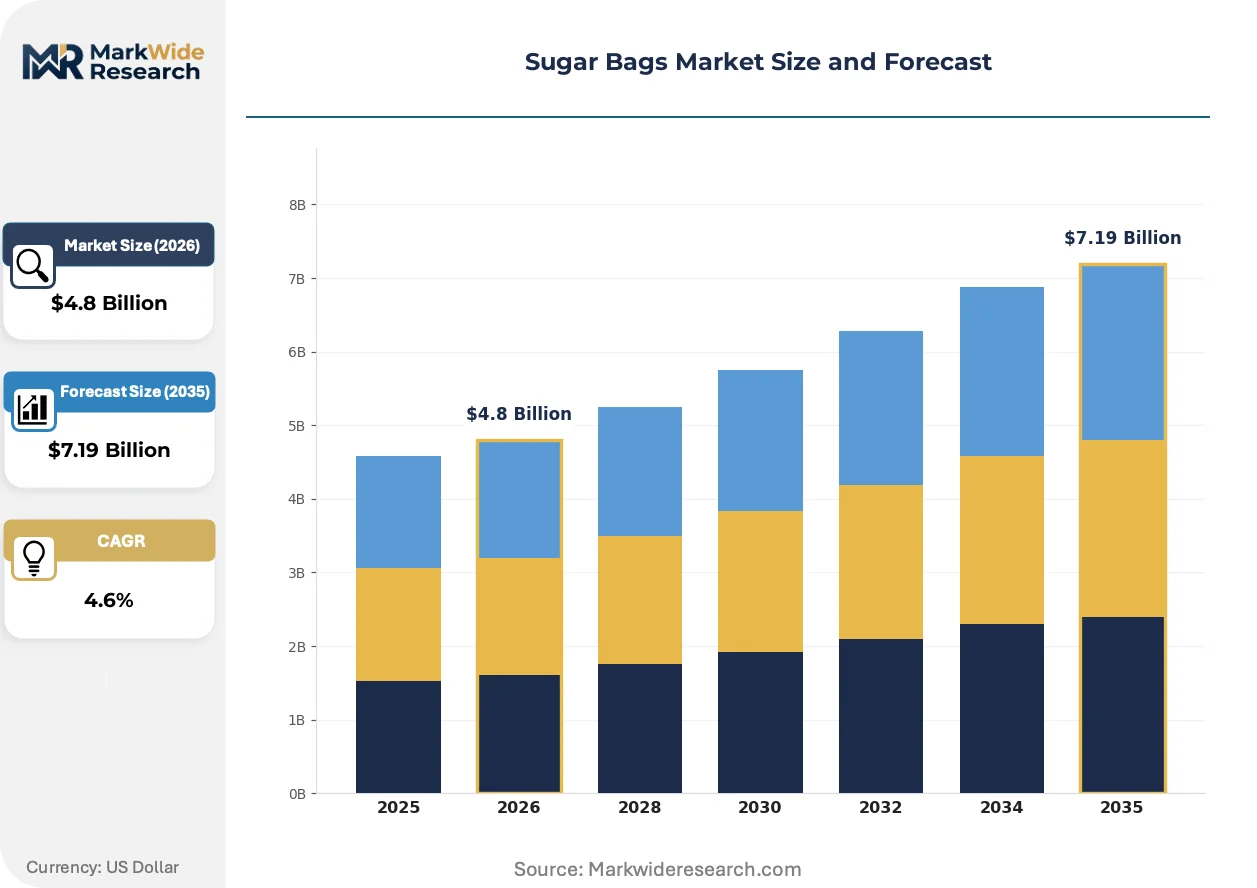
Market Dynamics
Brazil's Center-South cane belt concentration is compressing supplier margins and forcing packaging converters to co-locate extrusion capacity near milling clusters, fundamentally restructuring regional procurement geography.
Growth Catalysts
- BIS food-contact mandates:India's tightening material specifications for polyethylene and polypropylene laminates are pulling converters toward certified substrate portfolios that command premium positioning in South Asian bulk procurement.
- EU Packaging and Packaging Waste Regulation:The PPWR's recyclable-content thresholds are accelerating kraft-paper laminate adoption among European beverage and confectionery processors seeking compliance-ready sourcing.
- Organic certification traceability:North American and Western European buyers demanding compostable film layers with batch-coding capabilities are expanding the addressable premium segment beyond commodity polyethylene structures.
Market Restraints
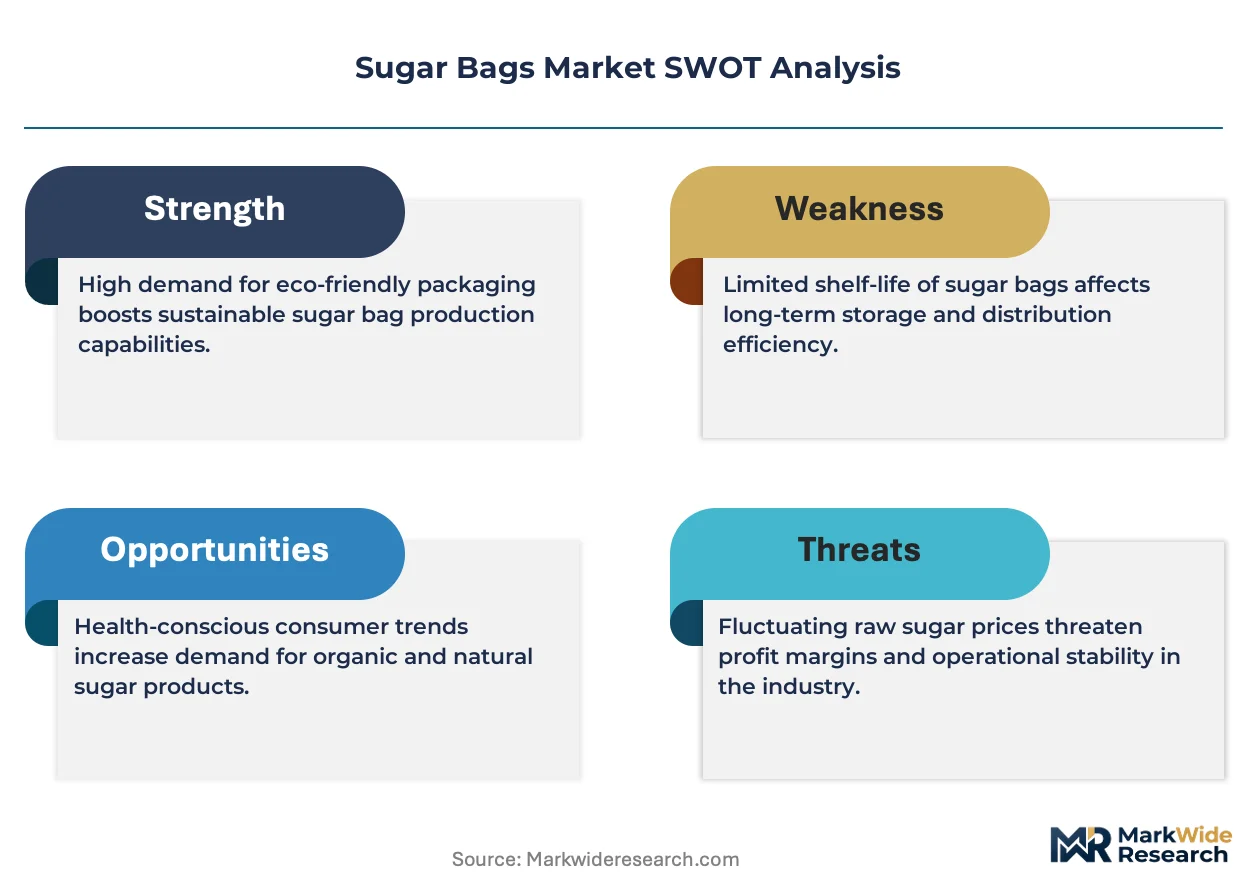
- Resin price volatility:Crude-linked polyethylene and polypropylene feedstock costs swing packaging converter margins unpredictably, compressing EBITDA at non-integrated extrusion operations.
- Brazilian supply concentration:Overreliance on Center-South milling clusters creates regional demand vulnerability to cane harvest variability and port logistics disruptions.
- Multilayer recycling incompatibility:Current mechanical recycling infrastructure cannot process laminated polyethylene-polypropylene-paper structures, limiting circular-economy claims and exposing producers to extended producer liability.
Strategic Opportunities
- India's PLI scheme for packaging:Production-linked incentives for food-grade flexible packaging are attracting capital toward domestic extrusion and printing capacity that serves subcontinent sugar processors.
- Mono-material barrier films:Advances in single-substrate high-barrier polyethylene are converging with EU recyclability mandates to create first-mover positioning for converters mastering seal-performance optimization.
- E-commerce bulk channels:Direct-to-factory digital procurement platforms are emerging as alternative channels that disintermediate traditional distributor networks for mid-size food manufacturers.
Industry Challenges
- Flexographic pre-press talent scarcity:Skilled operators capable of color-matching and plate-making for high-speed sugar-bag printing lines are in short supply across emerging market converter bases.
- Extended producer responsibility compliance timelines:Rapidly shifting EPR registration deadlines in Germany, France, and Italy are forcing packaging buyers to requalify suppliers on compressed certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Bags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Powdered Sugar, Brown Sugar, Organic Sugar Packaging Type: Bags, Boxes, Bulk Containers, Sachets End User: Food Manufacturers, Beverage Companies, Bakeries, Retail Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores |
| Companies Covered | BASF SE, Berry Global Inc., Amcor plc, Mondi Group, Sealed Air Corporation, International Paper Company, Huhtamaki Oyj, Uflex Limited, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Bags Market Evolving Landscape
Active materials science and digital printing integration are compressing production lead times while regulatory pressure on recyclability is rendering legacy multilayer structures economically untenable in premium segments.
Water-based barrier coatings applied to kraft paper substrates are rendering obsolete conventional polyethylene-laminated structures for moisture-sensitive sugar applications. European confectionery processors are specifying these coatings at scale for 25 kg retail-bound formats. The shift is compressing demand for thermal lamination equipment and redirecting converter capex toward aqueous coating lines.
The EU's Packaging and Packaging Waste Regulation is mandating minimum recycled content thresholds and design-for-recycling standards across member states. Flexible packaging converters serving industrial sugar buyers must now verify substrate recyclability through third-party protocols. German and French food manufacturers are accelerating supplier audits to lock in compliant sourcing ahead of 2030 enforcement windows.
Direct digital procurement platforms are fragmenting traditional distributor dominance in bulk sugar packaging. Mid-size Brazilian and Indian food processors are bypassing regional distributors to contract extrusion converters through B2B marketplaces that quote real-time pricing on volume-scaled orders. This channel compression is most visible in São Paulo State and Maharashtra, where mill-proximate buyers prioritize logistics cost reduction over relationship-based sourcing.
Sugar Bags Market Segmentation
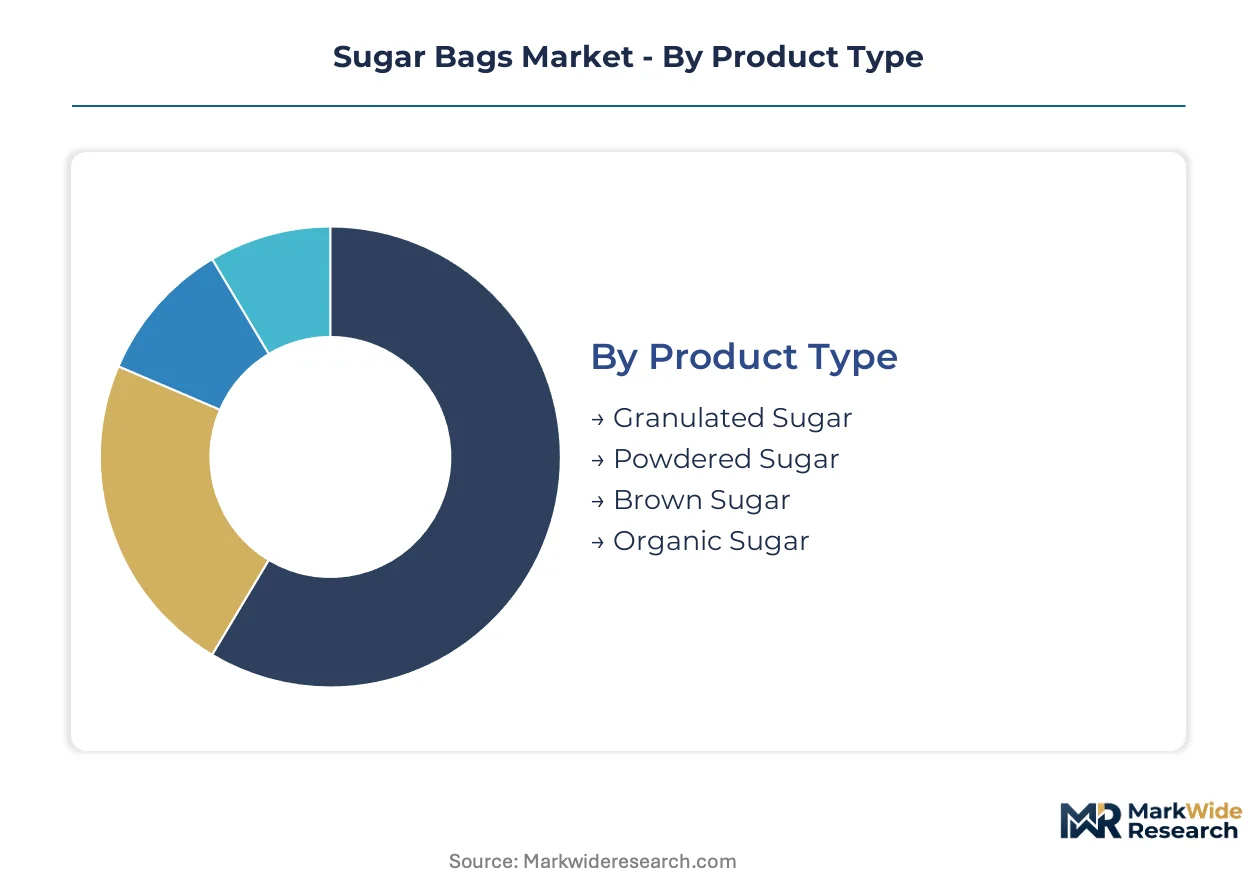
Segmentation in sugar packaging reveals divergent technical requirements across product states and buyer scale. Granulated formats demand moisture-barrier engineering, while organic certification drives substrate complexity. Channel selection determines run-length economics for converters serving industrial versus retail endpoints.
Product Type:
Cycle times vary sharply: commodity grades turn on annual harvest calendars, while organic and specialty sugars operate on certification-renewal cycles that stretch procurement timelines.
- Granulated Sugar:Crystalline sucrose with standardized particle size distribution requires polyethylene-polypropylene laminate barriers rated for tropical humidity exposure. Demand concentrates in Brazilian Center-South milling clusters where bulk beverage processors specify 50 kg formats with pallet-stacking load limits. The segment anchors converter volume but faces margin compression from resin price volatility.
- Organic Sugar:Certification-tracked sucrose from non-GMO cane or beet sources mandates compostable film layers with batch-coding traceability. North American and Western European buyers command premium positioning, pulling converters toward bio-based laminate R&D. This category climbs fastest as ESG procurement policies harden.
- Powdered Sugar:Finely milled sucrose with anti-caking additives requires higher-barrier structures to prevent moisture-induced clumping during storage.
- Brown Sugar:Molasses-retained sucrose with elevated moisture content demands specialized breathable films that balance humidity retention against mold resistance.
Granulated sugar dominates installed base. Organic sugar is where expansion concentrates.
Packaging Type:
Cost tiers separate industrial-scale formats from retail-ready units, with capital intensity and print complexity escalating down the volume-per-unit curve.
- Bags:Multi-layer flexible containers in 25-50 kg capacities constitute the industrial standard, engineered from polyethylene, polypropylene, or paper-laminate substrates with puncture resistance and moisture ingress protection. Brazilian mill clusters and Indian Maharashtra processors drive regional procurement volume for laminated structures.
- Sachets:Single-serve flexible pouches in 5-50 gram formats demand high-speed form-fill-seal compatibility and precise seal-strength tolerances. European foodservice distributors specify these for hospitality channel penetration, prioritizing portion-control precision over unit economics.
- Boxes:Rigid paperboard containers with polymer liners serve retail premium positioning and gift-segment applications.
- Bulk Containers:Flexible intermediate bulk containers and rigid totes handle 500-1000 kg payloads for industrial compounders and beverage concentrate manufacturers.
Bags capture the volume base. Sachets attract the steepest expansion trajectory as foodservice automation spreads.
End User:
Application requirements fragment sharply between process-scale automation and artisanal handling protocols.
- Food Manufacturers:Industrial processors of confectionery, dairy, and prepared foods specify 25-50 kg bags with automated filling-line compatibility, prioritizing seal integrity and pallet stability over print sophistication. Indian FSSAI compliance and EU PPWR recyclability mandates are reshaping substrate specifications for multinational procurement.
- Beverage Companies:Soft drink and juice concentrate producers demand 50 kg formats with extreme moisture barriers for tropical storage conditions. Brazilian Center-South cane belt concentration compresses logistics costs for mill-proximate buyers.
- Bakeries:Artisanal and industrial baking operations require mid-size formats with easy-open features and portion-control compatibility.
- Retail:Consumer-facing formats spanning 500g to 5kg demand high-impact flexographic or digital printing with shelf-appeal optimization.
Food manufacturers hold the installed base. Beverage companies concentrate expansion as cane-based sweetener demand climbs.
Distribution Channel:
Customer type determines order fragmentation, with direct procurement platforms disrupting traditional distributor intermediation.
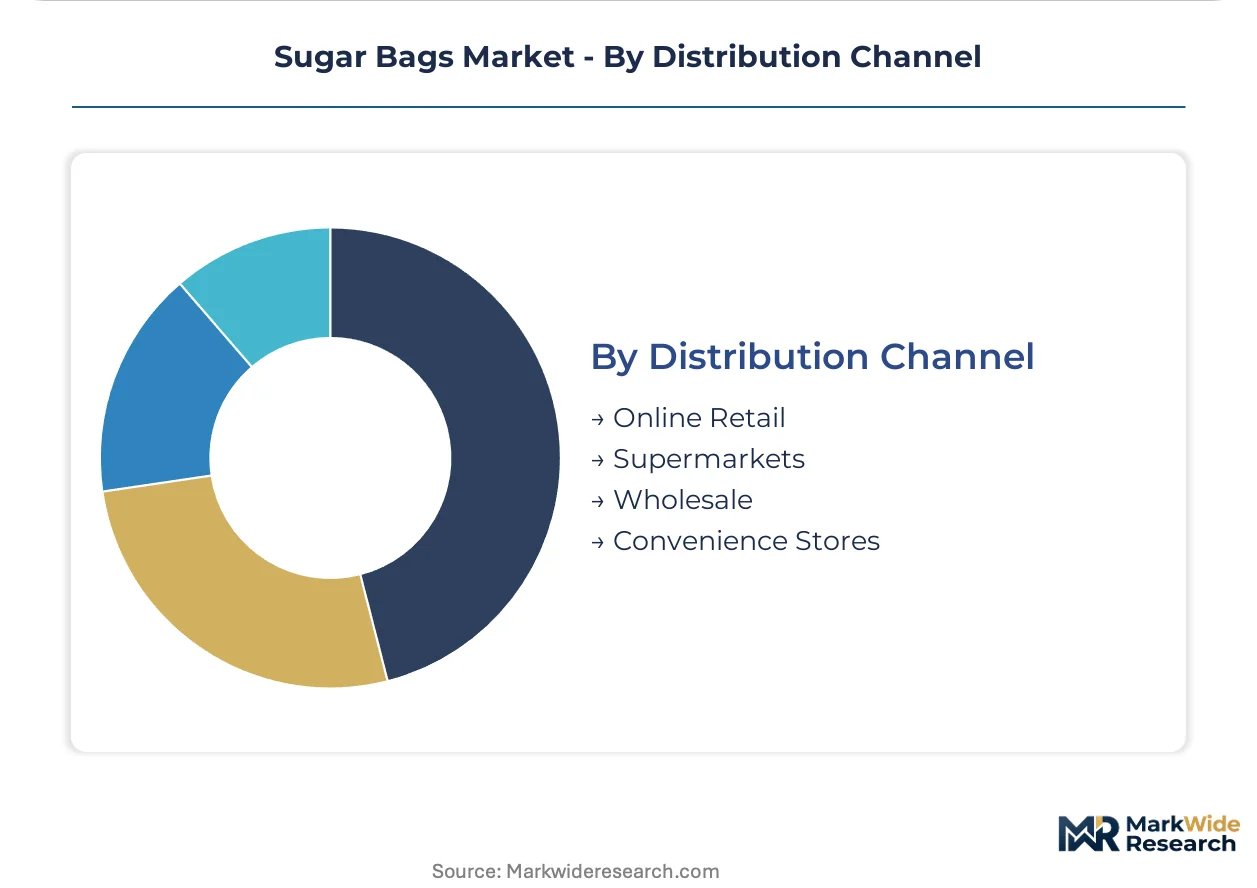
- Wholesale:Industrial distributors serving food manufacturers and beverage processors handle pallet-scale and truckload transactions with price-indexed contracts tied to resin and sugar commodity movements. São Paulo State and Maharashtra mill clusters favor this channel for logistics cost minimization.
- Online Retail:B2B marketplaces and direct-to-factory digital platforms are fragmenting traditional distributor dominance, particularly among mid-size Brazilian and Indian processors seeking real-time pricing transparency.
- Supermarkets:Retail grocery chains specify consumer formats with barcode compliance and shelf-ready merchandising features.
- Convenience Stores:Small-format retailers demand compact case packs and impulse-positioning packaging for grab-and-go sugar purchasing.
Wholesale channels dominate transaction value. Online retail is where buyer migration concentrates as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's ANVISA food-contact regulations anchor the dominant geography, with Center-South cane belt concentration dictating regional procurement patterns for industrial-grade laminated structures.
Brazil
Beverage processors in São Paulo State drive 50 kg format demand for tropical humidity resistance. ANVISA's tightening substrate compliance for polyethylene laminates is accelerating certified converter qualification cycles. Piracicaba and Ribeirão Preto milling clusters compress logistics costs for mill-proximate packaging buyers.
India
Maharashtra and Uttar Pradesh sugar processors scale bulk procurement of BIS-certified food-contact laminates. The PLI scheme for flexible packaging is attracting domestic extrusion capacity expansion. Kolhapur and Muzaffarnagar industrial corridors concentrate converter operations near cane crushing facilities.
Germany
Confectionery manufacturers specify kraft-paper laminates with verified recyclability under PPWR thresholds. ECHA chemical safety assessments influence multilayer adhesive approvals for direct sugar contact. Bavaria and North Rhine-Westphalia host converter R&D facilities optimizing aqueous barrier coatings.
United States
Organic certification buyers command compostable film layers with batch-coding traceability. FDA food additive regulations for PET copolymers shape multilayer film approvals. Corn Belt processors in Iowa and Illinois source 25 kg formats with automated filling-line compatibility.
China
Guangdong beverage concentrate producers demand moisture-barrier engineering for tropical storage conditions. SAMR national food-contact material standards are tightening polyethylene substrate specifications. Pearl River Delta packaging clusters serve domestic sugar refiners with cost-optimized flexographic printing.
Sugar Bags Market Competitive Landscape
Integrated film extruders and specialty converters split the market along substrate complexity lines. The vendor base concentrates among three tiers: multinational laminate suppliers with mill-proximate extrusion footprints, regional paper-based specialists serving circular-economy mandates, and emerging-market cost optimizers with high-volume flexographic capabilities. Dominant competitive moves include backward integration into resin compounding and strategic co-location near cane belt processing clusters.
Among North American and European diversified packaging groups, Berry Global Inc., Mondi Group, and Uflex Limited occupy distinct archetype positions. Berry exemplifies the mill-proximate extrusion model with Brazilian Center-South coverage. Mondi anchors European kraft-paper laminate supply for PPWR-compliant sourcing. Uflex represents cost-optimized emerging market production serving subcontinent bulk procurement.
| Leading Market Players |
|---|
| BASF SE |
| Berry Global Inc. |
| Amcor plc |
| Mondi Group |
| Sealed Air Corporation |
| International Paper Company |
| Huhtamaki Oyj |
| Uflex Limited |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in Brazilian Center-South extrusion facilities is compressing converter margins and forcing aggressive pricing postures toward mill-proximate buyers. This utilization imbalance simultaneously pressures Indian and Chinese suppliers to defend volume through discounted laminate quotations for bulk food manufacturers.
Pricing Analysis
Brazil-India price spreads for 50 kg laminated bags now exceed resin-adjusted freight differentials, revealing divergent competitive intensity across cane belt geographies. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification requirements and volume scale. Pricing pressure stems from polyethylene feedstock volatility and converter overbuild near São Paulo State milling clusters. Mid-size food manufacturers exhibit highest price sensitivity, while multinational beverage processors absorb premiums for verified recyclability and automated filling-line compatibility.
Supply Chain Analysis
Upstream polyethylene and polypropylene feedstock draws from petrochemical complexes in China, Saudi Arabia, and the US Gulf Coast, creating crude-linked cost exposure for non-integrated converters. Kraft paper substrates hinge on Nordic and Canadian pulp supply chains subject to seasonal logistics constraints. Single-source vulnerability concentrates in Brazilian Center-South cane belt milling clusters, where port congestion disrupts laminated bag delivery schedules. Distribution runs through industrial distributors for pallet-scale transactions, with B2B marketplaces fragmenting traditional channel control among mid-size processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated beverage processors in Brazil and India, as mill-proximate sourcing requirements reduce viable supplier pools and compress negotiation leverage for fragmented converters.
For Market Incumbents: Entrench mill-proximate extrusion capacity through co-location investments in Maharashtra and São Paulo State corridors, locking in logistics cost advantages against resin-price volatility. Accelerate BIS and PPWR certification portfolios to preempt regulatory disqualification as tightening mandates reshape qualification cycles. Backward integration into resin compounding secures margin control where feedstock swings destabilize non-integrated competitors. For New Entrants and Emerging Players: Pursue mono-material barrier film specialization targeting EU confectionery processors facing 2030 PPWR enforcement windows, where incumbent multilayer structures face obsolescence risk. Organic sugar packaging in North America offers penetrable white-space, as certification-driven buyers command premium positioning with limited compliant supply. Direct digital procurement platforms provide go-to-market acceleration, disintermediating distributor relationships among cost-sensitive mid-size Brazilian processors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated film extruders with captive resin supply and long-term offtake contracts to multinational beverage processors. Long-term viability favors converters mastering aqueous barrier coating technology and single-substrate recyclability verification. Acquisition targets should demonstrate proven mill-proximate logistics infrastructure and regulatory certification depth. Monitor EU member state EPR registration deadlines as inflection indicators for supplier requalification velocity and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Co-location Near Cane Belts | São Paulo State and Maharashtra mill proximity reduces logistics costs for 50 kg bag delivery. |
| Mono-material Barrier Film Development | High-barrier polyethylene structures align with EU PPWR recyclability mandates for confectionery processors. |
| Aqueous Coating Line Investment | Water-based kraft paper barriers displace thermal lamination equipment in European premium segments. |
| B2B Marketplace Channel Entry | Direct digital procurement fragments distributor control among mid-size Brazilian and Indian food manufacturers. |
| Backward Integration into Resin Compounding | In-house polyethylene production insulates margins from crude-linked feedstock volatility at non-integrated converters. |
Research Methodology
Cross-validation between converter production data and food manufacturer procurement disclosures anchors the qualitative findings in this study. Primary interviews with extrusion plant managers, flexible packaging procurement leads at beverage processors, BIS certification auditors, and logistics coordinators at São Paulo State milling clusters combined with secondary validation from customs trade records, BIS regulatory filings, EU PPWR implementation documents, and SEC disclosures from listed packaging groups. Bottom-up volume modeling and top-down macroeconomic calibration triangulate demand estimates across the analysis window.
Calibration against historical resin price cycles and cane harvest variability refines volume projections across product type, packaging format, end-use industry, and regional production hub dimensions. CAGRs derive from segment-level demand elasticity modeling and substitution rate analysis for organic versus conventional sugar formats. Forecast inputs incorporate BIS compliance timeline acceleration, EU EPR registration deadlines, and Brazilian ANVISA substrate specification tightening without year-specific anchoring.
Sensitivities concentrate around polyethylene feedstock volatility, Brazilian Center-South harvest variability, and EU member state PPWR enforcement pacing. Forecasts reflect assumptions regarding certification adoption curves and converter qualification cycle durations. Cross-checking against customs import data for laminated packaging substrates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Dried Honey Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Burritos Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
India Breakfast Cereals Market