
 US Canned Foods Market | 2026-2036
US Canned Foods Market Size, Share, and Industry Trends Forecast 2026-2036
US Canned Foods Market Intelligence
The customer base for canned foods in the United States is broadening beyond traditional household consumers to include a wider array of institutional and commercial buyers. Campbell Soup Company leverages its extensive distribution network to serve both retail and food service channels. Conagra Brands, Inc. differentiates through a diverse portfolio of ready-to-eat meals and vegetable products. Hormel Foods Corporation specializes in canned meats and protein-based offerings, anchoring its position in that specific category.
Canned foods are food products preserved in airtight containers, typically metal cans, through a process of thermal sterilization known as canning. This method deactivates microorganisms and enzymes to extend shelf life without refrigeration, preserving nutritional content. Within product types, canned vegetables and soups represent mature, high-volume categories, while canned meats offer higher margin potential. Distribution through supermarkets remains dominant, but the online retail channel represents the fastest-growing pathway to household end users.
The Food and Drug Administration (FDA) sets standards for canning processes, labeling, and the safety of packaging materials. Concurrently, the US Department of Agriculture (USDA) regulates canned meat, poultry, and egg products, including organic certifications. Producers must navigate evolving consumer preferences for clean labels and sustainable packaging materials to maintain market relevance.
Market Dynamics
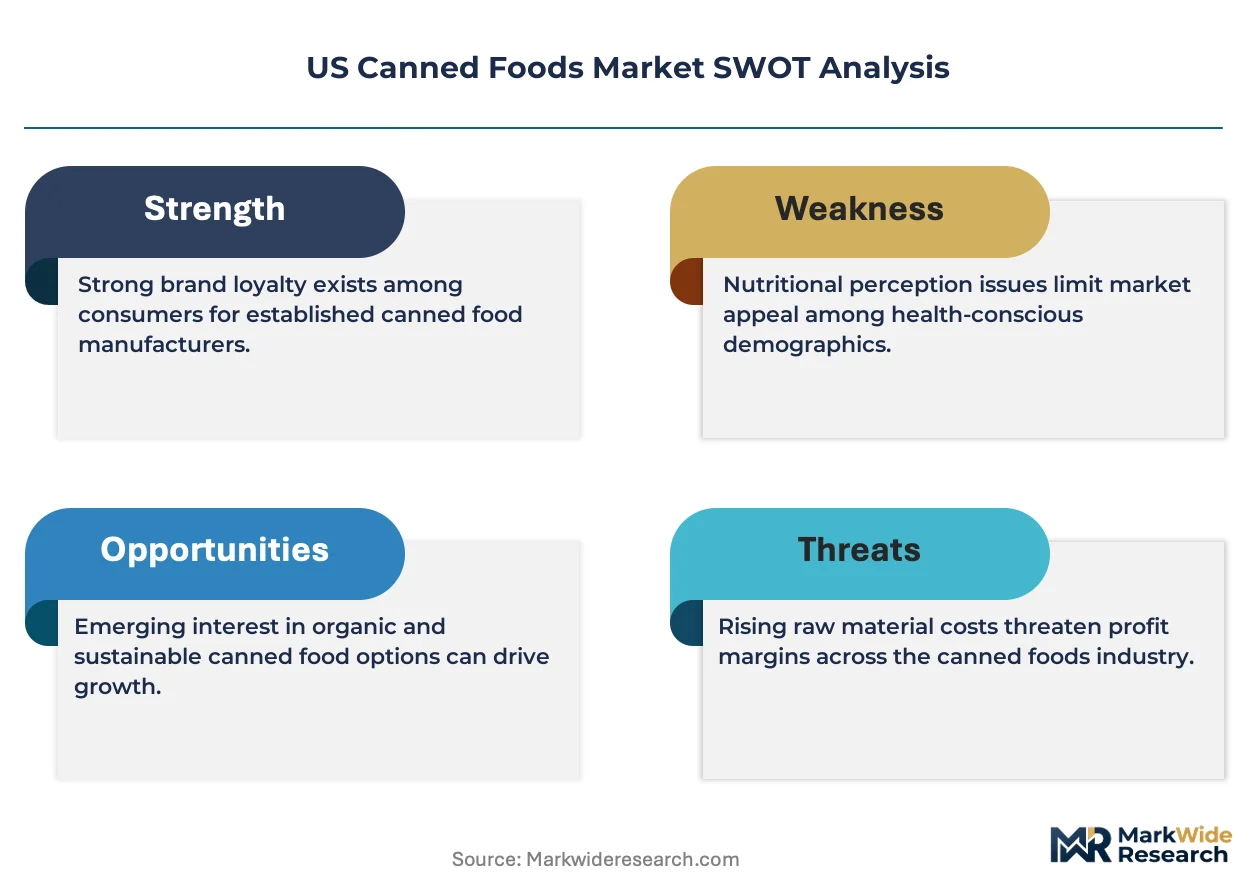
The central structural force shaping the US canned foods market is the dual pressure of regulatory modernization and consumer health consciousness. This dynamic compels manufacturers to innovate in packaging materials, particularly can linings, moving away from substances like BPA to meet new safety expectations.
Growth Catalysts
- Institutional Demand:Expanding use in the food service sector, including quick-service restaurants and institutional cafeterias, provides a consistent, high-volume demand channel for shelf-stable ingredients like vegetables and sauces.
- Packaging Innovation:Advances in can linings, guided by FDA safety assessments of materials like acrylic and polyester coatings, are improving product safety and helping to overcome consumer hesitancy regarding chemical migration.
- Demographic Shifts:Population growth and household formation in Sun Belt metropolitan areas, such as those in Texas and Florida, create concentrated pockets of demand for convenient, long-lasting food products.
Market Restraints
- Input Cost Volatility:Producer margins are exposed to price fluctuations in raw materials, specifically the steel and aluminum used for can manufacturing, which are influenced by global trade policies and commodity markets.
- Substitution from Fresh and Frozen:Canned products face intense competition from the fresh and frozen food categories, which are often perceived by consumers as healthier and of higher quality, limiting household pantry share.
- Negative Health Perceptions:Lingering consumer concerns about sodium levels, preservatives, and the nutritional degradation of food during the canning process act as a persistent barrier to wider acceptance, especially among health-conscious segments.
Strategic Opportunities
- Premium and Organic Niches:There is significant white space for growth in premium and certified organic canned products, targeting affluent consumers willing to pay more for clean labels, unique ingredients, and sustainable sourcing.
- Direct-to-Consumer Channels:Developing online subscription models and curated e-commerce storefronts allows brands to bypass traditional retail, build direct customer relationships, and test specialty products with lower risk.
- Enhanced Traceability:Integrating QR codes and other digital technologies onto packaging can provide consumers with transparent sourcing information, recipes, and nutritional data, building brand trust and engagement.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers must navigate the distinct and sometimes overlapping jurisdictions of the FDA for most canned foods and the USDA for canned meat, poultry, and egg products, increasing compliance costs.
- Sustainable Packaging Transition:The operational challenge involves reconfiguring supply chains and production lines to incorporate higher percentages of recycled content and develop solutions that address consumer concerns about packaging waste.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Canned Foods Market |
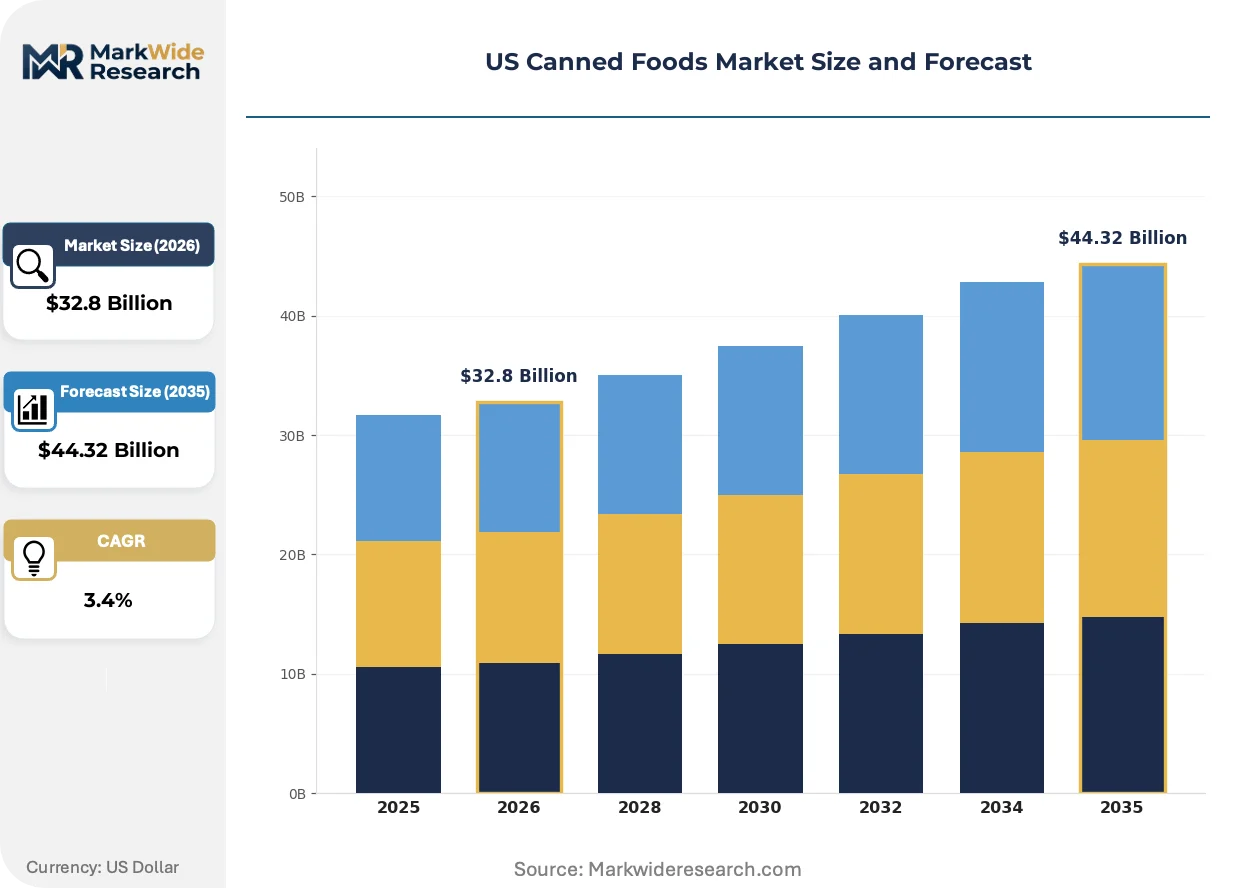
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $44.32 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Soups, Meats Packaging Type: Metal Cans, Plastic Containers, Glass Jars, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers End User: Households, Restaurants, Institutions, Food Manufacturers |
| Companies Covered | Conagra Brands, Inc., The Kraft Heinz Company, Campbell Soup Company, Hormel Foods Corporation, Del Monte Foods, Bumble Bee Seafoods, StarKist Co, General Mills, Inc., Nestlé, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Canned Foods Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of consumer demands for healthier, more transparent products and the technological capabilities enabling their delivery. This shift forces producers to reconsider everything from raw material sourcing to the information presented on the final package.
Technology and Product Evolution
Advanced BPA-free can linings, primarily based on polyester or acrylic polymers, provide a protective barrier between the food and the metal can. Food manufacturers and brand owners are rapidly adopting these materials to satisfy both consumer demand and retailer mandates for cleaner product formulations. This material science evolution is rewriting product safety standards and helping to rebuild consumer confidence in the long-term stability and inertness of canned food packaging.
Regulatory and Policy Shifts
The FDA's increasing scrutiny of per- and polyfluoroalkyl substances (PFAS) in the food supply chain is a significant regulatory development. This focus compels canners and packagers to conduct thorough audits of all food-contact materials, beyond just primary linings, to ensure their products are free from these chemicals. Canned seafood and acidic food producers are most directly affected, as they must accelerate reformulation efforts to mitigate any risk of chemical leaching and ensure compliance.
Demand-Side and Behavioral Shifts
A clear consumer pivot toward product transparency is altering purchasing behavior. Shoppers are increasingly using smartphones in-aisle or researching online to verify sourcing claims, organic certifications, and nutritional panels before making a purchase. This behavior directly challenges generic products and favors brands that use on-pack digital links, like QR codes, to provide detailed traceability, a trend most visible within the online grocery channel and among urban consumers.
US Canned Foods Market Segmentation
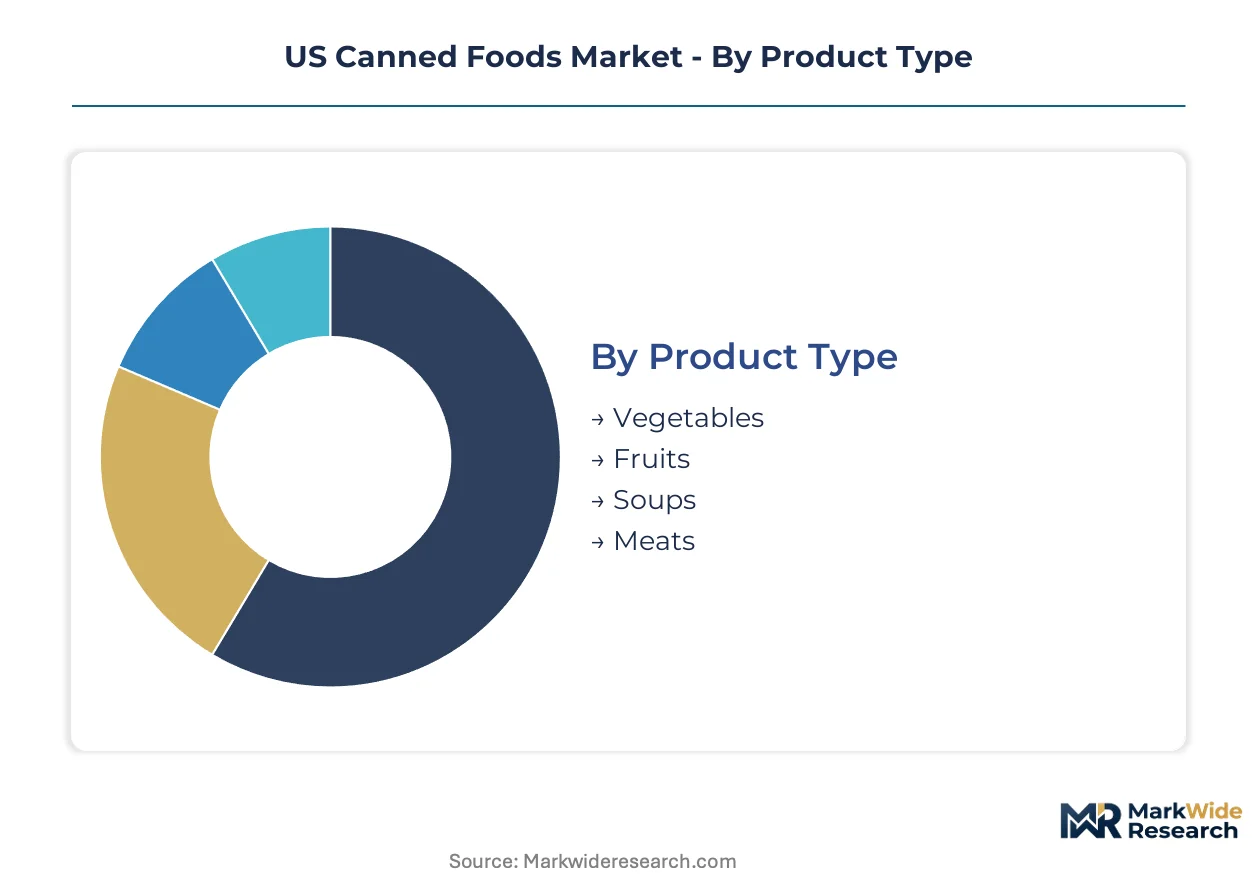
The US canned foods market exhibits diverse consumer and commercial purchasing patterns, necessitating a granular understanding of its various segments. Analyzing these distinct categories helps manufacturers align production capabilities with specific demand drivers and optimize distribution strategies. This segmentation framework provides clarity on where value creation is concentrated across the industry.
Product Type:
Canned meat and soup production often requires specialized processing lines and ingredient sourcing, representing higher capital intensity in manufacturing. These product types demand precise thermal processing to ensure safety and maintain quality over extended shelf lives.
- Meats:Canned meats encompass a range of protein products, from poultry to beef and pork, hermetically sealed for extended shelf life. Demand is particularly strong in institutional food service channels across major US metropolitan areas, driven by the need for shelf-stable, high-protein ingredients.
- Soups:Canned soups include condensed and ready-to-serve varieties, offering convenience and a base for numerous meals. Household consumption in the Northeast and Midwest remains significant, supported by traditional meal patterns and economic value.
- Vegetables:Canned vegetables provide preserved produce options like corn, peas, and green beans, widely used in home cooking and cafeterias.
- Fruits:Canned fruits, such as peaches, pears, and fruit cocktail, offer convenient dessert and snack components, particularly in school lunch programs.
Most installed capacity flows through Vegetables. Expansion is steepest in Meats.
Packaging Type:
Different packaging types serve distinct preservation, convenience, and sustainability objectives for canned food products. Material science innovations directly influence consumer acceptance and regulatory compliance for each format.
- Metal Cans:Metal cans, primarily steel or aluminum, provide robust protection against light, oxygen, and microbial spoilage, ensuring long product shelf life. Their widespread adoption in the US market, particularly for vegetables and soups, is sustained by established manufacturing infrastructure and efficient recycling programs.
- Pouches:Flexible pouches, often made from multi-layer laminates, offer lighter weight and easier storage compared to traditional cans. Consumer preference for convenience and reduced waste drives their increasing use for ready-to-eat meals and single-serving portions in urban centers.
- Plastic Containers:Plastic containers offer transparency and resealability for some canned food items, appealing to consumers seeking visual product inspection.
- Glass Jars:Glass jars provide inert storage and premium visual appeal, frequently chosen for organic or specialty canned goods by health-conscious shoppers.
Volume concentration remains highest in Metal Cans. Market share gains are most pronounced in Pouches.
Distribution Channel:
The effectiveness of a distribution channel is measured by its ability to connect products with the target consumer base efficiently. Each channel caters to specific purchasing habits and logistical requirements across the US market.
- Supermarkets:Supermarkets represent the primary retail channel, offering broad product assortments and competitive pricing for canned goods. Consumers in suburban and rural areas heavily rely on these stores for their weekly grocery shopping needs, ensuring consistent high volume.
- Online Retail:Online retail platforms facilitate direct-to-consumer sales and subscription models, providing convenience and access to niche products. Urban consumers and younger demographics drive this channel's rapid expansion, valuing home delivery and wider selection.
- Convenience Stores:Convenience stores cater to immediate consumption needs, stocking smaller formats of popular canned items for on-the-go consumers.
- Wholesalers:Wholesalers serve as intermediaries, supplying bulk canned food products to institutional buyers and smaller retail outlets across the country.
Traditional purchasing behavior remains anchored in Supermarkets. Emerging consumer preferences are driving growth in Online Retail.
End User:
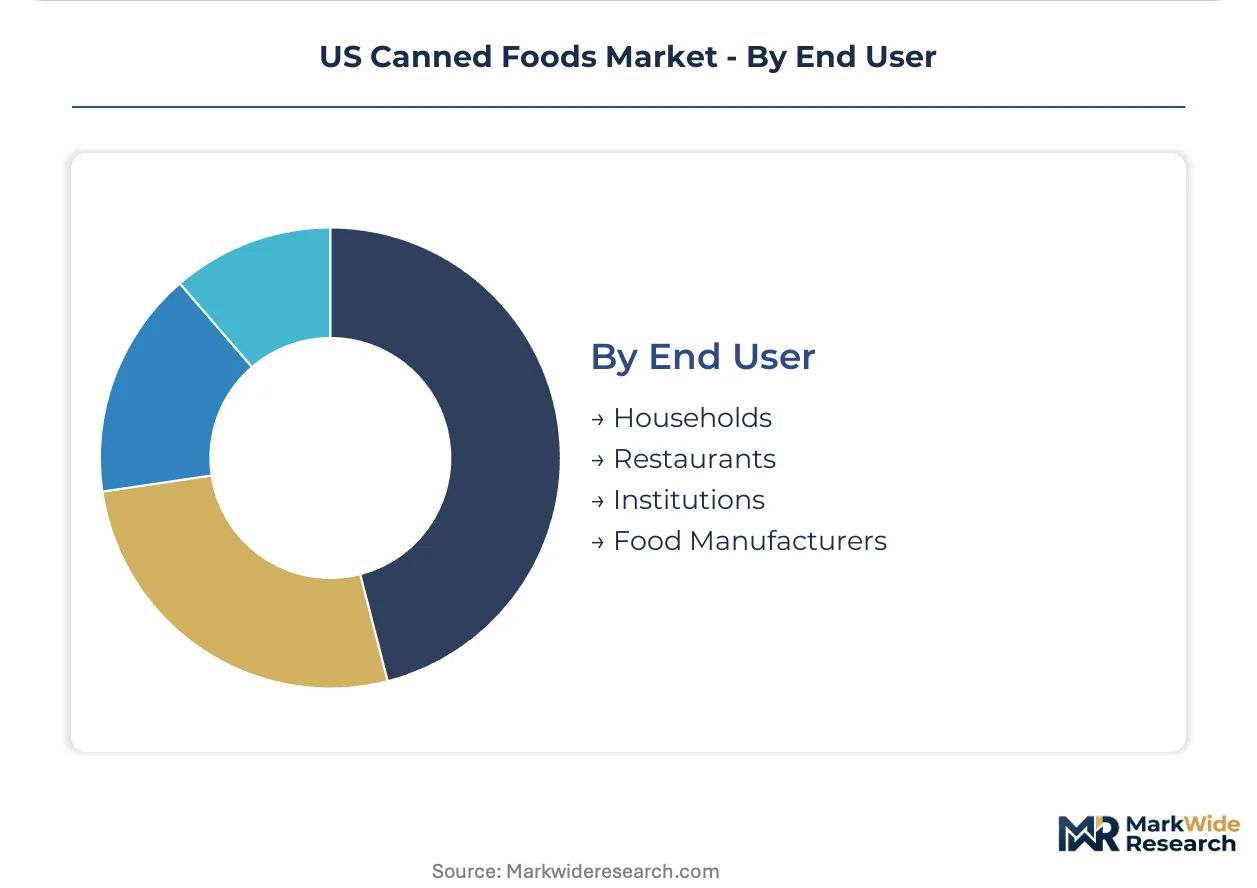
Different end-user segments present varying levels of demand stability and future expansion opportunities for canned food producers. Understanding these distinct user profiles helps tailor product development and marketing efforts.
- Households:Households represent the largest end-user segment, purchasing canned foods for daily meal preparation and pantry stocking. Demand across US households is influenced by economic conditions and the perceived value and convenience of shelf-stable products.
- Restaurants:Restaurants, particularly quick-service and casual dining establishments, utilize canned ingredients for consistency, cost control, and reduced preparation time. The institutional food service sector in Sun Belt cities shows particular interest in bulk canned vegetables and sauces.
- Institutions:Institutions like schools, hospitals, and correctional facilities rely on canned foods for large-scale meal provision due to their long shelf life and ease of storage.
- Food Manufacturers:Food manufacturers incorporate canned ingredients into their own processed food products, leveraging the pre-cooked and preserved nature of the components.
The largest volume of product is consumed by Households. New demand is heavily influenced by Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce concentrations across diverse metropolitan areas anchor the US canned foods market, driving both household and institutional demand. Consumers in these regions seek convenience and shelf-stable options for varied meal preparations. This geographic spread necessitates tailored distribution and product strategies.
Sun Belt (Texas and Florida)
Population growth and robust institutional food service expansion drive significant demand for canned foods across the Sun Belt. FDA guidance on innovative can linings influences packaging choices for producers serving this region. Food processing hubs in cities like Houston and Orlando concentrate production and distribution efforts for shelf-stable ingredients.
Northeast
Traditional household consumption patterns and perceived economic value sustain demand for canned soups and vegetables in the Northeast. USDA regulations for canned meat and poultry products are critical for manufacturers operating here. Older canning facilities in states such as Pennsylvania and New York maintain established supply chains for regional markets.
Midwest
Significant household consumption of canned goods, particularly soups and vegetables, characterizes the Midwest market, supported by traditional meal preparation habits. FDA standards for canning processes mandate compliance for all regional food producers. Agricultural processing centers in Illinois and Ohio serve as key production points for a range of canned products.
California
California consumers drive demand for premium and organic canned products, reflecting a strong health-conscious segment and clean label preferences. State-level regulations, such as those influenced by Proposition 65, impact food contact material choices for canners. Specialty food production clusters in the Central Valley and Bay Area innovate with unique ingredients and sustainable packaging.
US Canned Foods Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US canned foods market, creating a complex competitive environment. The market structure features large, established food companies alongside smaller, agile brands targeting niche segments. Strategic archetypes include broad portfolio providers, protein specialists, and organic/premium product innovators. Companies frequently engage in portfolio diversification and strategic partnerships to expand their market reach.
Among the diversified portfolio providers, Campbell Soup Company leverages its extensive distribution network, serving both retail and food service channels with a wide array of canned goods, from soups to sauces. Conagra Brands, Inc. exemplifies a broad product innovator, offering a diverse portfolio of ready-to-eat meals and vegetable products that cater to evolving consumer preferences for convenience. Hormel Foods Corporation occupies a specialized position, anchoring the canned meats and protein-based offerings segment with a strong focus on shelf-stable protein solutions for various end-users. These established entities represent the scale and market penetration characteristic of the industry's larger players.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Campbell Soup Company |
| Hormel Foods Corporation |
| Del Monte Foods |
| Bumble Bee Seafoods |
| StarKist Co |
| General Mills, Inc. |
| Nestlé |
Cost & Logistics Intelligence
Publicly traded conglomerates and family-owned mid-caps drive supply behavior and pricing discipline in the US canned foods market. Their scale influences raw material procurement and distribution efficiencies, directly impacting consumer and institutional pricing.
Pricing Analysis
Bundled product offerings, particularly for institutional buyers, define the pricing structure in this market. Price differentiation stems from the quality grade of ingredients, such as USDA Organic certification, and brand premium for established labels. Pricing pressure intensifies due to input cost volatility for steel and aluminum, alongside competition from fresh and frozen alternatives. Household consumers in economy segments exhibit the highest price sensitivity, while premium organic buyers are less impacted by price fluctuations.
Supply Chain Analysis
Wholesalers and direct distribution channels handle the flow of canned goods to various end-users across the US. Geographic supply concentration for agricultural inputs resides in states like California and the Midwest, while packaging material production is spread across various US industrial hubs. The supply chain draws from key raw materials including steel, aluminum, and agricultural produce like corn and tomatoes. Commodity price volatility for these inputs represents a significant structural risk. Distribution runs primarily through supermarkets for retail, with online retail gaining traction for direct-to-consumer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, leveraging differences in agricultural sourcing costs between US regions like the Midwest and the Sun Belt to optimize production expenses.
For Market Incumbents: Acquire specialized processing facilities to enhance efficiency and control over production. Invest in sustainable packaging R&D to address evolving consumer preferences and regulatory shifts, countering the threat from negative health perceptions. Consolidate distribution networks to improve logistics and reduce operational costs, leveraging existing scale.
For New Entrants and Emerging Players: Begin with niche product development, focusing on premium organic canned goods. Target urban consumers seeking transparent sourcing and convenience, a highly penetrable segment. Develop a direct-to-consumer go-to-market angle, emphasizing clean labels and sustainable packaging through digital channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional canning operations with established regional footprints. The long-term viability of this market rests on sustained demand for shelf-stable ingredients in the institutional food service sector. Target acquisition archetypes include brands with strong regional presence or unique product formulations. Increased institutional adoption rates for new product categories serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Introduce new premium organic canned food lines to capture health-conscious consumer segments. |
| Sustainable Packaging Integration | Reconfigure production lines to incorporate higher percentages of recycled content in metal cans. |
| Direct-to-Consumer Channel Development | Launch online subscription services to build direct customer relationships and bypass traditional retail. |
| Food Service Partnership Expansion | Secure long-term supply agreements with quick-service restaurants for bulk canned ingredients. |
| Traceability Technology Adoption | Implement QR codes on packaging to provide transparent sourcing and nutritional information to consumers. |
Research Approach
Multiple input streams—industry interviews, company reports, government publications—were reconciled to build a robust market perspective. This approach combined primary interviews with food manufacturers, retail buyers, food service procurement managers, and regulatory officials from the FDA and USDA. Secondary validation drew from US Census Bureau data, USDA Economic Research Service reports, and trade association publications, triangulating findings through both bottom-up and top-down analyses.
The cross-reference approach, comparing historical data with expert panel input, informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, packaging type, distribution channel, end-user, and regional demand. Compound annual growth rates were derived from a multi-factor analysis considering consumer preference shifts for clean labels and institutional food service expansion rates, among other industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen global trade policy shifts or rapid agricultural commodity price shocks. Forecasts reflect assumptions regarding consumer behavior and technological adoption. Significant shifts in consumer health perceptions or unexpected regulatory changes impacting packaging materials represent key risk factors that could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Instant Noodles Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Canned Goods Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Instant Cereals Market