
 Household Robots Market | 2026-2036
Household Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Household Robots Market Intelligence
Modular accessory ecosystems are shifting how buyers evaluate household robots, with docking stations, mop attachments, and self-emptying bins now sold as configurable bundles rather than fixed SKUs. iRobot Corporation leverages its proprietary mapping software to sustain premium positioning in North America. Ecovacs Robotics anchors its growth on integrated vacuum-mop hybrids with hot-water wash stations. Roborock Technology competes through laser navigation precision and aggressive price positioning in European channels.
Household robots are electromechanical systems combining locomotion platforms, sensor arrays, and embedded processors to execute domestic tasks with minimal human intervention, typically operating on battery power between 90 and 240 minutes per cycle. Their primary commercial purpose is substituting labor in repetitive home maintenance workflows. Floor cleaning robots dominate unit volumes as the most mature category, while personal assistant robots represent the fastest-expanding margin pool due to voice-interface integration and health monitoring capabilities. Security robots draw niche demand from property managers, though computer vision costs limit mass-market penetration.
FCC certification governs wireless connectivity in US-sold devices, while the EU AI Act imposes risk-classification requirements on autonomous navigation algorithms entering European markets. Japan's METI has issued safety guidelines for human-robot physical interaction in residential settings. Stakeholders must monitor whether emerging battery transport regulations constrain lithium-ion supply chains or accelerate solid-state alternatives.
Market Dynamics
The EU AI Act's risk-classification framework for autonomous navigation algorithms is forcing manufacturers to redesign sensor fusion architectures and revalidate certification pathways before European market entry.
Growth Catalysts
- Aging demographics:Japan and Germany face acute caregiver shortages, accelerating deployment of personal assistance robots with fall-detection and medication-reminder functions in residential settings.
- REACH compliance automation:Manufacturers embedding automated material declaration tools gain faster CE marking turnaround for battery-containing devices entering European distribution channels.
- Hot-water wash stations:Integrated vacuum-mop hybrids with self-cleaning dock systems reduce manual maintenance frequency, expanding addressable buyer segments beyond early adopters.
Market Restraints
- Lithium-ion supply concentration:Cathode material processing clusters in China create single-source vulnerability for battery pack procurement across mid-tier robot manufacturers.
- Computer vision cost floor:High-resolution depth cameras and edge AI processors remain prohibitively expensive for security robot mass-market penetration.
- FCC certification timelines:Wireless connectivity module approvals for US-sold devices extend product launch windows by four to six months versus non-connected alternatives.
Strategic Opportunities
- Rural elderly care:Underpenetrated Japanese prefectures outside Tokyo and Osaka present whitespace for telepresence-enabled companion robots with remote nurse monitoring.
- CSRD-aligned servitization:European corporate buyers facing sustainability reporting mandates show preference for lease-based robot fleet models with bundled maintenance and end-of-life recycling.
- Matter protocol convergence:Unified smart home interoperability standards enable voice-controlled robot scheduling through existing hub ecosystems, reducing standalone app friction.
Industry Challenges
- Embedded systems talent scarcity:Shortage of ROS-2 proficient engineers constrains firmware development velocity for simultaneous localization and mapping improvements.
- ISO 13482 compliance complexity:Safety requirements for physical human-robot interaction demand extensive collision-force testing, lengthening product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Robots Market |
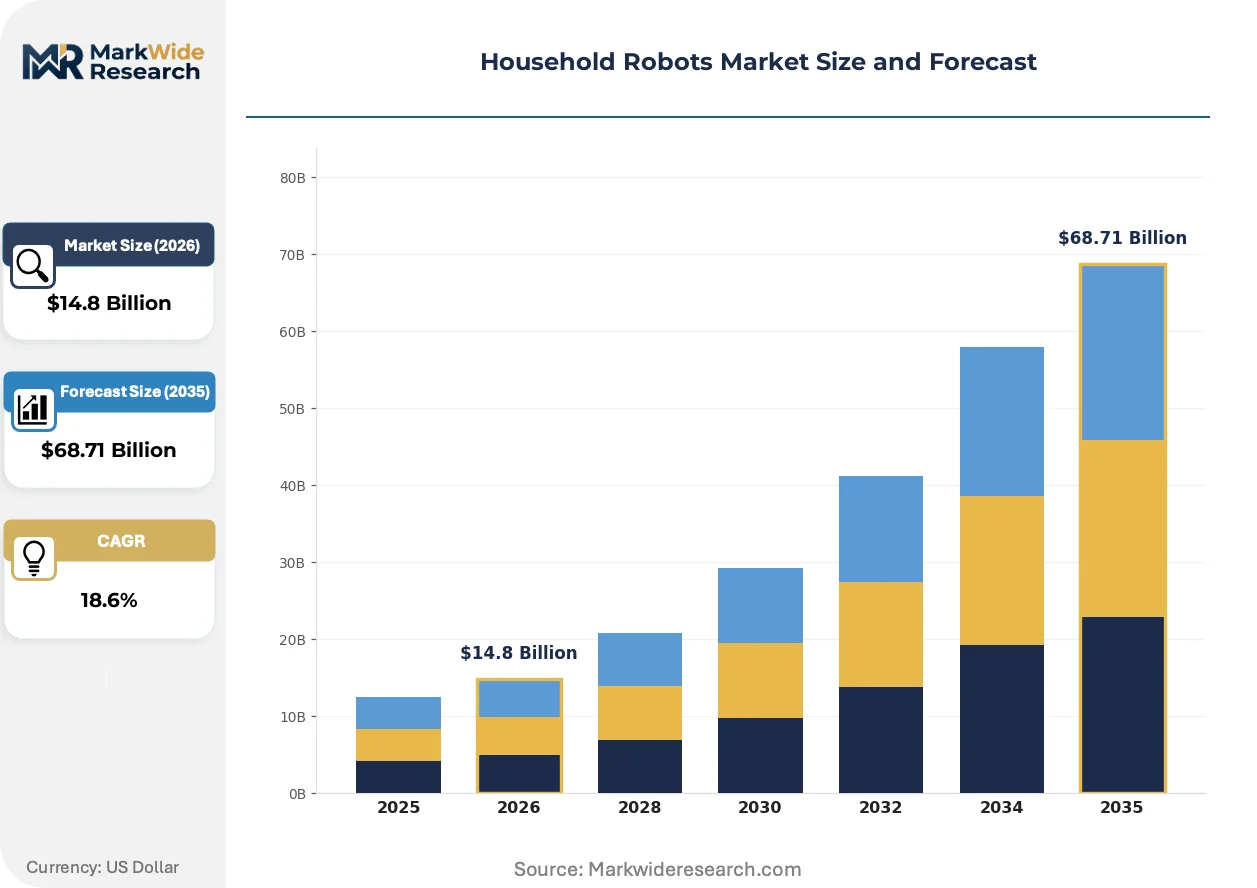
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Cleaning Robots, Lawn Mowing Robots, Security Robots, Personal Assistant Robots, Window Cleaning Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, Voice Recognition, Sensor Fusion Application: Home Cleaning, Lawn Care, Security Surveillance, Personal Assistance, Elderly Care End User: Homeowners, Property Managers, Caregivers, Technology Enthusiasts, Small Business Operators |
| Companies Covered | iRobot Corporation, Ecovacs Robotics Co., Ltd., Xiaomi Corporation, Samsung Electronics Co., Ltd., Roborock Technology Co., Ltd., Maytronics Ltd., SharkNinja Operating LLC, Dyson Limited, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Robots Market Strategic Shifts & Innovations
Modular hardware ecosystems and AI-driven predictive maintenance are compressing replacement cycles while elevating software monetization potential across installed bases.
Solid-state battery chemistry is rewriting power density assumptions for floor-cleaning robots. Premium manufacturers adopting silicon-anode cells achieve 180-minute runtime in compact form factors. This is compressing the performance gap between corded and cordless operation in large-residence applications.
The EU AI Act's transparency requirements for autonomous decision-making impose algorithmic audit obligations on navigation software deployed in European households. Manufacturers must document training data provenance and edge-case failure modes. Floor-cleaning robots with opaque black-box routing face distribution headwinds in German and French retail channels.
Subscription-based consumable replenishment is displacing transactional accessory purchases in North American e-commerce. Robot owners enroll in automated filter and brush replacement programs tied to usage telemetry. This pattern concentrates in urban households with above-average cleaning frequency and limited retail proximity.
Household Robots Market Segmentation
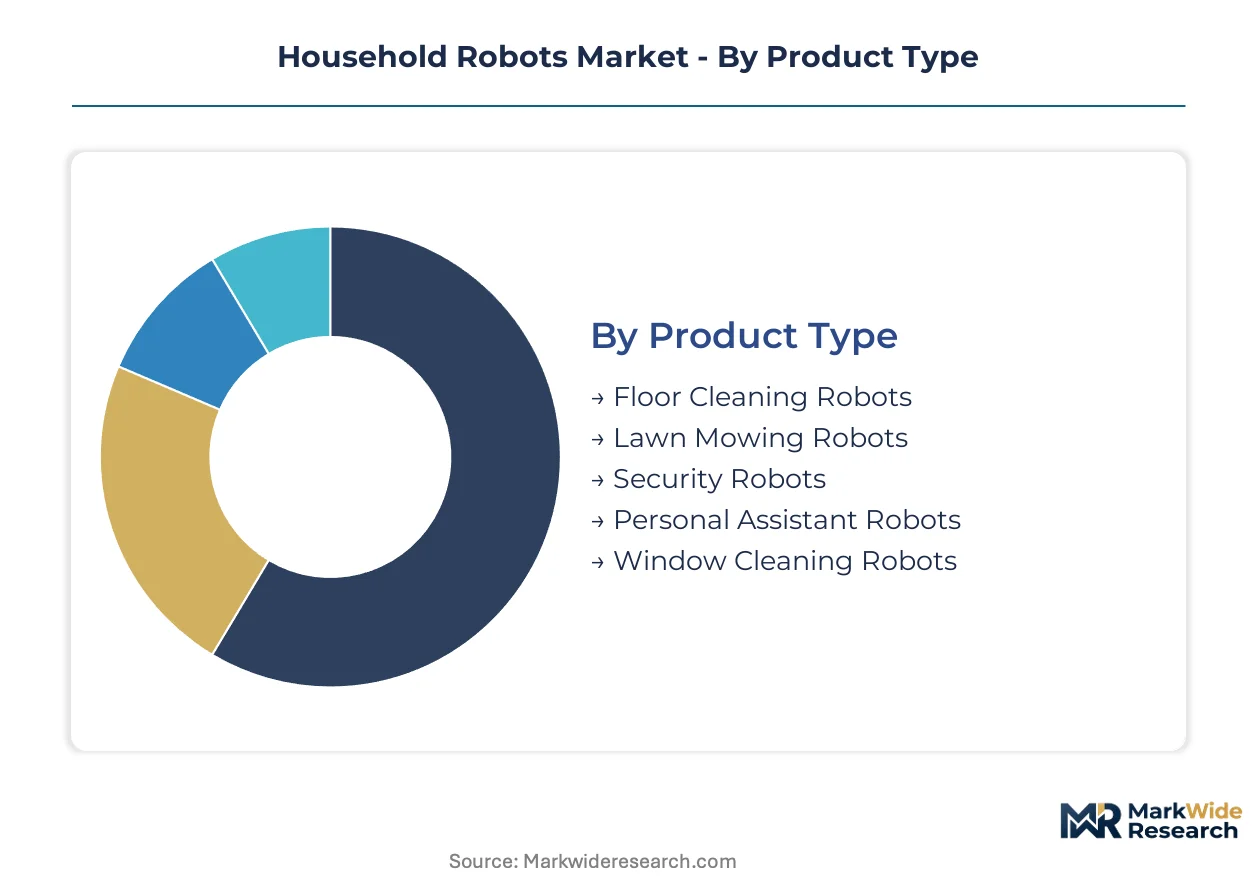
Household robots segment across hardware form factors, software intelligence layers, and use-case contexts that determine pricing power and replacement cadence. Manufacturers configure sensor suites and processing architectures differently for each slice, creating distinct margin profiles and certification requirements.
Product Type:
Customization spans from mass-market floor cleaners with standardized brush modules to bespoke elderly care platforms with configurable mobility bases.
- Floor Cleaning Robots:Vacuum-mop hybrids with hot-water wash stations dominate unit economics through consumable subscription attach rates. Demand clusters in Chinese urban households and German apartment complexes where hard flooring prevalence exceeds carpeted markets.
- Personal Assistant Robots:Voice-interface devices with health monitoring and fall-detection capabilities command premium positioning in Japanese prefectures facing acute caregiver shortages. METI safety guidelines for physical human-robot interaction constrain form factor choices.
- Lawn Mowing Robots:Perimeter-wire and GPS-RTK variants automate turf maintenance for suburban homeowners in France and the US.
- Security Robots:Computer vision and thermal imaging units patrol commercial properties; high component costs limit residential penetration.
- Window Cleaning Robots:Suction-based climbers with edge-detection sensors serve high-rise residential markets in Dubai and Singapore.
Leading the category by volume: Floor Cleaning Robots. Growing fastest: Personal Assistant Robots.
Technology:
Cost tier separates commodity sensor packages from edge-AI architectures requiring specialized firmware talent.
- Artificial Intelligence:Autonomous navigation algorithms face EU AI Act risk-classification requirements mandating training data documentation and failure-mode transparency. German and French retail channels increasingly reject opaque black-box routing systems.
- Computer Vision:High-resolution depth cameras and edge processors enable obstacle avoidance and room mapping; component costs remain prohibitive for mass-market security robot deployment.
- Machine Learning:Predictive maintenance models compress replacement cycles through usage telemetry analysis.
- Voice Recognition:Natural language interfaces integrate with Matter protocol ecosystems for hub-controlled scheduling.
- Sensor Fusion:Lidar, ultrasonic, and optical sensor combinations deliver simultaneous localization and mapping precision for laser-navigation competitors.
Widest deployment: Sensor Fusion. Steepest expansion trajectory: Artificial Intelligence.
Application:
Volume concentration versus margin potential splits this category between repetitive maintenance tasks and health-critical assistance functions.
- Home Cleaning:Automated floor and surface maintenance represents the most mature application with established replacement cycles and consumable revenue streams. Chinese manufacturing scale anchors global supply.
- Elderly Care:Medication reminders, telepresence nursing, and emergency alert systems address demographic pressure in Japan and Germany. Regulatory complexity from ISO 13482 physical interaction standards lengthens development timelines.
- Lawn Care:Seasonal deployment patterns in temperate climates create inventory management challenges.
- Security Surveillance:Property manager demand drives commercial adoption; residential penetration awaits cost reductions.
- Personal Assistance:Calendar management and smart home control functions compete with smartphone-based alternatives.
Highest shipment volumes: Home Cleaning. Gaining share fastest: Elderly Care.
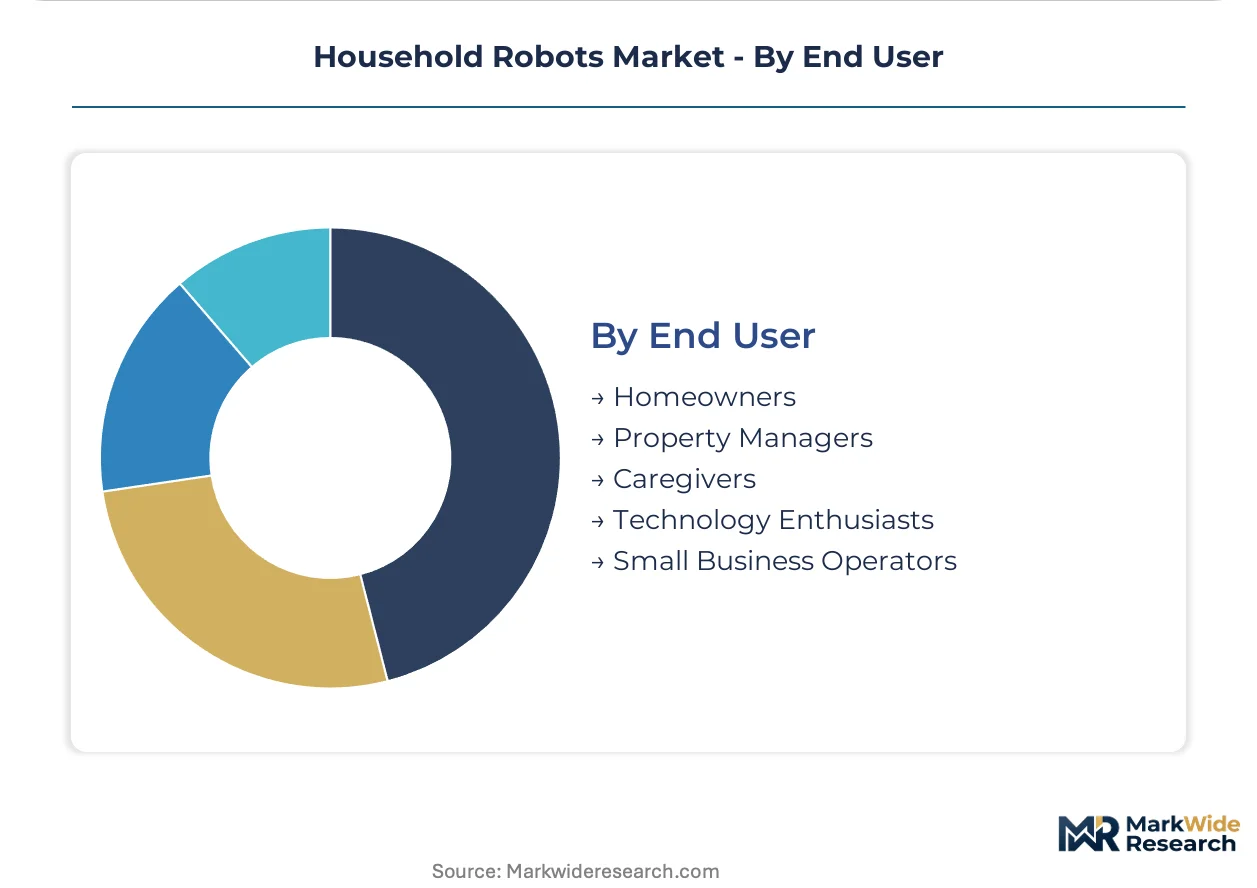
End User:
Procurement authority and technical sophistication determine whether sales flow through retail, B2B contracting, or healthcare procurement channels.
- Homeowners:Individual purchasers evaluate total cost of ownership including consumables and subscription services; urban households with limited retail proximity show strongest automated replenishment enrollment.
- Caregivers:Professional and family caregivers select devices with remote monitoring capabilities for rural elderly care applications in underpenetrated Japanese prefectures outside Tokyo and Osaka.
- Property Managers:Commercial buyers favor lease-based fleet models with bundled maintenance to satisfy CSRD-aligned sustainability reporting mandates in Europe.
- Technology Enthusiasts:Early adopters drive initial uptake of modular accessory ecosystems and beta firmware features.
- Small Business Operators:Cleaning service contractors deploy robot fleets to reduce labor costs in competitive metropolitan markets.
Largest installed base: Homeowners. Expanding most quickly: Caregivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in China while consumption spreads across aging societies in Japan, Germany, and the United States. This production-consumption divide shapes regional strategies for certification, distribution, and product localization.
China
Domestic brands command loyalty through integrated supply chains and aggressive pricing in urban households. MIIT standards for wireless connectivity and battery safety govern product launches. Shenzhen and Dongguan anchor manufacturing clusters where vacuum-mop hybrids achieve cost-efficient scale for export markets.
Japan
Acute caregiver shortages in prefectures outside Tokyo and Osaka accelerate personal assistance robot deployment with fall-detection capabilities. METI safety guidelines for physical human-robot interaction constrain form factor development. Nagoya-based engineering centers specialize in collision-force testing for ISO 13482 compliance.
Germany
Hard flooring prevalence in apartment complexes sustains demand for vacuum-mop hybrids with hot-water wash stations. The EU AI Act mandates algorithmic transparency for autonomous navigation systems entering distribution. Bavarian retail channels increasingly reject opaque black-box routing software.
United States
Urban households with limited retail proximity show strongest enrollment in automated consumable replenishment programs. FCC certification timelines for wireless connectivity modules extend product launch windows. Boston-area robotics clusters contribute firmware talent for simultaneous localization and mapping improvements.
South Korea
Technology-forward consumers drive early uptake of modular accessory ecosystems and Matter protocol integration. MFDS guidelines shape health monitoring features in personal assistance devices. Seoul Capital Area manufacturing sites supply sensor fusion components to regional OEMs.
Household Robots Market Key Industry Players
The competitive structure tilts toward diversified electronics conglomerates with captive distribution networks. Market concentration remains moderate, with no single vendor commanding dominant share across all product categories. Three archetypes define positioning: integrated platform specialists leveraging proprietary mapping software, scale-driven manufacturers optimizing cost structures through vertical integration, and premium appliance brands extending into autonomous categories. M&A activity concentrates on software capabilities and regional channel access, while portfolio diversification moves dominate as incumbents expand from floor cleaning into lawn care and security applications.
Within the integrated platform tier, iRobot Corporation and Ecovacs Robotics Co., Ltd. exemplify contrasting geographic emphases, with the former anchoring North American premium positioning and the latter dominating Chinese manufacturing scale and European channel penetration. Roborock Technology Co., Ltd. occupies a position between these poles, representing the precision-navigation specialist archetype competing on laser-based mapping accuracy. Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify the diversified conglomerate approach, leveraging existing appliance distribution infrastructure and smart home ecosystem integration to compete across multiple robot categories without category-exclusive focus.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics Co., Ltd. |
| Xiaomi Corporation |
| Samsung Electronics Co., Ltd. |
| Roborock Technology Co., Ltd. |
| Maytronics Ltd. |
| SharkNinja Operating LLC |
| Dyson Limited |
| LG Electronics Inc. |
| Others |
Cost & Logistics Intelligence
Subscription-based consumable replenishment in North American urban households is compressing margins on hardware while elevating lifetime value calculations, forcing manufacturers to restructure cost allocations toward recurring revenue streams and captive supply of brush modules and filter packs.
Pricing Analysis
Price erosion across mid-tier floor-cleaning robots traces to aggressive positioning by Chinese manufacturers with in-house motor production and Shenzhen-based assembly scale. Three-tier pricing structure across premium, standard, and economy levels separates laser-navigation systems with hot-water wash stations from basic gyroscope-guided units. Cost-down pressure on economy tiers accelerates because Xiaomi and Ecovacs anchor manufacturing scale and local brand loyalty. Technology enthusiasts show least price sensitivity; small business cleaning contractors exhibit highest.
Supply Chain Analysis
Lithium-ion cell supply rests on cathode material processing clusters in China, with secondary concentration in South Korea and Japan for separator films and electrolyte formulations. Silicon-anode solid-state cells, high-torque brushless motors, and Lidar sensor modules constitute critical component dependencies. Single-source vulnerability for battery pack procurement constrains mid-tier manufacturers without backward integration into cell chemistry. Distribution runs through e-commerce platforms and appliance retail chains with regional fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over battery cell supply and proprietary navigation firmware determines margin sustainability against commoditization pressure.
For Market Incumbents: Lock in firmware differentiation through ROS-2 engineering talent acquisition and simultaneous localization and mapping patent portfolios. Deepen upstream control over solid-state battery cell supply to escape lithium-ion cathode concentration risk. Defend against Roborock's laser-navigation precision and aggressive European channel pricing by embedding predictive maintenance telemetry that elevates switching costs.
For New Entrants and Emerging Players: Launch via telepresence-enabled companion robots targeting underpenetrated Japanese prefectures outside Tokyo and Osaka where caregiver shortages outstrip supply. Exploit whitespace in rural elderly care applications with remote nurse monitoring capabilities. Partner with regional healthcare procurement channels rather than competing through consumer retail.
For Investors and Strategic Acquirers: Re-rating potential sits with modular hardware ecosystem specialists given Matter protocol convergence and voice-interface integration catalysts. Five-to-ten year viability favors platform players with software monetization infrastructure over pure hardware assemblers. Watch EU AI Act algorithmic audit compliance timelines as inflection indicator for European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Solid-state silicon-anode chemistry secures 180-minute runtime advantage and insulates from Chinese cathode concentration. |
| ROS-2 Firmware Talent Acquisition | Embedded systems scarcity constrains mapping precision improvements; captive engineering accelerates ISO 13482 compliance. |
| Matter Protocol Certification | Unified smart home interoperability enables voice-controlled scheduling through existing hub ecosystems. |
| Subscription Consumable Infrastructure | Automated filter and brush replenishment programs elevate lifetime value and reduce retail channel dependence. |
| EU AI Act Algorithmic Audit Investment | Training data documentation and failure-mode transparency unlock German and French retail distribution. |
Research Approach
Multi-period observation of patent filings, certification registrations, and component bill-of-materials shifts anchored the trend analysis, supplemented by interviews with robotics firmware engineers, appliance retail category managers, battery procurement leads at OEMs, and METI safety guideline working group participants. Secondary validation drew from MIIT wireless connectivity filings, FCC equipment authorization databases, EU AI Act implementation guidance, and SEC 10-K robotics segment disclosures. Bottom-up shipment modeling triangulated against top-down household penetration assumptions.
Segment-weighting across product type, technology layer, application context, and end-user procurement authority structured the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves fitted to replacement cycle data and demographic penetration ceilings. Forecast inputs included solid-state battery cost curves, EU AI Act compliance timeline scenarios, and caregiver shortage projections by Japanese prefecture.
Regulatory enforcement variance, battery chemistry transition delays, and algorithmic audit rejection rates are the dominant revision risks to modeled adoption trajectories. Forecasts embed documented assumptions subject to revision as these factors materialize. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
GCC AUV Market