
 Global Soldering Robot Market | 2026-2036
Global Soldering Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soldering Robot Market Outlook
Buyer concentration among automotive electronics suppliers is expanding as tier-1 component manufacturers consolidate procurement of precision soldering systems across multiple assembly lines. Apollo Seiko leverages its specialization in selective soldering heads for high-mix electronics production. KUKA anchors its position through integrated robotic cells that combine motion control with thermal process management. Kurtz Ersa Corporation sustains technology leadership in wave soldering retrofits for legacy automotive plants.
Soldering robots are programmable articulated systems that apply molten filler metal to join electronic components or metal assemblies, typically operating at temperatures between 180°C and 400°C with repeatability below 0.05mm for microelectronics packaging. Their primary purpose is to automate thermal joining in high-volume manufacturing while eliminating human exposure to lead fumes and repetitive strain injuries. Industrial robots dominate current installations due to payload capacity and reach requirements in automotive component lines, while collaborative robots represent the fastest-growing category as electronics assemblers seek flexible redeployment across low-volume, high-mix product cycles. Infrared soldering technology leads in semiconductor packaging applications where non-contact heating preserves delicate substrate structures.
The EPA enforces workplace exposure limits for solder fume particulates under OSHA standards, compelling manufacturers to specify integrated extraction systems. REACH restricts lead content in consumer electronics sold across Europe, accelerating demand for lead-free process control algorithms. China's MEE implements emissions monitoring for industrial thermal equipment, shaping product certification requirements for equipment suppliers. Stakeholders must monitor how evolving carbon border adjustments and semiconductor subsidy conditions in the US, EU, and East Asia reshape equipment qualification timelines and sourcing geography.
Market Dynamics
Tier-1 automotive electronics suppliers are consolidating procurement across multiple EV powertrain assembly lines, compressing vendor qualification timelines and reshaping equipment specification standards.
Growth Catalysts
- EV Powertrain Assembly:Automotive OEMs in Germany, Japan, and South Korea are mandating precision soldering systems for battery management system modules, creating sustained equipment demand.
- EU F-Gas Regulation:Tightening emissions standards for industrial thermal processes are accelerating replacement cycles in legacy automotive plants across European manufacturing clusters.
- Semiconductor Packaging:Advanced substrate technologies require non-contact infrared soldering methods, pulling investment into next-generation robotic thermal systems.
Market Restraints
- Copper and Tin Price Volatility:Input cost swings for solder alloys compress margin visibility for equipment purchasers deferring capital commitments.
- Controller Chip Supply Concentration:Motion control hardware sourcing from limited East Asian foundries creates lead time uncertainty for robot integrators.
- REACH Compliance Friction:Lead-free process certification timelines extend equipment validation cycles for European-bound production lines.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component assembly are attracting soldering robot deployments in emerging packaging facilities.
- Collaborative Robot Convergence:Force-sensing cobot arms combined with vision-guided soldering heads enable flexible redeployment across high-mix product cycles.
- China Dual Carbon Goals:MEE emissions monitoring mandates for industrial thermal equipment create upgrade demand in legacy Guangdong and Jiangsu manufacturing bases.
Industry Challenges
- Multi-Axis Motion Programming:Shortage of technicians proficient in robot kinematics and thermal process parameter optimization constrains deployment velocity.
- Legacy Line Integration:Retrofitting wave soldering infrastructure with robotic cells requires custom mechanical interfacing and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soldering Robot Market |
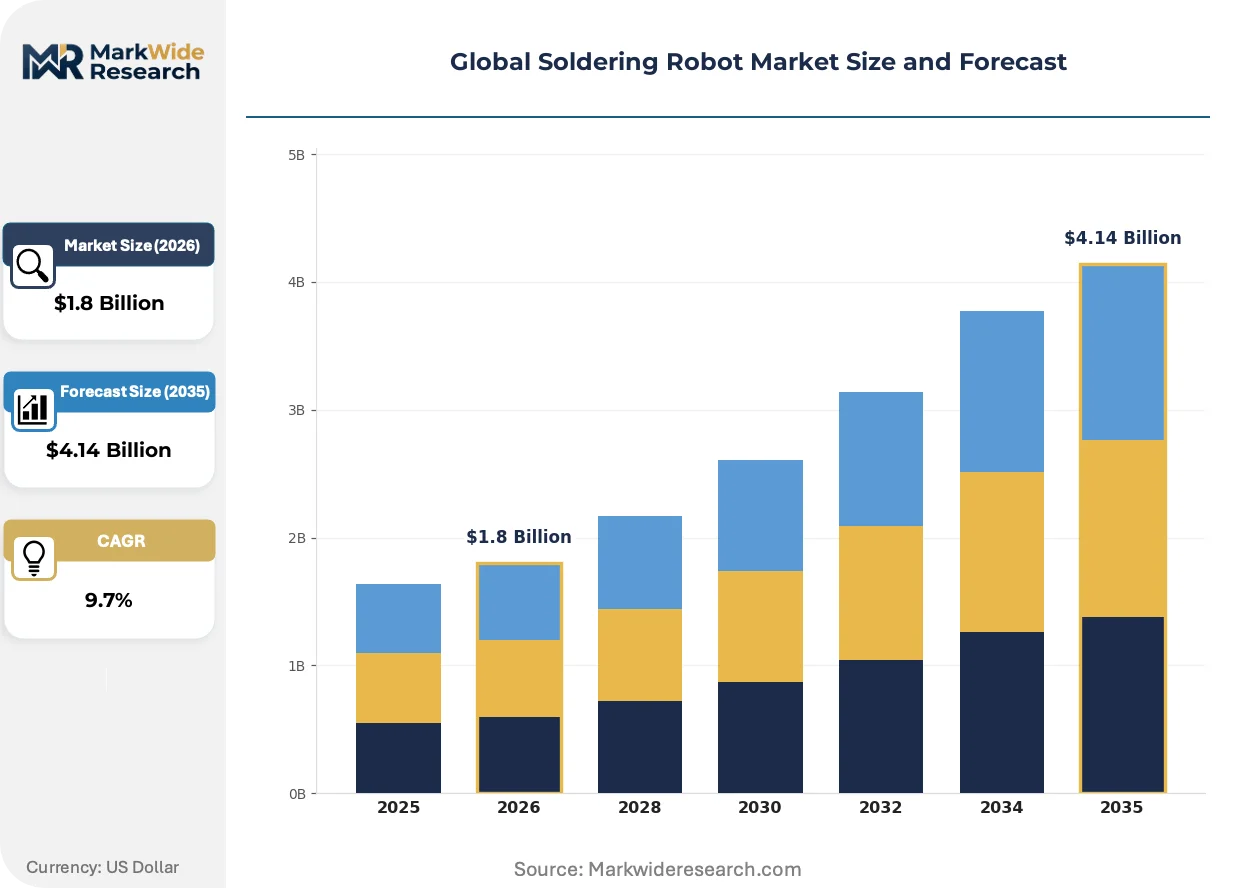
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Robots, Industrial Robots, Compact Robots, Collaborative Robots Technology: Conductive Soldering, Induction Soldering, Infrared Soldering, Wave Soldering End User: Telecommunications, Consumer Electronics, Automotive Components, Aerospace Manufacturing Installation: Standalone Systems, Integrated Solutions, Custom Solutions, Mobile Platforms |
| Companies Covered | Japan Unix, Apollo Seiko, KUKA, Tsutsumi Electric Corporation, HAKKO, Cosmic Corporation, Kurtz Ersa Corporation, Janome, Quick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soldering Robot Market Strategic Shifts
Automation architectures are converging around modular thermal process cells that separate motion control from heating subsystems, enabling faster reconfiguration across product generations.
Vision-guided selective soldering is consolidating defect detection and path correction into single-cycle operations. Automotive PCB assemblers in Stuttgart and Toyota City are deploying these systems for ADAS controller production. The technology is compressing quality assurance headcount requirements while tightening joint reliability specifications.
EPA enforcement of OSHA solder fume exposure limits is mandating integrated extraction infrastructure for new equipment installations. Metal fabrication facilities across Michigan and Ohio are retrofitting legacy lines with compliant ventilation architectures. This regulatory pressure is elevating total cost of ownership calculations and favoring vendors with bundled environmental compliance packages.
Contract electronics manufacturers are unbundling after-sales service from equipment purchases, opting for third-party maintenance networks over OEM service agreements. Foxconn-affiliated facilities in Shenzhen and Pegatron operations in Taoyuan are piloting independent technician certification programs. The shift is compressing vendor margin structures while expanding regional service provider ecosystems.
Global Soldering Robot Market Segmentation
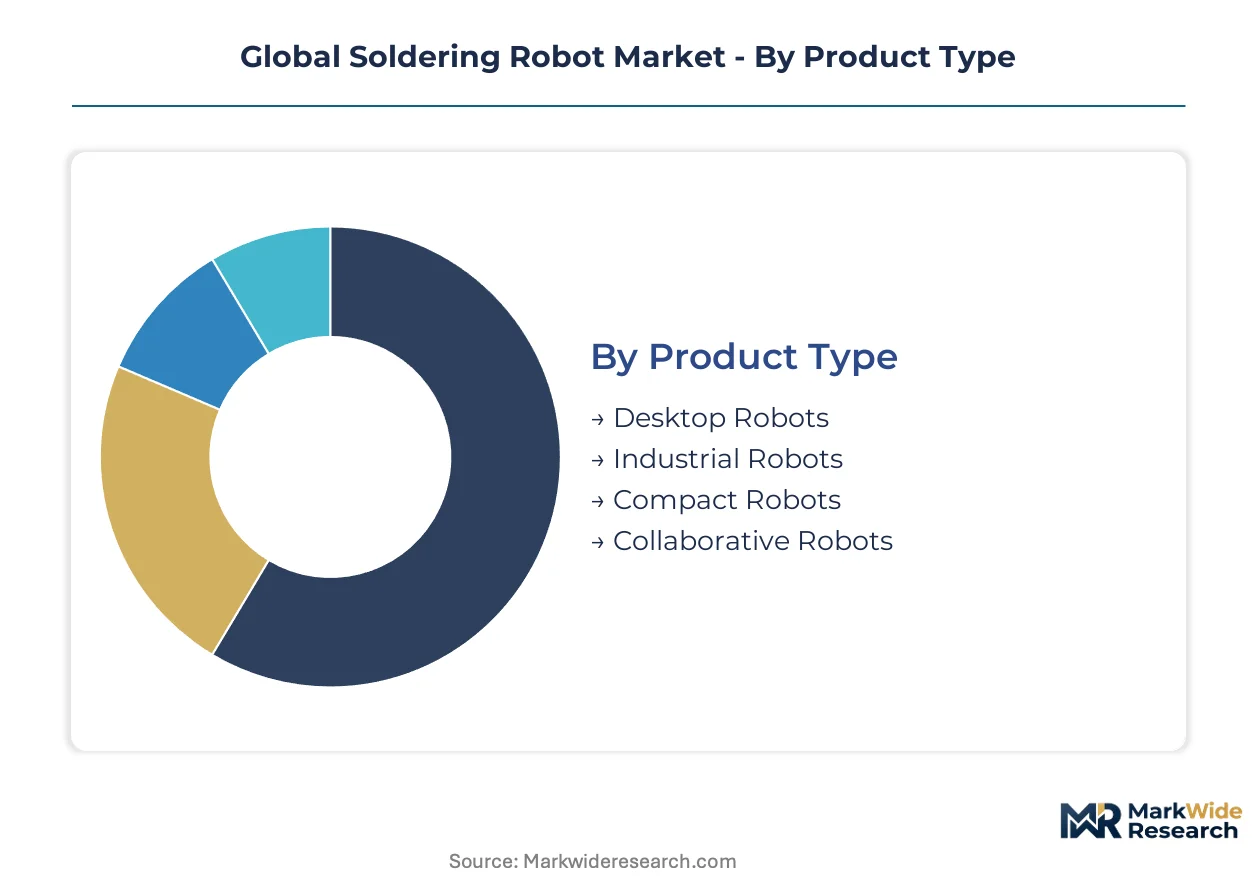
Soldering robot segmentation reveals distinct certification pathways and compliance burdens across product architectures. Equipment categories face divergent regulatory timelines under EU machinery directives, OSHA workplace safety mandates, and China's GB standards for industrial automation.
Product Type:
Certification burdens cluster around motion safety standards and electromagnetic compatibility, with collaborative variants triggering additional force-limiting validation protocols under ISO/TS 15066.
- Industrial Robots:Articulated six-axis systems with payload capacities exceeding 20kg dominate automotive powertrain assembly lines in Germany and South Korea. Tier-1 EV battery manufacturers in Stuttgart and Gyeonggi Province specify these systems for busbar welding operations where repeatability below 0.05mm preserves electrical conductivity.
- Collaborative Robots:Force-sensing cobot arms with integrated vision systems enable redeployment across high-mix electronics cycles without safety fencing. Electronics assemblers in Shenzhen and Taoyuan are adopting these for consumer PCB production where batch sizes shift weekly.
- Desktop Robots:Compact three-axis units serve prototyping labs and small-batch semiconductor packaging in research clusters.
- Compact Robots:SCARA configurations address mid-volume automotive sensor assembly with reduced footprint requirements.
Leading the category by volume: Industrial Robots. Growing fastest: Collaborative Robots.
Technology:
Process selection determines emissions compliance scope, with thermal methods triggering MEE monitoring mandates in China and F-Gas Regulation scrutiny across European installations.
- Infrared Soldering:Non-contact radiant heating preserves delicate substrate structures in advanced semiconductor packaging. Memory module manufacturers in Hsinchu and Pyeongtaek deploy these systems for HBM stack assembly where temperature gradients below 2°C prevent die warpage.
- Wave Soldering:Molten alloy bath systems remain entrenched in legacy automotive plants across Michigan and Ohio despite rising lead-free conversion costs. Retrofit robotics for these lines requires custom mechanical interfacing to existing conveyor infrastructure.
- Conductive Soldering:Direct resistance heating suits high-thermal-mass automotive components with predictable joint geometries.
- Induction Soldering:Electromagnetic field heating targets localized joints in aerospace turbine electronics where flame proximity risks material degradation.
Volume leadership sits with Wave Soldering retrofits. Steepest expansion trajectory: Infrared Soldering for semiconductor substrates.
End User:
Customer verticals impose divergent qualification timelines, with aerospace and automotive triggering extended validation cycles under sector-specific quality regimes.
- Automotive Components:EV powertrain assembly demands precision soldering for battery management systems, inverters, and onboard charging modules. OEMs in Toyota City and Wolfsburg mandate IPC-A-610 Class 3 compliance for safety-critical joints, compressing vendor qualification windows.
- Consumer Electronics:Smartphone and wearable manufacturers in Dongguan and Hanoi prioritize throughput over joint sophistication, favoring compact robotic cells with rapid program changeover. REACH lead-free restrictions extend equipment validation for European-bound production.
- Telecommunications:Base station and optical transceiver assembly requires hermetic sealing compatibility in 5G infrastructure deployments.
- Aerospace Manufacturing:Satellite and avionics electronics command NADCAP accreditation for process traceability in defense-adjacent supply chains.
Automotive Components generate the largest equipment procurement volumes. Consumer Electronics posts the most rapid deployment acceleration.
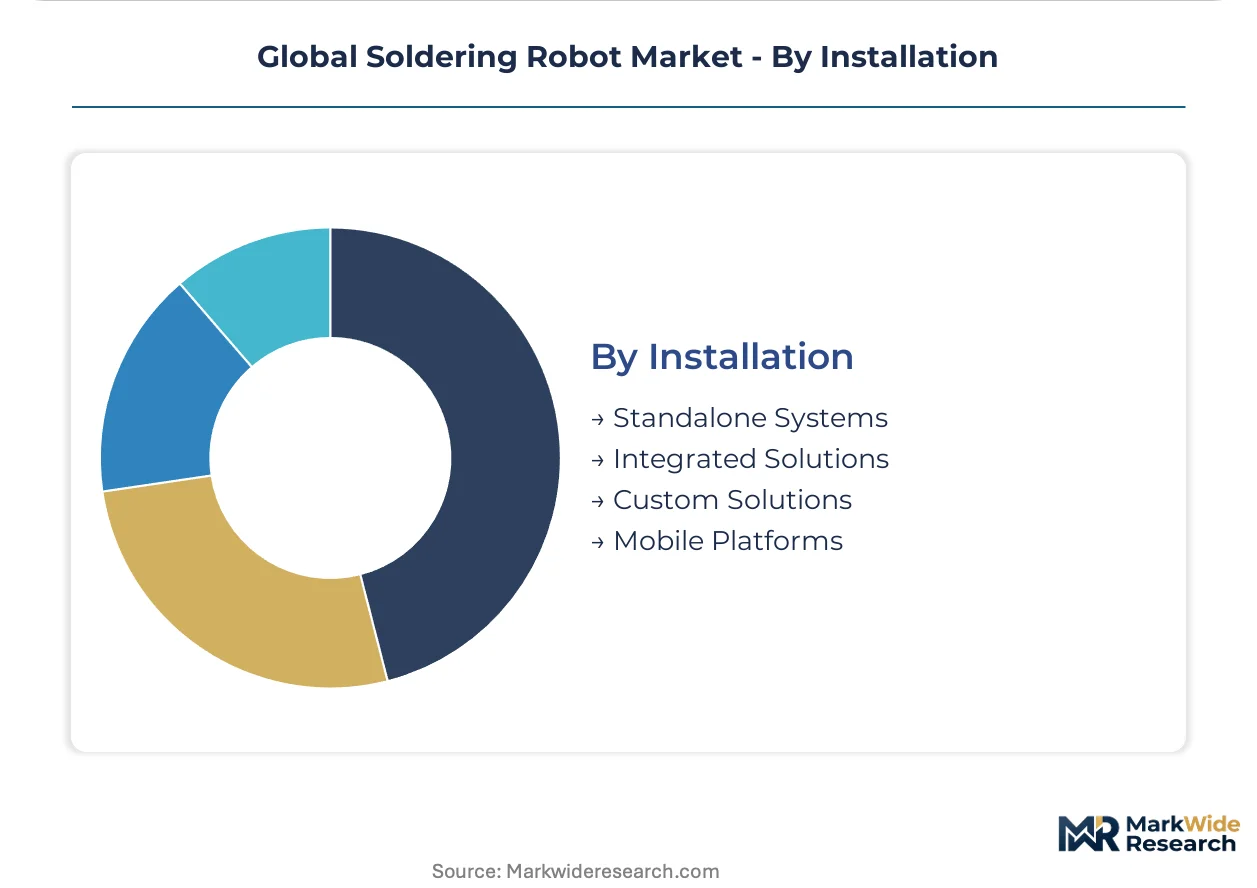
Installation:
System architecture determines integration complexity and downtime exposure, with custom solutions requiring extended mechanical engineering cycles.
- Integrated Solutions:Pre-engineered robotic cells combining motion control, thermal subsystems, and fume extraction reduce commissioning time for greenfield electronics facilities. Foxconn-affiliated plants in Zhengzhou and Juarez specify these turnkey configurations to compress production ramp schedules.
- Standalone Systems:Modular units with standardized interfaces enable incremental automation of legacy wave soldering lines in European automotive plants facing F-Gas Regulation replacement deadlines.
- Custom Solutions:Bespoke mechanical interfacing addresses unique substrate handling requirements in aerospace component shops.
- Mobile Platforms:Rail-mounted or AMR-based systems serve distributed repair operations in telecommunications field service networks.
Integrated Solutions dominate new facility investments. Mobile Platforms are gaining share fastest in aftermarket service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tin and copper alloy supply corridors from Southeast Asian smelters feed precision soldering equipment demand across three manufacturing continents. Equipment procurement patterns diverge sharply between established automotive electronics clusters and emerging semiconductor packaging facilities.
China
Guangdong and Jiangsu provinces host dense concentrations of consumer electronics contract manufacturers upgrading legacy thermal equipment. MEE emissions monitoring mandates for industrial thermal processes accelerate replacement cycles in Shenzhen and Dongguan assembly plants. The Yangtze River Delta semiconductor packaging corridor in Shanghai and Suzhou deploys infrared soldering systems for advanced memory module production.
Germany
Stuttgart and Wolfsburg automotive OEMs mandate IPC-A-610 Class 3 compliant precision soldering for EV battery management systems. EU F-Gas Regulation tightening drives retrofit demand across Bavarian and Baden-Württemberg manufacturing clusters. Industrial robot integrators in Munich anchor continental equipment specification standards for tier-1 component suppliers.
Japan
Toyota City and Nagoya automotive electronics suppliers consolidate procurement across multiple powertrain assembly lines. METI industrial automation incentives support selective soldering head deployments in precision component shops. Osaka and Kyoto semiconductor packaging facilities specialize in high-mix, low-volume robotic thermal systems for advanced substrate technologies.
South Korea
Gyeonggi Province EV battery manufacturers specify six-axis systems for busbar welding operations requiring sub-0.05mm repeatability. Seoul Capital Area semiconductor foundries in Hsinchu-adjacent supply chains deploy infrared methods for HBM stack assembly. MFDS workplace safety standards shape fume extraction infrastructure specifications for new equipment installations.
United States
Michigan and Ohio automotive plants retrofit wave soldering infrastructure with EPA-compliant robotic cells under enforced OSHA solder fume exposure limits. EPA regulatory pressure elevates total cost of ownership calculations in Detroit and Cleveland manufacturing bases. Southeast electronics assemblers in North Carolina and Texas pilot collaborative robot deployments for flexible high-mix production cycles.
Global Soldering Robot Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue collaborative robot convergence and modular thermal process architectures. The vendor base stratifies across industrial automation conglomerates, precision soldering specialists, and regional equipment fabricators. Three archetypes dominate: integrated robotic cell providers, selective soldering head specialists, and wave soldering retrofit experts. Competitive moves center on strategic partnerships for controller chip supply security and geographic expansion into India PLI scheme beneficiary facilities.
Among Japanese precision equipment specialists, Apollo Seiko, Japan Unix, and Tsutsumi Electric Corporation exemplify the selective soldering head archetype for high-mix electronics production. These Tokyo and Chiba-based entities occupy positions within the premium-tier equipment segment, anchoring technology specifications for automotive PCB assemblers. Their market presence represents concentrated expertise in thermal process parameter optimization rather than broad industrial robot portfolio breadth.
| Leading Market Players |
|---|
| Japan Unix |
| Apollo Seiko |
| KUKA |
| Tsutsumi Electric Corporation |
| HAKKO |
| Cosmic Corporation |
| Kurtz Ersa Corporation |
| Janome |
| Quick |
| Others |
Value Chain & Pricing Dynamics
Tin and copper alloy feedstock costs cascade through three distinct pricing tiers for soldering robot systems, with raw material volatility compressing margin structures most acutely at the economy end of the equipment spectrum. Contract electronics manufacturers in Guangdong and Taoyuan unbundle after-sales service from capital purchases, forcing vendors to recalibrate bundled versus à la carte pricing architectures.
Pricing Analysis
Warranty and service-bundling unbundling now separates premium-tier vendors from mid-market competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO/TS 15066 force-limiting certification status and IPC-A-610 compliance grade. Cost compression in the standard tier intensifies because tier-1 automotive suppliers consolidate multi-line procurement and extract volume discounts. Consumer electronics assemblers exhibit highest price sensitivity, while aerospace NADCAP-accredited facilities tolerate premium positioning for traceability guarantees.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries supplying motion control hardware to robot integrators. Controller chip fabrication concentrates in Taiwan, South Korea, and Japan, while precision soldering head components source predominantly from Tokyo and Chiba manufacturing clusters. Lead time uncertainty hinges on semiconductor wafer allocation priorities. Distribution runs through tier-1 automotive electronics suppliers consolidating procurement across EV powertrain assembly lines in Germany, Japan, and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collaborative robot architectures are displacing fixed industrial robot deployments in high-mix electronics cycles, compressing the window for legacy wave soldering retrofit specialists to defend installed base positions.
For Market Incumbents: Deepen backward integration into selective soldering head manufacturing to offset controller chip supply concentration risk from East Asian foundries. Anchor certification investment in REACH lead-free process validation to extend equipment qualification timelines for European-bound production lines. Consolidate channel control through captive service networks in Stuttgart and Toyota City automotive clusters before third-party maintenance ecosystems mature. For New Entrants and Emerging Players: EU F-Gas Regulation tightening opens a window for emissions-compliant infrared soldering system penetration in Bavarian and Baden-Württemberg automotive plants facing replacement deadlines. India's PLI scheme for semiconductor assembly presents the most penetrable geography for greenfield integrated solution deployments. Lead with force-sensing cobot architectures bundled with vision-guided path correction to bypass incumbent industrial robot footprint advantages. For Investors and Strategic Acquirers: Tier-1 automotive supplier consolidation of multi-line procurement is the leading indicator that vendor qualification timelines will compress further, favoring scaled players with existing IPC-A-610 Class 3 accreditation. Target selective soldering head specialists with captive thermal process IP rather than broad industrial robot portfolio breadth. Watch for MFDS workplace safety standard tightening in South Korea as the next regulatory inflection forcing fume extraction infrastructure upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control Hardware | Reduces lead time exposure from Taiwan and South Korea foundry concentration. |
| REACH Lead-Free Process Certification | Extends equipment validation cycles for European automotive PCB assemblers. |
| Force-Sensing Cobot Architecture Development | Enables redeployment across high-mix cycles without safety fencing infrastructure. |
| India PLI Scheme Geographic Expansion | Captures greenfield semiconductor packaging facility deployments in emerging clusters. |
| Third-Party Service Network Partnership | Aligns with Foxconn and Pegatron unbundling of OEM maintenance agreements. |
Study Parameters
Trade flow databases, machinery directive filings, and customs records formed the secondary backbone for supply corridor mapping and equipment import pattern analysis. Primary interviews with plant engineers at automotive electronics facilities, procurement leads at tier-1 component suppliers, and aftermarket service heads validated installation trends and unbundling behavior. Bottom-up unit deployment tracking across Germany, Japan, South Korea, China, and the United States combined with top-down manufacturing value-add estimates to anchor market sizing.
Historical trendline analysis of industrial robot density in automotive electronics clusters established baseline penetration rates for projection modeling. Segmentation dimensions spanned product architecture, thermal process technology, end-use vertical, and installation type across the analysis window. CAGRs derived from equipment replacement cycle compression under EU F-Gas Regulation and China's MEE emissions mandates, cross-referenced with semiconductor packaging capacity expansion announcements.
Caveats apply where copper and tin alloy price volatility or controller chip supply disruption could materially shift the outlook for capital equipment procurement timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Middle East and Africa Warehouse Robotics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Agricultural Robots Market