
 Commercial Service Robotics Market | 2026-2036
Commercial Service Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Service Robotics Market Insights
Healthcare logistics is repositioning as the fastest-expanding demand vertical for commercial service robotics, overtaking traditional hospitality deployments. ABB leverages its industrial automation heritage to anchor European hospital logistics contracts. SoftBank Robotics Group competes through brand strength in reception and concierge formats across Asian commercial real estate. Pudu Robotics specializes in compact delivery form factors for restaurant and retail corridors.
Commercial service robotics encompasses autonomous electromechanical systems designed for non-manufacturing environments, typically integrating lidar arrays, ultrasonic sensors, and edge-computing processors to execute navigation, manipulation, or surveillance tasks without human teleoperation. These systems serve primary commercial purposes spanning inventory transport, facility sanitization, perimeter monitoring, and guest interaction across physical business locations. Cleaning robots occupy mature margin pools in airport and mall contracts where procurement cycles are standardized, while AI-powered platforms represent the fastest-growing technology segment as natural language processing and predictive path planning capabilities diffuse from research into operational deployments. Delivery robots within the logistics application segment are capturing expanded warehouse footprints as e-commerce fulfillment networks deepen automation layers.
The EU AI Act and CE marking requirements under the Machinery Directive shape product standards and market access for autonomous commercial units entering European facilities. In the United States, OSHA guidelines and emerging state-level autonomous vehicle classifications influence deployment protocols for mobile robots operating alongside human workers. In China, MIIT national standards and GB certification frameworks govern sensor reliability and electromagnetic compatibility for commercial service platforms. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment go-to-market strategies and determine which technology architectures achieve cross-border scalability.
Market Dynamics
Labor substitution economics in warehousing and logistics operations are compressing payback periods for autonomous mobile robot deployments below eighteen months across major facility networks.
Growth Catalysts
- EU AI Act compliance deadlines:European facility operators are accelerating procurement timelines to secure CE-marked autonomous units before certification bottlenecks intensify in 2026.
- Last-mile delivery robotics:Urban logistics hubs in Germany and Japan are deploying sidewalk-capable delivery platforms to reduce per-package labor costs in dense commercial corridors.
- Edge-computing processor diffusion:Onboard NVIDIA Jetson and Qualcomm RB3 platforms are enabling real-time path planning without cloud dependency, expanding deployable environments.
Market Restraints
- LiDAR sensor supply concentration:High-performance solid-state lidar arrays depend on limited production capacity in Chinese and Japanese component foundries.
- OSHA workplace safety protocols:Emerging state-level autonomous vehicle classifications in the United States create deployment friction for mobile robots operating alongside human warehouse staff.
- Manual cleaning labor substitution:Low-wage janitorial services in emerging economies limit robot vacuum economics in airport and mall contracts outside premium markets.
Strategic Opportunities
- Hospital logistics underpenetration:European healthcare facilities represent expandable addressable market for medication and specimen transport automation.
- MIIT national standards alignment:Chinese GB certification frameworks for electromagnetic compatibility create regulatory tailwind for domestic manufacturers exporting sensor platforms.
- Natural language processing convergence:Integration of GPT-class models with robotic operating systems enables guest interaction deployments in hospitality and concierge formats.
Industry Challenges
- Robotics integration engineering scarcity:Facility operators lack in-house expertise to calibrate sensor fusion arrays and fleet management software across heterogeneous vendor environments.
- CE marking timeline compression:Machinery Directive conformity assessment delays for autonomous navigation systems extend product launch windows by six to twelve months.
- Legacy warehouse management system interoperability:Proprietary WMS architectures in established logistics networks resist API standardization for robot fleet orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Service Robotics Market |
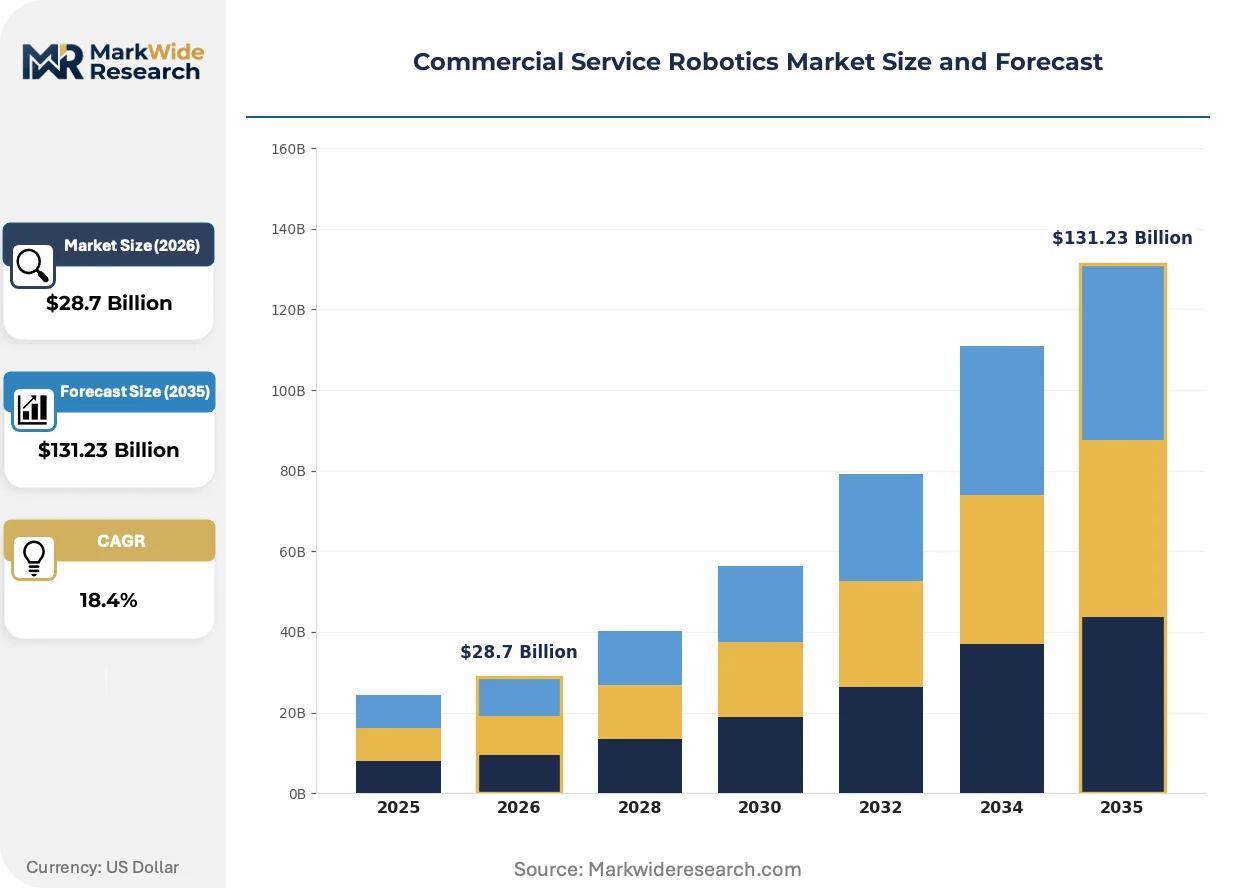
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $131.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Robots, Delivery Robots, Security Robots, Reception Robots Application: Hospitality, Healthcare, Retail, Logistics Technology: AI-Powered, Autonomous Navigation, Machine Learning, Sensor-Based End User: Hotels, Restaurants, Hospitals, Warehouses |
| Companies Covered | iRobot Corporation, Intuitive Surgical, SoftBank Robotics Group, Daifuku Co., Ltd., DJI, ABB, Yaskawa Electric, Pudu Robotics, Boston Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Service Robotics Market Trends and Innovations
Sensor fusion architectures and predictive maintenance algorithms are compressing operational downtime while expanding deployable environments beyond climate-controlled facilities.
Multi-modal sensor stacks combining solid-state lidar, millimeter-wave radar, and thermal imaging are automating navigation reliability in low-visibility warehouse conditions. Third-party logistics operators in the United States are retrofitting existing facilities with these perception upgrades at twice the pace of greenfield deployments. The technology is automating the shift from fixed-conveyor infrastructure to flexible robotic transport networks that reconfigure with seasonal demand fluctuations.
The EU AI Act's risk-classification framework for autonomous systems is mandating conformity assessment procedures for commercial service robots operating in human-populated environments. German facility operators face the steepest compliance costs as national machine safety standards layer additional requirements onto CE marking obligations. Healthcare logistics segments are responding by consolidating procurement around vendors with established EU notified body relationships.
Facility managers are unbundling after-sales service contracts from hardware acquisition, opting instead for performance-based maintenance agreements tied to uptime guarantees. This purchasing pattern is displacing traditional capital expenditure models in airport and retail corridor deployments. Japan's commercial real estate sector exhibits the most pronounced shift, with SoftBank Robotics and domestic competitors restructuring pricing around operational availability metrics.
Commercial Service Robotics Market Segmentation
Commercial service robotics vendors configure product architectures around four distinct axes: physical form factor, operational environment, intelligence layer, and facility type. Each segmentation dimension carries different margin profiles, certification requirements, and sales cycle lengths that shape go-to-market economics.
Product Type:
Physical form factor determines sensor payload capacity, battery endurance, and maneuverability constraints across corridor widths and elevator dimensions.
- Cleaning Robots:These units integrate vacuum suction arrays, UV-C sterilization modules, and water-based scrubbing mechanisms for hard surface maintenance. Demand concentrates in German airport terminals and Japanese shopping complexes where standardized procurement frameworks and 24-hour operational requirements compress payback calculations.
- Delivery Robots:Sidewalk-capable platforms with insulated cargo compartments and secure compartmentalization for medication or meal transport. Chinese hospital networks and German urban logistics hubs are expanding fleet deployments as labor substitution economics strengthen in dense commercial corridors.
- Security Robots:Perimeter patrol units equipped with thermal imaging, acoustic anomaly detection, and strobe deterrent systems for facility surveillance.
- Reception Robots:Humanoid or kiosk-form platforms integrating natural language processing for guest check-in, wayfinding, and basic concierge functions.
Cleaning robots lead on scale; delivery robots lead on momentum.
Application:
End-use environment dictates regulatory exposure, integration complexity, and human-robot interaction protocols.
- Healthcare:Medication transport, specimen delivery, and sanitization automation within hospital campuses. European facilities under EU AI Act risk-classification frameworks are consolidating procurement around CE-marked vendors with notified body relationships.
- Logistics:Warehouse inventory transport, sortation assistance, and last-mile handoff operations. United States e-commerce fulfillment networks are retrofitting existing facilities with multi-modal sensor stacks at twice greenfield deployment pace.
- Hospitality:Guest-facing concierge, room service delivery, and lobby maintenance functions.
- Retail:Inventory scanning, customer assistance, and cleaning operations within store environments.
Logistics commands the largest installed base; healthcare is expanding most quickly.
Technology:
Intelligence architecture determines cloud dependency, real-time responsiveness, and cybersecurity surface area.
- AI-Powered:GPT-class language models and predictive path planning algorithms executing guest interaction and dynamic route optimization. Japanese commercial real estate operators and Chinese hospital networks are deploying these platforms for reception and concierge functions.
- Autonomous Navigation:SLAM-based mapping, obstacle avoidance, and elevator integration without facility infrastructure modifications. United States warehouse operators favor these systems for retrofit deployments across heterogeneous legacy environments.
- Machine Learning:Pattern recognition for anomaly detection, predictive maintenance, and fleet optimization.
- Sensor-Based:Reactive obstacle detection and basic path following without predictive capabilities.
Autonomous navigation leads on deployment volume; AI-powered platforms show the steepest expansion trajectory.
End User:
Facility operator profiles determine procurement authority structures, maintenance capabilities, and financing preferences.
- Warehouses:Third-party logistics operators and e-commerce fulfillment networks with dedicated engineering staff for fleet management. United States operators are unbundling after-sales service contracts in favor of performance-based uptime agreements.
- Hospitals:European healthcare systems accelerating procurement timelines ahead of EU AI Act compliance deadlines. German facility operators face layered national machine safety standards atop CE marking obligations.
- Hotels:Brand-managed and independent properties with varying capital expenditure authorization levels.
- Restaurants:Quick-service and full-service chains deploying compact corridor-capable delivery form factors.
Warehouses dominate unit shipments; hospitals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's robotics corridor anchors commercial service robot manufacturing and deployment density, with Chinese facilities driving sensor platform standardization and GB certification alignment. The United States, Germany, and Japan concentrate demand through divergent regulatory pathways and facility automation priorities.
United States
Third-party logistics operators in Memphis and Louisville fulfillment networks are retrofitting existing warehouses with multi-modal sensor stacks at twice greenfield deployment pace. OSHA workplace safety protocols and emerging state-level autonomous vehicle classifications create deployment friction for mobile robots operating alongside human staff. California's Bay Area robotics clusters concentrate AI-powered platform development for hospitality and concierge applications.
China
MIIT national standards and GB certification frameworks for electromagnetic compatibility create regulatory tailwinds for domestic manufacturers exporting sensor platforms. Pudu Robotics and DJI anchor Shenzhen's hardware ecosystem, supplying compact delivery form factors to restaurant chains and retail corridors nationwide. Beijing-Tianjin-Hebei hospital networks are expanding medication transport automation ahead of smart healthcare infrastructure deadlines.
Germany
EU AI Act risk-classification frameworks and Machinery Directive CE marking requirements impose layered compliance costs on facility operators accelerating procurement timelines. ABB leverages its industrial automation heritage to anchor European hospital logistics contracts in Bavaria and North Rhine-Westphalia. KBA and national machine safety standards add certification complexity atop baseline European obligations.
Japan
SoftBank Robotics Group competes through brand strength in reception and concierge formats across Tokyo and Osaka commercial real estate. METI standards and JIS certification frameworks govern sensor reliability for domestic deployment. Facility managers in Kanto corridor properties are restructuring pricing around operational availability metrics rather than traditional capital expenditure models.
United Kingdom
London Heathrow and Gatwick airport terminals are standardizing cleaning robot procurement frameworks where 24-hour operational requirements compress payback calculations. GDPR and emerging AI liability frameworks shape data governance for autonomous navigation systems collecting facility mapping information. Southeast England logistics hubs are piloting sidewalk-capable delivery platforms for last-mile urban corridors.
Commercial Service Robotics Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge hardware manufacturing with fleet management software capabilities. The vendor base organizes around three tiers: diversified industrial conglomerates with automation heritage, pure-play robotics specialists with focused form factors, and emerging AI-platform companies integrating language models with physical systems. Two archetypes define competitive positioning: industrial automation incumbents leveraging existing facility relationships, and agile specialists capturing corridor-scale delivery and hospitality niches. M&A activity concentrates on sensor fusion and edge-computing software assets, while geographic expansion through distributor networks accelerates in European and Asia-Pacific healthcare verticals.
Among diversified industrial conglomerates, ABB and Yaskawa Electric represent the automation heritage archetype, anchoring European and Japanese hospital logistics contracts through established industrial channel relationships. SoftBank Robotics Group exemplifies the brand-driven hospitality specialist, while Pudu Robotics occupies the compact delivery form factor niche. These three companies illustrate the competitive spectrum from facility-scale automation integration to corridor-scale mobility specialization.
| Leading Market Players |
|---|
| iRobot Corporation |
| Intuitive Surgical |
| SoftBank Robotics Group |
| Daifuku Co., Ltd. |
| DJI |
| ABB |
| Yaskawa Electric |
| Pudu Robotics |
| Boston Dynamics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up sensor specialists anchor pricing discipline across the commercial service robotics value chain, compressing distributor margins while feeding component scarcity into tiered hardware premiums. Their consolidated ownership of LiDAR foundries in Chinese and Japanese manufacturing corridors tightens supply allocation protocols, forcing facility operators into longer-term offtake contracts to secure solid-state arrays.
Pricing Analysis
Distributor markups absorb 15-25 point spreads between OEM direct pricing and end-user procurement, with volume-scaled enterprise buyers capturing steepest discounts. Three-tier pricing structure across premium CE-marked, standard ISO-certified, and economy non-certified levels segments buyer budgets, while EU AI Act compliance deadlines are intensifying cost compression in European tiers as operators accelerate procurement. Warehouse logistics buyers exhibit highest price sensitivity due to thin e-commerce fulfillment margins, whereas hospital systems prioritize certification tier over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale warehouse operator demand, while distributor networks serve fragmented hospitality and retail corridor deployments. Component manufacturing concentrates in China, Japan, and South Korea, with solid-state LiDAR arrays, NVIDIA Jetson edge processors, and precision motor drives feeding final assembly. Single-source vulnerability in Chinese LiDAR foundries exposes European and North American integrators to allocation constraints, while distribution runs through specialized robotics distributors with certified integration capabilities rather than general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility operators arbitrage regulatory compliance costs between European CE-marking requirements and Chinese GB certification frameworks, sourcing identical sensor platforms through Shenzhen distributors at 20-30 point cost advantages before European conformity assessment fees.
For Market Incumbents: Cement fleet management software dominance through backward integration into sensor fusion calibration services, neutralizing emerging pure-play AI-platform entrants. Expand notified body relationships ahead of EU AI Act enforcement waves to capture hospital procurement consolidation. Capacity addition in German industrial corridors reinforces proximity to Bavarian healthcare networks facing layered KBA and Machinery Directive obligations. For New Entrants and Emerging Players: Mid-tier European hospitals with limited engineering staff represent the most penetrable buyer archetype, underserved by incumbent automation conglomerates focused on flagship academic medical centers. Sidewalk-capable delivery platforms for German urban logistics hubs offer white-space expansion with lighter CE marking pathways than healthcare deployments. Partner with third-party logistics operators on performance-based uptime agreements rather than capital expenditure sales cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among sensor fusion software specialists lacking hardware manufacturing scale but commanding recurring revenue from fleet optimization platforms. Long-term viability hinges on cross-border regulatory scalability across EU AI Act, OSHA, and MIIT frameworks. Watch for CE marking timeline compression as inflection indicator—delays extending product launches signal consolidation pressure on capital-constrained vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | Secures EU AI Act conformity assessment capacity ahead of German facility operator procurement waves. |
| Edge-Computing Platform Integration | Onboard NVIDIA Jetson architectures to reduce cloud dependency for warehouse retrofit deployments. |
| Performance-Based Maintenance Restructuring | Aligns pricing with operational availability metrics displacing traditional capital expenditure models in Japan. |
| Multi-Modal Sensor Stack Development | Combines solid-state LiDAR with millimeter-wave radar for low-visibility navigation in Memphis fulfillment networks. |
| Healthcare Logistics Vertical Penetration | Captures medication transport automation demand in Beijing-Tianjin-Hebei hospital networks ahead of smart infrastructure deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with warehouse operations directors, hospital biomedical engineering leads, robotics distributor principals, and EU notified body assessment officers with secondary validation. SEC 10-K filings from automation conglomerates, MIIT GB standard publication records, EU AI Act implementation guidance documents, and customs trade data for sensor platform imports anchored bottom-up installation estimates against top-down facility automation spending surveys.
Historical reference periods spanning pre-pandemic facility automation baselines through post-acceleration deployment waves anchored the forecast window, with projection horizons extending across the analysis window. Segmentation dimensions modeled include physical form factor, operational environment, intelligence layer architecture, and facility type, with CAGRs derived from regression-weighted scenario probabilities. Edge-computing processor diffusion curves and EU AI Act compliance deadline clustering served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; healthcare logistics and warehouse automation carry tighter precision than hospitality deployments given more standardized procurement reporting. Forecasts reflect assumptions around regulatory timeline adherence, sensor foundry capacity expansion, and labor substitution economics across major facility networks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
GCC AUV Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Robotic Waste Sorting System Market