
 Automated Facade Contact Cleaning Robot Market | 2026-2036
Automated Facade Contact Cleaning Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Facade Contact Cleaning Robot Market Insights
Direct-to-facility-manager distribution is rewriting how cleaning robotics reach building operators. Skyline Robotics leverages its R&D intensity to develop precision contact mechanisms for glass curtain walls. Serbot AG anchors European demand through specialized manufacturing of compact climbing units. KITE Robotics B.V. competes on sensor integration for adaptive surface detection across varied facade materials.
Automated facade contact cleaning robots are electromechanical systems combining vacuum adhesion, rotary brush assemblies, and rail-guided traversal mechanisms to remove particulate and organic buildup from vertical building envelopes without suspended human labor. These systems typically operate at pressures between 50 and 150 bar with brush rotation speeds calibrated to substrate hardness, serving primarily to reduce workplace injury liability while extending cladding material service life. Robotic Cleaners dominate current product-type revenue as established units penetrate commercial high-rise contracts, while AI-Driven technology segments attract disproportionate engineering investment for autonomous edge-detection capabilities. Commercial Buildings anchor end-user demand through sustained facility-management outsourcing trends, though Government Structures present faster growth potential as public-sector procurement modernizes.
OSHA fall-protection standards and the EU Machinery Directive shape product-safety certifications required for market entry, with CE marking and ISO 10218 compliance becoming baseline qualifications for supplier qualification. The EU AI Act introduces additional conformity obligations for autonomous navigation algorithms, compelling manufacturers to document decision-pathway transparency. Stakeholders must weigh regulatory compliance costs against the operational savings of reduced scaffolding deployment when evaluating portfolio expansion into European markets.
Market Dynamics
Labor cost inflation for suspended-platform workers is compressing payback periods for robotic cleaning systems, while the EU Green Deal's building-efficiency mandates accelerate retrofit procurement across member states.
Growth Catalysts
- EU Green Deal retrofit mandates:Building-efficiency directives in member states compel facade upgrades, creating bundled procurement opportunities for cleaning-automation vendors.
- Workplace injury liability reduction:Commercial high-rise operators face climbing insurance premiums for suspended human crews, shifting capital allocation toward electromechanical alternatives.
- Glass curtain wall proliferation:Contemporary architecture favors extensive glazed envelopes that demand frequent maintenance, expanding addressable surface area per building.
Market Restraints
- Brush assembly supply concentration:Precision rotary mechanisms for varied substrate hardness rely on specialized German and Japanese component suppliers, creating single-source vulnerabilities.
- CE marking and EU AI Act compliance costs:Documentation requirements for autonomous navigation algorithms impose fixed regulatory burdens that disadvantage smaller entrants.
- Scaffolding rental substitution:Established temporary-access providers in Southern Europe price aggressively to retain facility-management contracts, delaying robotic adoption.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland maintain extensive commercial high-rise stock with limited robotic deployment, presenting first-mover advantages for adaptive-climbing systems.
- Government structure procurement modernization:Public-sector facility managers in France and the Netherlands are piloting autonomous units for ministry and courthouse complexes.
- Sensor-lidar convergence:Integration of solid-state lidar with pressure-feedback brushes enables real-time substrate mapping, opening heritage and composite-material applications previously excluded from automation.
Industry Challenges
- Multi-surface calibration expertise gap:Field technicians capable of programming brush pressure and rotation speed for limestone, terracotta, and anodized aluminum remain scarce across service networks.
- ISO 10218 certification timelines:Safety validation for collaborative robotic operation on occupied buildings extends product launch schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Facade Contact Cleaning Robot Market |
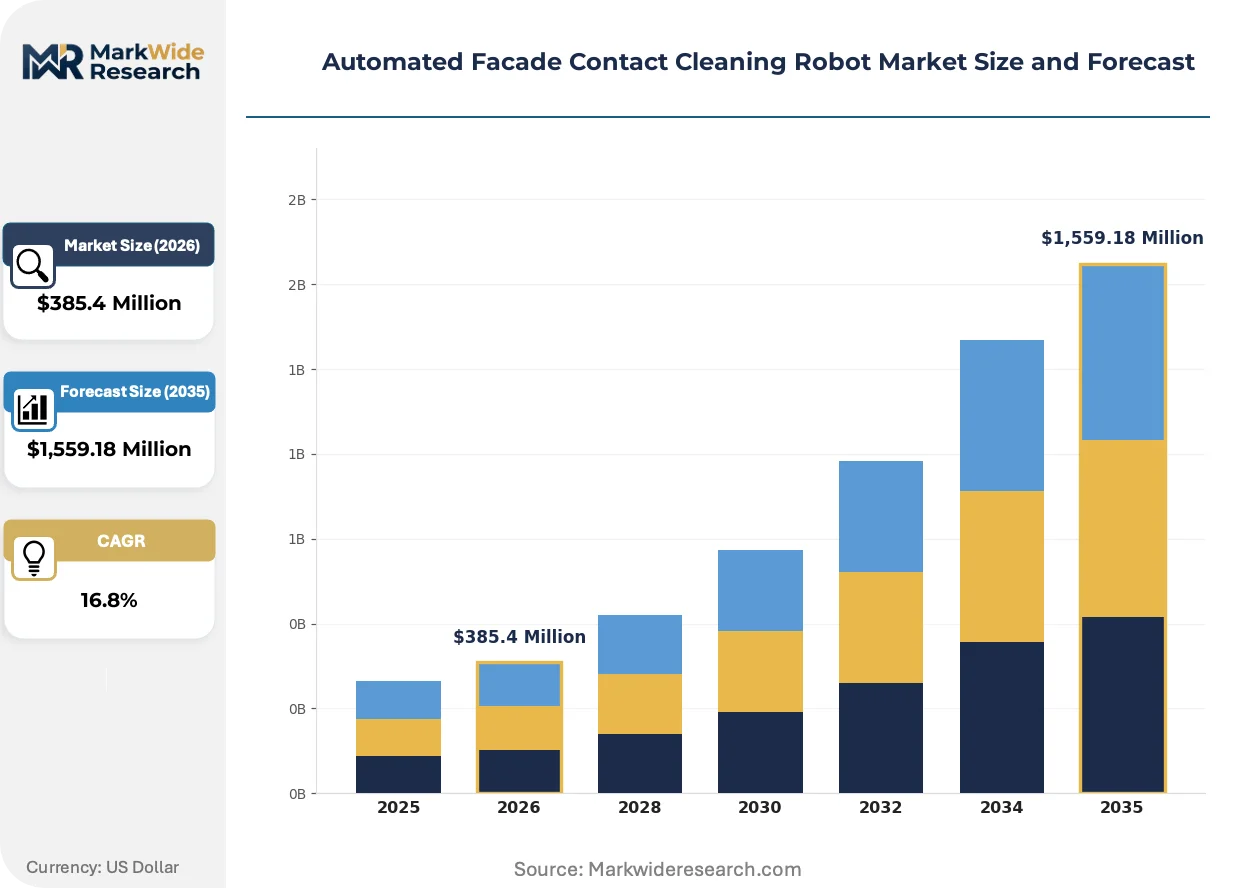
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,559.18 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Cleaners, Autonomous Devices, Manual Tools, Semi-Automated Systems Technology: AI-Driven, Computer Vision, Remote Operated, Sensor-Based End User: Commercial Buildings, Residential Properties, Industrial Facilities, Government Structures Service Type: Maintenance, Installation, Consulting, Support |
| Companies Covered | Skyline Robotics, Serbot AG, Fraunhofer IFF, Sky Pro, LLC, KITE Robotics B.V., RF Co. Ltd., IPC Eagle, FAT CAT Robotics, Autonopia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Facade Contact Cleaning Robot Market Trends and Innovations
Electromechanical systems are absorbing capabilities from adjacent automation sectors, compressing development cycles and expanding substrate compatibility beyond traditional glass-dominant deployments.
Vacuum adhesion technology is hybridizing with magnetic gripping arrays to enable operation on steel-framed curtain walls and composite cladding where pure suction fails. Facility managers in Germany and the United Kingdom are piloting these dual-mode units for mixed-material facades. The convergence is collapsing the historical segmentation between glass-specialist and universal-surface systems, forcing incumbents to broaden R&D scope or cede mid-market share.
The EU AI Act's transparency requirements for autonomous decision pathways are compelling manufacturers to document edge-detection algorithms and emergency-stop logic for notified-body review. Industrial consequence includes extended conformity assessment periods and elevated documentation costs for navigation software updates. German and French suppliers are responding by establishing dedicated regulatory-affairs functions and pre-certifying modular algorithm libraries.
Facility-management outsourcing firms are consolidating vendor relationships from equipment purchase toward integrated service agreements bundling hardware, maintenance, and cleaning schedules. This displaces traditional capital-sale channels and compresses supplier margins in exchange for multi-year revenue visibility. The shift is most pronounced in the Netherlands and Belgium where integrated property-service conglomerates dominate high-rise portfolios.
Automated Facade Contact Cleaning Robot Market Segmentation
Segmentation in the automated facade contact cleaning robot market reveals distinct service intensity patterns across product configurations. Technical complexity and deployment scale determine aftermarket revenue potential and customer lifetime value for equipment suppliers.
Product Type:
After-sales service intensity varies sharply across product categories, with autonomous platforms demanding continuous software updates and predictive maintenance contracts.
- Robotic Cleaners:Electromechanical systems combining vacuum adhesion with rotary brush assemblies operate at calibrated pressures for substrate-specific cleaning. Facility managers in Germany and the United Kingdom favor these units for commercial high-rise portfolios, driven by compressed payback periods from reduced suspended-platform labor costs. By volume, Robotic Cleaners leads. By growth pace, Autonomous Devices is ahead.
- Autonomous Devices:Self-navigating units integrate solid-state lidar with pressure-feedback systems for real-time substrate mapping. Pilot deployments in French ministry complexes and Dutch courthouse portfolios signal public-sector procurement modernization accelerating adoption.
- Manual Tools:Hand-operated pole and cradle systems retain niche applications for heritage facades with restricted robotic access.
- Semi-Automated Systems:Operator-supervised units bridge manual and fully autonomous operation for mixed-material envelopes.
Service contract attach rates diverge most dramatically between autonomous and manual product tiers.
Technology:
Technology selection dictates sensor fusion requirements and regulatory compliance pathways under the EU AI Act.
- AI-Driven:Algorithms for edge detection and emergency-stop logic require documented transparency for notified-body review under EU conformity obligations. German and French suppliers pre-certify modular algorithm libraries to accelerate deployment timelines.
- Computer Vision:Camera-based surface analysis enables adaptive brush calibration across glass, limestone, and terracotta substrates. Demand concentrates in heritage restoration projects across Italy and Spain where material diversity exceeds single-sensor capabilities.
- Remote Operated:Tethered control systems dominate early-stage pilot programs where full autonomy remains restricted by building occupancy protocols.
- Sensor-Based:Pressure and proximity arrays provide baseline environmental awareness for cost-sensitive installations.
AI-Driven platforms command premium pricing. Computer Vision systems expand fastest into material-specialist applications.
End User:
End-user category determines procurement authority structure and contract duration preferences.
- Commercial Buildings:Outsourced facility-management firms in the Netherlands and Belgium bundle hardware, maintenance, and cleaning schedules into multi-year integrated service agreements. This displaces capital-sale channels while securing supplier revenue visibility.
- Government Structures:Public-sector procurement modernization in France and the Netherlands pilots autonomous units for ministry and courthouse complexes, with faster growth potential than commercial segments.
- Residential Properties:High-rise condominium associations in urban Germany represent emerging demand for compact climbing units.
- Industrial Facilities:Manufacturing plant envelopes with specialized coating systems require substrate-calibration expertise from scarce field technician networks.
Commercial Buildings anchor current revenue. Government Structures show steepest expansion trajectory.
Service Type:
Service mix reflects shifting customer preferences from equipment ownership toward outcome-based building maintenance.
- Maintenance:Predictive service contracts covering brush assembly replacement and navigation software updates generate recurring revenue streams. These agreements dominate aftermarket economics for autonomous system suppliers.
- Installation:Rail-guided traversal mechanism deployment and facade anchoring verification require certified technician presence for ISO 10218 compliance.
- Consulting:Substrate hardness assessment and brush rotation speed programming address the multi-surface calibration expertise gap across service networks.
- Support:Remote diagnostics and algorithm troubleshooting minimize downtime for occupied building operations.
Maintenance contracts yield highest margins. Consulting services expand most quickly as material diversity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates and OSHA fall-protection standards shape procurement patterns across the dominant geographies. Germany, France, and the United Kingdom concentrate current deployment activity. Facility managers in these markets weigh regulatory compliance costs against scaffolding substitution savings.
Germany
Commercial high-rise portfolios in Frankfurt and Munich drive demand for precision contact mechanisms. The EU Machinery Directive and ISO 10218 compliance requirements extend product launch schedules for domestic suppliers. Bavaria's industrial corridor hosts specialized manufacturers of compact climbing units serving mixed-material facades.
France
Ministry and courthouse complexes pilot autonomous navigation systems under public-sector procurement modernization. The EU AI Act imposes documented transparency obligations for edge-detection algorithms. Île-de-France facility managers bundle hardware, maintenance, and cleaning schedules into multi-year integrated service agreements.
United Kingdom
Glass curtain wall proliferation in London's financial district expands addressable surface area per building. HSE working-at-height regulations compress payback periods for electromechanical alternatives. The Southeast corridor anchors outsourced facility-management outsourcing trends for robotic cleaning contracts.
Netherlands
Integrated property-service conglomerates dominate high-rise portfolios in Amsterdam and Rotterdam. CE marking requirements create baseline qualifications for supplier qualification. Randstad urban clusters present first-mover advantages for adaptive-climbing systems in underpenetrated municipal stock.
United States
OSHA fall-protection standards and climbing insurance premiums shift capital allocation toward robotic systems. New York and Chicago high-rise operators face workplace injury liability reduction pressures. Pacific Northwest tech corridors attract sensor-lidar convergence engineering for real-time substrate mapping applications.
Automated Facade Contact Cleaning Robot Market Competitive Landscape
Specialized robotics developers and diversified automation conglomerates split the market across distinct capability vectors. R&D-intensive specialists compete on precision contact mechanisms and adaptive surface detection. Diversified industrial players leverage manufacturing scale and established facility-management relationships. Competitive moves center on sensor-lidar convergence integration and strategic partnerships with outsourced property-service firms.
Among precision-contact specialists, Skyline Robotics and Serbot AG exemplify archetypes concentrated on glass-dominant and mixed-material applications respectively. KITE Robotics B.V. occupies a position within the sensor-integration tier, representing the adaptive-detection capability cluster. These three entities anchor the competitive structure through distinct technical specializations rather than scale advantages.
| Leading Market Players |
|---|
| Skyline Robotics |
| Serbot AG |
| Fraunhofer IFF |
| Sky Pro, LLC |
| KITE Robotics B.V. |
| RF Co. Ltd. |
| IPC Eagle |
| FAT CAT Robotics |
| Autonopia |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's container rate volatility transmits directly into landed costs for precision rotary brush assemblies sourced from German and Japanese component suppliers, compressing margins for system integrators while enabling price differentiation between configured-to-order autonomous units and standard robotic cleaner platforms.
Pricing Analysis
Configured-to-order pricing for AI-driven autonomous units commands substantial premiums over standard robotic cleaner platforms due to substrate-specific calibration requirements and EU AI Act documentation obligations. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked autonomous systems with pre-certified algorithm libraries from basic sensor-based units and refurbished manual tool inventories. Cost compression in the standard tier is intensifying because scaffolding rental providers in Southern Europe price aggressively to retain facility-management contracts. Municipal procurement offices in France and the Netherlands exhibit highest price sensitivity due to budget cycle constraints, while outsourced facility-management conglomerates in Belgium accept premium pricing for multi-year integrated service agreements that bundle predictive maintenance contracts.
Supply Chain Analysis
Upstream feedstock for precision rotary mechanisms draws from specialized manufacturing clusters in Germany, Japan, and South Korea, where brush assembly production rests on high-tensile polymer composites and rare-earth magnetic arrays for vacuum adhesion systems. Solid-state lidar modules and pressure-feedback sensors feed from semiconductor fabrication facilities in Taiwan and South Korea, creating single-source vulnerabilities for sensor-lidar convergence technologies. Distribution runs through direct-to-facility-manager channels that displace traditional equipment distributors, with integrated property-service conglomerates in the Netherlands and Belgium consolidating vendor relationships toward outcome-based building maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated property-service conglomerates that bundle hardware, maintenance, and cleaning schedules, fragmenting procurement authority away from individual facility managers and compressing supplier margins in exchange for multi-year revenue visibility.
For Market Incumbents: Insulate margin position by establishing dedicated regulatory-affairs functions to pre-certify modular algorithm libraries under EU AI Act transparency requirements, accelerating deployment timelines against emerging sensor-integration specialists. Deepen backward integration into brush assembly production to reduce dependence on specialized German and Japanese component suppliers, mitigating single-source vulnerability exposure.
For New Entrants and Emerging Players: Build out adaptive-climbing system capabilities targeting underpenetrated Nordic markets in Sweden and Finland, where extensive commercial high-rise stock lacks robotic deployment infrastructure. Heritage restoration projects across Italy and Spain present the most penetrable application segment due to material diversity exceeding single-sensor capabilities of incumbent glass-specialist platforms. A go-to-market angle emphasizing computer vision substrate analysis for limestone and terracotta facades differentiates against established vacuum-adhesion specialists.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by elevating compliance documentation costs that disadvantage smaller entrants without pre-certified algorithm libraries, favoring targets with established regulatory-affairs infrastructure. Long-term viability across the projection horizon hinges on sensor-lidar convergence capabilities that expand substrate compatibility beyond glass-dominant deployments. The signal to monitor is public-sector procurement modernization velocity in France and the Netherlands, where autonomous unit pilots for ministry and courthouse complexes indicate sector expansion readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EU AI Act documentation requirements extend conformity assessment periods for navigation software updates. |
| Sensor-Lidar Convergence R&D | Solid-state lidar integration enables real-time substrate mapping for heritage and composite-material applications. |
| Integrated Service Agreement Expansion | Facility-management outsourcing firms in the Netherlands consolidate vendor relationships toward multi-year bundled contracts. |
| Backward Integration into Brush Assembly | In-house production of precision rotary mechanisms reduces single-source dependence on German and Japanese suppliers. |
| Nordic Market Entry Programs | Sweden and Finland commercial high-rise stock presents first-mover advantages for adaptive-climbing systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with facility management directors, robotics R&D leads, regulatory compliance officers, and aftermarket service heads; and secondary validation against customs/trade data for component imports, EU notified-body conformity assessment records, SEC filings from diversified automation conglomerates, and facility-management outsourcing contract disclosures. Bottom-up unit deployment estimates triangulated against top-down addressable surface area calculations across commercial high-rise portfolios.
Forecast inputs considered product type segmentation across robotic cleaners, autonomous devices, manual tools, and semi-automated systems; technology tiers spanning AI-driven, computer vision, remote operated, and sensor-based platforms; and end-user categories including commercial buildings, government structures, residential properties, and industrial facilities. CAGRs were derived from elasticity modeling of labor cost inflation against scaffolding substitution savings, with trajectory validation against EU Green Deal retrofit mandate implementation schedules and OSHA fall-protection standard enforcement intensity.
Practitioners should monitor regulatory enforcement velocity for EU AI Act algorithm transparency requirements and brush assembly supply disruptions from German and Japanese component manufacturers for early signals of forecast deviation. Cross-checking against facility-management outsourcing contract renewal rates in the Netherlands and Belgium is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
United Kingdom Cloud Robotics Market