
 Global Medical Telepresence Robot Market | 2026-2036
Global Medical Telepresence Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Telepresence Robot Market Intelligence
A shortage of specialized clinical staff is reorganizing how hospitals and clinics deliver acute and consultative care. This dynamic creates an opportunity for established telehealth providers like InTouch Health (Teladoc Health), which leverages its extensive network and existing hospital relationships. Ava Robotics Inc. specializes in autonomous mobile robots designed for enterprise environments, including sterile healthcare settings. OhmniLabs, Inc. competes on the basis of rapid, on-demand 3D printing for customized robot production.
Medical telepresence robots are remotely controlled devices, equipped with high-definition cameras and two-way audio systems, facilitating real-time interaction between clinicians and patients. They operate over secure, low-latency networks to enable critical healthcare delivery and diagnostic support from a distance. Mobile robots represent the largest product type, valued for their flexibility in navigating hospital floors. In applications, teleconsultation holds the dominant share, while remote surgery presents a high-growth niche.
Regulatory compliance is critical for market access, with devices needing clearance from bodies like the Food and Drug Administration (FDA) in the United States. In Europe, adherence to the Medical Device Regulation (MDR) is mandatory, while Japan's PMDA sets comparable standards for medical robotics. These frameworks govern electrical safety and data privacy, directly influencing design costs. Future success depends on navigating these complex approvals while advancing robot autonomy and diagnostic capabilities.
Market Dynamics
The convergence of stringent data privacy mandates, such as HIPAA and GDPR, with the need for cross-border medical device clearance is the central force defining robot design, software architecture, and market access strategies for manufacturers.
Growth Catalysts
- Clinical Staff Shortages:A deficit of specialists in nations like Germany and Japan drives telepresence adoption in acute and elderly care to multiply expert reach.
- Teleconsultation Demand:The need to deliver specialist care to rural populations accelerates adoption of mobile robots for remote consultations inside clinics.
- Network Infrastructure:Secure, low-latency networks enable the high-fidelity, real-time communication essential for remote diagnostics and critical patient interaction.
Market Restraints
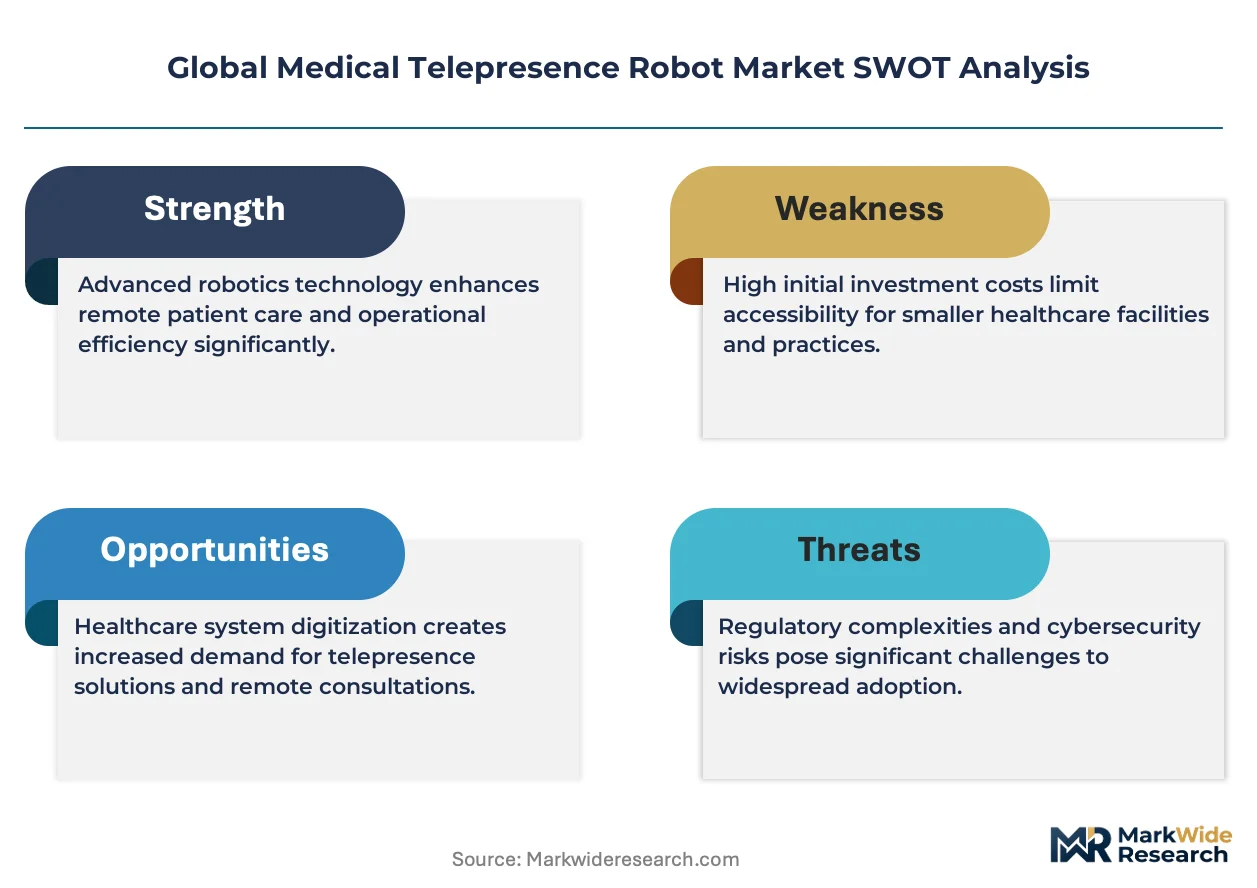
- High Capital Outlay:The substantial upfront cost to purchase and integrate medical-grade robots is a primary adoption barrier for many healthcare providers.
- Complex Regulatory Pathways:Gaining clearance from the FDA or certifying for Europe's MDR is a costly, time-consuming process that delays market entry.
- Data Privacy Compliance:Adhering to patient data rules under HIPAA and GDPR adds significant software development and operational overhead.
Strategic Opportunities
- Aged Care Integration:Expanding into residential elderly care facilities for chronic disease monitoring and virtual consultations represents a major area for growth.
- Remote Surgery Niche:Developing specialized, high-precision robots for the remote surgery market offers a high-value opportunity beyond standard teleconsultation.
- AI-Enabled Diagnostics:Integrating machine learning for autonomous patient data collection and preliminary analysis can significantly increase the platform's clinical value.
Industry Challenges
- System Interoperability:Integrating robot data with legacy hospital IT systems and electronic health records (EHRs) is a major technical hurdle, impeding deployment at scale.
- Clinical Workflow Adoption:Overcoming staff resistance and the need for extensive training to incorporate robots into daily routines is a significant operational barrier to effective use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Telepresence Robot Market |
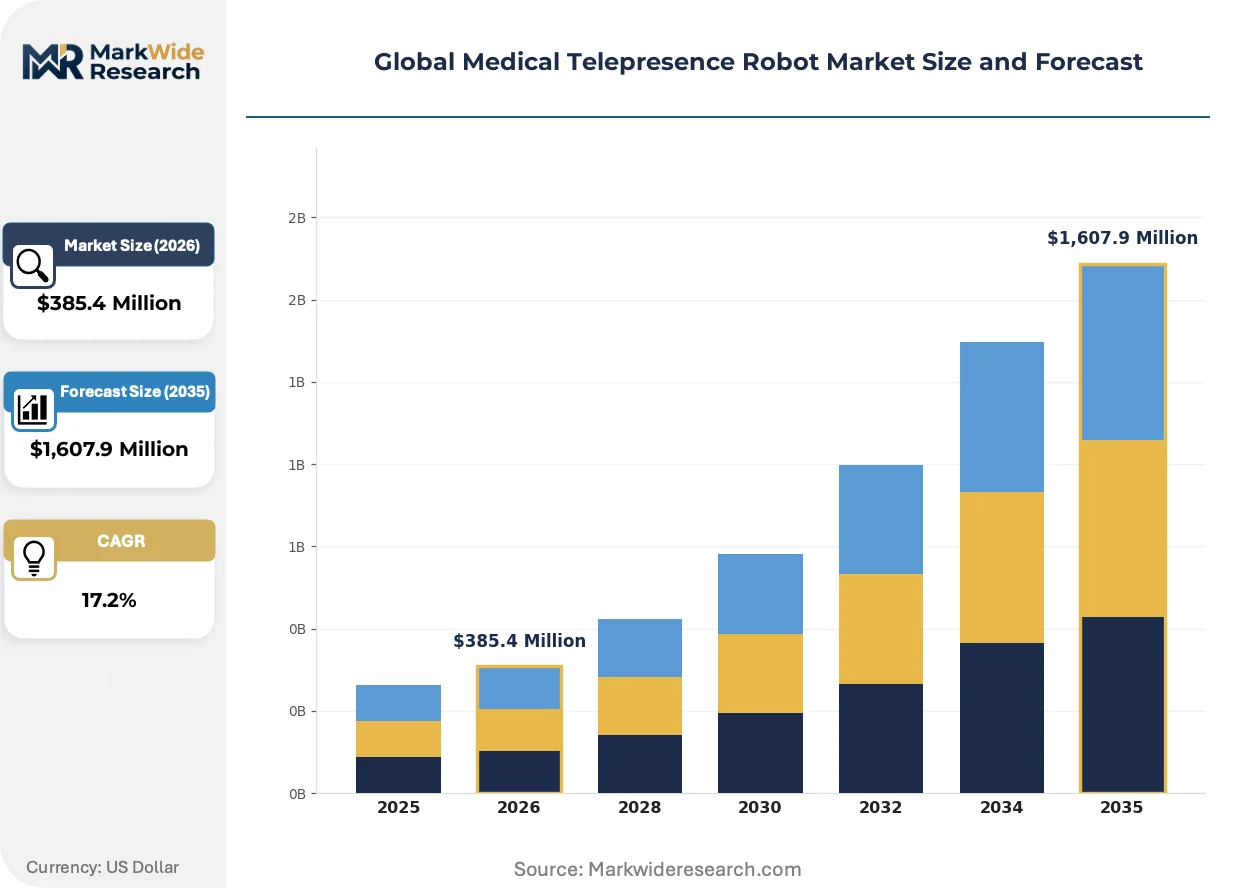
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,607.9 Million |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Stationary Robots, Hybrid Robots, Autonomous Robots Application: Remote Surgery, Patient Monitoring, Teleconsultation, Emergency Response, Medical Training End User: Hospitals, Diagnostic Centers, Rehabilitation Centers, Elderly Care Facilities Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | InTouch Health (Teladoc Health), Ava Robotics Inc., OhmniLabs, Inc., Amy Robotics, Blue Ocean Robotics, AXYN Robotics, Double Robotics, VGo Communications Inc., Xandex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Telepresence Robot Market Strategic Shifts & Innovations
Advancements in autonomy and artificial intelligence are transforming telepresence robots from simple remote communication tools into active participants in clinical workflows. This evolution creates new value propositions for healthcare providers while also introducing new design and regulatory complexities.
Autonomous navigation, enabled by sensor fusion and SLAM algorithms, allows robots to move independently through dynamic hospital environments. Large healthcare systems are adopting these advanced mobile platforms to automate routine rounds and improve logistical efficiency. This capability is bifurcating the market between basic stationary devices and sophisticated, self-driving robots for acute care settings.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence, risk management, and post-market surveillance on manufacturers. This policy increases compliance costs and lengthens development timelines for all medical robotics sold in the EU. Software components are particularly scrutinized, forcing vendors to invest heavily in quality management systems and comprehensive technical documentation.
A shift toward Robotics-as-a-Service (RaaS) and subscription models is changing how healthcare systems acquire this technology. This approach lowers the upfront capital investment for hospitals, converting it into a predictable operational expense and bundling maintenance. This procurement model is most visible in the United States, where large hospital networks seek greater financial flexibility.
Global Medical Telepresence Robot Market Segmentation
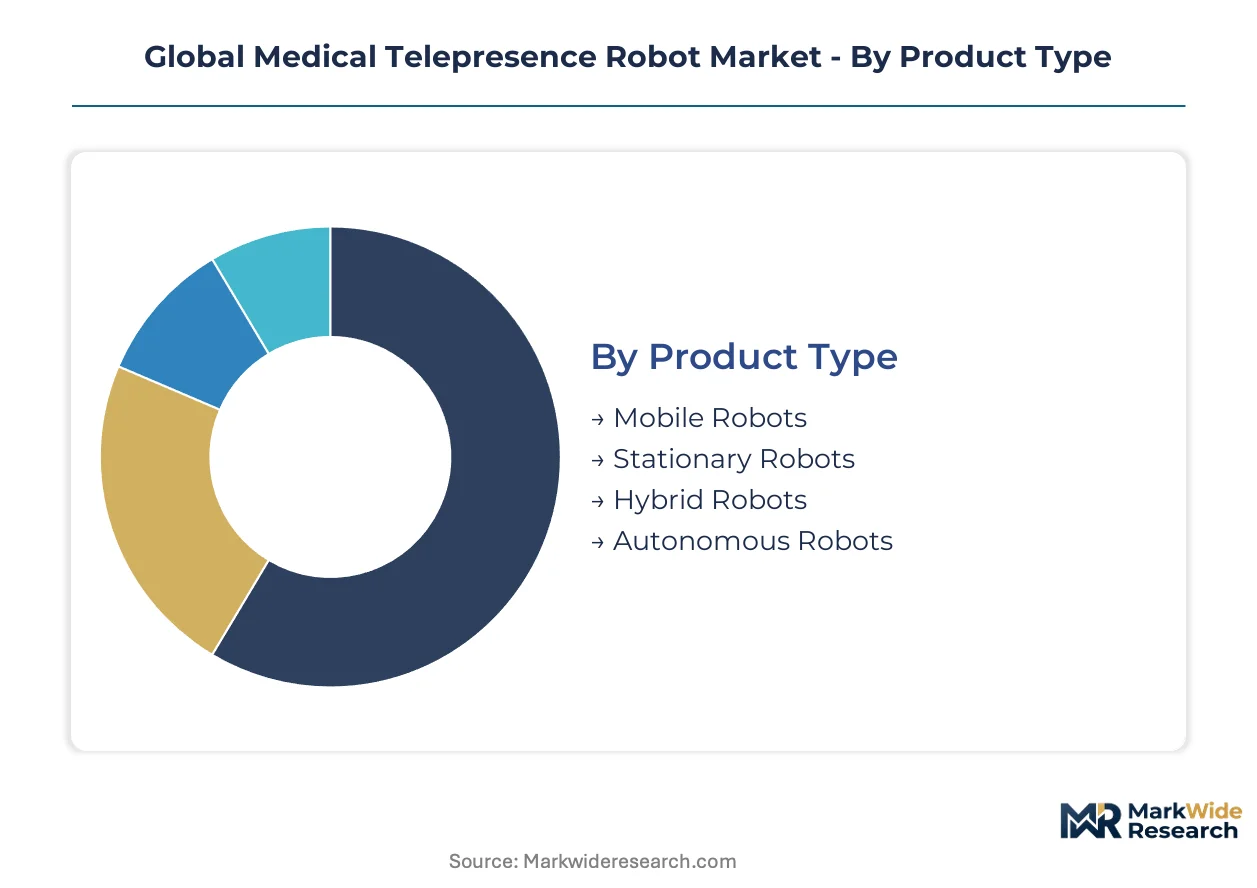
The medical telepresence robot market is structured by distinct product types, diverse applications, and varied end-user environments, each presenting unique deployment considerations. Understanding these segments clarifies the technological requirements and market penetration strategies for manufacturers globally. This segmentation highlights areas of established demand versus emerging opportunities across the healthcare ecosystem.
Product Type:
The geographic spread of medical telepresence robot adoption often dictates the preferred product type, with developed nations favoring advanced autonomous units for complex hospital environments.
- Mobile Robots:These devices offer dynamic movement capabilities, allowing clinicians to navigate hospital corridors and patient rooms remotely. Demand for mobile robots concentrates in countries with high labor costs like the United States and Germany, where they optimize staff efficiency.
- Autonomous Robots:Equipped with advanced navigation and AI, these robots operate independently within defined healthcare settings, performing routine tasks without direct human control. Investment in autonomous robots is accelerating in large hospital networks seeking to automate logistical flows and enhance operational efficiency.
- Stationary Robots:Fixed-position devices provide telepresence capabilities from a single location, often used for remote consultations within a dedicated examination room. These robots see steady demand in smaller clinics and specialized consultation rooms where mobility is not a primary requirement.
- Hybrid Robots:These systems combine aspects of both mobile and stationary units, offering flexible deployment options that can adapt to different clinical scenarios. Hybrid solutions provide versatility for facilities with evolving space and patient interaction needs.
Mobile Robots holds the largest share; momentum sits with Autonomous Robots.
Application:
The utility of medical telepresence robots spans a spectrum of clinical activities, from routine consultations to highly specialized surgical procedures, each demanding specific technical capabilities and regulatory clearances.
- Teleconsultation:This application enables real-time, two-way audio-visual communication between patients and clinicians, facilitating remote diagnostic support and specialist advice. Teleconsultation demand is accelerating to serve rural populations and elderly care facilities, especially in Japan.
- Remote Surgery:High-precision robotic systems allow surgeons to perform complex operations from a distant location, leveraging advanced haptic feedback and imaging technologies. This high-growth niche presents significant value opportunities, particularly in advanced surgical centers.
- Patient Monitoring:Robots equipped with sensors and cameras can remotely track vital signs and observe patient conditions, alerting staff to critical changes. This application improves patient safety and streamlines nursing workflows in acute care settings.
- Emergency Response:Telepresence robots can be deployed in hazardous environments or disaster zones to assess situations and provide initial medical guidance without endangering human responders. These units enhance safety and extend reach during crises.
- Medical Training:Robots simulate patient scenarios for educational purposes, allowing medical students and practitioners to practice procedures and refine clinical skills remotely. This application supports continuous professional development.
Teleconsultation commands the largest segment; Remote Surgery is expanding most quickly.
End User:
Different healthcare providers integrate medical telepresence robots based on their operational scale, patient demographics, and specific clinical needs, influencing the feature sets and deployment models required.
- Hospitals:Large medical institutions utilize telepresence robots for a wide range of applications, including specialist consultations, remote patient rounds, and even surgical assistance. Hospitals in the United States represent a significant market due to their complex operational needs and high patient volumes.
- Elderly Care Facilities:These residential settings adopt robots for chronic disease monitoring, virtual doctor visits, and social interaction, addressing staff shortages and improving resident well-being. Integration into elderly care facilities is a major growth area, especially in aging societies like Germany.
- Diagnostic Centers:Specialized centers use telepresence robots to facilitate remote expert consultations for complex imaging results or pathology samples, extending specialist reach. These centers prioritize high-definition imaging and secure data transmission.
- Rehabilitation Centers:Robots assist in physical therapy sessions, monitor patient progress, and provide interactive exercises under remote supervision. These applications enhance patient engagement and treatment consistency.
Hospitals holds the largest share; Elderly Care Facilities is climbing the fastest.
Deployment:
The deployment model for medical telepresence robots significantly impacts their scalability, data security, and integration with existing IT infrastructure, guiding software architecture decisions for manufacturers.
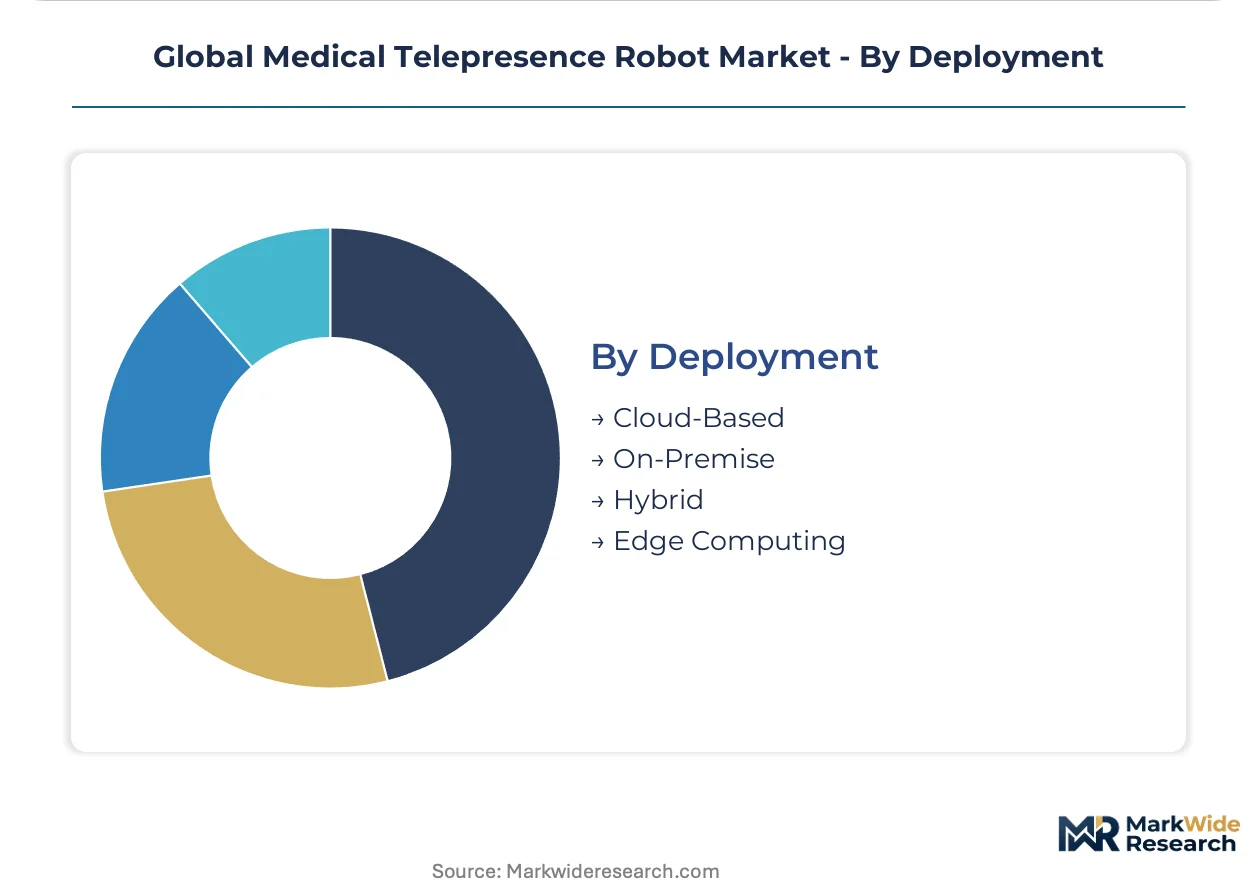
- Cloud-Based:This model leverages remote servers for data storage and processing, offering scalability, accessibility, and reduced upfront IT infrastructure costs for healthcare providers. Cloud deployment aligns with stringent data privacy mandates like GDPR in Europe.
- Edge Computing:Processing data closer to the source, at the "edge" of the network, reduces latency and enhances real-time responsiveness, crucial for critical applications like remote surgery. Edge computing solutions are gaining traction for high-fidelity diagnostic support.
- On-Premise:Systems hosted directly within the healthcare facility provide maximum control over data security and network performance, often preferred by institutions with strict compliance requirements. This model requires substantial internal IT resources for maintenance.
- Hybrid:Combining elements of both cloud and on-premise solutions, this model offers flexibility, allowing sensitive data to remain local while leveraging cloud resources for scalability. Hybrid deployments balance security with operational agility.
Cloud-Based holds the largest share; Edge Computing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global medical telepresence robot market exhibits a varied consumption mix, with developed nations prioritizing advanced autonomous units for complex hospital environments, while other regions concentrate on basic teleconsultation. High labor costs in countries like the United States and Germany drive the demand for efficiency-enhancing robotic solutions. Regulatory frameworks significantly influence market entry and product development across these diverse geographies.
United States
High labor costs and the extensive network of large hospital systems drive demand for advanced mobile and autonomous robots for specialist consultations and patient monitoring. HIPAA mandates stringent data security, influencing software architecture and cloud deployment strategies. Major medical technology clusters, particularly around Boston and California, foster significant innovation in robot design and AI integration.
Germany
An aging population and persistent clinical staff shortages accelerate the adoption of telepresence robots in elderly care facilities and acute settings. Adherence to the Medical Device Regulation (MDR) is mandatory, requiring robust clinical evidence and risk management. Key medical technology hubs like Munich and Stuttgart are actively developing and integrating robotic solutions into healthcare workflows.
Japan
The rapidly aging demographic and the need to deliver specialist care to rural populations propel the teleconsultation segment. PMDA sets rigorous standards for medical robotics, influencing product design and market access. Research institutions and technology firms in Tokyo and Kyoto lead advancements in autonomous navigation and human-robot interaction for healthcare applications.
China
Expanding healthcare access and addressing disparities between urban and rural medical services stimulate demand for telepresence robots, particularly for remote diagnostics. NMPA clearance is essential for market entry, governing device safety and efficacy. Medical device parks in Shanghai and Shenzhen are becoming centers for manufacturing and deploying innovative robotic solutions.
United Kingdom
The National Health Service (NHS) focuses on efficiency gains and extends specialist reach through teleconsultation and remote patient monitoring. GDPR compliance is critical for all data handling, impacting cloud deployment and software development. London's health tech ecosystem actively supports companies developing and integrating telepresence solutions into primary and secondary care.
Global Medical Telepresence Robot Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the medical telepresence robot market. This market structure reflects a blend of established healthcare technology providers and agile robotics innovators. Strategic archetypes include comprehensive telehealth platform providers, specialized autonomous robot developers, and custom manufacturing solutions. Dominant competitive moves involve strategic partnerships for market access and continuous technological innovation to enhance capabilities.
Within the comprehensive telehealth platform segment, InTouch Health (Teladoc Health) exemplifies leveraging existing hospital relationships and extensive networks. Ava Robotics Inc. represents specialized autonomous mobile robot development for enterprise environments. OhmniLabs, Inc. occupies a unique position as a custom robot production specialist, utilizing rapid 3D printing.
| Leading Market Players |
|---|
| InTouch Health (Teladoc Health) |
| Ava Robotics Inc. |
| OhmniLabs, Inc. |
| Amy Robotics |
| Blue Ocean Robotics |
| AXYN Robotics |
| Double Robotics |
| VGo Communications Inc. |
| Xandex Inc. |
| Others |
Cost & Logistics Intelligence
Subscription-based service agreements in the medical telepresence robot market lock in both supply access for ongoing maintenance and provide greater price visibility for healthcare providers. This model mitigates high upfront capital outlays, particularly for smaller facilities.
Pricing Analysis
Subscription-based service agreements dominate the market, converting capital expenditure into predictable operational costs. Price differentiation stems from the level of autonomy and specialized features, such as advanced AI diagnostics, and the breadth of post-sales support. Pricing pressure stems from the need to lower initial adoption barriers for budget-constrained facilities, especially within elderly care. Large hospital networks, seeking high-value solutions for labor cost reduction, exhibit lower price sensitivity for advanced autonomous platforms.
Supply Chain Analysis
Access to specialized microcontrollers and high-definition optical components represents a chokepoint for advanced medical telepresence robot manufacturing. Geographic supply concentrates in China for general electronics, with precision components often sourced from Japan and Germany, while advanced AI processors originate from the United States. Single-source vulnerability for specific sensor technologies or secure communication modules poses a structural risk. Distribution runs through direct sales channels to large hospital systems and specialized medical technology distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the increasing demand for specialized care delivery models due to persistent clinical staff shortages. These shifts create distinct niches for targeted robotic solutions.
For Market Incumbents:Consolidate existing hospital relationships by expanding Robotics-as-a-Service (RaaS) offerings, bundling maintenance and software updates into flexible contracts. Acquire specialist firms developing advanced AI for diagnostic support or autonomous navigation to counter emerging technological threats. Leverage extensive networks and R&D capabilities to integrate next-generation sensor technology, enhancing clinical utility and maintaining market leadership against agile new entrants.
For New Entrants and Emerging Players:Anchor in specific high-growth niches, such as remote surgery or chronic disease monitoring in elderly care facilities. The elderly care segment, with its clear need for virtual consultations, represents the most penetrable market. Focus on achieving rapid regulatory clearance, like Europe's MDR, for a targeted, high-impact application. A go-to-market strategy emphasizing demonstrated ROI for staff efficiency or patient outcome improvement will accelerate adoption.
For Investors and Strategic Acquirers:Capital is best deployed toward vertically integrated specialists in AI-driven autonomy or niche surgical robotics, which offer high intellectual property value and strong growth trajectories. The long-term viability of this market is strong, given global demographic shifts and healthcare labor shortages. An acquisition target archetype involves companies with proven regulatory compliance and a strong pipeline of AI-enabled diagnostic features. Revision becomes warranted when successful FDA or MDR clearances for advanced autonomous diagnostic features cross critical thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-enabled Diagnostic Module | Introduces advanced capabilities, enhancing robot utility in diagnostic centers. |
| Strategic Partnership: Hospital System for Pilot Deployment | Validates clinical efficacy and integrates solutions into real-world healthcare workflows. |
| Acquisition of Specialist Firm: Advanced Sensor Technology | Secures critical intellectual property and strengthens core technological competencies. |
| CE Marking Pathway: Market Access in Europe | Ensures compliance with stringent Medical Device Regulation for European expansion. |
| Robotics-as-a-Service Expansion: Lowering Upfront Capital Barriers | Increases accessibility for smaller healthcare providers, accelerating market penetration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Interviews included hospital administrators, clinical specialists, elderly care facility managers, robot engineers, and regulatory experts. Secondary data sources comprised FDA, MDR, and PMDA guidelines, healthcare IT journals, company financial reports, and medical device databases. This approach enabled bottom-up and top-down triangulation of market insights.
Forecasting across the projection horizon involved a robust analytical framework, segmenting the market by product type, application, end-user environment, deployment model, and regional regulatory landscape. Compound annual growth rates were derived from historical market data, observed adoption rates, and anticipated technological advancements. Industry-specific forecast inputs included clinical staff shortage projections and healthcare infrastructure investment trends across key geographies.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and continued investment in digital health infrastructure; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological maturation and market acceptance. Revision becomes warranted when unforeseen changes in medical device regulations or major cybersecurity breaches cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Middle East and Africa Underwater Robotics Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Thailand Cloud Robotics Market