
 US Content Services Platform Market | 2026-2036
US Content Services Platform Market Size, Share, and Industry Trends Forecast 2026-2036
US Content Services Platform Market Insights
API-first architecture is broadening platform economics as lightweight integration frameworks displace monolithic enterprise content management stacks. Microsoft Corporation leverages its Azure cloud backbone to anchor hybrid deployment pipelines across federal and state agencies. Adobe Inc. differentiates through creative workflow integration, while Hyland Software, Inc. specializes in vertical-specific compliance modules for healthcare and insurance sectors.
A content services platform is a cloud-native software architecture that unifies document management, workflow automation, and records governance through RESTful APIs and microservices, typically processing structured and unstructured data at petabyte scale with sub-second retrieval latency for mission-critical operations. Cloud-based deployment leads segment economics due to elastic scaling demands from remote workforces, while API integration captures the fastest expansion as enterprises dismantle legacy ECM silos. Healthcare end users represent the deepest margin pool given HIPAA audit trail requirements and long-term records retention obligations.
The Federal Risk and Authorization Management Program (FedRAMP) shapes vendor eligibility for government contracts, while the SEC's electronic recordskeeping rules for broker-dealers mandate immutable audit architectures that elevate platform standards. State-level privacy laws, including the California Consumer Privacy Act, force cross-border data handling protocols that increase implementation complexity. Stakeholders must monitor emerging state AI governance frameworks that will redefine automated content classification liabilities.
Market Dynamics
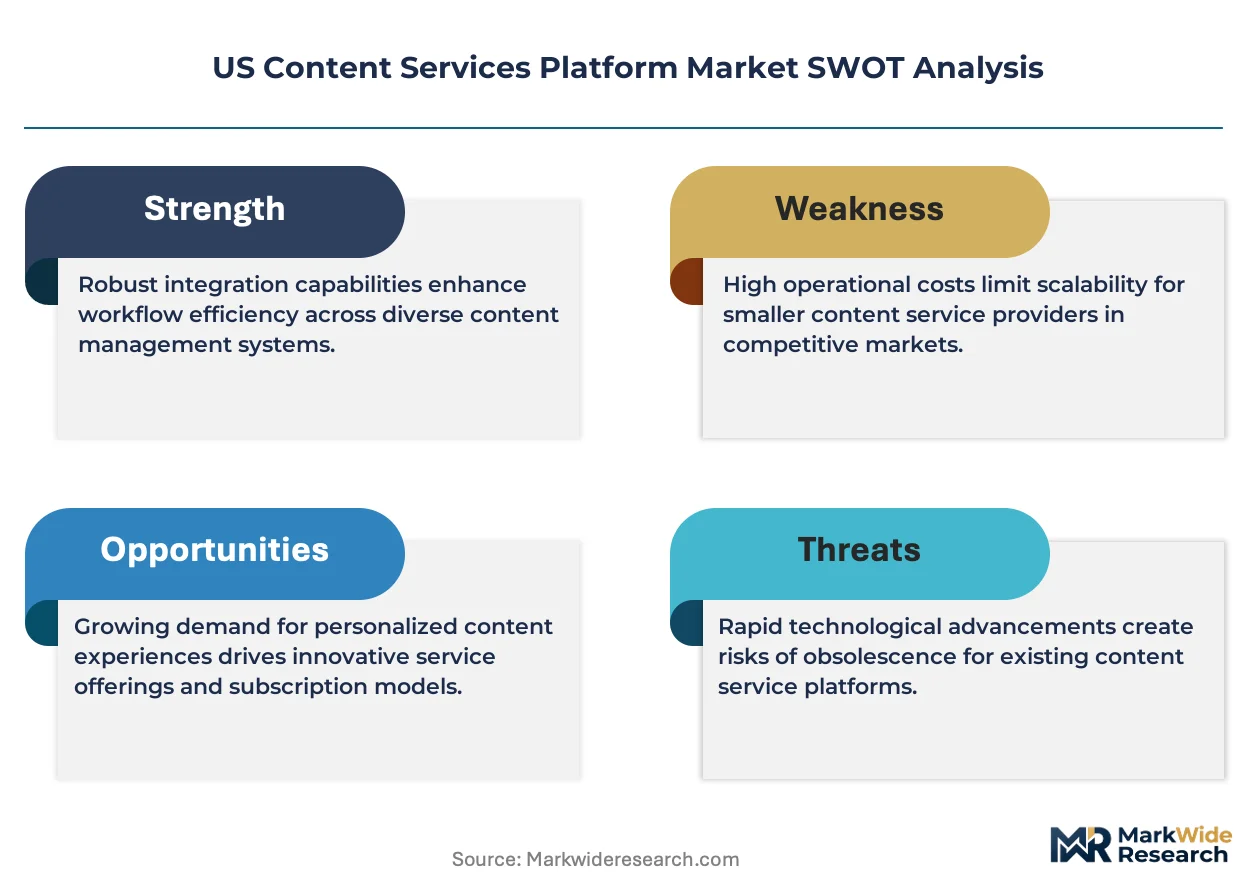
FedRAMP authorization requirements are restructuring vendor eligibility for federal contracts, forcing platform providers to re-architect security postures around zero-trust frameworks and immutable audit trails.
Growth Catalysts
- HIPAA Modernization Rules:Federal healthcare agencies are mandating digitization timelines that compress procurement cycles for compliant content platforms.
- California's Enterprise Corridor:BFSI and healthcare providers in the San Francisco-San Jose technology cluster are consolidating vendor relationships around API-native architectures.
- Microservices Migration:Enterprises are dismantling monolithic ECM stacks through RESTful API frameworks that enable elastic workload orchestration.
Market Restraints
- Cloud Concentration Risk:Three hyperscale providers dominate federal-compliant infrastructure, creating single-point-of-failure exposure for mission-critical deployments.
- State Privacy Fragmentation:California Consumer Privacy Act compliance obligations conflict with cross-border data handling protocols, forcing redundant architecture investments.
- Legacy Integration Debt:Technical limitations around on-premise document repositories impose latency penalties on hybrid cloud migrations.
Strategic Opportunities
- AI Governance Frameworks:Emerging state-level automated content classification regulations will create first-mover advantages for platforms with embedded machine learning audit trails.
- Texas Healthcare Expansion:Underserved hospital systems in the Dallas-Houston corridor present whitespace for vertical-specific compliance modules.
- API Monetization Channels:Developer marketplace distribution models are unlocking new revenue streams beyond traditional enterprise licensing.
Industry Challenges
- FedRAMP Authorization Timelines:Certification backlogs extend sales cycles by 12-18 months for vendors seeking federal contract eligibility.
- Zero-Trust Architecture Skills:Talent scarcity around cloud security engineering and immutable ledger implementation is constraining platform roadmap execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Content Services Platform Market |
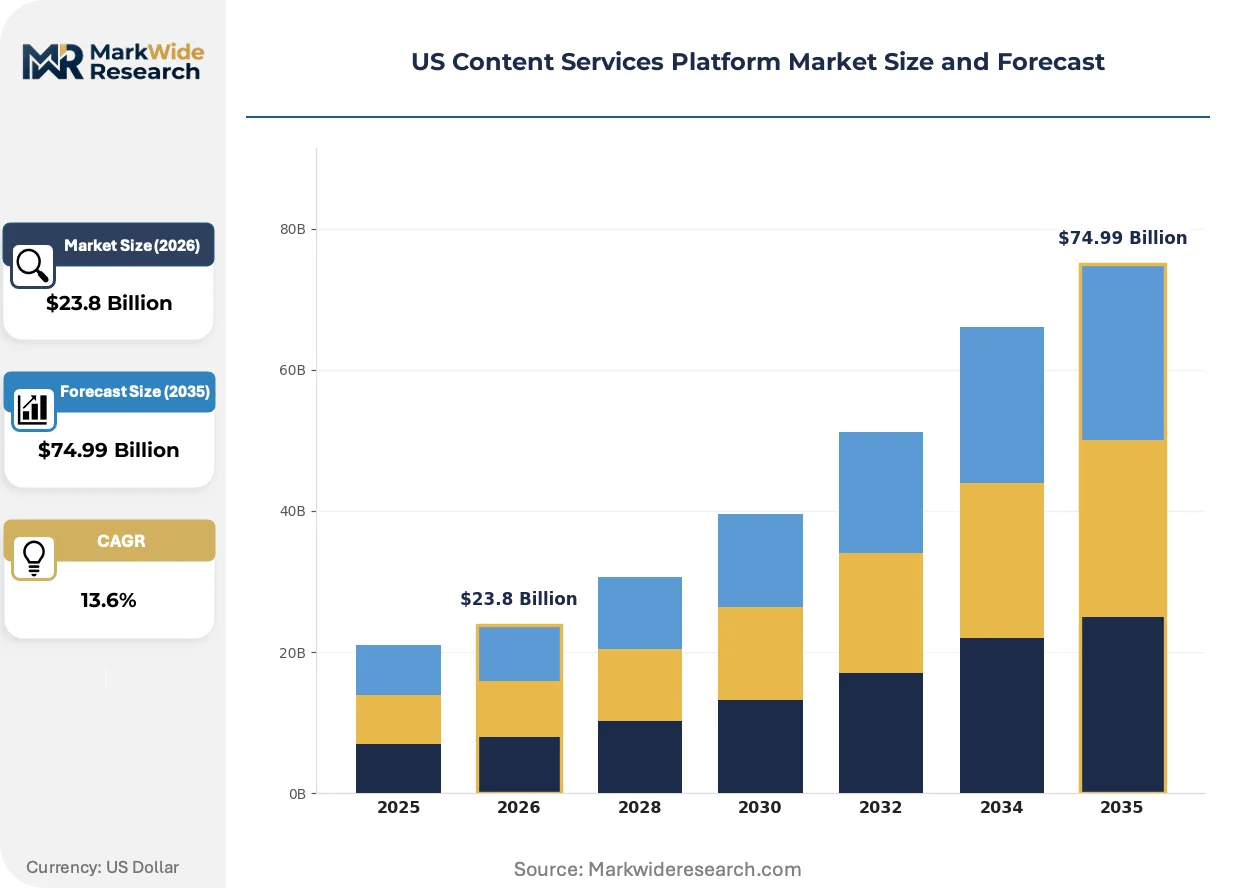
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $74.99 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-Based, On-Premises, Hybrid, Managed Service End User: Healthcare, BFSI, Retail, Education Content Type: Text, Video, Audio, Image Integration Level: API Integration, Full Integration, Limited Integration, No Integration |
| Companies Covered | Box, Inc., Adobe Inc., Microsoft Corporation, Laserfiche, Oracle Corporation, IBM Corporation, Hyland Software, Inc., M-Files, OpenText Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Content Services Platform Market Trends and Innovations
API-first architectures are compressing platform economics while regulatory mandates around immutable records are elevating technical standards. Three forces are actively restructuring competitive positioning.
Blockchain-anchored audit trails are decentralizing records governance across healthcare and financial services workflows. Hospital systems in Massachusetts and Illinois are piloting distributed ledger verification for HIPAA-compliant document provenance. This architecture is decentralizing trust mechanisms away from centralized vendor databases toward cryptographically verified multi-party consensus.
SEC electronic recordskeeping rules for broker-dealers are mandating write-once-read-many storage architectures with sub-second retrieval latency. Compliance teams at regional banks are re-platforming around immutable object stores to satisfy audit trail requirements. The broker-dealer segment is responding by consolidating vendor relationships around FedRAMP-authorized providers with pre-certified infrastructure.
Subscription consumption models are displacing perpetual licensing across state government procurement offices. Procurement officers in Colorado and Virginia are piloting usage-based pricing for document processing workloads. This shift is most visible in municipal healthcare exchanges where seasonal enrollment spikes demand elastic capacity without capital commitment.
US Content Services Platform Market Segmentation
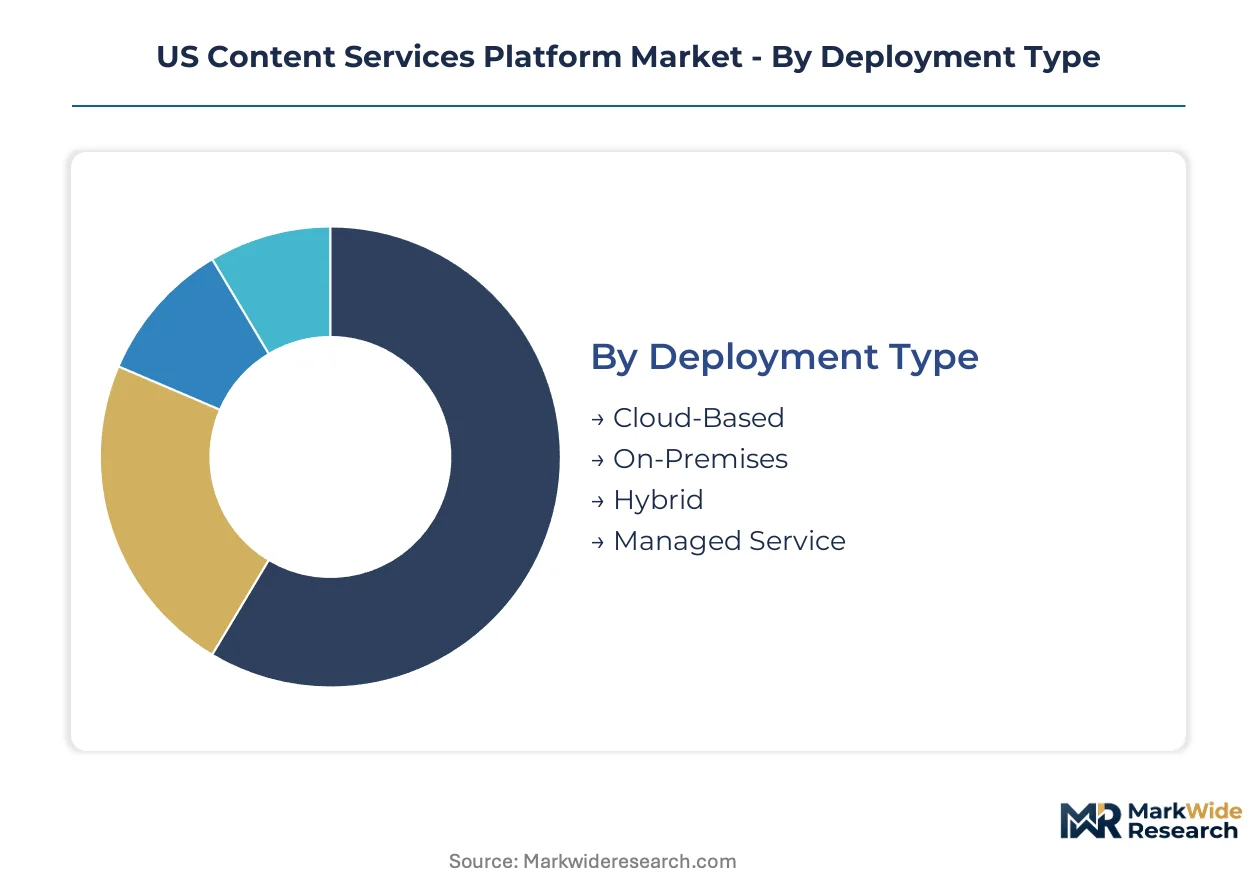
Platform procurement patterns diverge sharply across deployment models and vertical applications. HIPAA modernization mandates and API-first migration strategies are redefining how buyers evaluate segment trade-offs between compliance depth and architectural flexibility.
Deployment Type:
Cloud-native elasticity separates architectures that scale with federal workload spikes from fixed-capacity alternatives.
- Cloud-Based:Elastic infrastructure provisions compute resources on-demand for seasonal enrollment surges at California health exchanges. Federal agencies favor this model for FedRAMP-authorized environments with zero-trust security postures.
- Hybrid:Split-stack architectures synchronize on-premise legacy repositories with cloud-based processing layers, addressing latency constraints in Texas hospital systems with decade-old document stores. This deployment captures procurement momentum from risk-averse CIOs seeking staged migration paths.
- On-Premises:Air-gapped installations persist in defense-adjacent facilities requiring physical data sovereignty.
- Managed Service:Third-party operational control appeals to municipal governments lacking cloud engineering benches.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Vertical compliance burdens create tiered pricing power across regulated and unregulated buyer categories.
- Healthcare:HIPAA audit trail mandates and long-term records retention obligations drive premium platform configurations. Hospital systems in Massachusetts and Illinois pilot blockchain-anchored document provenance to satisfy federal digitization timelines.
- BFSI:SEC electronic recordskeeping rules for broker-dealers mandate immutable write-once-read-many storage with sub-second retrieval. Regional banks in California's enterprise corridor consolidate vendor relationships around FedRAMP-authorized infrastructure.
- Retail:Seasonal transaction spikes demand elastic document processing without capital commitment.
- Education:State university systems prioritize cost containment over compliance depth in procurement evaluations.
Healthcare leads on margin; BFSI leads on procurement velocity.
Content Type:
Processing architecture varies with data structure complexity and retrieval latency requirements.
- Text:Structured document repositories dominate federal healthcare digitization workflows, with optical character recognition pipelines extracting metadata from legacy paper records. Massachusetts hospital systems deploy machine learning classification for automated routing of clinical notes.
- Video:Surveillance and telemedicine archives require petabyte-scale object storage with frame-level indexing. Texas healthcare expansion corridors are piloting compressed encoding standards for long-term retention compliance.
- Audio:Call center recordings and voice-to-text transcription drive niche storage economics.
- Image:Medical imaging DICOM integration creates specialized workflow requirements.
Text leads on volume; Video leads on infrastructure investment intensity.
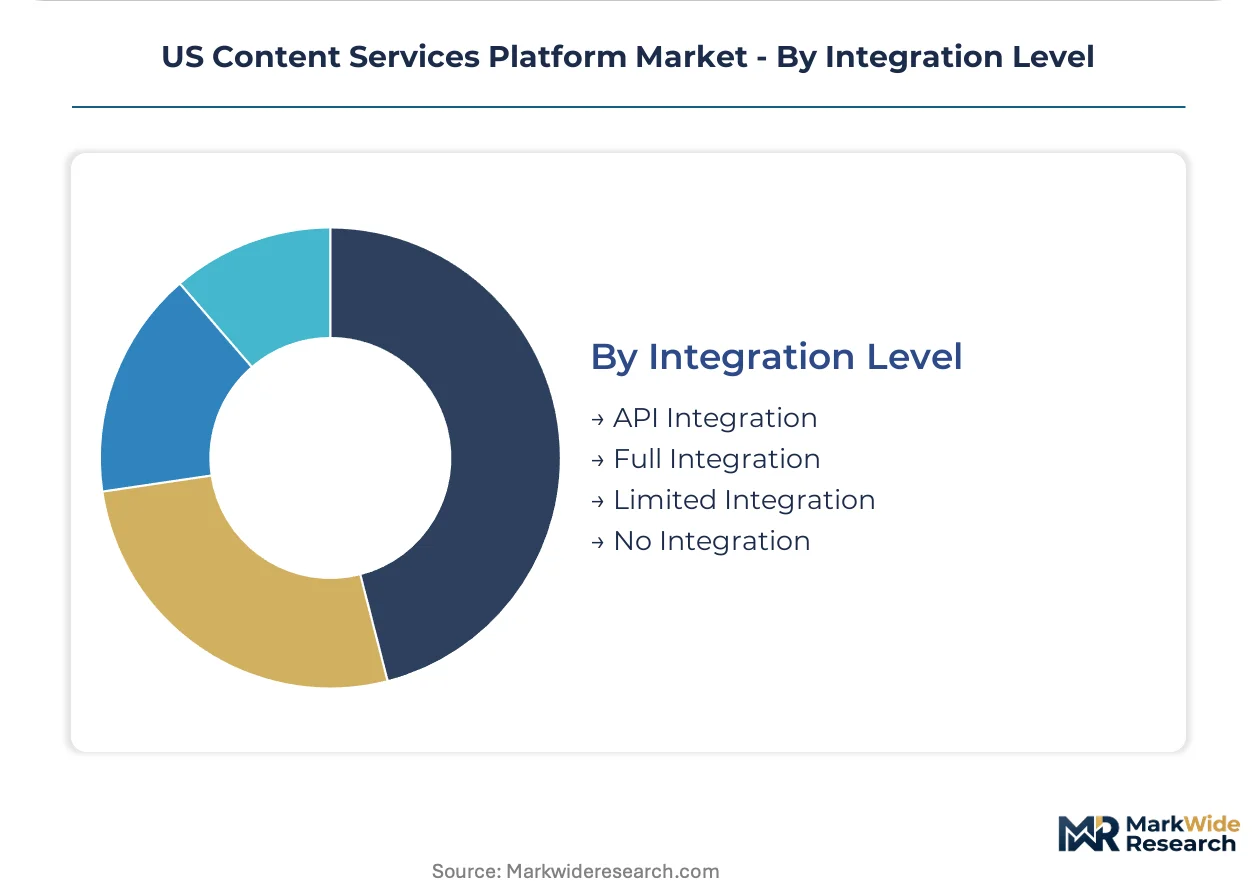
Integration Level:
API maturity determines platform extensibility and ecosystem lock-in exposure for enterprise buyers.
- API Integration:RESTful microservices frameworks enable elastic workload orchestration as enterprises dismantle monolithic ECM stacks. California BFSI providers consolidate procurement around lightweight integration architectures that reduce vendor switching costs.
- Full Integration:Pre-built connectors to ERP and CRM systems accelerate deployment timelines for mid-market buyers. Colorado state procurement offices pilot usage-based pricing models contingent on seamless interoperability with existing infrastructure.
- Limited Integration:Point-to-point connectors satisfy single-workflow requirements without platform commitment.
- No Integration:Standalone deployments persist in legacy technology environments with minimal IT resources.
API Integration leads on strategic priority; Full Integration leads on near-term revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's enterprise technology corridor anchors platform procurement velocity, with San Francisco-San Jose metroplex hospitals and financial institutions driving API-native architecture consolidation. State-level privacy mandates and federal healthcare digitization timelines compress vendor selection cycles across the Western region.
California
BFSI providers and healthcare systems in the San Francisco-San Jose corridor consolidate procurement around FedRAMP-authorized cloud infrastructure. CCPA compliance obligations force redundant data handling architecture investments. Silicon Valley technology firms pilot blockchain-anchored document provenance for HIPAA audit trails.
Texas
Underserved hospital systems in the Dallas-Houston corridor present whitespace for vertical-specific compliance modules. State procurement offices explore usage-based pricing for seasonal enrollment workloads. Austin-based technology vendors target hybrid deployment pipelines for legacy repository synchronization.
Massachusetts
Hospital systems pilot distributed ledger verification for clinical document provenance under federal digitization mandates. State university procurement prioritizes cost containment over compliance depth. Greater Boston healthcare clusters demand sub-second retrieval latency for mission-critical imaging archives.
Illinois
Chicago-area healthcare networks deploy machine learning classification for automated routing of clinical notes. State-level Medicaid expansion drives elastic capacity requirements without capital commitment. Regional banks re-platform around immutable object stores for SEC electronic recordskeeping compliance.
Colorado
Municipal healthcare exchanges pilot usage-based pricing models for seasonal enrollment spikes. State procurement offices evaluate API monetization channels beyond traditional enterprise licensing. Denver technology corridors attract cloud engineering talent for zero-trust security implementation.
US Content Services Platform Market Competitive Landscape
Global majors compete with regional champions across federal compliance certification and API-native architecture depth. The vendor base stratifies between hyperscale cloud providers with pre-authorized infrastructure and vertical specialists with embedded healthcare compliance modules. Three archetypes dominate: platform conglomerates with ecosystem lock-in, compliance-first specialists with FedRAMP pedigree, and API-native challengers with microservices orchestration. Competitive moves center on M&A for zero-trust security capabilities and strategic partnerships for state-level procurement channel access.
Within the platform conglomerate tier, Microsoft Corporation and Adobe Inc. anchor hybrid deployment pipelines across federal and state agencies. Oracle Corporation exemplifies the compliance-first archetype with immutable audit trail architectures. Hyland Software, Inc. occupies a specialist position in vertical-specific modules for healthcare and insurance sectors. These three entities represent distinct competitive vectors: cloud backbone dominance, creative workflow integration, and regulated industry depth.
| Leading Market Players |
|---|
| Box, Inc. |
| Adobe Inc. |
| Microsoft Corporation |
| Laserfiche |
| Oracle Corporation |
| IBM Corporation |
| Hyland Software, Inc. |
| M-Files |
| OpenText Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud compute pricing indices cascade through vendor cost structures into three-tier subscription tiers separating FedRAMP-authorized premium deployments from standard API-native configurations and economy managed-service offerings. Input cost volatility in semiconductor memory and network bandwidth feeds directly into platform margin compression, forcing vendors to rebalance service-level guarantees against price positioning.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers dominates platform economics, with hyperscaler rate adjustments flowing into vendor pricing within one to two quarters. Pricing stratifies across premium FedRAMP-authorized tiers, standard HIPAA-compliant configurations, and economy municipal service levels, with certification depth and zero-trust architecture maturity as primary differentiation drivers. Cost compression in the economy tier is intensifying because municipal buyers lack procurement sophistication to evaluate security postures. Healthcare systems demonstrate lowest price sensitivity given audit trail liability exposure, while state university procurement offices drive hardest bargain negotiations.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premise document repositories create specialized data migration service revenue streams, as Texas hospital systems extract value from decade-old tape archives before cloud transition. Supply concentration rests on hyperscale infrastructure in the United States, with secondary dependencies on Taiwan for server components and South Korea for memory modules. Single-source vulnerability around FedRAMP-authorized cloud regions creates mission-critical deployment risk. Distribution runs through direct enterprise sales teams for federal contracts and channel partners for state and municipal procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory digitization mandates generate predictable procurement cycles with limited demand elasticity.
For Market Incumbents: Lock in federal contract renewals through zero-trust certification investments before authorization backlogs clear. Deepen API marketplace distribution to defend against emerging microservices challengers. FedRAMP authorization scarcity creates durable competitive moats for pre-certified infrastructure providers. For New Entrants and Emerging Players: The mid-market price-point gap between premium FedRAMP tiers and economy municipal offerings presents whitespace for vertical-specific compliance modules. Target underserved hospital systems in Texas and Colorado with hybrid deployment expertise. Go-to-market leverage rests on developer ecosystem partnerships rather than direct sales capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with API-native challengers possessing embedded machine learning audit trails ahead of state AI governance framework implementation. Five-to-ten year viability favors platforms with demonstrated federal procurement channel access. Monitor FedRAMP authorization queue clearance rates as inflection signal for competitive intensity normalization.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks federal healthcare and BFSI procurement channels with 12-18 month sales cycle compression. |
| API Marketplace Development | Creates developer-driven distribution beyond traditional enterprise licensing for California BFSI buyers. |
| Vertical Compliance Module Expansion | Captures Texas hospital system whitespace with HIPAA-specific workflow automation. |
| Strategic Partnership with Hyperscalers | Secures pre-authorized infrastructure access reducing zero-trust architecture implementation risk. |
| Blockchain-Anchored Audit Trail Pilot | Positions for SEC electronic recordskeeping rule expansion beyond broker-dealer segment. |
Research Methodology
Bottom-up healthcare and BFSI procurement modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, federal procurement officers, HIPAA compliance leads, and channel integration specialists combined with secondary validation against SEC filings, FedRAMP authorization databases, state procurement records, and hospital system RFP archives. Triangulation between vendor-reported deployment metrics and end-user platform adoption surveys ensures data integrity.
Input-output matrix framing connects cloud infrastructure capex cycles to platform subscription revenue recognition patterns across the projection horizon. Segmentation dimensions modeled include deployment architecture, vertical compliance burden, integration complexity, and regional procurement maturity. CAGRs derive from elasticity-adjusted adoption curves applied to federal digitization mandate timelines. Forecast inputs incorporate HIPAA modernization rule implementation velocity and FedRAMP authorization queue dynamics.
Caveats apply where FedRAMP certification backlogs or state AI governance framework delays could materially shift the outlook. Practitioners should monitor emerging state privacy law fragmentation and hyperscaler concentration risk for early signals of vendor selection pattern disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Identity Resolution Software Market
Software & Services
PCB CAD Software Market
Software & Services
Device Tracking Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
ITSM Market
Software & Services
Lead Management Software Market
Software & Services
3PL Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
SAP HANA and S4HANA Market
Software & Services
Business Rules Management System Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Webcasting Software Market
Software & Services
High Education Software Market
Software & Services
Collaboration Software Market