
 Metal Recycling Software Market | 2026-2036
Metal Recycling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Recycling Software Market Insights
German steel recyclers is repositioning toward cloud-native platforms that connect yard operations with mill scheduling systems. AMCS leverages its ERP heritage to anchor complex multi-site recycling chains across European ports. ScrapRight competes on price-transparent modules built for mid-tier scrap dealers in the US Midwest. GreenSpark differentiates through AI-powered material grading that reduces manual assay dependency at inbound scales.
Metal recycling software coordinates the tracking, valuation, and logistics of ferrous and non-ferrous scrap streams through modules handling weighbridge integration, spectroscopy data ingestion, and outbound shipment documentation. Cloud-based deployment is gaining share fastest among scrap dealers seeking mobile yard access without server maintenance overhead, while ERP solutions remain the margin pool for vendors serving integrated steel producers with multi-entity consolidation needs. Inventory management modules show structural growth where just-in-time mill feedstock contracts require real-time scrap availability visibility.
The EU Green Deal and REACH compliance frameworks mandate mass-balance documentation for recycled content claims, pushing software vendors to embed audit-trail functionality. EPA hazardous waste manifest rules in the US and China's dual carbon goals enforced by MEE both tighten emissions-linked scrap processing standards. Stakeholders must monitor how carbon-border adjustment mechanisms reshape the economic logic of cross-border scrap movements and the software features required to certify origin and processing history.
Market Dynamics
Cloud-native deployment is compressing the competitive window for metal recycling software vendors as scrap dealers abandon on-premise servers for mobile-first yard management platforms.
Growth Catalysts
- EU Green Deal mass-balance mandates:Steel mills and aluminum smelters across Germany, France, and Italy now require software that embeds audit-trail functionality for recycled content claims, forcing procurement upgrades.
- Just-in-time mill feedstock contracts:Real-time inventory visibility modules are becoming standard where steel producers in the Rhine-Ruhr corridor synchronize scrap availability with blast furnace scheduling.
- Spectroscopy data ingestion:Handheld XRF and LIBS devices at inbound scales are automating material grading, reducing assay turnaround from hours to minutes at high-volume yards.
Market Restraints
- Legacy ERP integration costs:Mid-tier scrap dealers face capital barriers when connecting new cloud modules to decades-old on-premise accounting systems, slowing replacement cycles.
- Input cost volatility in ferrous scrap:Price swings in shredded auto scrap and heavy melt compress margins, making software ROI calculations unstable for smaller operators.
- Technical limitation in alloy identification:Current spectroscopy libraries struggle with mixed-grade aluminum and certain stainless steel series, requiring manual override that defeats automation gains.
Strategic Opportunities
- Carbon-border adjustment mechanisms:The EU's CBAM is creating demand for origin-certification features that document processing history and emissions intensity of imported scrap metal.
- AI-powered predictive logistics:Converging machine learning with weighbridge and railcar tracking enables scrap dealers to pre-position inventory before mill procurement calls.
- Underpenetrated secondary aluminum sector:Smelters in Spain and Poland lag Northern European peers in software adoption, presenting white-space for vendors with multilingual support.
Industry Challenges
- Specialized technician scarcity:Yards struggle to hire staff capable of calibrating spectroscopy hardware and troubleshooting API connections between scales and cloud platforms.
- REACH compliance documentation:The complexity of tracking hazardous substance thresholds across mixed scrap streams extends software implementation timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Recycling Software Market |
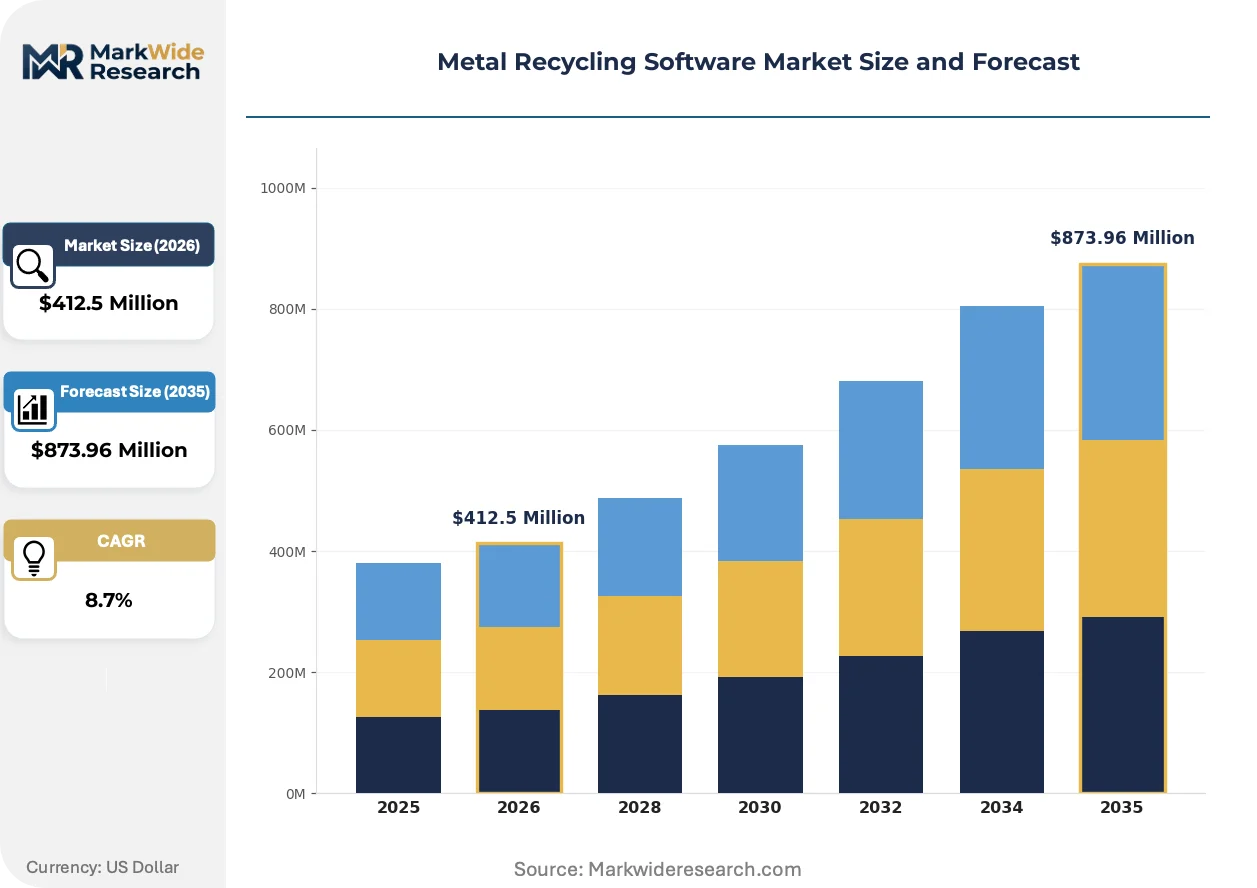
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ERP Solutions, CRM Solutions, Inventory Management, Data Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Recycling Facilities, Scrap Dealers, Manufacturers, Waste Management Companies Integration Level: Standalone, Integrated, Custom Solutions, Platform-as-a-Service |
| Companies Covered | AMCS, Yard Wizard, Scrap Dragon, cieTrade, GreenSpark, ReMatter, MorTrack, MetalCalc, ScrapRight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Recycling Software Market Trends and Innovations
Artificial intelligence is rewiring how scrap metal is valued and routed, compressing the gap between physical inspection and automated classification. Vendors are racing to embed machine learning at the point of material intake.
Computer vision systems paired with deep learning models are electrifying inbound scrap assessment at European steel mills and North American shredder operations. AMCS and GreenSpark have deployed camera arrays that classify material grades from surface texture and oxidation patterns, cutting manual sampling by sixty percent at high-volume facilities. The technology is compressing labor costs while accelerating throughput at scales where assay bottlenecks previously throttled yard capacity.
REACH and the EU Green Deal are tightening documentary requirements for recycled content claims across the European steel and aluminum sectors. Mass-balance accounting now requires software to generate immutable audit trails linking specific scrap batches to finished metal products. German steel recyclers are responding by demanding ERP modules that integrate yard management with mill scheduling systems, creating compliance-ready data pipelines.
Subscription pricing for cloud-based inventory modules is displacing perpetual license models among mid-tier scrap dealers in the US Midwest and Canadian Prairie provinces. Monthly fees aligned with tonnage processed reduce upfront capital requirements and align vendor incentives with customer volume growth. This shift is most visible among dealers serving automotive shredder feedstock markets where seasonal volume swings make fixed-cost software ownership economically inefficient.
Metal Recycling Software Market Segmentation
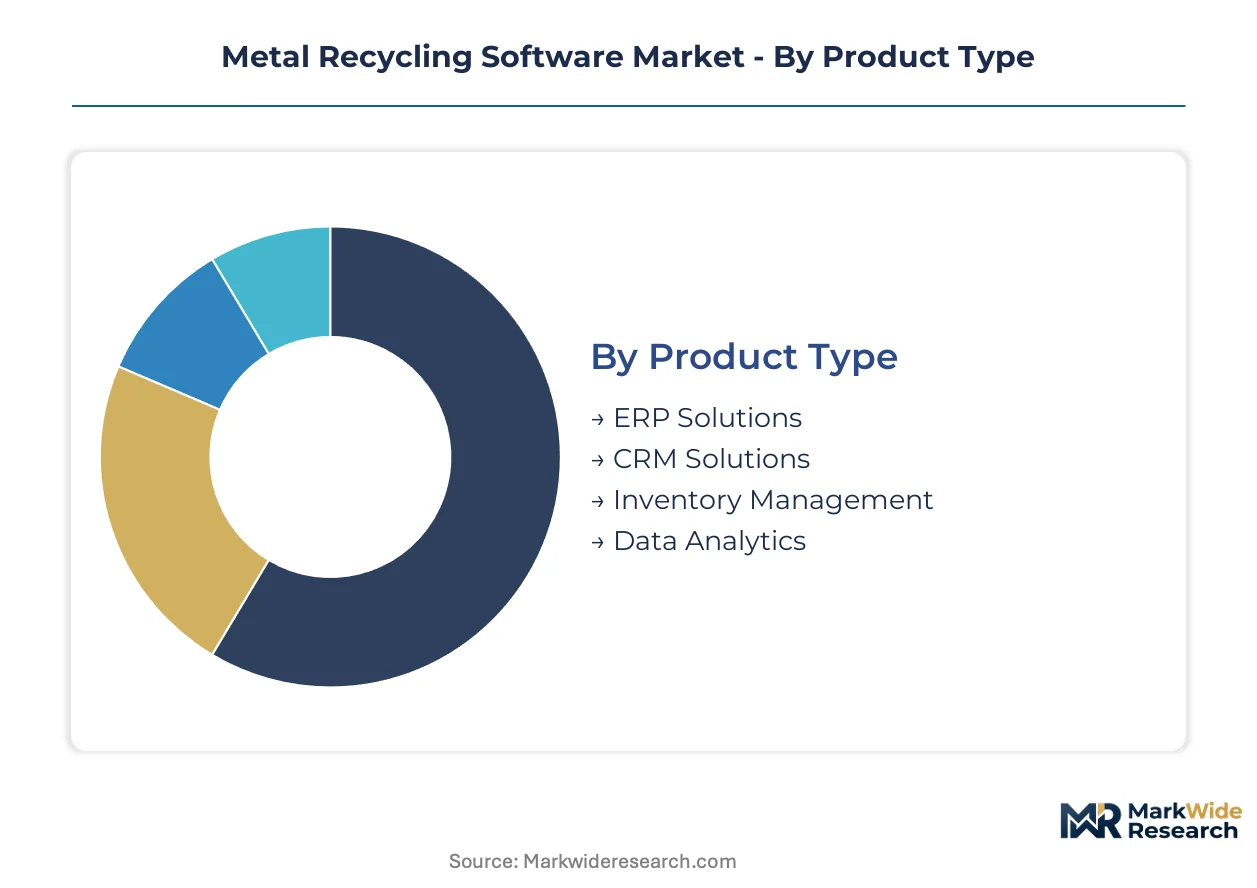
Metal recycling software vendors structure their offerings around four intersecting axes: product functionality, infrastructure deployment, customer operational model, and systems architecture. These dimensions determine pricing architecture, implementation complexity, and competitive differentiation in a market where scrap dealers and steel mills face divergent digital maturity.
Product Type:
Software functionality clusters around operational control, customer relationship orchestration, material tracking, and predictive intelligence.
- ERP Solutions:Comprehensive enterprise resource planning modules consolidate financial reporting, procurement, and multi-site inventory across integrated steel producers and large scrap conglomerates. German steel recyclers in the Rhine-Ruhr corridor anchor procurement decisions on ERP systems that synchronize yard operations with blast furnace scheduling through real-time data pipelines.
- Inventory Management:Specialized modules deliver weighbridge integration, spectroscopy data ingestion, and lot-level traceability for high-volume scrap yards processing just-in-time mill feedstock contracts. Demand concentrates among North American scrap dealers seeking mobile yard access without server maintenance overhead, driven by seasonal volume swings that make fixed-cost ownership inefficient.
- CRM Solutions:Customer relationship platforms manage supplier contracts, pricing negotiations, and outbound shipment documentation for scrap dealers with dispersed feedstock sources.
- Data Analytics:Predictive tools forecast scrap price movements, optimize logistics routing, and grade material quality through machine learning models trained on historical assay data.
ERP Solutions lead on scale; Inventory Management leads on momentum.
Deployment:
Infrastructure choices reflect capital constraints, connectivity reliability, and workforce mobility requirements across scrap yard environments.
- Cloud-Based:Browser-accessible platforms eliminate server maintenance and enable mobile yard management through tablet and smartphone interfaces. North American scrap dealers accelerate adoption here, abandoning on-premise servers for subscription models aligned with tonnage processed.
- On-Premise:Locally hosted systems retain favor among integrated steel producers with stringent data sovereignty requirements and legacy accounting system dependencies.
- Hybrid:Mixed architectures keep sensitive financial data on local servers while pushing operational data to cloud analytics engines.
- Mobile:Native applications for weighbridge operators and yard supervisors prioritize offline functionality and ruggedized hardware compatibility.
Cloud-Based deployment is climbing the fastest; On-Premise retains entrenched positions in heavy industry.
End User:
Customer segments span the scrap value chain from collection through processing to manufacturing integration.
- Scrap Dealers:Independent and mid-tier operators purchase modular, price-transparent systems for inventory tracking, supplier management, and outbound logistics. The US Midwest shows concentrated demand where dealers serve automotive shredder feedstock markets.
- Recycling Facilities:Large-scale yards with spectroscopy-equipped scales and high-throughput shredding operations require platforms integrating computer vision, assay data, and railcar tracking.
- Manufacturers:Steel mills and aluminum smelters demand ERP-integrated solutions with mass-balance accounting for EU Green Deal compliance and recycled content certification.
- Waste Management Companies:Diversified environmental services firms adopt metal-specific modules as extensions of existing municipal and industrial waste platforms.
Scrap Dealers represent the broadest addressable base; Manufacturers command the steepest expansion trajectory.
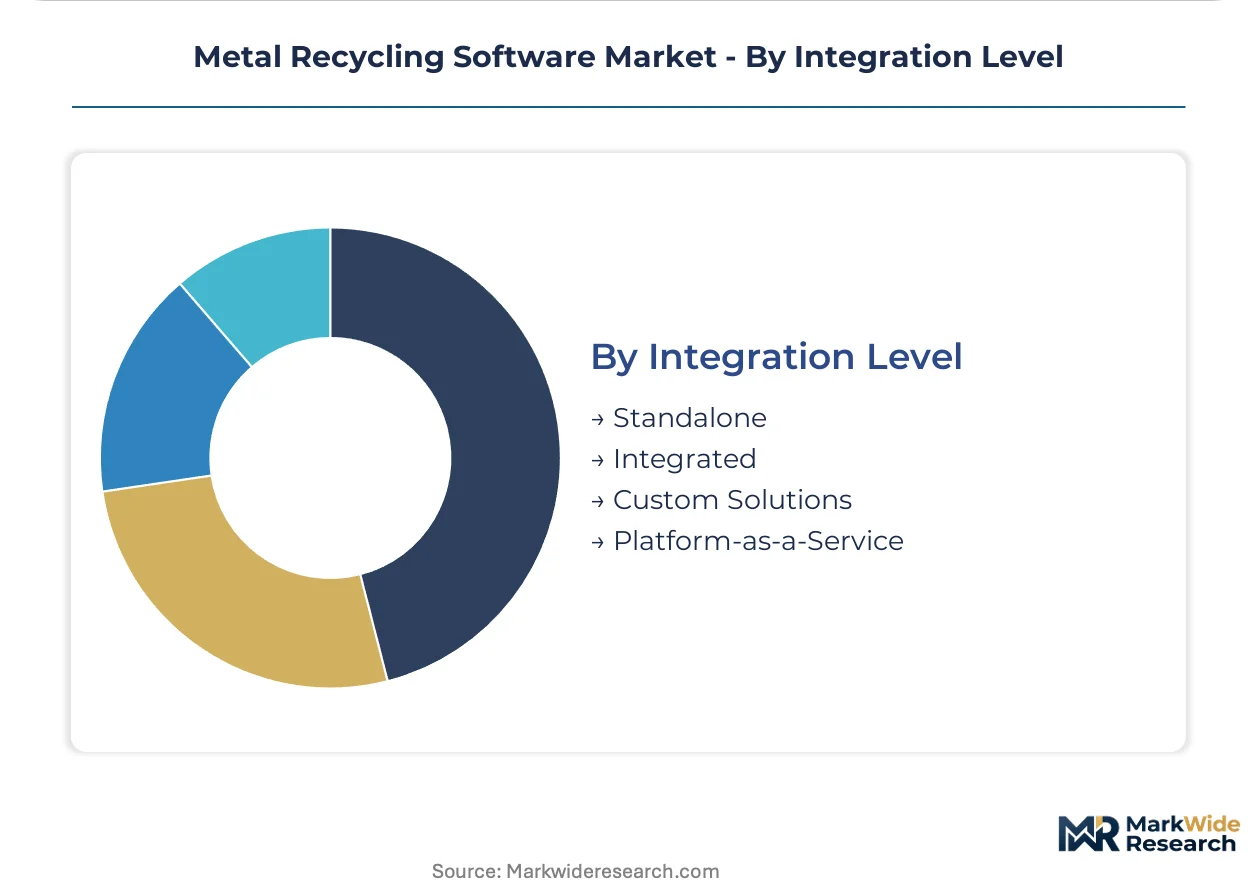
Integration Level:
Systems architecture choices determine implementation scope, professional services intensity, and long-term vendor lock-in.
- Integrated:Pre-built connectors to weighbridge hardware, spectroscopy devices, and mill scheduling systems reduce deployment timelines for complex multi-site operations. European port-based recycling chains favor these configurations.
- Standalone:Self-contained modules address single-function needs without external system dependencies, appealing to smaller yards with limited IT resources.
- Custom Solutions:Bespoke development accommodates unique material streams, proprietary grading protocols, or specialized compliance documentation requirements.
- Platform-as-a-Service:API-first architectures enable scrap dealers to compose workflows from modular microservices, embedding recycling-specific capabilities within broader enterprise software ecosystems.
Integrated systems dominate revenue concentration; Platform-as-a-Service shows the sharpest adoption curve among digitally native operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where metal recycling software vendors prioritize deployment, as compliance-cost differentials between jurisdictions accelerate cross-border platform migration. The EU Green Deal's mass-balance mandates and the US EPA's hazardous waste manifest rules create divergent cost structures that influence vendor resource allocation.
Germany
Rhine-Ruhr corridor steel mills drive demand for ERP-integrated systems synchronizing yard operations with blast furnace scheduling. REACH compliance documentation requirements from ECHA tighten software specifications for recycled content certification. Duisburg and Dortmund industrial clusters anchor procurement decisions on platforms embedding audit-trail functionality.
United States
Midwestern automotive shredder feedstock markets concentrate cloud-based inventory adoption among dealers facing seasonal volume swings. EPA hazardous waste manifest rules govern emissions-linked scrap processing standards across Illinois and Ohio operations. Chicago and Detroit metropolitan yards prioritize mobile-first platforms eliminating server maintenance overhead.
China
Dual carbon goals enforced by MEE tighten traceability requirements for steel and aluminum recyclers in coastal manufacturing zones. GB standards alignment pressures software vendors to embed emissions-intensity tracking for mill procurement contracts. Yangtze River Delta smelters in Shanghai and Jiangsu province integrate platforms with production workflow systems.
United Kingdom
Post-Brexit regulatory divergence from EU REACH creates compliance complexity for scrap exporters serving continental steel mills. Environment Agency permitting rules extend software implementation timelines for hazardous substance tracking. Midlands recycling clusters around Birmingham and Sheffield demand multilingual platforms bridging UK and EU documentation requirements.
India
BIS quality certification mandates for secondary steel producers accelerate software adoption among organized scrap aggregators. PLI scheme incentives for domestic manufacturing tighten feedstock traceability requirements for mill procurement. Gujarat and Maharashtra industrial corridors concentrate demand for cloud modules serving just-in-time aluminum smelter contracts.
Metal Recycling Software Market Competitive Landscape
European vendors anchor one tier through ERP heritage and compliance-integrated platforms; North American specialists hold another through cloud-native yard management systems. The vendor base stratifies across three tiers: enterprise conglomerates serving integrated steel producers, mid-market modular providers for independent scrap dealers, and emerging AI-native entrants targeting automated material grading. Consolidation pressure intensifies as spectroscopy hardware vendors seek software capabilities and cloud platforms pursue vertical functionality expansion.
Within the ERP-heritage tier, AMCS represents the archetype of multi-site recycling chain orchestration across European port operations. Among North American cloud-native specialists, ScrapRight and GreenSpark exemplify divergent positioning—one toward price-transparent modular systems for mid-tier dealers, the other toward AI-powered material grading reducing manual assay dependency. ReMatter occupies a position within the emerging predictive logistics segment converging machine learning with weighbridge and railcar tracking capabilities.
| Leading Market Players |
|---|
| AMCS |
| Yard Wizard |
| Scrap Dragon |
| cieTrade |
| GreenSpark |
| ReMatter |
| MorTrack |
| MetalCalc |
| ScrapRight |
| Others |
Pricing and Supply Chain Analysis
Integrated steel producers in the Rhine-Ruhr corridor anchor procurement decisions on subscription-based SaaS tiers that align software fees with tonnage processed, compressing upfront licensing models among smaller operators.
Pricing Analysis
Distributor margins for cloud-native deployment modules range between fifteen and twenty-five percent, with direct-to-mill contracts commanding steeper discounts for multi-site ERP implementations. Three-tier pricing structure across premium, standard, and economy levels separates compliance-integrated suites from basic inventory trackers. Cost compression in mid-tier scrap dealer segments is intensifying because seasonal volume swings make fixed-cost ownership economically inefficient. Independent yards in the US Midwest show highest price sensitivity, while German steel recyclers prioritize audit-trail functionality over license cost.
Supply Chain Analysis
Freight costs for spectroscopy hardware and ruggedized mobile devices concentrate supply dependencies on Germany, the United States, and China, where component manufacturers cluster near industrial automation hubs. Software vendors draw from Taiwanese semiconductor foundries for weighbridge integration chipsets, German sensor producers for XRF device calibration, and Chinese cloud infrastructure providers for data hosting. Single-source vulnerability in spectroscopy library updates creates procurement risk when alloy identification databases require manual override. Distribution runs through direct sales teams for enterprise ERP contracts and value-added resellers for mid-market cloud modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal recycling software market functions as a stable compounder where regulatory compliance mandates—particularly EU Green Deal mass-balance documentation—generate recurring upgrade cycles that outpace discretionary IT spending volatility.
For Market Incumbents: Hedge against cloud-native disruption by embedding AI-powered material grading into existing ERP suites before specialized entrants capture high-volume yard segments. Acquire spectroscopy hardware calibration capabilities to reduce customer dependency on scarce technician labor. Prioritize REACH compliance documentation modules as the defensive moat against modular competitors. For New Entrants and Emerging Players: Spectroscopy hardware vendors represent the most accessible channel partnership for vertical software integration into established yard operations. Target Spain and Poland's secondary aluminum smelters, where software penetration lags Northern European peers and multilingual support creates differentiation. Lead with predictive logistics modules that pre-position inventory before mill procurement calls. For Investors and Strategic Acquirers: Private equity firms with industrial software portfolios are the most active acquirer in this space, consolidating mid-market vendors into platform plays. Five-to-ten year viability hinges on carbon-border adjustment mechanism compliance features becoming standard rather than premium. Watch for EU CBAM enforcement tightening as the inflection signal for origin-certification software demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | AMCS anchors multi-site recycling chains across European ports through ERP-heritage connectivity. |
| AI-Powered Material Grading | Computer vision deployment at inbound scales cuts manual sampling by sixty percent at high-volume facilities. |
| Geographic Expansion | Cloud-native vendors penetrate Spain and Poland's underpenetrated secondary aluminum sector with multilingual modules. |
| Strategic Partnership | Spectroscopy hardware vendors seek software capabilities to bundle assay automation with device sales. |
| Acquisition of Specialist Firm | Consolidation pressure intensifies as predictive logistics entrants like ReMatter attract platform buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with scrap yard operations managers, steel mill procurement directors, software vendor product leads, and spectroscopy equipment distributors alongside secondary validation. Trade data from Eurofer and Bureau of International Recycling, EPA hazardous waste manifest filings, ECHA REACH registration databases, and vendor SEC disclosures anchored market sizing. Bottom-up yard-level software spend estimates triangulated against top-down segment revenue aggregation.
Historical reference periods spanning the decade preceding the analysis window established baseline adoption curves for cloud deployment versus on-premise systems. The forecast framework modeled deployment model, end-user operational scale, integration complexity, and regional regulatory enforcement patterns across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic scrap metal volume forecasts and compliance deadline schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism implementation timelines and spectroscopy hardware cost curves. Model outputs reflect assumptions about EU Green Deal enforcement consistency and MEE dual carbon goal adherence in China. A model refresh is warranted upon material change in REACH documentation complexity or scrap metal price volatility thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Coaching Management Software Market
Software & Services
Global ERP Software Market
Software & Services
File Sharing Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Europe Printing Software Market
Software & Services
Global Data Recovery Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Visitor Identification Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Codeless Testing Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Email Marketing Software Market
Software & Services
Global Dance Studio Software Market