
 Humanoid Robot Market | 2026-2036
Humanoid Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Humanoid Robot Market Analysis
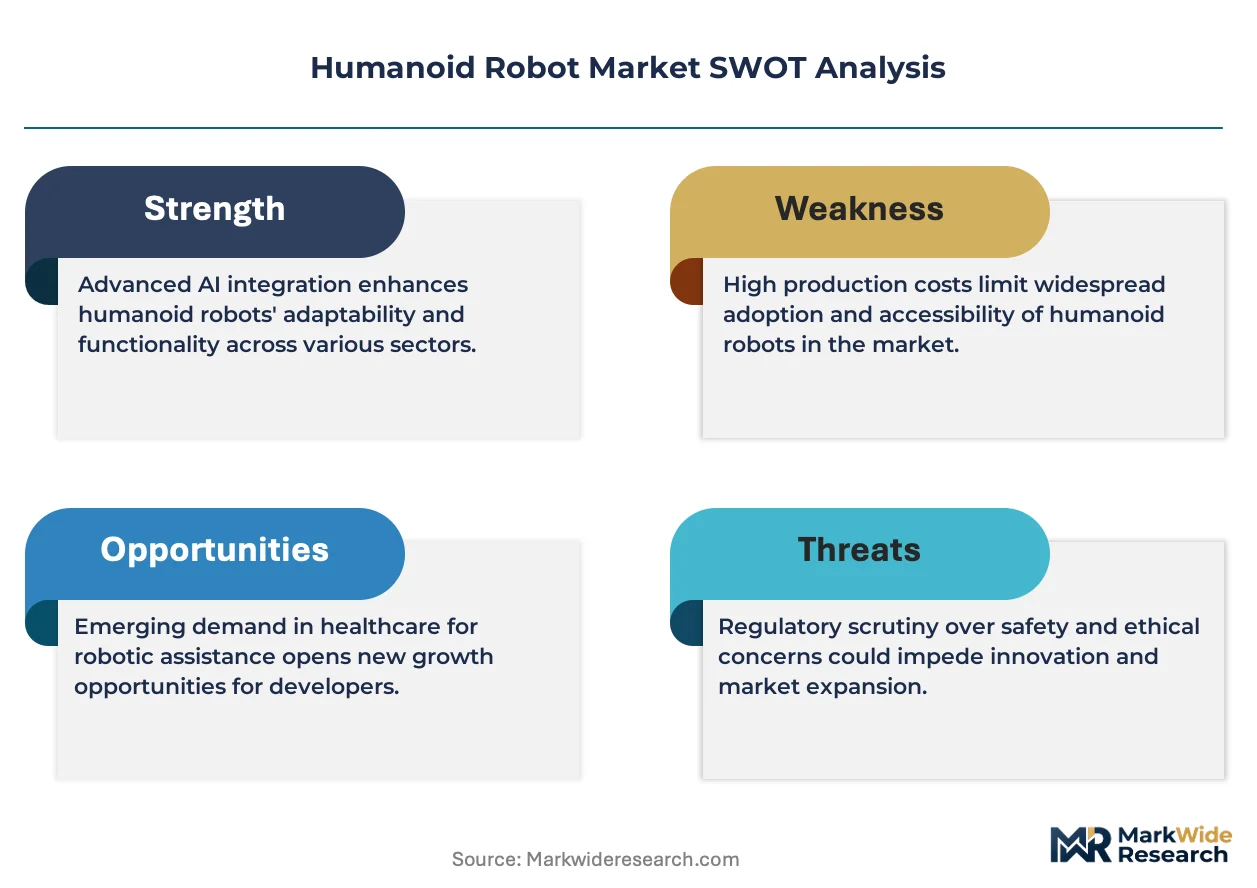
Skilled robotics engineering talent is bifurcating between mechatronics hardware specialists and AI software architects, constraining OEMs that cannot recruit across both domains. Tesla leverages its in-house battery and actuator production to control unit economics at scale. Boston Dynamics anchors its position through decades of locomotion R&D and rigorous field testing protocols. Agility Robotics specializes in warehouse-centric designs with purpose-built grippers for logistics workflows.
Humanoid robots are electromechanical systems with bipedal locomotion, multi-degree-of-freedom limbs, and sensor-integrated control architectures typically exceeding 40 actuators, designed to operate in environments engineered for human workers. The primary commercial purpose centers on task substitution in labor-constrained settings where retrofitting infrastructure for wheeled automation proves uneconomical. Service robots occupy the dominant revenue position as hospitality and retail operators pilot reception and concierge deployments. Healthcare applications are expanding fastest as hospitals evaluate patient mobility assistance and sterile environment tasks, though regulatory clearance timelines compress near-term margin pools. Educational robots sustain steady institutional demand from technical universities establishing dedicated humanoid research laboratories.
OSHA workplace safety standards in the United States and the EU AI Act's risk classification framework for autonomous systems are shaping product certification requirements and deployment liability structures. China's MIIT guidelines on intelligent robotics and Japan's METI safety standards for collaborative robots further fragment compliance obligations for multinational vendors. Stakeholders must monitor how divergent liability regimes for human-robot workplace interaction reshape geographic rollout sequencing and partnership strategies.
Market Dynamics
Reinforcement learning pipelines trained on human motion capture datasets are compressing locomotion development cycles from years to months, forcing OEMs to restructure R&D staffing models or surrender competitive position.
Growth Catalysts
- EU AI Act risk classification:Clear liability frameworks for autonomous systems reduce deployment uncertainty for European logistics operators evaluating bipedal material handling.
- Warehouse labor constraints:E-commerce fulfillment centers in Germany and the Netherlands are accelerating bipedal procurement where retrofitting for wheeled automation proves uneconomical.
- Actuator torque density advances:High-torque electric motors with integrated harmonic drives enable human-scale payloads without hydraulic systems.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility and concentrated Chinese processing capacity expose motor cost structures to input shocks.
- OSHA workplace safety certification:Absence of established incident liability protocols delays commercial deployment in US manufacturing facilities.
- Wheeled AMR substitution:Autonomous mobile robots with manipulator arms satisfy 70% of material handling tasks at 40% lower unit cost.
Strategic Opportunities
- Japan METI collaborative robot standards:Regulatory clarity creates first-mover advantage for vendors certifying human-robot workplace coexistence protocols.
- Healthcare patient mobility assistance:Hospitals in France and Switzerland pilot sterile-environment deployment for fall prevention and rehabilitation support.
- Edge AI inference convergence:Onboard neural processing units paired with tactile sensor arrays enable real-time grasp adaptation without cloud dependency.
Industry Challenges
- Mechatronics-AI talent bifurcation:Hardware specialists and software architects occupy disconnected labor pools, forcing OEMs to maintain duplicate R&D tracks.
- Multi-joint calibration complexity:Forty-plus actuator systems require precision alignment protocols that extend factory acceptance testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humanoid Robot Market |
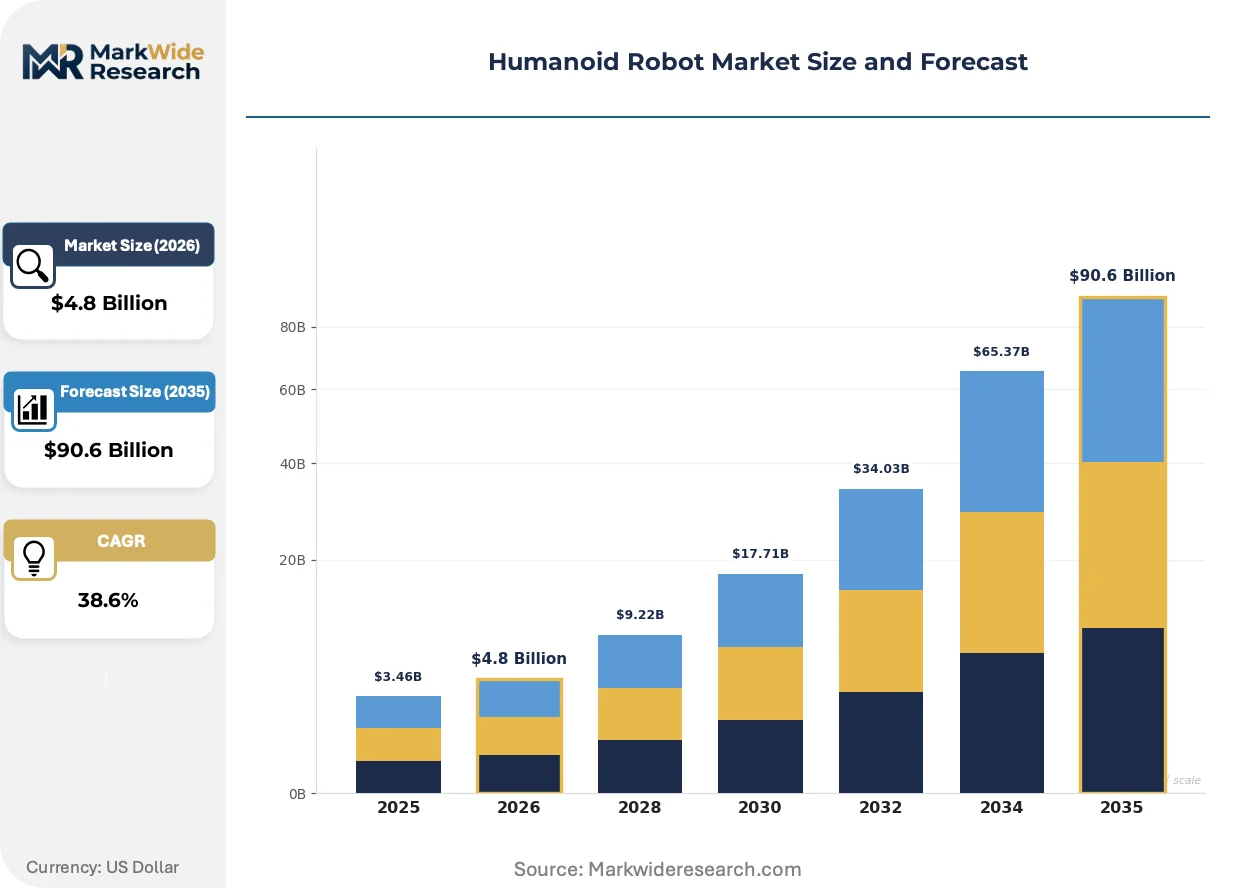
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $90.6 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assistive Robots, Entertainment Robots, Service Robots, Educational Robots Technology: AI, Machine Learning, Computer Vision, Natural Language Processing Application: Healthcare, Hospitality, Retail, Research End User: Home Use, Educational Institutions, Hospitals, Corporate |
| Companies Covered | Agility Robotics, UBTECH Robotics, Tesla, Neura Robotics, Apptronik, Figure AI, Unitree Robotics, AgiBot, Boston Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humanoid Robot Market Emerging Trajectories
Locomotion control architectures are migrating from centralized model-based systems to distributed learning-based approaches, reshaping how vendors structure firmware teams and validation protocols.
Compact force-torque sensors with fiber-optic strain measurement cores are miniaturizing wrist and ankle load feedback systems. Automotive assembly plants in South Korea are integrating these units for precision insertion tasks. The technology is miniaturizing previously hydraulic-heavy end-effector designs into all-electric configurations with comparable payload capacity.
China MIIT intelligent robotics guidelines establish safety performance levels for human-robot collaborative workspaces. Domestic manufacturers must certify against these metrics for government procurement eligibility. Export-focused OEMs are dual-tracking certification against MIIT and EU AI Act requirements to preserve market access flexibility.
Hospital capital equipment committees now require humanoid platforms to demonstrate interoperability with existing nurse call systems and electronic health record infrastructure. Device vendors are embedding HL7 FHIR connectivity modules to satisfy this procurement gate. Germany's university hospital network exhibits the most stringent integration requirements, compressing vendor qualification cycles to under six months.
Humanoid Robot Market Segmentation
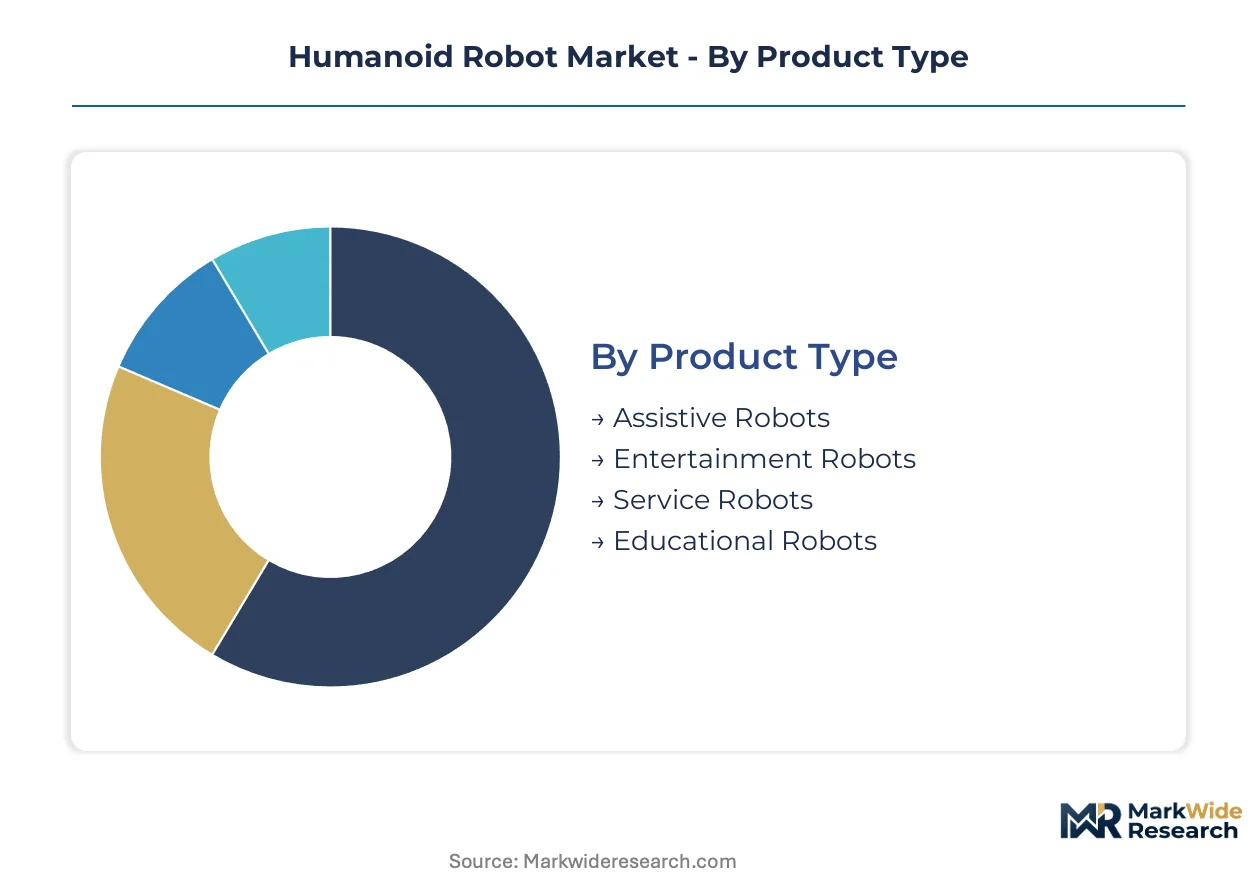
Segmentation in the humanoid robot market reveals how regulatory frameworks and end-use requirements fragment product specifications across jurisdictions. Vendors must engineer modular architectures that satisfy divergent certification standards while preserving manufacturing economies of scale.
Product Type:
EU AI Act risk classifications and Japan METI collaborative robot standards differentiate compliance burdens across product categories, with higher-risk tiers demanding extensive third-party validation.
- Service Robots:Bipedal platforms with 40-plus actuator architectures designed for reception, concierge, and facility guidance tasks. Hospitality operators in France and Switzerland pilot these units for guest interaction workflows where wheeled alternatives fail on aesthetic and mobility requirements. EU AI Act autonomous system classifications impose incident liability protocols that extend procurement cycles.
- Educational Robots:Research-grade platforms with open control architectures and programmable kinematic chains. Technical universities in Germany and South Korea establish dedicated humanoid laboratories, driving institutional procurement with requirements for ROS-compatible middleware and documented inverse kinematics APIs.
- Assistive Robots:Patient mobility support systems with force-limited actuators and fall-detection sensor arrays.
- Entertainment Robots:Choreography-capable units with expressive gesture libraries for theme park and exhibition deployments.
Service robots handle the majority of throughput; educational robots are expanding most quickly on share.
Technology:
Cost tier differentiation separates premium sensor-fusion stacks from economy configurations that sacrifice real-time performance for unit economics.
- AI:Onboard neural processing units enable edge inference without cloud dependency. Automotive assembly plants in South Korea integrate these architectures for precision insertion tasks requiring sub-100-millisecond response latencies.
- Computer Vision:Depth-sensing camera arrays with simultaneous localization and mapping capabilities. Warehouse operators in the Netherlands deploy these systems for bin-picking operations where lighting variability defeats conventional 2D approaches.
- Machine Learning:Reinforcement learning pipelines trained on human motion capture datasets.
- Natural Language Processing:Multimodal interaction systems with accent-robust speech recognition.
AI commands the dominant R&D allocation; computer vision is climbing the fastest on deployment share.
Application:
Customer type concentration shapes feature prioritization, with institutional buyers demanding interoperability certifications that consumer segments ignore.
- Healthcare:Sterile-environment platforms with HL7 FHIR connectivity modules for nurse call system integration. Germany's university hospital network imposes six-month vendor qualification cycles, compressing margin pools for non-compliant entrants.
- Hospitality:Reception and concierge deployments with multilingual interaction capabilities. Hotels in Switzerland evaluate these units for front-desk automation where labor shortages constrain service levels.
- Retail:Customer guidance and inventory assistance configurations.
- Research:Laboratory automation with precision manipulation specifications.
Healthcare absorbs the steepest investment trajectory; hospitality delivers the broadest installed base.
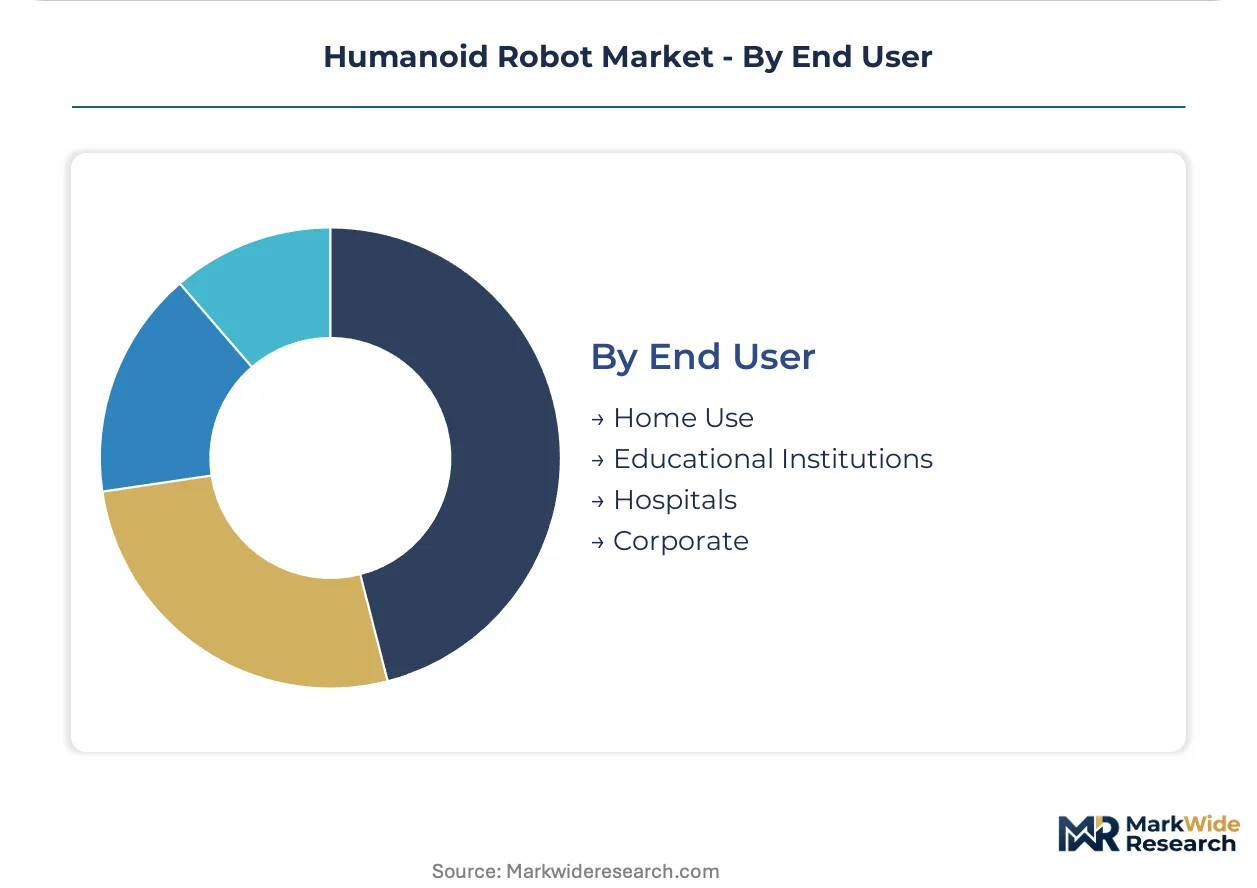
End User:
Supply concentration in actuator manufacturing creates tiered pricing structures that stratify procurement across volume scales.
- Hospitals:Capital equipment committees require electronic health record interoperability and documented safety performance levels. China's MIIT guidelines on intelligent robotics establish additional certification requirements for government procurement eligibility.
- Corporate:Logistics and facility management operators with standardized fleet deployment models. E-commerce fulfillment centers in Germany accelerate bipedal procurement where retrofitting for wheeled automation proves uneconomical.
- Educational Institutions:Technical universities with dedicated research laboratory budgets.
- Home Use:Consumer segments with price sensitivity and limited technical integration requirements.
Corporate end users drive the dominant procurement volume; hospitals exhibit the fastest contract velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in China exceeds that in Germany by a substantial margin, reflecting divergent procurement scales and captive manufacturing ecosystems. Domestic Chinese OEMs command unit economics that European competitors cannot replicate without tariff exposure or joint venture structures.
China
Warehouse operators in Guangdong and Jiangsu provinces accelerate bipedal deployments for e-commerce fulfillment tasks. MIIT guidelines on intelligent robotics establish safety performance levels that domestic manufacturers must certify against for government procurement eligibility. Shenzhen-based production clusters scale actuator output for both export markets and captive deployment across manufacturing and service sectors.
United States
Automotive assembly plants in Michigan and South Carolina pilot humanoid systems for precision insertion tasks requiring sub-100-millisecond response latencies. OSHA workplace safety standards lack established incident liability protocols, delaying commercial deployment in manufacturing facilities. Boston maintains concentrated R&D operations anchored by decades of locomotion research and rigorous field testing protocols.
Germany
Logistics operators in Bavaria and North Rhine-Westphalia evaluate bipedal procurement where retrofitting for wheeled automation proves uneconomical. EU AI Act risk classifications impose incident liability protocols that extend procurement cycles for autonomous systems. Stuttgart's automotive engineering corridor drives demand for force-torque sensor integration in precision manipulation workflows.
Japan
Healthcare facilities in Tokyo and Osaka pilot sterile-environment deployments for patient mobility assistance and fall prevention. METI safety standards for collaborative robots create regulatory clarity for vendors certifying human-robot workplace coexistence protocols. Nagoya's industrial automation cluster concentrates precision actuator manufacturing for domestic and export supply.
South Korea
Electronics manufacturers in Gyeonggi Province integrate humanoid platforms for component handling in cleanroom environments. National standards for intelligent robotics align with international frameworks to preserve export market access. Seoul's robotics research institutes compress locomotion development cycles through reinforcement learning pipelines trained on domestic motion capture datasets.
Humanoid Robot Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. Automotive-originated entrants leverage captive battery and actuator supply chains to control unit economics at scale. Pure-play robotics specialists anchor positions through decades of locomotion R&D and purpose-built hardware architectures. Strategic moves concentrate on vertical integration into core electromechanical components and geographic certification dual-tracking to preserve market access flexibility.
Within the automotive-leveraged tier, Tesla exemplifies scale-driven manufacturing integration, while Boston Dynamics occupies a position defined by extended field validation protocols. Among pure-play specialists, Agility Robotics represents warehouse-centric design specialization with logistics workflow optimization. These three anchors illustrate how competitive positioning diverges between cost-engineered scale and validated performance premiums.
| Leading Market Players |
|---|
| Agility Robotics |
| UBTECH Robotics |
| Tesla |
| Neura Robotics |
| Apptronik |
| Figure AI |
| Unitree Robotics |
| AgiBot |
| Boston Dynamics |
| Others |
Supply Flow & Price Mechanics
Actuator manufacturing scale in Shenzhen and Guangdong provinces compresses unit economics for domestic Chinese OEMs, creating price floors that European and North American competitors cannot match without tariff exposure or joint venture structures. This concentration simultaneously elevates pricing power for integrated manufacturers while squeezing margin pools for vendors dependent on third-party motor and harmonic drive sourcing.
Pricing Analysis
Configured-to-order pricing for healthcare and automotive precision-insertion deployments commands substantial premiums over standard warehouse-logistics configurations. Three-tier pricing structure across premium, standard, and economy levels separates certified sterile-environment platforms from uncertified logistics units from research-grade educational kits. Price differentiation rests on MIIT certification status and EU AI Act risk-classification tier. Pricing pressure stems from wheeled AMR substitution in material-handling applications. E-commerce fulfillment centers exhibit highest price sensitivity; hospital capital equipment committees demonstrate lowest.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam and Shenzhen-Long Beach trade lanes elevate inbound logistics costs for European and North American integrators sourcing complete actuator assemblies. Geographic supply concentrates in China for rare-earth magnet processing and motor winding, Japan for precision harmonic drives, and South Korea for compact force-torque sensors. Raw material dependencies include neodymium-iron-boron magnets, high-grade electrical steel, and fiber-optic strain measurement cores. Single-source vulnerability in Chinese rare-earth processing exposes cost structures to input shocks. Distribution runs through direct OEM sales for large fleet deployments and specialized robotics distributors for research and pilot installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Humanoid robot vendors face substitution defense against wheeled AMR systems that satisfy equivalent material-handling functions at substantially lower unit economics, forcing positioning clarity on bipedal mobility premiums.
For Market Incumbents: Compound locomotion R&D advantages through reinforcement learning pipeline investment trained on proprietary motion capture datasets. Anchor market position via backward integration into high-torque electric motor production to escape neodymium price volatility exposure. Defend against automotive-originated entrants by accelerating METI and EU AI Act certification timelines that create switching costs for qualified installations. For New Entrants and Emerging Players: Certification fast-track through Japan METI collaborative robot standards creates first-mover positioning in sterile-environment healthcare deployments where regulatory clarity remains sparse. Target hospital patient mobility assistance in France and Switzerland where six-month qualification cycles compress incumbent response windows. Pursue direct-to-hospital sales models bypassing distributor markups that inflate landed costs for research-stage vendors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors bundling fleet management software with hardware deployments, creating SaaS-like retention profiles in logistics operator accounts. Long-term viability over the projection horizon favors OEMs with captive battery and actuator supply chains that control unit economics at manufacturing scale. Acquisition target archetype: pure-play specialists with validated field testing protocols and warehouse-centric gripper IP. Signal to watch: MIIT certification completion rates as proxy for Chinese government procurement pipeline visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Actuator Manufacturing | Captive motor production insulates Tesla and comparable OEMs from neodymium price shocks concentrated in Chinese processing. |
| Dual-Track Certification Investment | Parallel MIIT and EU AI Act validation preserves market access flexibility across government procurement and European logistics sectors. |
| Edge AI Inference Convergence | Onboard neural processing units paired with tactile sensors enable real-time grasp adaptation without cloud dependency latency. |
| Healthcare System Partnership | HL7 FHIR connectivity modules satisfy Germany's university hospital network procurement gates and compress vendor qualification cycles. |
| Reinforcement Learning Pipeline Development | Human motion capture dataset training compresses locomotion development cycles from years to months for competitive positioning. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and OEM technical documentation. Primary interviews engaged robotics engineering directors, warehouse operations managers at e-commerce fulfillment centers, hospital biomedical engineers, and MIIT certification specialists. Secondary validation drew from EU AI Act implementation guidance, OSHA workplace safety standards, Japan METI collaborative robot directives, and South Korean intelligent robotics national standards. Bottom-up triangulation across component supplier interviews and top-down reconciliation against end-user procurement data ensured cross-verified demand estimates.
Segmentation dimensions modeled span product type, technology stack, application vertical, and end-user category across the analysis window. The analytical framework projects bipedal platform deployment trajectories in logistics, healthcare, hospitality, and research segments. CAGRs were derived from installed base build rates, replacement cycles, and penetration assumptions against addressable labor-constrained task environments. Industry-specific forecast inputs include reinforcement learning algorithm maturity curves and rare-earth magnet price elasticity coefficients for motor cost structures.
Decision-makers should treat outputs as directional under assumptions of sustained warehouse labor constraints and stable rare-earth supply availability; material deviation would warrant model refresh. Specific risk factors that could revise trajectories include OSHA incident liability protocol finalization, wheeled AMR capability advancement, or Chinese export restriction imposition on processed neodymium. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Humanoids Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Underwater Exploration Robots Market