
 Bagging Equipment Market | 2026-2036
Bagging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bagging Equipment Market Analysis
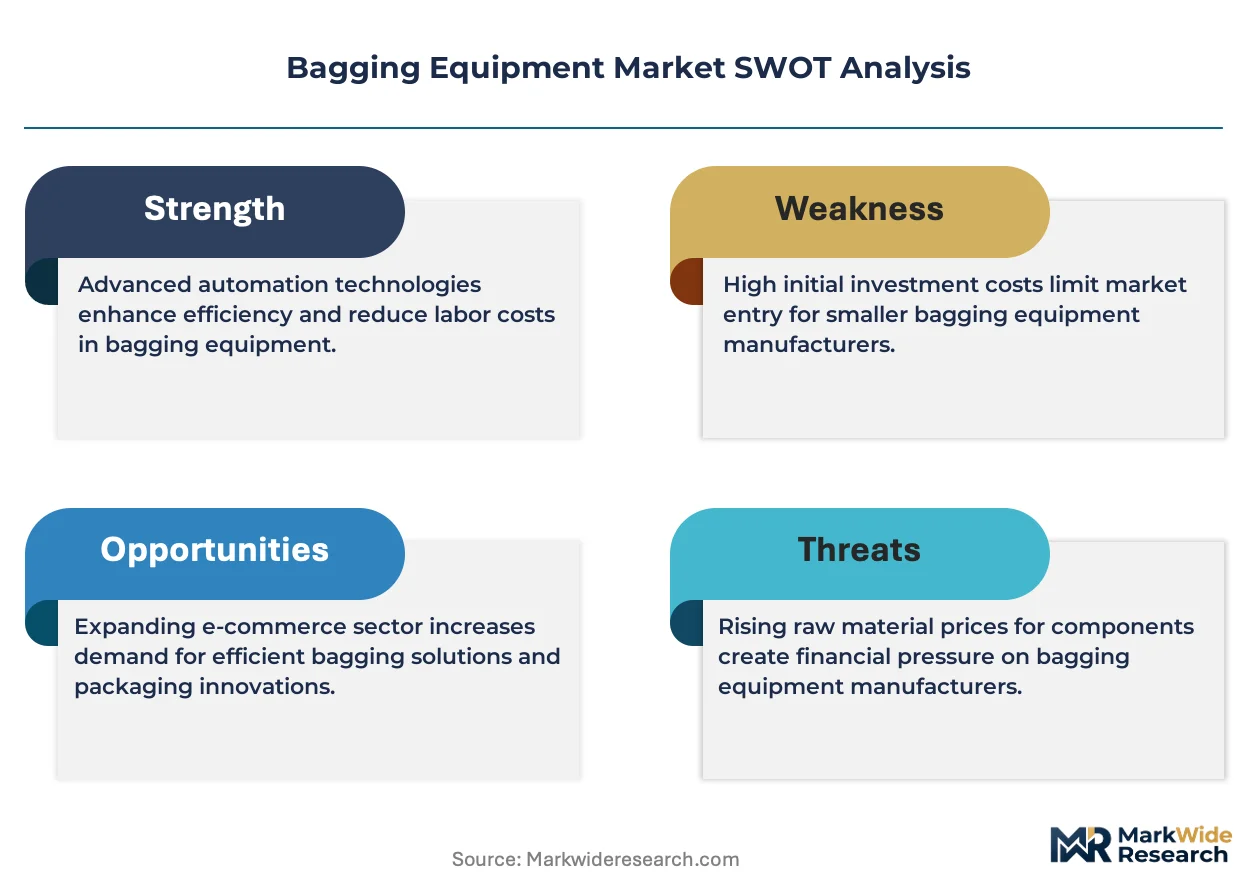
Equipment leasing and project finance is tilting competitive access toward mid-tier processors that previously deferred capital deployment. Haver & Boecker OHG anchors its position through captive engineering of woven bag systems for construction and agricultural inputs. Robert Bosch GmbH leverages modular servo architectures to sustain technology leadership in high-speed pharmaceutical lines. Tokyo Automatic Machinery Works Ltd. dominates precision filling applications across East Asian food exporters.
Bagging equipment comprises machinery designed to form, fill, and seal flexible containers, typically operating at speeds from 10 to 120 bags per minute with fill accuracies of ±0.5% to ±2% depending on product density and flow characteristics. Its primary purpose is to automate the terminal packaging stage across bulk and consumer-goods operations, reducing labor exposure to dust and repetitive motion while ensuring lot traceability. Vertical Form Fill Seal systems occupy the largest installed base owing to their compact footprint and versatility across powders and granules, though Automation Solutions is the fastest-expanding technology segment as processors retrofit legacy lines with vision-guided robotics and IoT-enabled predictive maintenance. Horizontal Form Fill Seal equipment commands premium positioning in pre-made pouch applications where shelf aesthetics and resealability drive purchase decisions.
FDA food-contact material regulations and EU machinery safety directives (CE marking under the Machinery Regulation) compel OEMs to validate stainless steel grades, hygienic welding standards, and emergency-stop redundancies before market entry. OSHA lockout/tagout requirements in United States manufacturing plants further shape equipment guarding designs and service-access protocols. Stakeholders must monitor how evolving extended producer responsibility frameworks for flexible packaging waste alter equipment specifications for recyclable film compatibility and material-thinning capabilities.
Market Dynamics
Automation retrofits on legacy bagging lines are compressing replacement cycles as processors prioritize throughput-per-square-meter over greenfield capacity additions. Servo-driven motion control and vision-guided robotics are displacing mechanical cam systems in mid-tier food and pharmaceutical plants.
Growth Catalysts
- EU Machinery Regulation (CE marking):Mandatory hygienic design standards for food-contact surfaces are accelerating stainless-steel equipment refresh cycles across European dairy and meat processing facilities.
- Pharmaceutical serialization mandates:Track-and-trace requirements for unit-level identification are forcing secondary packaging line upgrades that integrate bagging with aggregation stations.
- German machinery engineering clusters:Concentrated OEM supply chains around Stuttgart and Düsseldorf reduce lead times for EMEA processors seeking turnkey automation solutions.
Market Restraints
- Stainless steel alloy volatility:Grade 316L price swings compress margin predictability for equipment fabricators locked into fixed-price project contracts.
- Precision servo motor supply:Dependence on Japanese and German drive manufacturers creates 16-24 week delivery exposure for high-speed filling lines.
- Film substrate incompatibility:Recyclable mono-material films exhibit seal-strength variability that limits running speeds on legacy vertical form-fill-seal systems.
Strategic Opportunities
- Indian food processing expansion:Cold chain infrastructure buildout under PLI scheme incentives creates demand for moisture-barrier bagging in spice and snack exports.
- Convergence of collaborative robotics with bagging:Force-limited articulated arms enable human-robot mixed-model packing for short-run contract manufacturers.
- Extended producer responsibility frameworks:EU packaging waste directives are mandating design-for-recycling specifications that favor equipment with quick-changeover film handling.
Industry Challenges
- Mechatronics technician scarcity:Integration of servo systems, PLCs, and vision hardware requires cross-trained maintenance staff that regional vocational pipelines fail to produce at scale.
- Legacy control architecture integration:Proprietary fieldbus protocols from 1990s-era installations obstruct seamless IoT retrofit without full line controller replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagging Equipment Market |
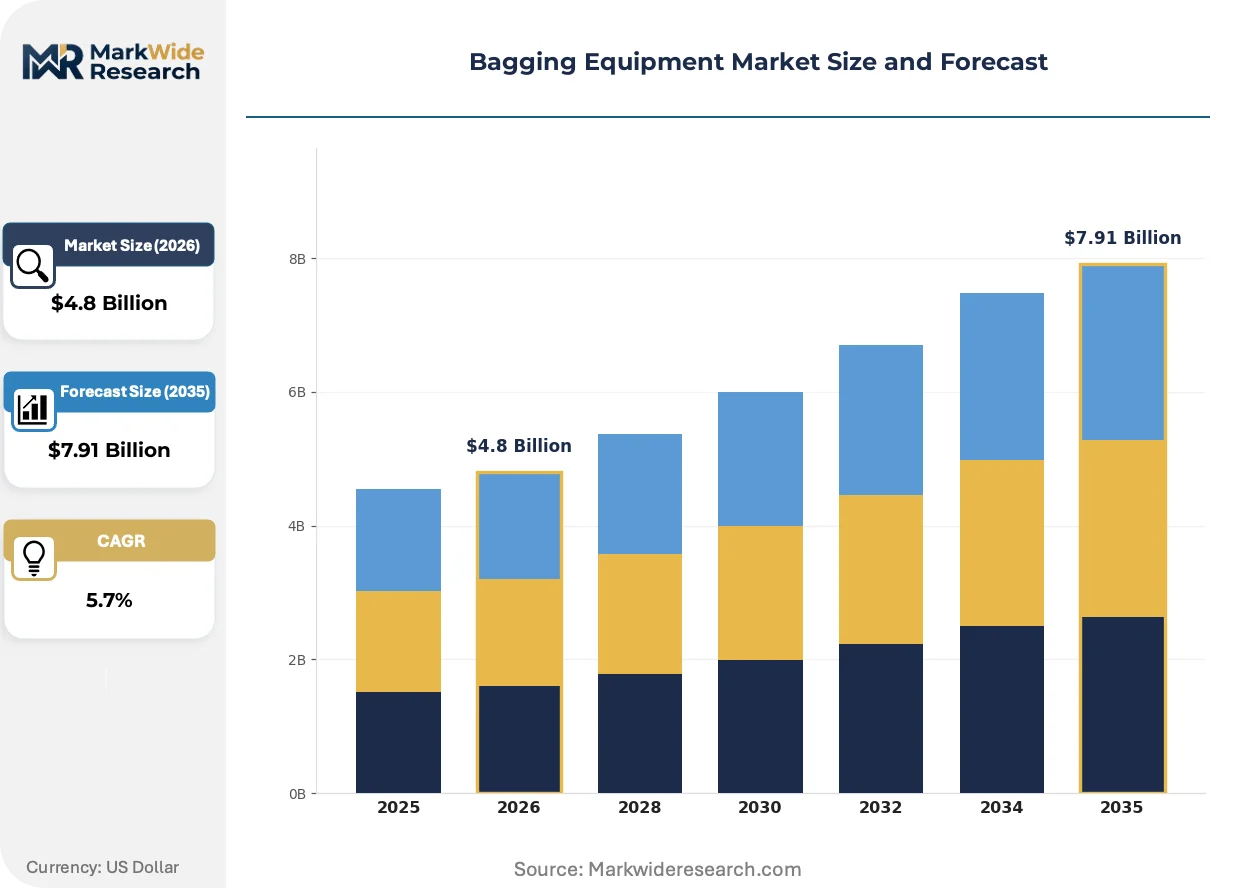
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Form Fill Seal, Horizontal Form Fill Seal, Manual Bagging, Automatic Bagging End User: Agriculture, Food Processing, Chemicals, Pharmaceuticals Technology: Weighing Systems, Filling Systems, Sealing Systems, Automation Solutions Application: Powders, Granules, Liquids, Bulk Packaging |
| Companies Covered | Barry-Wehmiller Companies, Premier Tech Chronos, I.M.A. Industria Macchine Automatiche S.p.A., Automated Packaging Systems, Inc., BEUMER Group GmbH & Co. KG, Haver & Boecker OHG, All-Fill Inc., Robert Bosch GmbH, Tokyo Automatic Machinery Works Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagging Equipment Market Emerging Trajectories
Equipment architecture is pivoting from fixed mechanical designs toward software-configurable platforms that accommodate SKU proliferation without hardware changeover. This reconfiguration prioritizes modularity over throughput maximization.
Servo-driven rotary jaw systems are migrating from intermittent-motion mechanical cam drives to continuous-motion electronic gearing. Pharmaceutical contract packers in Switzerland and New Jersey are adopting these architectures to compress changeover intervals below 15 minutes. The shift is migrating from high-margin therapeutic packaging into generic oral solid dose lines where batch sizes below 5,000 units previously justified manual operations.
REACH compliance documentation under ECHA oversight now requires full material disclosure for food-contact polymers and lubricants. Equipment OEMs must validate substance inventories across their supply chains before CE marking authorization. German and Italian manufacturers are absorbing third-party audit costs into base pricing, while smaller Eastern European fabricators face market exit pressure from compliance overhead.
After-sales service unbundling is separating predictive maintenance software subscriptions from hardware warranty coverage. Food processors in the Netherlands and Denmark are negotiating standalone SaaS contracts for vibration monitoring and spare-part forecasting. This restructuring concentrates bargaining power with buyers who operate multi-vendor installed bases and can demand API-standardized data portability.
Bagging Equipment Market Segmentation
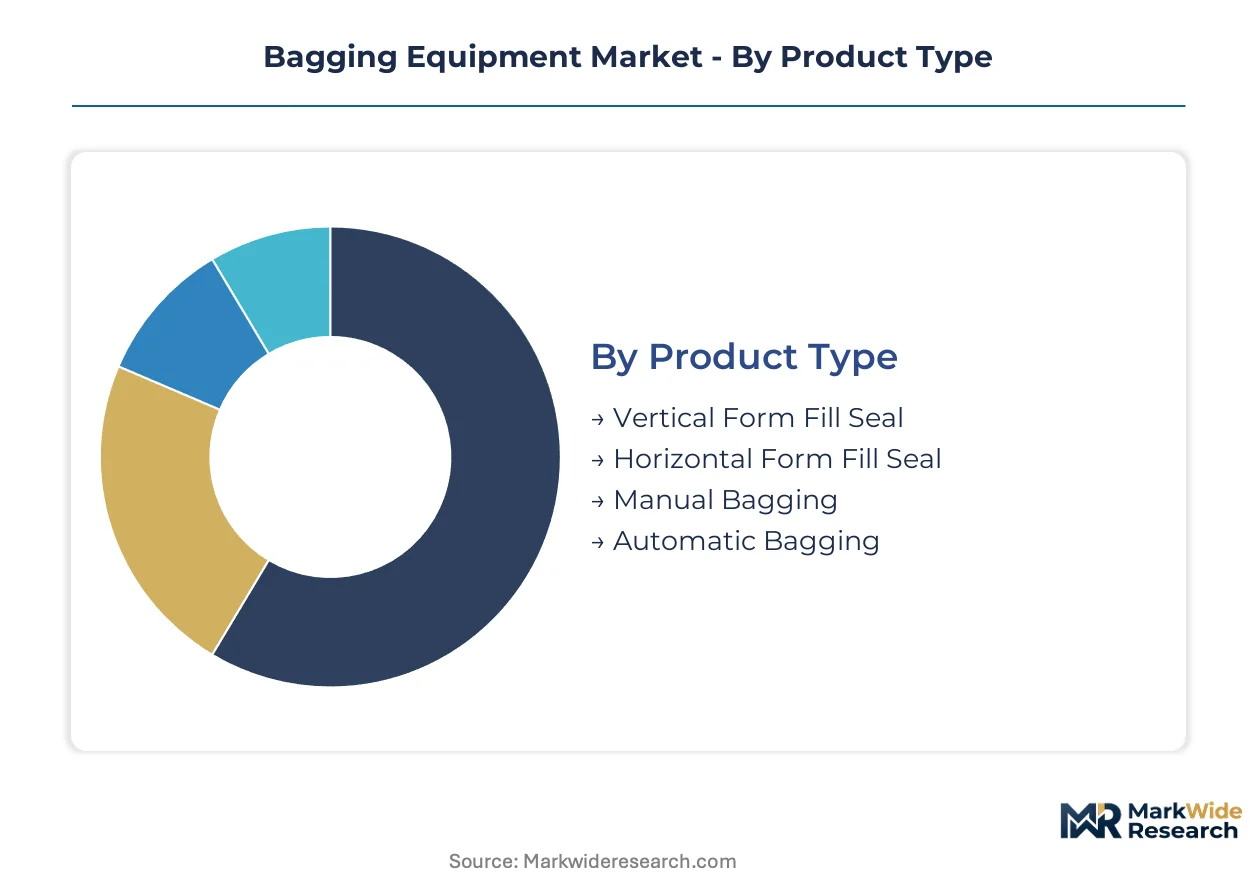
Equipment configuration decisions in bagging machinery hinge on throughput requirements, product flow characteristics, and integration complexity with upstream processing lines. Segmentation reveals where service contract intensity concentrates and which technology investments command premium support pricing.
Product Type:
After-sales service intensity varies sharply across product architectures, with continuous-motion systems demanding predictive maintenance subscriptions and intermittent-motion equipment relying on break-fix arrangements.
- Vertical Form Fill Seal:Compact footprint machines form bags from rollstock film, fill product, and seal in a vertical configuration. Demand clusters in German dairy powder operations and Indian spice exporters seeking stainless-steel sanitary designs. CE marking under EU Machinery Regulation drives refresh cycles for legacy pneumatic systems.
- Horizontal Form Fill Seal:Pre-made pouch handling equipment accommodates resealable closures and shaped bags for shelf differentiation. Swiss pharmaceutical contract packers deploy these for unit-dose serialization compliance. Film registration precision requirements elevate servo motor specification thresholds.
- Manual Bagging:Operator-fed systems with foot-pedal or hand-triggered sealing for batch-scale operations.
- Automatic Bagging:Fully integrated lines with robotic palletizing for high-volume continuous production.
By volume, Vertical Form Fill Seal leads. By growth pace, Automatic Bagging is ahead.
End User:
Margin profiles diverge across end-use sectors, with pharmaceutical lines commanding 40-60% service attach rates versus 15-25% in agricultural applications.
- Food Processing:Hygienic design mandates from FDA food-contact rules and EU Machinery Regulation compel stainless-steel construction and clean-in-place compatibility. German meat processors and Netherlands dairy cooperatives prioritize throughput-per-square-meter in retrofit decisions.
- Pharmaceuticals:Track-and-trace serialization requirements under FDA DSCSA and EU FMD force aggregation-capable secondary packaging integration. New Jersey and Switzerland contract packers adopt continuous-motion rotary jaw architectures for sub-15-minute changeovers.
- Agriculture:Woven polypropylene bag handling for seeds, fertilizers, and animal feed with lower precision tolerance.
- Chemicals:Explosion-proof configurations and corrosion-resistant materials for hazardous powder handling.
By installed base, Food Processing dominates. By expansion trajectory, Pharmaceuticals climbs fastest.
Technology:
Technology stack selection determines spare parts forecasting complexity and field service specialization requirements.
- Automation Solutions:Vision-guided robotics and IoT-enabled predictive maintenance platforms. East Asian food exporters in Japan and South Korea deploy force-limited collaborative arms for mixed-model packing. API-standardized data portability becomes a procurement negotiation lever for multi-vendor operators in Denmark and Netherlands.
- Weighing Systems:Load cell-based gravimetric filling with ±0.5% accuracy for high-value pharmaceutical powders.
- Filling Systems:Auger, cup, or piston mechanisms matched to product flow characteristics.
- Sealing Systems:Heat-seal, ultrasonic, or impulse technologies adapted to film substrate properties.
By adoption breadth, Filling Systems spans widest. By investment momentum, Automation Solutions gains share fastest.
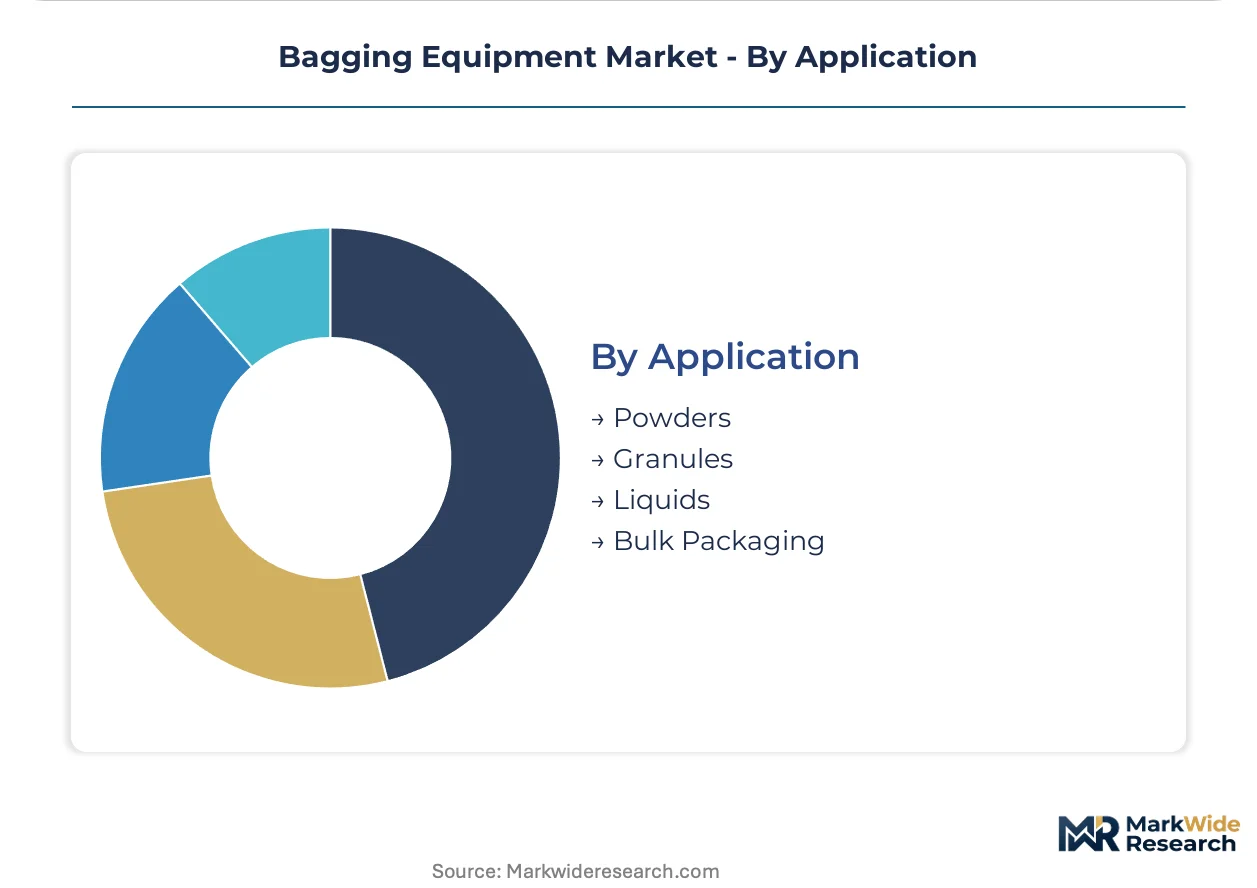
Application:
Product physical state dictates sealing technology selection and line speed optimization parameters.
- Powders:Dust-containment and nitrogen-flush capabilities for oxidation-sensitive materials. Indian spice exporters under PLI scheme incentives demand moisture-barrier specifications for cold chain export integrity.
- Granules:Free-flowing particulate handling with vibratory feeding and checkweighing integration.
- Liquids:Positive-displacement pumping and drip-free nozzle designs for viscous products.
- Bulk Packaging:Heavy-duty woven bag systems for 10-50kg agricultural and construction materials.
By shipment volume, Granules leads. By specification complexity, Powders is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and FDA food-contact enforcement in the United States are redirecting capital toward automated bagging retrofits. Machinery engineering clusters in Germany and precision equipment hubs in Japan supply turnkey solutions across their respective trade zones. Cold chain infrastructure buildouts and pharmaceutical serialization mandates are compressing equipment procurement timelines in multiple jurisdictions.
Germany
Stuttgart and Düsseldorf machinery clusters supply vertical form-fill-seal systems to dairy cooperatives across EMEA. CE marking under the EU Machinery Regulation accelerates refresh cycles for pneumatic legacy lines. Meat processors in Lower Saxony prioritize throughput-per-square-meter in brownfield automation decisions.
United States
Pharmaceutical contract packers in New Jersey adopt continuous-motion rotary jaw architectures for DSCSA track-and-trace compliance. OSHA lockout/tagout requirements shape equipment guarding designs and service-access protocols. Midwest food processors retrofit legacy lines with IoT-enabled predictive maintenance platforms.
India
Cold chain infrastructure expansion under the PLI scheme creates demand for moisture-barrier bagging in spice and snack exports. FSSAI food safety standards elevate stainless-steel sanitary design specifications. Gujarat and Maharashtra processing facilities deploy automated lines to meet export throughput targets.
Japan
East Asian food exporters deploy force-limited collaborative arms for mixed-model packing of short-run SKUs. METI industrial automation directives encourage servo-driven motion control adoption. Tokyo-area precision equipment manufacturers supply gravimetric filling systems to pharmaceutical contract packers.
Switzerland
Swissmedic pharmaceutical regulations mandate aggregation-capable secondary packaging integration for unit-dose serialization. Contract packers in Basel and Zurich compress changeover intervals below 15 minutes using modular servo architectures. Precision weighing system suppliers cluster around the country's pharmaceutical manufacturing corridor.
Bagging Equipment Market Vendor Landscape
On the supply side, the industry is tiered between diversified industrial conglomerates and specialized machinery fabricators. German and Japanese engineering clusters anchor premium positioning through captive servo technology and hygienic design expertise. Strategic moves concentrate on modular platform development and predictive maintenance software unbundling. Geographic expansion into Indian food processing and Swiss pharmaceutical contract packing dominates capital allocation decisions.
Among diversified industrial conglomerates, Robert Bosch GmbH and Tokyo Automatic Machinery Works Ltd. exemplify the premium-tier archetype through integrated servo architectures and precision filling capabilities. Haver & Boecker OHG occupies a distinct position within woven bag system specialization for construction and agricultural inputs. Barry-Wehmiller Companies represents the North American consolidator model with project finance capabilities that tilt competitive access toward mid-tier processors.
| Leading Market Players |
|---|
| Barry-Wehmiller Companies |
| Premier Tech Chronos |
| I.M.A. Industria Macchine Automatiche S.p.A. |
| Automated Packaging Systems, Inc. |
| BEUMER Group GmbH & Co. KG |
| Haver & Boecker OHG |
| All-Fill Inc. |
| Robert Bosch GmbH |
| Tokyo Automatic Machinery Works Ltd. |
| Others |
Supply Flow & Price Mechanics
Stainless steel alloy volatility determines both pricing tier spreads and supply chain configuration across bagging equipment manufacturing. Grade 316L price swings compress margin predictability for fabricators locked into fixed-price contracts while forcing tiered pricing stratification based on material certification grades.
Pricing Analysis
Certification level (CE marking under EU Machinery Regulation versus non-certified economy tiers) creates the primary spread between premium and standard equipment pricing. Three-tier pricing structure across FDA-grade pharmaceutical lines, CE-marked food-contact systems, and non-certified agricultural equipment reflects validation cost absorption. Pricing pressure stems from Japanese and German servo motor supply constraints extending delivery windows. Agricultural processors exhibit highest price sensitivity, while pharmaceutical contract packers prioritize traceability compliance over capital cost.
Supply Chain Analysis
German and Japanese precision equipment manufacturers hold concentrated capacity for servo-driven motion control systems and hygienic design engineering. Supply draws from stainless steel mills in Italy and South Korea, precision servo motor producers in Japan and Germany, and control system integrators in Switzerland. Single-source vulnerability runs through Japanese drive manufacturers for high-speed filling applications. Distribution runs through machinery engineering clusters in Stuttgart and Düsseldorf serving EMEA processors, with direct OEM relationships dominating pharmaceutical and food processing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software subscriptions are expanding faster than hardware warranty coverage, creating a service-attach opportunity that concentrates bargaining power with multi-vendor operators demanding API-standardized data portability.
For Market Incumbents: Harden position against emerging automation retrofit specialists by deepening captive servo technology development and accelerating modular platform standardization. CE marking compliance investments create switching costs that protect installed base revenue from Eastern European price competitors. For New Entrants and Emerging Players: Indian cold chain infrastructure expansion under PLI scheme incentives represents the most penetrable geography for moisture-barrier bagging equipment targeting spice and snack exporters. Force-limited collaborative robotics integration offers a go-to-market angle for short-run contract manufacturers in East Asia. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision weighing system specialists with pharmaceutical corridor proximity. Long-term viability hinges on software-configurable platform development rather than throughput maximization hardware. Monitor extended producer responsibility framework implementation timelines as inflection indicators for recyclable film handling capability demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Unbundling | Netherlands and Denmark food processors negotiate standalone SaaS contracts for vibration monitoring. |
| Modular Servo Architecture Development | Swiss pharmaceutical contract packers compress changeover intervals below 15 minutes. |
| Recyclable Film Handling Capability Investment | EU packaging waste directives mandate quick-changeover equipment specifications. |
| Indian Market Geographic Expansion | Gujarat and Maharashtra facilities deploy automated lines under PLI scheme incentives. |
| Collaborative Robotics Convergence | East Asian exporters deploy force-limited arms for mixed-model short-run SKU packing. |
Methodological Framework
Desk research of EU Machinery Regulation compliance databases, FDA food-contact material filings, and stainless steel trade flow data preceded structured interviews with plant engineers at German dairy cooperatives, maintenance directors at Indian spice processing facilities, and aftermarket service heads at pharmaceutical contract packers. Secondary validation drew from ECHA REACH substance inventories, SEC equipment manufacturer filings, and Japanese METI industrial automation directives. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure patterns across food processing and pharmaceutical verticals.
Fixed assumptions across the analysis window include sustained REACH compliance documentation requirements and continued PLI scheme incentive availability for Indian cold chain infrastructure. Segmentation modeling incorporated product type (vertical versus horizontal form-fill-seal), end-use sector (food processing, pharmaceuticals, agriculture, chemicals), technology stack (automation solutions, weighing systems, filling systems, sealing systems), and application physical state (powders, granules, liquids, bulk packaging). CAGRs were derived from regression analysis of historical capital expenditure cycles and projected replacement demand from regulatory refresh mandates.
Practitioners should monitor stainless steel alloy price volatility, servo motor delivery window extensions, and extended producer responsibility framework implementation pace for early signals of forecast revision. Quarterly review of ECHA substance inventory updates, FDA food-contact rule amendments, and Indian FSSAI sanitary design specification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Container Washing System Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Powder Filling Equipment Market