
 Inflatable Void Fill System Market | 2026-2036
Inflatable Void Fill System Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Void Fill System Market Foresight
Single-source reliance on pre-formed bubble wrap is decoupling from large-scale fulfillment operations as packagers adopt on-demand air generation. Sealed Air Corporation leverages integrated equipment-and-film systems to anchor North American e-commerce accounts. Pregis Corporation sustains R&D intensity in biodegradable film formulations. Ranpak Holdings Corp. differentiates through paper-based alternatives that compete alongside inflatable systems in sustainability-sensitive channels.
An inflatable void fill system comprises on-demand air pillow or column generation equipment paired with compatible film substrates, typically coextruded polyethylene ranging from 15 to 40 microns in thickness, designed to occupy empty spaces within shipping containers and absorb shock during transit. The equipment heats and seals flat film into discrete chambers while inflating them with ambient or nitrogen-charged air to specified pressure thresholds. Custom air pillows command margin pools in pharmaceutical and electronics verticals where product-specific cavity geometries prevent migration damage. Automated installation systems represent the fastest-growing configuration as warehouse labor costs and throughput requirements intensify. Biodegradable plastics in material composition remain nascent but attract capital allocation from brands with published packaging reduction commitments.
The EPA regulates volatile organic compound emissions from film extrusion processes, while FDA compliance governs inflatable materials contacting food-grade shipments in the United States. The EU Green Deal and REACH chemical restrictions are reshaping material certification requirements for polyethylene and polypropylene substrates entering European distribution networks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional material qualification investments versus global substrate standardization strategies.
Market Dynamics
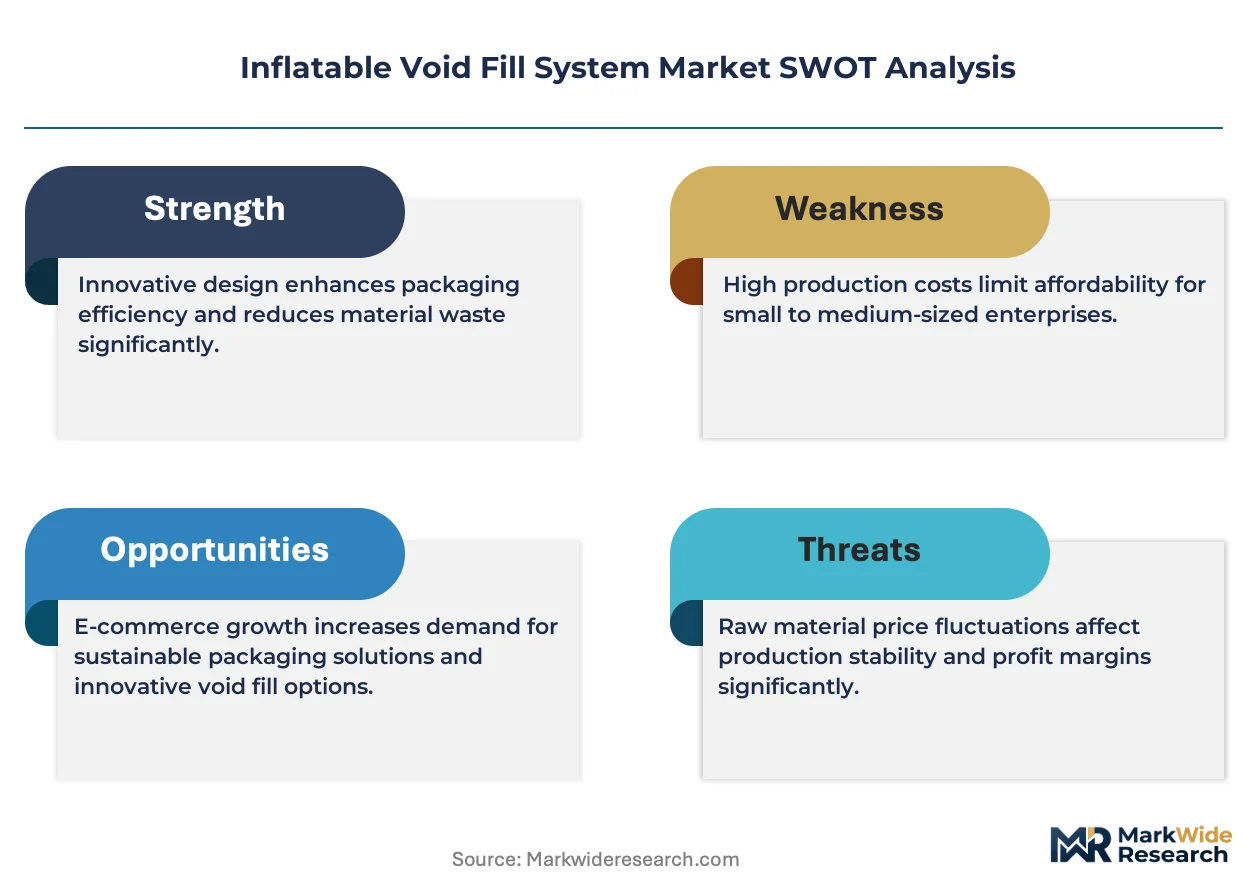
On-demand air generation equipment is decoupling fulfillment operations from pre-formed bubble wrap inventory, compressing warehouse footprints and eliminating dimensional weight penalties through just-in-time cushioning production.
Growth Catalysts
- E-commerce fulfillment automation:Third-party logistics providers in Germany deploy high-speed inflatable systems to process automotive parts and consumer electronics at throughput rates exceeding 500 packages per hour.
- REACH chemical restrictions:The EU Packaging and Packaging Waste Regulation accelerates transitions toward biodegradable polyethylene substrates, creating certified material demand pools for compliant film suppliers.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution networks adopt nitrogen-charged air columns to prevent product migration within insulated shippers during multi-day transit.
Market Restraints
- Petrochemical feedstock volatility:Coextruded polyethylene film costs fluctuate with ethylene spot pricing, squeezing converter margins during upstream supply disruptions.
- Equipment supplier concentration:North American fulfillment networks depend on a narrow base of integrated equipment-and-film system providers, creating single-source vulnerability for maintenance and substrate continuity.
- Paper-based substitution pressure:Ranpak Holdings and competing paper void fill manufacturers capture sustainability-sensitive accounts with curbside-recyclable alternatives that bypass plastic waste concerns.
Strategic Opportunities
- India e-commerce infrastructure buildout:Flipkart and Amazon India fulfillment centers remain underpenetrated by automated inflatable systems, presenting first-mover installation contracts for equipment providers.
- Food-grade inflatable contact materials:FDA-compliant low-density polyethylene films for direct food contact applications open specialty margin pools in meal kit and fresh produce subscription channels.
- Equipment-as-a-service models:Subscription-based pricing for air generation hardware reduces capital barriers for mid-market fulfillment operations, expanding addressable customer segments beyond enterprise accounts.
Industry Challenges
- Biodegradable film certification timelines:ASTM D6400 and EN 13432 industrial compostability testing extends product development cycles by 18-24 months, delaying revenue recognition for novel substrate formulations.
- Legacy warehouse management integration:Pack stations with existing WMS architectures require custom API development to synchronize inflatable equipment with order routing systems, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Void Fill System Market |
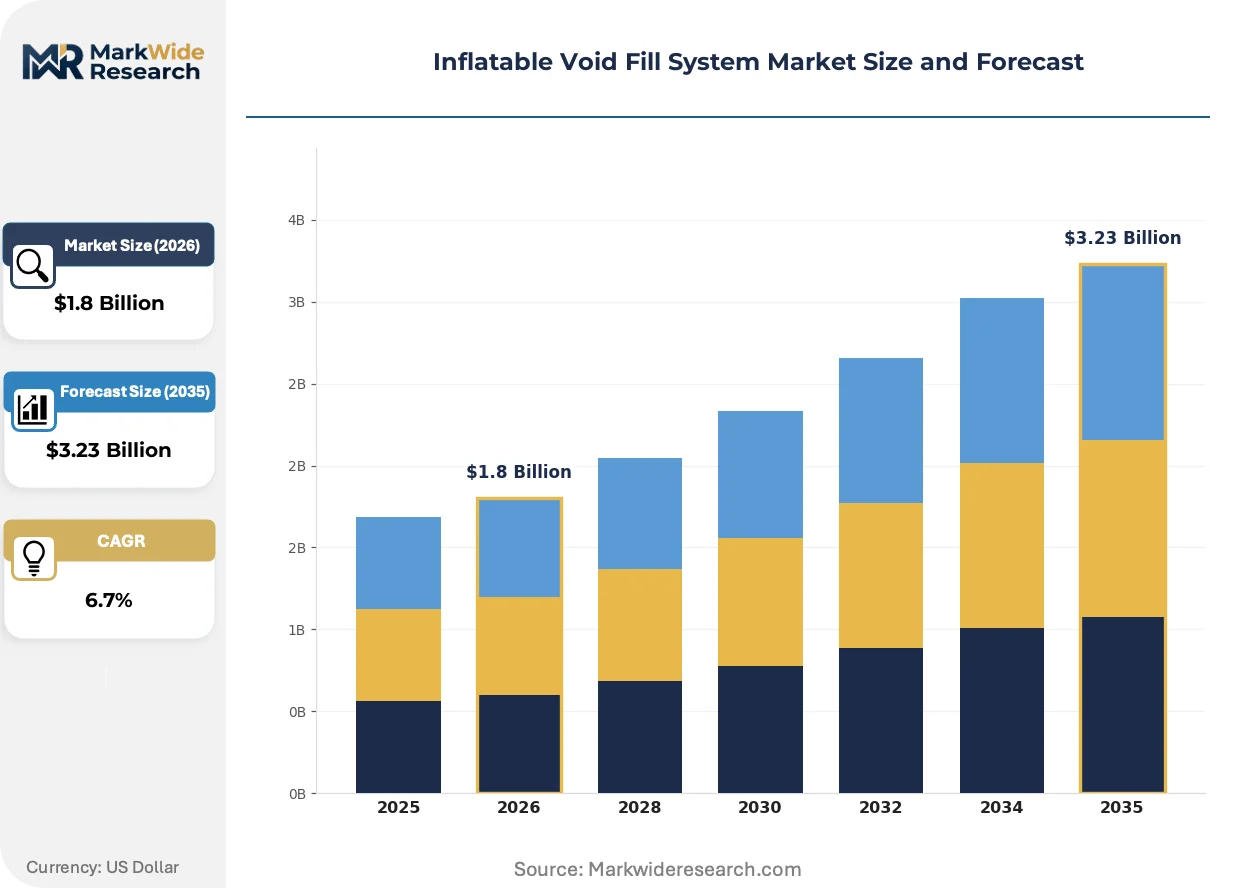
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Air Bags, Custom Air Pillows, Inflatable Columns, Bladder Systems End User: E-Commerce, Retail Packaging, Manufacturing, Transportation Material: Polyethylene, Biodegradable Plastics, Polypropylene, Nylon Installation: Manual Assembly, Automated Systems, Semi-Automated Solutions, On-Demand Production |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Storopack Hans Reichenecker GmbH, Ranpak Holdings Corp., Intertape Polymer Group Inc., Sonoco Products Company, Berry Global Inc., Automated Packaging Systems Inc., Inflatable Packaging Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Void Fill System Market Shifts & Advancements
Electrification of film sealing mechanisms and AI-driven pressure calibration are compressing equipment footprints while expanding substrate compatibility ranges beyond standard polyethylene formulations.
High-frequency induction sealing technology is electrifying the thermal bonding process in next-generation air pillow equipment, replacing resistive heating elements with electromagnetic field generation that reduces energy consumption by forty percent. Pharmaceutical distributors in Switzerland and electronics fulfillment centers in Japan adopt these systems to achieve nitrogen purity thresholds required for moisture-sensitive product protection. The technology is electrifying competitive differentiation among equipment manufacturers, forcing legacy thermal designs into commodity positioning.
The EU Green Deal's extended producer responsibility frameworks are mandating recyclability certification for all polyethylene packaging substrates entering European distribution networks by 2030. Film converters must requalify existing coextrusion formulations through ECHA-registered testing protocols, adding compliance overhead that favors larger substrate suppliers with dedicated regulatory affairs functions. German automotive parts distributors and Dutch flower export operations face the most acute compliance deadlines, accelerating supplier consolidation toward certified material providers.
Outcome-based service contracts are displacing capital equipment purchases among mid-market e-commerce fulfillment operations, transferring maintenance liability and substrate inventory risk to equipment vendors. Third-party logistics providers in France and contract packagers in Spain prefer per-package pricing models that align cushioning costs with actual shipping volumes. This shift concentrates vendor relationships toward integrated system suppliers with balance sheet capacity to carry installed base assets.
Inflatable Void Fill System Market Segmentation
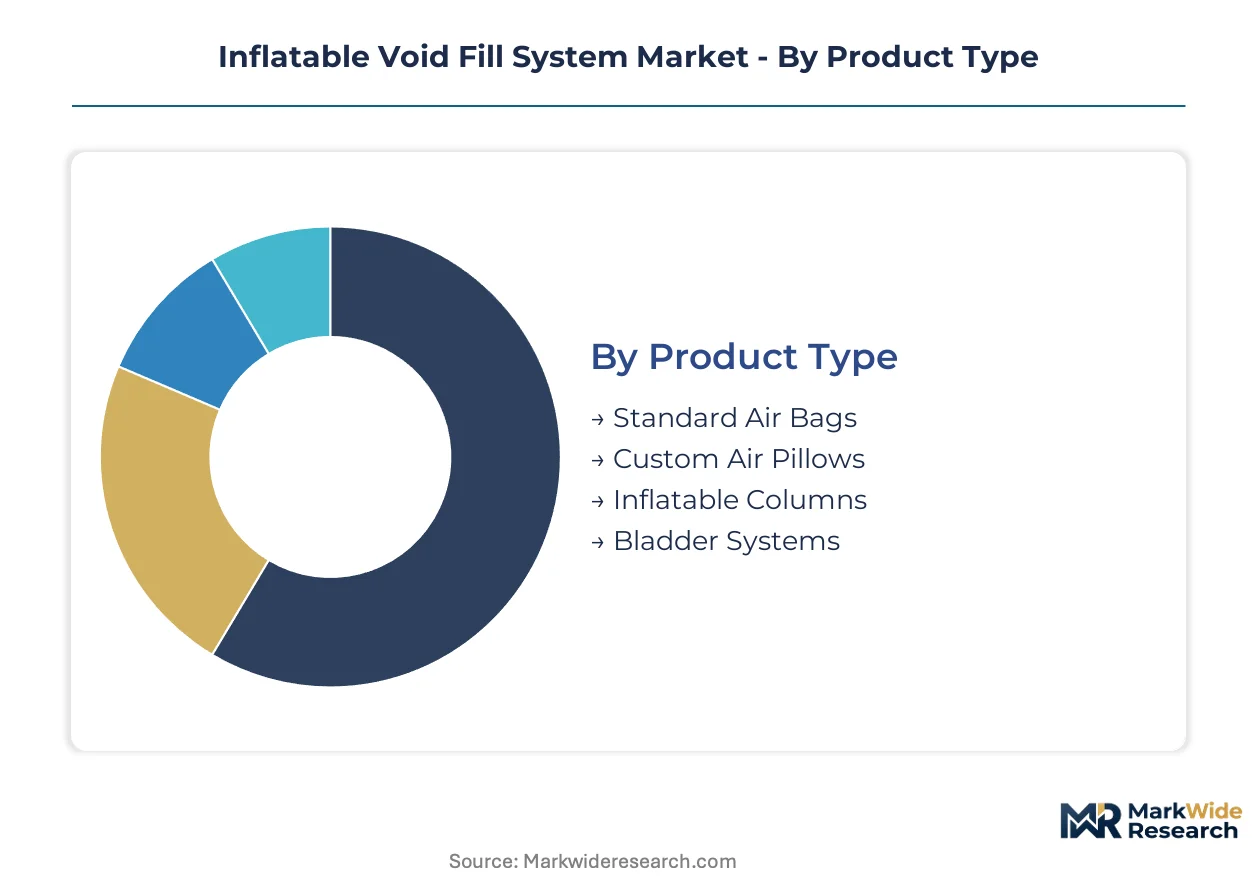
Segmentation in inflatable void fill systems reveals how equipment specifications, material chemistry, and installation intensity map to distinct margin pools. Procurement decisions diverge sharply between high-velocity e-commerce fulfillment and precision pharmaceutical packaging, with material certification requirements acting as the primary filter for supplier qualification.
Product Type:
Upgrade cycles in fulfillment automation are accelerating replacement of legacy bubble wrap stations with integrated air generation equipment, compressing replacement timelines from seven-year horizons to four-year refresh rates.
- Standard Air Bags:These chambers utilize 20-30 micron coextruded polyethylene film sealed through thermal bonding to create uniform cushioning geometry. Demand concentrates in German automotive parts distribution networks where high-volume throughput requirements exceed 500 packages per hour. The EU Packaging and Packaging Waste Regulation is forcing substrate transitions toward certified recyclable films, adding compliance overhead for converters.
- Custom Air Pillows:Product-specific cavity geometries accommodate irregular pharmaceutical vial arrangements and electronics component nesting. Swiss cold chain distributors and Japanese electronics fulfillment centers deploy nitrogen-charged variants to achieve moisture purity thresholds for sensitive cargo. Margin pools expand through FDA-compliant formulations for direct food contact applications.
- Inflatable Columns:Vertical chamber arrays stabilize palletized loads in transportation corridors.
- Bladder Systems:Reusable inflatable dunnage targets manufacturing returnable packaging loops with durability specifications.
Standard air bags sit at the top of the volume ranking, with custom air pillows climbing the fastest.
End User:
Cost tier differentiation separates capital-intensive automated installations from manual pack stations, with subscription pricing models eroding traditional procurement boundaries between enterprise and mid-market accounts.
- E-Commerce:Third-party logistics providers deploy on-demand air generation to eliminate dimensional weight penalties and compress warehouse footprints. Flipkart and Amazon India fulfillment centers remain underpenetrated, presenting installation contract opportunities for equipment vendors with localized service networks.
- Retail Packaging:Store-level pack stations prioritize equipment compactness over throughput velocity.
- Manufacturing:Captive packaging operations within automotive and electronics assembly plants favor semi-automated configurations.
- Transportation:Freight consolidators utilize inflatable columns for load stabilization in cross-dock environments.
E-commerce commands the dominant revenue share, while pharmaceutical cold chain expansion within manufacturing applications demonstrates the steepest expansion trajectory.
Material:
Supply concentration in petrochemical feedstock regions shapes converter economics, with ethylene spot volatility transmitting directly to film pricing and margin compression during upstream disruptions.
- Polyethylene:Low-density and linear low-density formulations dominate substrate volumes through coextrusion compatibility with standard heat-sealing equipment. REACH chemical restrictions and ECHA-registered testing protocols are requalifying existing formulations, favoring larger suppliers with dedicated regulatory affairs functions.
- Biodegradable Plastics:ASTM D6400 and EN 13432 industrial compostability certification extends development cycles by 18-24 months. Pregis Corporation and competing converters allocate capital toward certified substrate pipelines to capture sustainability-sensitive accounts.
- Polypropylene:Higher stiffness properties suit temperature-resistant applications in food distribution.
- Nylon:Barrier-grade films target nitrogen retention in pharmaceutical cold chain configurations.
Polyethylene maintains volume leadership, with biodegradable plastics gaining share fastest among brands with published packaging reduction commitments.
Installation:
Customer type stratification separates enterprise fulfillment networks with dedicated maintenance staff from mid-market operations outsourcing equipment uptime responsibility to vendor service contracts.
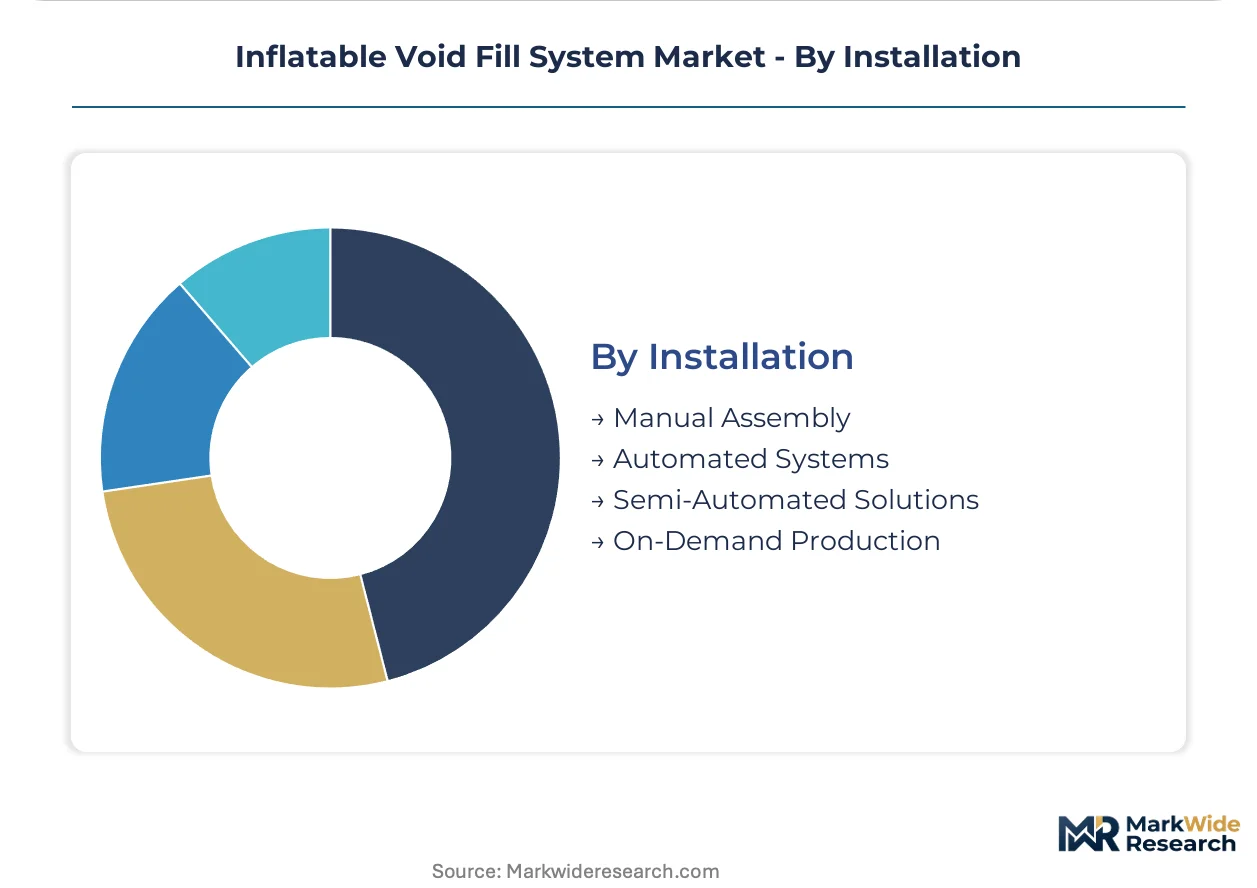
- Automated Systems:High-frequency induction sealing technology reduces energy consumption by forty percent versus resistive heating elements. French third-party logistics providers and Spanish contract packagers increasingly prefer outcome-based service contracts with per-package pricing that aligns cushioning costs with shipping volumes.
- On-Demand Production:Just-in-time air generation decouples operations from pre-formed inventory, though legacy warehouse management system integration requires custom API development that inflates implementation costs.
- Manual Assembly:Entry-level pack stations without compressed air infrastructure.
- Semi-Automated Solutions:Hybrid configurations bridging manual feed with automated sealing cycles.
Automated systems anchor current revenue concentration, with on-demand production expanding most quickly as warehouse labor costs intensify throughput requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive parts distribution networks anchor installed base concentration for high-throughput inflatable systems, with regulatory pressure from Brussels accelerating material transitions across European fulfillment corridors.
Germany
Automotive parts distributors in Stuttgart and Wolfsburg deploy automated air generation equipment processing 500-plus packages hourly. The EU Packaging and Packaging Waste Regulation mandates recyclability certification for polyethylene substrates entering distribution networks by 2030. Bavarian converter operations near Munich requalify coextrusion formulations through ECHA-registered testing protocols.
United States
Third-party logistics providers in Chicago and Dallas-Fort Worth compress warehouse footprints through on-demand cushioning production. FDA compliance governs inflatable materials contacting food-grade shipments in meal kit distribution channels. EPA volatile organic compound regulations from film extrusion processes shape converter site selection in Texas and Ohio.
India
Flipkart and Amazon India fulfillment centers in Bangalore and Hyderabad remain underpenetrated by automated inflatable systems. The Bureau of Indian Standards monitors packaging material specifications for e-commerce shipments. Maharashtra-based contract packagers near Mumbai represent first-mover installation opportunities for equipment vendors with localized service networks.
Japan
Electronics fulfillment centers in Osaka and Nagoya adopt nitrogen-charged air columns for moisture-sensitive component protection. METI efficiency standards for industrial equipment influence sealing mechanism specifications. Chubu region pharmaceutical distributors deploy high-frequency induction sealing technology to achieve nitrogen purity thresholds.
Switzerland
Cold chain distributors in Basel and Zurich utilize custom air pillows for temperature-sensitive biologics transit. Swissmedic pharmaceutical packaging guidelines shape cavity geometry specifications for vial arrangements. Geneva-area logistics operations integrate nitrogen-charged variants into multi-day insulated shipper configurations.
Inflatable Void Fill System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable substrate specialization and equipment-as-a-service models. The vendor base concentrates around integrated equipment-and-film system providers with captive converter relationships. Three archetypes dominate: multinational packaging conglomerates with extrusion assets, regional equipment specialists with localized service networks, and sustainability-focused substrate innovators with certified biodegradable pipelines. Capacity expansion in Asia-Pacific fulfillment corridors and strategic partnerships for WMS integration represent the dominant competitive vectors.
Within the multinational conglomerate tier, Sealed Air Corporation and Berry Global Inc. exemplify scale-driven positioning through integrated manufacturing footprints. Pregis Corporation occupies a specialist position in biodegradable film formulation development. Ranpak Holdings Corp. anchors the paper-based alternative segment, competing alongside inflatable systems in sustainability-sensitive channels. These three represent divergent strategic postures: substrate standardization, material innovation, and category substitution.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Storopack Hans Reichenecker GmbH |
| Ranpak Holdings Corp. |
| Intertape Polymer Group Inc. |
| Sonoco Products Company |
| Berry Global Inc. |
| Automated Packaging Systems Inc. |
| Inflatable Packaging Inc. |
| Others |
Supply & Pricing Matrix
Skilled equipment technician pools in southern Germany concentrate maintenance expertise, widening labor-cost differentials between automated system tiers and compressing pricing spreads across standard and premium inflatable void fill configurations.
Pricing Analysis
Ethylene spot price volatility transmits directly to coextruded polyethylene film costs, forcing converters to absorb margin compression during upstream petrochemical disruptions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact formulations from industrial-grade substrates and entry-level manual equipment. Cost compression in standard air bag tiers is intensifying because of paper-based substitution pressure from Ranpak Holdings and competing curbside-recyclable alternatives. Mid-market third-party logistics providers exhibit highest price sensitivity, while pharmaceutical cold chain distributors prioritize nitrogen purity certification over unit economics.
Supply Chain Analysis
Ocean freight rate fluctuations between Asia-Pacific resin producers and European converter operations amplify working capital requirements for film inventory positioning. Feedstock supply concentrates in Saudi Arabia, South Korea, and the United States Gulf Coast, with ethylene cracker capacity expansions in each region shaping regional pricing benchmarks. Converter operations draw from linear low-density polyethylene pellets, nitrogen generation systems, and induction sealing components. Single-source vulnerability persists for high-frequency induction sealing equipment, where Sealed Air Corporation and limited integrated vendors control maintenance access. Distribution runs through captive converter relationships for multinational packaging conglomerates and independent film suppliers serving regional equipment specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflatable void fill system market represents a late-cycle quality story as e-commerce fulfillment automation shifts procurement criteria from capital cost minimization toward total cost of ownership and nitrogen purity specifications.
For Market Incumbents: Anticipate biodegradable substrate certification timelines extending competitive moats for converters with ASTM D6400 and EN 13432 pipelines already in progress. Defend against paper-based substitution by accelerating high-frequency induction sealing technology deployment to achieve forty percent energy reduction benchmarks. Deepen backward integration into film extrusion assets to control polyethylene substrate continuity during ethylene spot volatility. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation in Europe opens a window for certified biodegradable film specialists to capture sustainability-sensitive accounts from incumbent polyethylene converters. Target underpenetrated Flipkart and Amazon India fulfillment centers in Bangalore and Hyderabad with equipment-as-a-service models that reduce capital barriers for mid-market adoption. Lead with localized service networks and per-package pricing structures that align vendor incentives with customer shipping volumes. For Investors and Strategic Acquirers: Private equity firms with industrial packaging portfolios are the most active acquirer in this space, consolidating regional equipment specialists to build integrated system capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity film production scale. Monitor biodegradable certification completion rates among substrate innovators as the inflection indicator for sustainable competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Certification Investment | ASTM D6400 and EN 13432 compliance captures EU Green Deal-mandated demand pools by 2030. |
| Equipment-as-a-Service Model Launch | Per-package pricing aligns vendor revenue with French third-party logistics provider shipping volumes. |
| High-Frequency Induction Sealing Adoption | Forty percent energy reduction meets METI efficiency standards for Japanese electronics fulfillment centers. |
| India Service Network Expansion | Localized maintenance capacity secures first-mover installation contracts at underpenetrated Flipkart facilities. |
| Food-Grade FDA Compliance Pathway | Direct-contact low-density polyethylene formulations open meal kit subscription channel margin pools. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging equipment procurement directors, film converter operations managers, third-party logistics fulfillment executives, and regulatory affairs specialists at multinational conglomerates with secondary validation from SEC 10-K filings, EU ECHA-registered testing protocol databases, customs and trade data on polyethylene resin flows, and Bureau of Indian Standards packaging specifications. Bottom-up equipment installation tracking and top-down e-commerce fulfillment revenue estimates were triangulated against regional automotive parts distribution network throughput data.
Historical reference periods anchored volume and value projections, with modeling spanning equipment replacement cycle compression from seven-year to four-year refresh rates and substrate transition timelines under extended producer responsibility frameworks. Segmentation dimensions included product type, end-user vertical, material chemistry tier, and installation automation intensity. CAGRs were derived from equipment shipment data cross-referenced with fulfillment center expansion announcements and petrochemical feedstock capacity forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Packaging and Packaging Waste Regulation enforcement or sustained ethylene price volatility. A model refresh is warranted upon material change in biodegradable certification completion rates or India e-commerce infrastructure buildout pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Packing Belt Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Packer Market
Packaging Equipment
Nitrogen Filling Systems Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Coding and Marking Equipment Market