
 Global End-Of-Line Packaging Market | 2026-2036
Global End-Of-Line Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global End-Of-Line Packaging Market Analysis
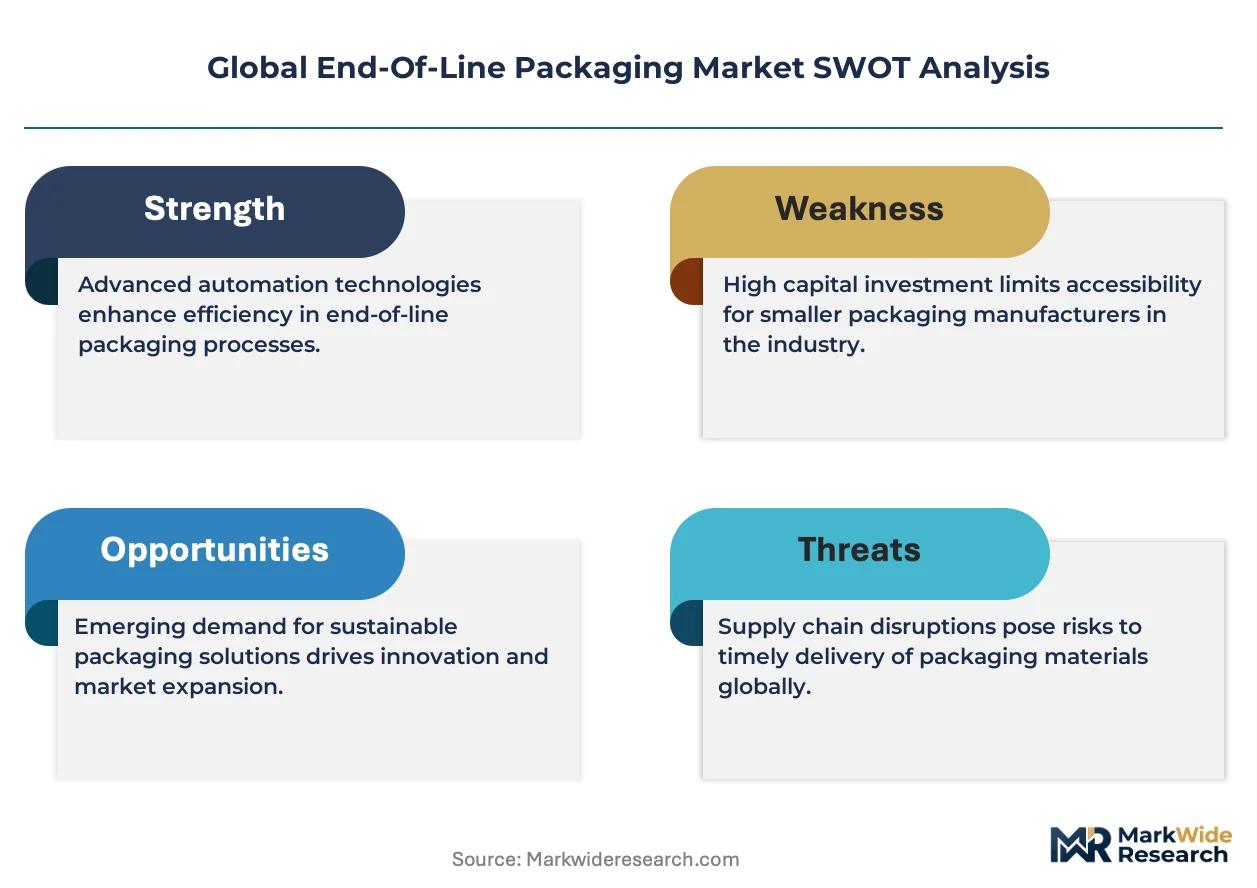
The gap between premium automated lines and basic semi-automatic equipment is restructuring procurement patterns across the Global End-Of-Line Packaging Market. Krones AG leverages its integrated beverage systems expertise to dominate high-throughput palletizing installations for multinational bottlers. DS Smith anchors its position through corrugated box design specialization that feeds directly into downstream cartoning workflows. Robert Bosch GmbH differentiates via deep R&D investment in robotic pick-and-place modules that reduce changeover times.
End-of-line packaging encompasses the final automated or semi-automated operations that consolidate, protect, and unitize finished goods for distribution, typically operating at throughputs exceeding 200 units per minute for beverage applications. These systems employ servo-driven stretch film dispensers, heat-shrink tunnels with precise temperature control bands, and gantry or articulated robot arms to form stable pallet loads prior to warehouse dispatch. Palletizing and robotic technology segments command the strongest margin pools as labor costs escalate and throughput requirements tighten across food and beverage operations. Stretch film applications sustain volume leadership in consumer electronics, where thin-gauge pre-stretched formulations reduce material consumption per load. Cartoning retains maturity in pharmaceuticals, where serialization and aggregation requirements add regulatory complexity rather than equipment turnover.
The US FDA enforces drug traceability through the Drug Supply Chain Security Act, compelling pharmaceutical end-of-line upgrades with aggregation-capable cartoning and verification systems. The EU F-Gas Regulation and REACH directives constrain blowing-agent chemistry in shrink film formulations, pushing converters toward monomaterial and bio-based alternatives. China's SAMR enforces GB standards for pallet dimensional consistency that affect export-bound equipment specifications. Stakeholders must weigh regulatory compliance timelines against automation payback periods when sequencing capital deployment across geographies.
Market Dynamics
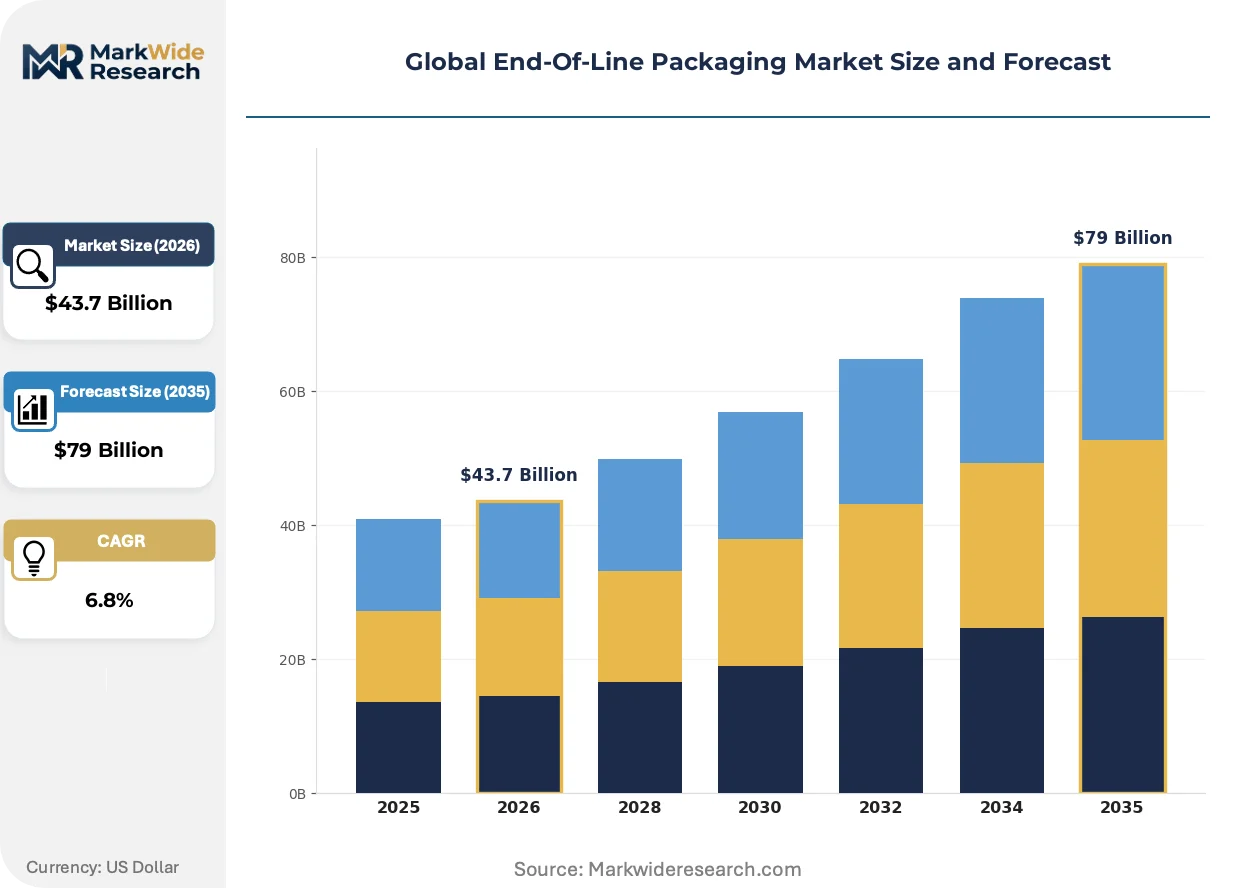
The Global End-Of-Line Packaging Market is undergoing a structural bifurcation between high-throughput automated installations and retrofit semi-automatic upgrades, driven by divergent labor cost trajectories and serialization compliance deadlines across pharmaceutical and food processing corridors.
Growth Catalysts
- EU Falsified Medicines Directive:Aggregation mandates for pharmaceutical cartoning are compelling European manufacturers to deploy verification-capable end-of-line systems before enforcement deadlines tighten.
- Stretch film pre-stretching technology:Thin-gauge formulations are cutting material consumption per pallet load in consumer electronics distribution centers, accelerating equipment replacement cycles.
- Yangtze River Delta concentration:Domestic Chinese food and beverage brands are retrofitting manual handling facilities with automated shrink wrapping and palletizing lines to match export quality benchmarks.
Market Restraints
- Resin price volatility:Petrochemical feedstock fluctuations are compressing margins for stretch film and shrink wrap converters, forcing equipment buyers to absorb material cost pass-throughs.
- German robotics supply concentration:Articulated arm palletizing systems rely on a narrow base of precision servo motor suppliers, creating lead time vulnerability for high-throughput beverage installations.
- EU F-Gas Regulation constraints:Blowing-agent chemistry restrictions are limiting shrink tunnel heat-recovery efficiency gains, capping energy cost reductions for film-based unitizing operations.
Strategic Opportunities
- India pharmaceutical corridor:CDSCO serialization timelines lag EU and US enforcement by several years, creating a window for aggregation-capable cartoning system deployment ahead of regulatory alignment.
- Monomaterial film convergence:Heat-shrink formulations compatible with mechanical recycling streams are opening retrofit demand from brands facing extended producer responsibility obligations.
- Servitization revenue models:Outcome-based contracts tying equipment payments to uptime guarantees are penetrating multinational bottler procurement frameworks, displacing traditional capex purchase structures.
Industry Challenges
- Mechatronics skill scarcity:Servo-driven stretch film dispensers and robotic palletizing cells require maintenance technicians with cross-trained mechanical-electrical competencies that outpace vocational pipeline output.
- Legacy WMS integration friction:Greenfield robotic palletizing installations face data protocol mismatches with existing warehouse management systems, extending commissioning timelines and acceptance testing periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global End-Of-Line Packaging Market |
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartoning, Stretch Film, Shrink Wrapping, Palletizing Technology: Automatic, Semi-Automatic, Robotic, Manual End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, Personal Care Packaging Type: Boxes, Pallets, Bundles, Trays |
| Companies Covered | Krones AG, DS Smith, Combi Packaging Systems LLC, ProMach, Robert Bosch GmbH, Coesia Group, Sidel Group, Festo, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global End-Of-Line Packaging Market Emerging Trajectories
Active developments across materials science, regulatory compliance architecture, and buyer procurement logic are compressing equipment refresh cycles and reconfiguring vendor-customer relationships in end-of-line packaging.
Collaborative robot palletizing is expanding into mid-volume food and beverage operations previously served by fixed gantry systems. Regional bottlers in Spain and Mexico are deploying force-limited articulated arms for mixed-SKU pallet building at throughputs below 150 units per minute. The technology is expanding into applications where changeover flexibility outweighs pure speed, compressing the addressable market for traditional Cartesian coordinate machines.
REACH and EU F-Gas Regulation amendments are constraining perfluorinated compound use in high-clarity shrink films. Converters in Italy and Poland are accelerating trials of bio-based polyolefin alternatives with comparable optical properties. Pharmaceutical cold-chain shippers represent the most affected segment, as temperature-indicating film integrity cannot degrade during regulatory qualification periods.
Consolidated procurement through corporate engineering standards is displacing plant-level equipment specification authority. Multinational consumer packaged goods operators in the United States and Germany are mandating preferred vendor lists for palletizing and cartoning modules, narrowing competitive access for regional machinery builders. This concentration is most visible in beverage operations where parent-company engineering teams dictate subsystem interoperability requirements across multiple production sites.
Global End-Of-Line Packaging Market Segmentation
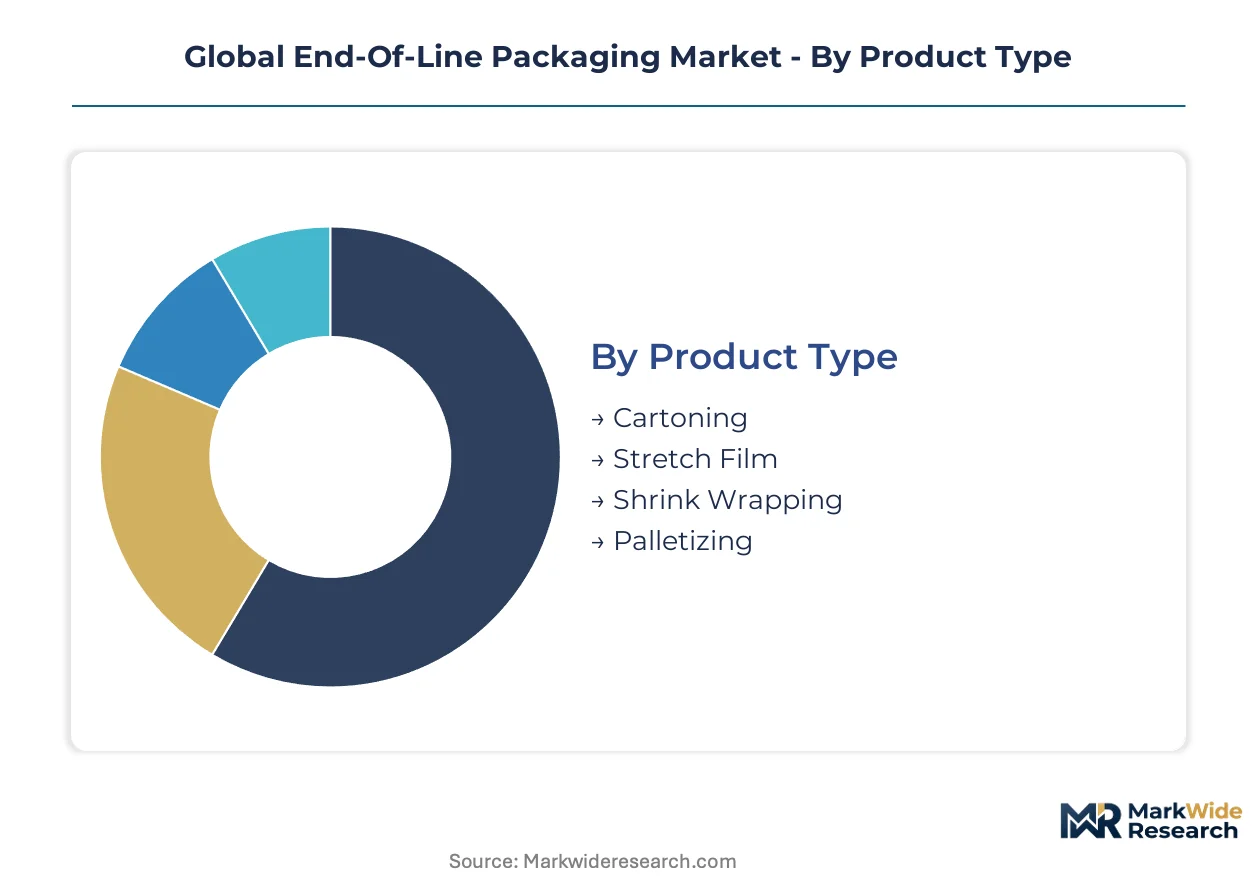
End-of-line packaging procurement diverges sharply by integration depth, with standalone palletizing cells commanding premium pricing against embedded cartoning modules. Technology choices cascade through material selection and labor substitution economics, creating distinct margin pools across installation types.
Product Type:
Standalone palletizing systems operate independently of upstream filling lines, while stretch film and shrink wrapping modules embed directly into conveyor-fed workflows.
- Cartoning:Servo-driven carton erectors and closure systems handle rigid board formats at throughputs exceeding 300 units per minute. Pharmaceutical serialization mandates in Germany and the United States are accelerating aggregation-capable cartoning deployments ahead of regulatory deadlines.
- Palletizing:Gantry and articulated robot arms form stable unit loads using slip sheets, corner boards, and tier sheets prior to stretch film application. China's Yangtze River Delta beverage corridor dominates volume installations as domestic brands retrofit manual handling facilities.
- Stretch Film:Pre-stretched thin-gauge formulations reduce resin consumption per pallet load in consumer electronics distribution.
- Shrink Wrapping:Heat-shrink tunnels with multi-zone temperature control bundle multi-packs for retail-ready display.
Volume placements concentrate in Palletizing; the faster expansion belongs to Cartoning.
Technology:
Cost tier stratification separates fully automated lines from semi-automatic retrofits, with robotic systems occupying the premium installation bracket.
- Robotic:Force-limited collaborative arms enable mixed-SKU pallet building without safety fencing at throughputs below 150 units per minute. Spanish and Mexican regional bottlers are deploying these systems where changeover flexibility outweighs pure speed requirements.
- Automatic:Integrated servo-controlled lines operate unattended across cartoning, wrapping, and palletizing stations with centralized HMI oversight. US pharmaceutical manufacturers favor these configurations to meet FDA Drug Supply Chain Security Act traceability requirements.
- Semi-Automatic:Operator-assisted stretch film dispensers and manual case sealers bridge labor cost gaps in emerging market facilities.
- Manual:Hand wrapping and pallet assembly persist in low-volume specialty operations and developing economy micro-facilities.
Automatic systems capture the highest absolute placements; robotic configurations are climbing the fastest on collaborative technology adoption.
End User:
Application severity drives specification divergence, with pharmaceutical cold-chain demands imposing tighter validation protocols than ambient food handling.
- Food & Beverage:High-throughput bottling lines require synchronized palletizing speeds exceeding 200 units per minute with washdown-capable construction. China's domestic brand retrofit wave concentrates demand for shrink wrapping and robotic palletizing in the Yangtze River Delta cluster.
- Pharmaceuticals:Aggregation-capable cartoning with serialization verification commands premium pricing due to EU Falsified Medicines Directive and US DSCSA compliance architecture. Cold-chain shippers impose additional temperature-indicating film integrity requirements.
- Consumer Electronics:Thin-gauge pre-stretched film formulations minimize material consumption for high-value device distribution.
- Personal Care:Mixed-SKU handling and promotional bundling favor flexible robotic palletizing over fixed gantry systems.
Food & Beverage dominates absolute volume; Pharmaceuticals posts the steepest expansion trajectory on regulatory-driven equipment refresh cycles.
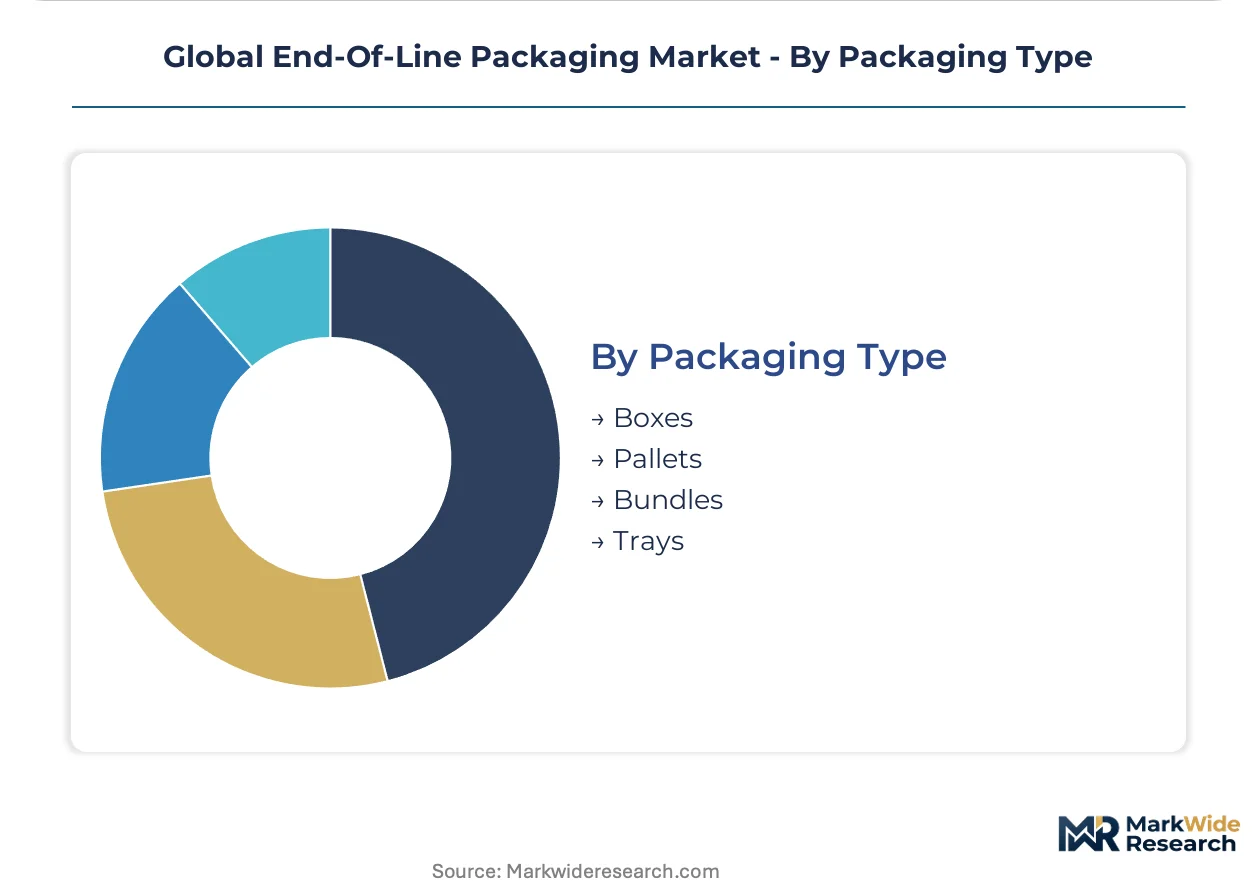
Packaging Type:
Geographic concentration in export-oriented manufacturing clusters shapes pallet and bundle specification standards.
- Pallets:Wooden and plastic platform unitization remains the dominant dispatch format for intermodal freight. China's SAMR enforces GB standards for dimensional consistency that affect export-bound equipment specifications.
- Boxes:Corrugated RSC and die-cut formats feed directly into downstream cartoning workflows with automated case packing.
- Bundles:Multi-unit shrink-wrapped configurations serve retail-ready shelf placement requirements.
- Trays:Display-ready platforms support point-of-sale merchandising for personal care and electronics products.
Pallet placements lead in absolute terms; bundle configurations gain share fastest on retail-ready packaging trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors end-of-line packaging retrofit activity as Chinese food and beverage brands replace manual handling with automated stretch film and palletizing systems to meet export quality benchmarks.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina are expanding aggregation-capable cartoning lines to comply with FDA Drug Supply Chain Security Act serialization mandates. The FDA enforcement timeline is compressing equipment procurement cycles. Chicago-area distribution centers for consumer electronics deploy thin-gauge pre-stretched film systems to reduce resin consumption per pallet load.
Germany
Bavarian beverage bottlers source high-throughput palletizing installations from precision automation suppliers concentrated in Baden-Württemberg. The EU F-Gas Regulation constrains blowing-agent chemistry in shrink tunnel operations. Stuttgart's industrial automation corridor supplies servo motor components for robotic palletizing cells serving export-bound pharmaceutical packaging lines.
China
Domestic food brands in Shanghai and Jiangsu province retrofit facilities with automated shrink wrapping systems under SAMR-enforced GB standards for pallet dimensional consistency. The national dual carbon goals accelerate energy-efficient heat-shrink tunnel adoption. Suzhou's machinery manufacturing cluster produces stretch film dispensers for regional consumer electronics distribution networks.
India
Maharashtra-based pharmaceutical contract manufacturers prepare for CDSCO serialization timelines lagging EU enforcement by several years. The country's national pharmaceutical regulator is aligning aggregation requirements with international traceability standards. Ahmedabad's formulation packaging corridor pilots robotic cartoning modules ahead of regulatory deadline acceleration.
Spain
Regional bottlers in Catalonia deploy force-limited collaborative robot arms for mixed-SKU pallet building at throughputs below 150 units per minute. The EU Falsified Medicines Directive drives verification-capable end-of-line system adoption. Barcelona's packaging machinery district serves mid-volume food operations prioritizing changeover flexibility over pure speed.
Global End-Of-Line Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and regulatory compliance capability. The market exhibits tiered concentration with multinational system integrators controlling high-throughput beverage installations while regional specialists serve mid-volume retrofit demand. Three archetypes dominate: integrated line builders with captive control technology, corrugated substrate specialists feeding downstream cartoning workflows, and precision robotics suppliers reducing pharmaceutical changeover times. Competitive moves center on servitization revenue models tying payments to uptime guarantees, and backward integration into servo motor and control system production to narrow supply vulnerability.
Among Germany-based precision automation suppliers, Krones AG and Robert Bosch GmbH exemplify divergent strategic positions. Krones anchors the integrated beverage systems tier through captive palletizing technology bundled with upstream filling line coordination. Bosch occupies the robotic module specialist position with articulated arm systems targeting pharmaceutical serialization applications. DS Smith represents the substrate-to-systems archetype, leveraging corrugated box design specialization that feeds directly into downstream cartoning workflows for consumer goods distribution.
| Leading Market Players |
|---|
| Krones AG |
| DS Smith |
| Combi Packaging Systems LLC |
| ProMach |
| Robert Bosch GmbH |
| Coesia Group |
| Sidel Group |
| Festo |
| IMA Group |
| Others |
Supply Flow & Price Mechanics
Mechatronics technician scarcity in Baden-Württemberg widens labor-cost differentials between premium robotic installations and semi-automatic retrofits, compressing pricing spreads at the mid-tier where buyers trade throughput guarantees for capital flexibility.
Pricing Analysis
Outcome-based contracts tying equipment payments to uptime guarantees anchor value-based pricing for high-throughput beverage lines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from commodity stretch film dispensers. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in semi-automatic tiers is intensifying because resin price volatility forces converters to pass through material costs. Regional machinery builders in emerging markets exhibit highest price sensitivity; multinational bottlers with corporate engineering standards show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German precision servo motor suppliers serving articulated arm palletizing systems. Component manufacturing concentrates in Germany, China, and Italy. Raw material dependencies include petrochemical resins for film formulations, rare-earth magnets for servo motors, and specialty steels for robotic arm construction. Supply chain risk centers on tariff exposure for Chinese-manufactured control systems. Distribution runs through OEM-direct channels for large installations and regional distributor networks for retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Falsified Medicines Directive aggregation mandates erect barrier-to-entry moats favoring vendors with pre-validated pharmaceutical architectures.
For Market Incumbents: Cement market position through captive servo motor production and backward integration into control system manufacturing. Regional specialists threaten margin pools in mid-volume food applications; counter by locking in multinational bottlers through corporate engineering standards that specify subsystem interoperability. For New Entrants and Emerging Players: Mid-volume pharmaceutical contract manufacturers in India represent an underserved buyer archetype with lagging CDSCO compliance timelines. Penetrate this white-space through aggregation-capable cartoning modules priced below EU-validated systems. Lead with regulatory consultancy bundling to differentiate from established automation suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with robotic module specialists given collaborative arm adoption acceleration in mixed-SKU operations. Long-term viability favors precision automation vendors with pharmaceutical serialization expertise. Watch CDSCO deadline acceleration as inflection indicator for Indian pharmaceutical corridor equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servitization Revenue Models | Outcome-based contracts displace capex purchases among multinational bottlers seeking uptime guarantees. |
| Backward Integration into Servo Motors | In-house production of precision components narrows supply vulnerability from German motor suppliers. |
| Monomaterial Film Development | Heat-shrink formulations compatible with mechanical recycling streams address EU extended producer responsibility obligations. |
| Collaborative Robot Deployment | Force-limited arms expand addressable market into mid-volume food operations below 150 units per minute. |
| Regulatory Pre-Validation Investment | FDA and EMA aggregation-ready architectures command premium pricing in pharmaceutical procurement cycles. |
Methodological Framework
Independent corroboration across plant engineers at beverage bottlers, procurement leads at pharmaceutical contract manufacturers, and aftermarket service heads at automation distributors underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and channel partners combined with secondary validation from customs records, SEC filings of listed machinery builders, and industry association production surveys. Bottom-up installation counts triangulate against top-down market sizing.
Rate-of-change decomposition separates volume effects from mix shifts across the projection horizon. Segmentation dimensions modeled include technology tier, end-use industry, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and compliance deadline phasing. Industry-specific forecast inputs incorporate pharmaceutical serialization enforcement timelines and food and beverage export quality benchmark adoption curves.
Revisions become necessary when resin price volatility exceeds historical bands or when regulatory enforcement timelines accelerate materially. Deviation in mechatronics technician pipeline output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Rotary Tray Sealers Market
Packaging Equipment
Stretch Wrappers Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Basket Granulator Extruder Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Flow Wrap Packaging Market