
 Hot Fill Packaging Market | 2026-2036
Hot Fill Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Fill Packaging Market Outlook
Asset-light contract manufacturing and third-party leasing of hot fill lines is rewriting capital requirements for mid-tier beverage entrants. Graham Packaging Company leverages captive blow-molding capacity to sustain cost advantages across North American dairy and juice accounts. ALPLA Werke Alwin Lehner GmbH and Co KG anchors European supply through integrated preform production near major bottling corridors. Amcor plc differentiates via multi-layer barrier technologies that extend shelf life for aseptic-hot fill hybrid applications.
Hot fill packaging refers to containers engineered to withstand liquid filling temperatures between 82°C and 96°C without dimensional distortion, typically constructed from heat-set PET, glass, or multilayer polypropylene with crystallinity-enhanced sidewalls. The process sterilizes both product and interior container surfaces, eliminating post-fill pasteurization for acidic beverages and ready-to-drink soups. Plastic bottles occupy the largest volume share due to lightweighting advantages and compatibility with existing dairy and juice infrastructure. Stand-up pouches represent the fastest-expanding packaging type as brands seek format differentiation in functional beverages and portable meal solutions. Glass jars retain premium positioning in organic and clean-label segments where consumer perception favors inert material contact.
FDA regulations under 21 CFR Part 113 govern low-acid food hot fill processes in the United States, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for PET containers sold across member states. EFSA guidelines on food contact materials further constrain additive migration limits, pushing converters toward virgin-quality recycled PET flake. REACH compliance in Europe and evolving EPA frameworks on per- and polyfluoroalkyl substances are reshaping material qualification timelines for barrier coatings. Stakeholders must monitor regulatory divergence between jurisdictions to avoid dual-certification costs that erode margin on standardized global product lines.
Market Dynamics
EU recyclability mandates under the Packaging and Packaging Waste Regulation are compressing converter margins while forcing rapid material requalification cycles across PET hot fill supply chains.
Growth Catalysts
- Heat-set PET crystallinity advances:Enhanced sidewall engineering enables thinner-gauge bottles to withstand 96°C filling without deformation, reducing resin consumption per unit for juice processors.
- EU recycled content mandates:The Packaging and Packaging Waste Regulation's minimum thresholds for post-consumer PET are pulling investment toward food-grade rPET flake purification capacity near German bottling corridors.
- Ready-to-drink tea expansion:Shelf-stable beverage brands in Southeast Asia are adopting hot fill protocols to bypass cold-chain infrastructure gaps in tropical distribution.
Market Restraints
- Preform supply concentration:European hot fill bottle converters depend on a narrow base of integrated preform producers clustered in southern Germany and northern Italy.
- Barrier coating qualification timelines:EFSA migration limits on novel oxygen scavengers extend certification cycles to 18-24 months, freezing formulation choices for aseptic-hot fill hybrids.
- Glass substitution in premium segments:Organic beverage brands retain preference for inert glass contact surfaces, capping PET penetration in clean-label SKUs above $4.50 retail price points.
Strategic Opportunities
- Stand-up pouch format expansion:Functional beverage startups in South Korea are piloting hot fill-compatible multilayer pouches for protein-fortified soups, bypassing rigid bottle tooling costs.
- US dairy infrastructure retrofit:Existing aseptic milk lines in Wisconsin and New York can be converted to hot fill at one-third of greenfield capex, unlocking shelf-stable drinkable yogurt capacity.
- India PLI scheme alignment:The Production Linked Incentive scheme for food processing equipment subsidizes domestic blow-molding line installation, reducing import dependence for PET bottle supply.
Industry Challenges
- Heat-set process engineering talent:Crystallinity control technicians with simultaneous expertise in blow-molding dynamics and thermal profiling remain scarce across Midwest US dairy packaging operations.
- Legacy line integration:Retrofitting 1990s-era filling valves for precise 85-92°C temperature windows requires custom actuator replacement programs that disrupt 72-hour production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Fill Packaging Market |
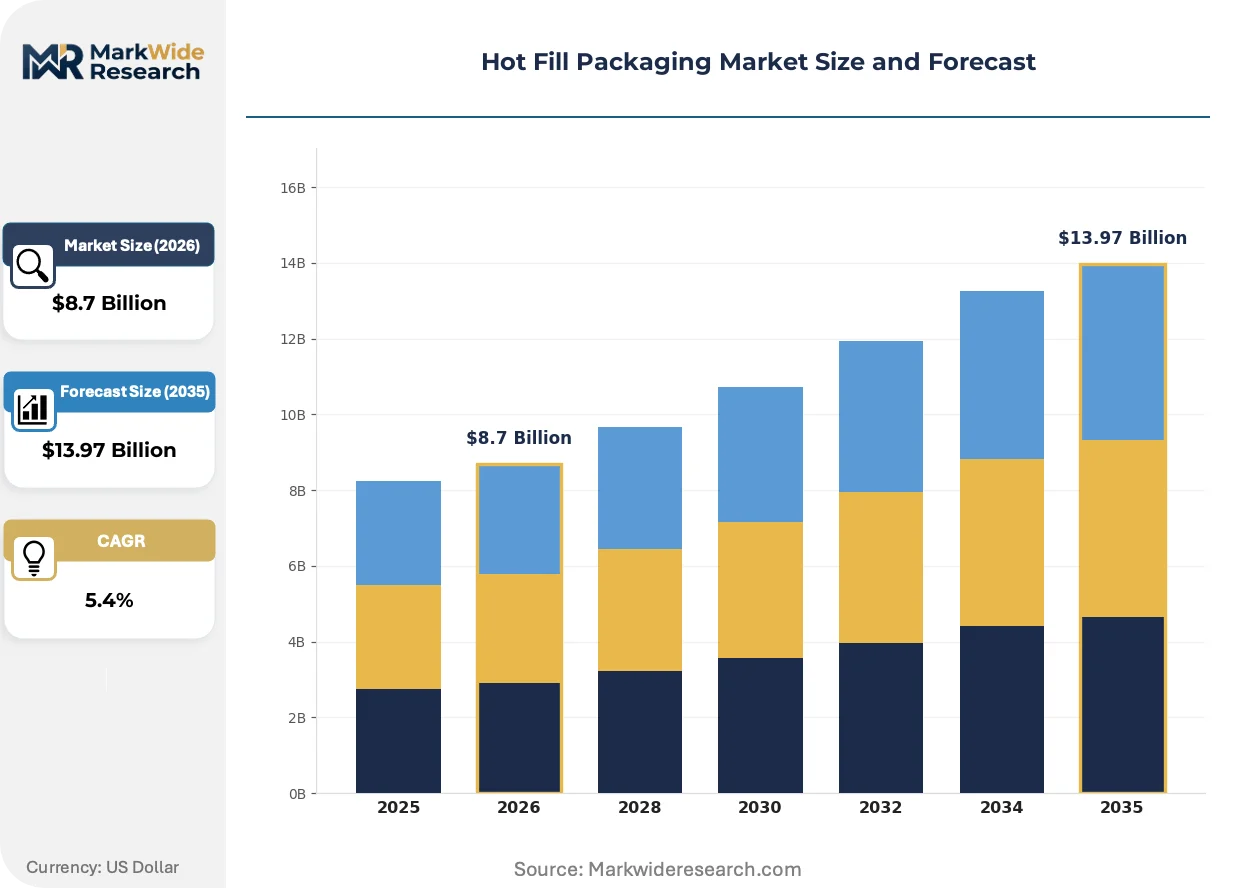
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Pouches, Cans Material: Plastic, Glass, Aluminum, Composite End User: Food & Beverages, Pharmaceuticals, Personal Care, Household Products Packaging Type: Flexible Packaging, Rigid Packaging, Stand-Up Pouches, Vacuum Sealed |
| Companies Covered | Graham Packaging Company, ALPLA Werke Alwin Lehner GmbH and Co KG, Amcor plc, RESILUX NV, Plastipak Packaging Inc, Berry Global Inc, Sonoco Products Company, Ardagh Group SA, Silgan Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Fill Packaging Market Strategic Shifts
Material science breakthroughs and regulatory tightening are converging to redefine barrier performance standards and production economics across hot fill packaging platforms.
Multilayer co-injection technology is migrating from high-barrier aseptic applications toward mid-tier juice and dairy segments. Regional bottlers in Spain and Portugal are piloting five-layer structures with EVOH cores at 15% cost premiums to monolayer heat-set PET. This migration from monolayer to multilayer is compressing the shelf-life gap between premium aseptic and standard hot fill formats.
REACH compliance deadlines for per- and polyfluoroalkyl substances are accelerating substitution of fluorinated barrier coatings with silicon oxide plasma treatments. German converters near Cologne report 30% longer qualification cycles for new coating chemistries under EFSA food contact protocols. The regulatory pressure falls heaviest on small-to-mid converters lacking in-house migration testing laboratories.
Buyers are consolidating procurement of hot fill bottles with aseptic line services under single-source contracts. North American dairy cooperatives now bundle preform supply, blow-molding, and third-party logistics under five-year agreements. This bundling is most advanced in California's Central Valley, where processor concentration enables volume guarantees that justify dedicated production lines.
Hot Fill Packaging Market Segmentation
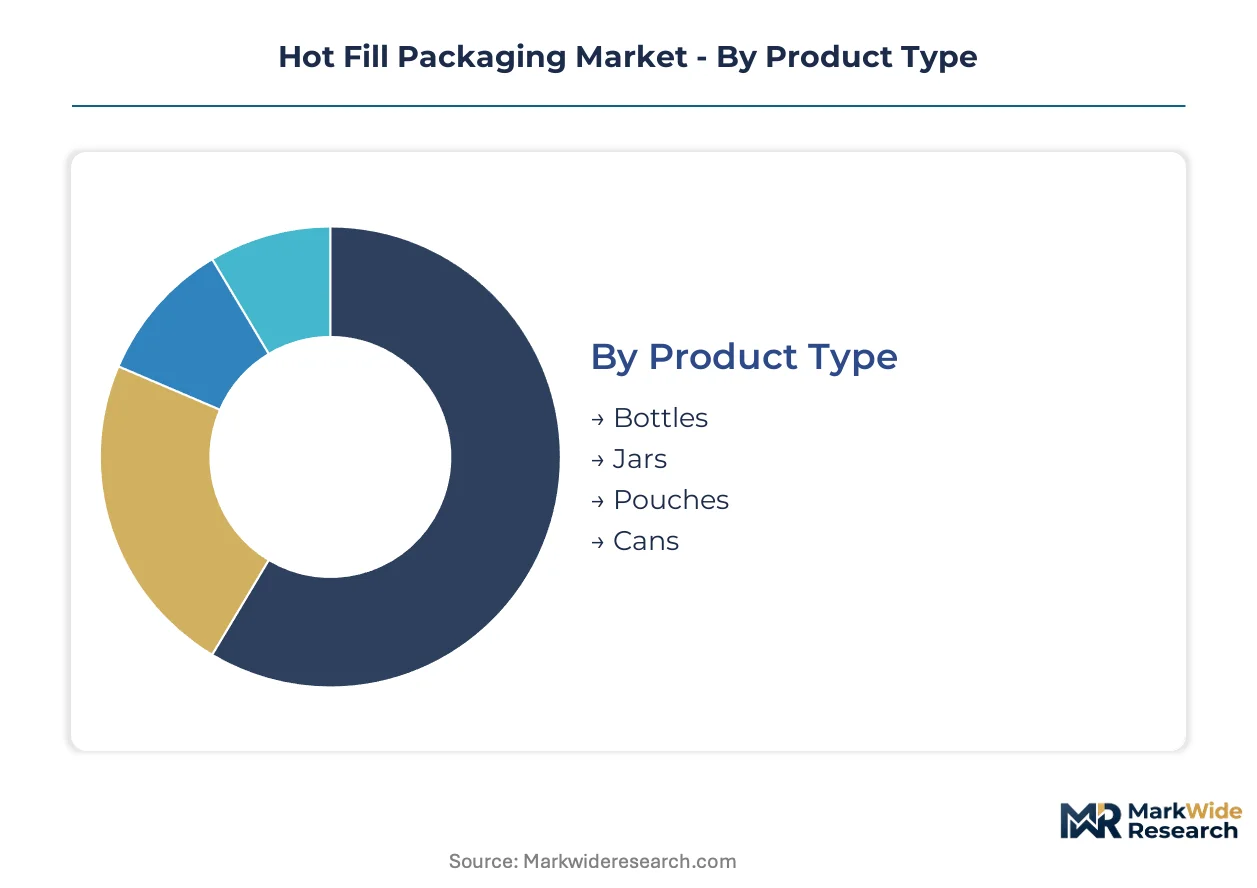
Hot fill packaging procurement cycles vary dramatically by container rigidity and thermal tolerance requirements. Brand owners sequence investments across segments based on line retrofit complexity and shelf-life extension targets.
Product Type:
Cycle times stretch from 18 months for standard bottles to 36 months for specialized pouch tooling, reshaping how converters allocate blow-molding capacity.
- Bottles:Heat-set PET construction with crystallinity-enhanced sidewalls withstands filling temperatures up to 96°C without dimensional distortion. Demand clusters around German food processing corridors where dairy and juice processors pursue lightweighting advantages over glass. EFSA migration limits on recycled content are compressing margin on rPET-heavy formulations.
- Pouches:Multilayer co-extruded structures with aluminum oxide barrier coatings enable hot fill compatibility in flexible formats. South Korean functional beverage startups are piloting stand-up configurations for protein-fortified soups, bypassing rigid bottle capital requirements. REACH compliance timelines for novel coating chemistries extend qualification to 24 months.
- Jars:Wide-mouth glass and heat-resistant polypropylene variants serve ready-to-drink soups and meal solutions. Organic brands in France retain preference for inert glass contact surfaces.
- Cans:Aluminum two-piece construction with internal epoxy liners accommodates acidic beverages at reduced thermal stress versus PET. Japanese tea processors favor cans for vending machine compatibility.
Bottles anchor the volume base while pouches gain share at the steepest rate.
Material:
Cost tiers separate commodity resins from engineered barrier systems, with qualification expense creating defensible margin bands.
- Plastic:Heat-set PET dominates through blow-molding infrastructure compatibility and lightweighting economics. German converters near Cologne are investing in food-grade rPET flake purification to meet EU recycled content mandates. EFSA additive migration limits constrain scavenger incorporation.
- Glass:Borosilicate and soda-lime formulations provide inert contact surfaces for premium organic SKUs. Italian prosecco and specialty juice bottlers retain glass for retail price points above €4.50.
- Aluminum:Two-piece drawn-and-ironed construction suits acidic beverages with moderate thermal loads. Japanese and Southeast Asian tea brands leverage existing canning infrastructure.
- Composite:Multilayer cartons with polyethylene and aluminum lamination bridge rigid and flexible formats. Spanish dairy processors pilot composite hot fill for drinkable yogurt.
Plastic captures the broadest volume while composite materials expand most quickly in dairy retrofit applications.
End User:
Application requirements dictate barrier sophistication, with pharmaceutical and food safety standards diverging sharply on migration limits.
- Food & Beverages:Acidic juices, ready-to-drink teas, and shelf-stable soups constitute the core demand base. FDA 21 CFR Part 113 governs low-acid processes in the United States, while EU regulations enforce stricter recycled content thresholds.
- Pharmaceuticals:Oral liquid formulations and nutritional supplements require validated sterility assurance. Migration testing protocols extend qualification cycles beyond standard food applications.
- Personal Care:Hot fill-compatible polymers serve hair masks and thermal-activated treatments. Korean beauty brands drive format experimentation.
- Household Products:Cleaning concentrates and automotive fluids utilize hot fill for chemical stability. Lower regulatory burden permits faster material substitution.
Food and beverages anchor the volume base while pharmaceuticals command the steepest pricing tier.
Packaging Type:
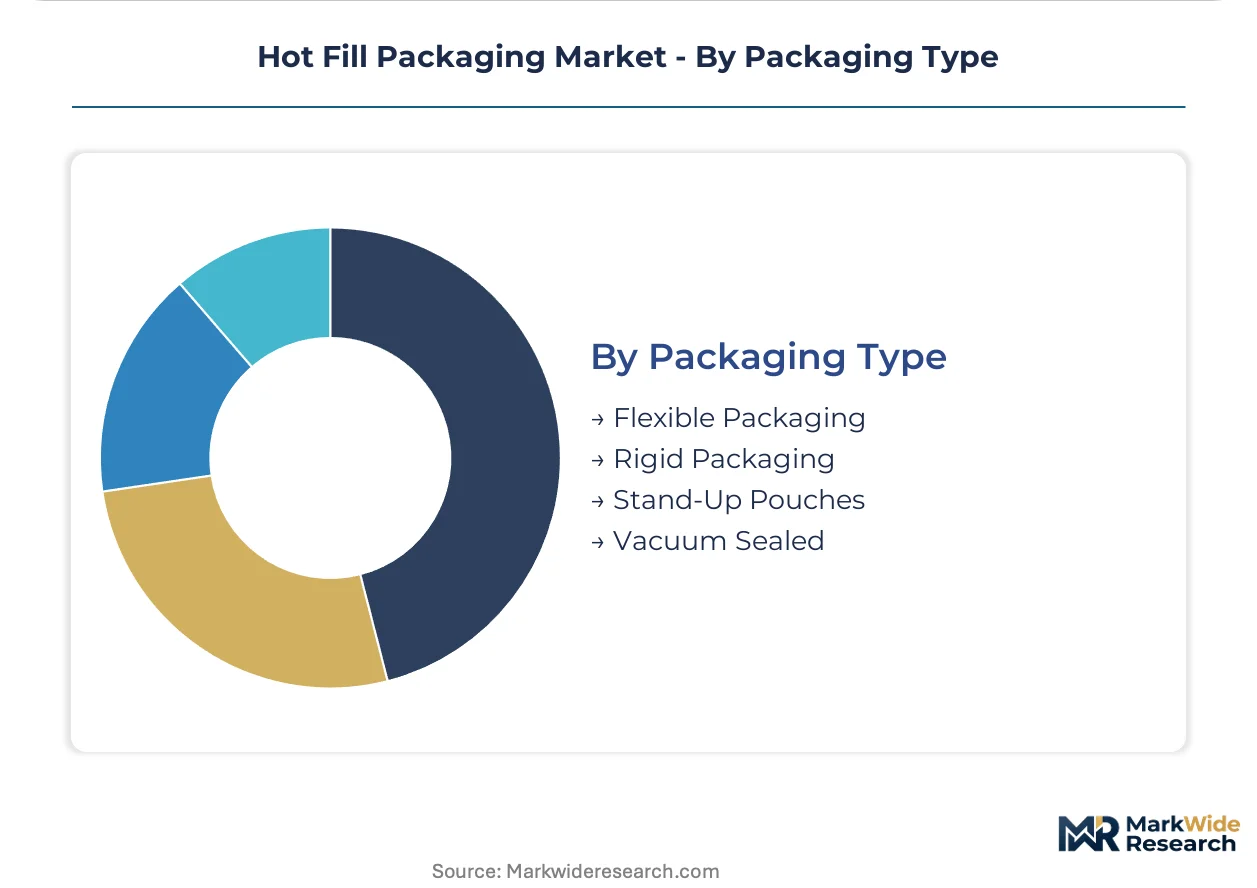
Customer type separates brand owners seeking format differentiation from private-label operators prioritizing line flexibility.
- Rigid Packaging:Bottles and jars constitute the installed base across dairy and juice processing infrastructure. Wisconsin and New York retrofit projects target this segment for aseptic-to-hot fill conversion.
- Flexible Packaging:Rollstock and formed pouches enable lightweight distribution economics. Stand-up configurations are gaining traction in functional beverage segments.
- Stand-Up Pouches:Gusseted bottom structures with spout fitments combine portability with hot fill compatibility. Korean and Japanese startups lead format adoption.
- Vacuum Sealed:Modified atmosphere integration extends shelf life for premium meal solutions. German and Austrian organic food processors favor this configuration.
Rigid packaging anchors the volume base while stand-up pouches gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers at multinational beverage brands concentrate purchasing authority in corridors with integrated preform supply and regulatory clarity. This geographic clustering shapes converter investment patterns and qualification timelines.
United States
Dairy cooperatives in Wisconsin and New York are retrofitting legacy aseptic lines for hot fill protocols at reduced capital outlay. FDA 21 CFR Part 113 governs low-acid food processes, requiring validated thermal treatment records. California's Central Valley anchors contract manufacturing bundling where processors secure five-year agreements combining preform supply with third-party logistics.
Germany
Food-grade rPET flake purification capacity is expanding near Cologne and Düsseldorf bottling corridors to meet EU Packaging and Packaging Waste Regulation thresholds. EFSA migration limits on food contact materials constrain scavenger incorporation timelines. Bavarian dairy clusters drive bulk procurement of heat-set PET bottles for shelf-stable drinkable yogurt.
China
Domestic blow-molding equipment installation accelerates under food processing modernization programs targeting import substitution. SAMR food contact material standards govern additive approval timelines. Yangtze River Delta beverage processors are qualifying multilayer structures for ready-to-drink tea expansion into tropical distribution networks.
Japan
Tea processors favor aluminum can formats for vending machine compatibility, though PET hot fill adoption is penetrating premium juice segments. METI circular economy guidelines pressure converters toward recycled content integration. Osaka-Kobe industrial corridors host specialized coating qualification laboratories serving barrier film developers.
India
The Production Linked Incentive scheme subsidizes domestic food processing equipment installation, reducing import dependence for PET bottle supply chains. FSSAI packaging regulations enforce specific migration limits for acidic beverage contact. Maharashtra and Gujarat food processing clusters are piloting hot fill-compatible stand-up pouches for functional beverage startups.
Hot Fill Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service models. The vendor base organizes around captive blow-molding capacity, integrated preform production, and multi-layer barrier technology licensing. Three archetypes dominate: integrated resin-to-bottle converters, asset-light contract manufacturers, and specialty barrier coating developers. Competitive moves concentrate on backward integration into preform supply and five-year procurement bundling with logistics providers.
Among North American fabricators, Graham Packaging Company and Plastipak Packaging Inc occupy positions within the integrated converter tier. European supply chains anchor through ALPLA Werke Alwin Lehner GmbH and Co KG, representing the captive preform production archetype. Amcor plc exemplifies multi-layer barrier specialization for shelf-life extension applications.
| Leading Market Players |
|---|
| Graham Packaging Company |
| ALPLA Werke Alwin Lehner GmbH and Co KG |
| Amcor plc |
| RESILUX NV |
| Plastipak Packaging Inc |
| Berry Global Inc |
| Sonoco Products Company |
| Ardagh Group SA |
| Silgan Holdings Inc |
| Others |
Value Chain & Pricing Dynamics
Preform production concentration in southern Germany and northern Italy feeds directly into margin capture by integrated converters serving dairy and juice processors across European bottling corridors. Buyers without captive blow-molding capacity face persistent cost disadvantages as resin qualification cycles and EFSA migration testing extend procurement timelines.
Pricing Analysis
Certification level under EFSA food contact protocols creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects rPET content ratios and barrier sophistication. Cost compression in mid-tier heat-set PET bottles is intensifying because EU recycled content mandates force rapid material requalification. Private-label operators exhibit highest price sensitivity, while organic beverage brands tolerate premiums for glass substitution.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Graham Packaging Company and Plastipak Packaging Inc in North America, ALPLA Werke Alwin Lehner GmbH and Co KG in Europe. Raw material flows draw from virgin PET resin suppliers, food-grade rPET flake purifiers, and EVOH barrier film producers. Single-source vulnerability runs through narrow preform supply bases clustered in German and Italian manufacturing zones. Distribution runs through dairy cooperative bundling agreements and five-year procurement contracts with third-party logistics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical talent scarcity in crystallinity control and thermal profiling constrains capacity expansion timelines, creating defensible positions for converters with established engineering benches. The gap between qualified blow-molding technicians and retrofit project demand widens across Midwest dairy corridors.
For Market Incumbents: Build regulatory certification moats by accelerating EFSA food contact material approvals ahead of REACH compliance deadlines. Invest in captive rPET flake purification capacity near Cologne and Düsseldorf bottling clusters to defend margin position against integrated resin-to-bottle competitors. Threat substitution from aseptic-hot fill hybrid technologies demands barrier coating R&D prioritization. For New Entrants and Emerging Players: Pursue stand-up pouch format penetration in South Korean and Indian functional beverage segments where rigid bottle tooling costs exclude established competitors. Target white-space in protein-fortified soup packaging and thermal-activated personal care treatments. Go-to-market leverage rests on asset-light contract manufacturing partnerships bypassing greenfield blow-molding capex. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding five-year dairy cooperative bundling agreements. Long-term viability frames around converters with demonstrated EFSA migration testing capabilities and integrated preform supply. Monitor PLI scheme utilization rates in Maharashtra and Gujarat as inflection signal for Indian domestic capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Flake Purification Capacity Expansion | EU Packaging and Packaging Waste Regulation compliance secures supply for German dairy processors. |
| Multilayer Barrier Technology Licensing | Five-layer EVOH structures bridge shelf-life gaps between premium aseptic and standard hot fill formats. |
| Asset-Light Contract Manufacturing Partnership | Third-party line leasing reduces capital barriers for Southeast Asian ready-to-drink tea entrants. |
| Legacy Aseptic Line Retrofit Program | Wisconsin and New York dairy infrastructure conversions unlock shelf-stable yogurt capacity at reduced capex. |
| Silicon Oxide Plasma Treatment Substitution | REACH-compliant fluorinated coating replacements address EFSA qualification timeline compression. |
Study Parameters
Desk research of regulatory filings, trade customs data, and food processing equipment installation records preceded structured interviews with blow-molding plant managers, dairy procurement leads, barrier coating R&D directors, and third-party logistics coordinators. Primary fieldwork with German and North American converters validated secondary estimates of crystallinity control technician availability. Bottom-up capacity modeling triangulated against top-down demand projections from beverage brand expansion announcements.
Assumptions held fixed include EU Packaging and Packaging Waste Regulation enforcement timelines and FDA 21 CFR Part 113 thermal treatment standards, while resin price volatility and rPET flake supply elasticity were varied across sensitivity scenarios. Segmentation dimensions spanned container rigidity, material grade tier, end-use application, and regional bottling corridor concentration. CAGRs derived from installed base expansion rates and line retrofit project pipelines, with specific inputs including PLI scheme uptake in India and SAMR food contact approval timelines in China.
Macroeconomic conditions sit as an overlay; deviation in resin commodity prices, currency exchange rates affecting German import equipment costs, or abrupt regulatory reinterpretation by EFSA would shift the trajectory. Quarterly review of rPET purification capacity utilization, EFSA migration testing queue lengths, and dairy cooperative bundling contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Global Dispensing Systems Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Loading Spout Market