
 Dispensing Booth Market | 2026-2036
Dispensing Booth Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Booth Market Insights
Buyer concentration in pharmaceutical contract manufacturing is pivoting toward large CDMOs operating multi-site networks across India and Eastern Europe. STERICOX leverages its installed base in South Asian pharmaceutical hubs to sustain recurring filter and validation service contracts. Esco Lifesciences anchors its position through biosafety cabinet cross-selling into dispensing booth specifications at research institutions. BIOBASE competes aggressively on lead times for standard HEPA configurations in mid-tier quality control labs.
A dispensing booth is a ventilated enclosure engineered to ISO 14644-1 cleanroom standards, typically achieving ISO Class 5 to 7 through HEPA-filtered laminar airflow at 0.3 to 0.5 m/s face velocity, designed to protect both the operator and the material from cross-contamination during weighing, subdivision, or transfer of powders and liquids. Pharmaceutical dispensing booths dominate current procurement volumes, reflecting GMP mandates for containment of potent compounds and cytotoxic materials. HEPA filtration technology leads technology segment bookings, while negative-pressure configurations represent the fastest-growing specification as facilities retrofit for OSHA and REACH-aligned operator exposure limits. Electronic component booths occupy a mature niche with stable replacement cycles tied to semiconductor cleanroom expansion in South Korea and Taiwan.
FDA's guidance on containment strategies for potent compounds, EMA's GMP Annex 1 revisions on barrier technology, and India's CDSCO alignment with PIC/S standards collectively elevate certification requirements for booth suppliers entering regulated pharmaceutical supply chains. OSHA permissible exposure limits and REACH substance restrictions on active pharmaceutical ingredients force engineering upgrades to sealed glove-port configurations and automated weighing integrations. Stakeholders must monitor regulatory divergence between FDA's risk-based containment approach and EMA's prescriptive barrier classifications when configuring product portfolios for multi-territory pharmaceutical clients.
Market Dynamics
HEPA filtration upgrades and negative-pressure system mandates are compressing procurement cycles as pharmaceutical facilities in India and Southeast Asia race to meet FDA and EMA audit timelines for sterile powder containment.
Growth Catalysts
- EMA GMP Annex 1 revisions:The updated barrier technology requirements are forcing CDMOs across Eastern Europe to replace legacy open-front weighing stations with certified dispensing enclosures, creating immediate replacement demand.
- Hyderabad pharmaceutical cluster expansion:Active investments by contract manufacturers in this Indian hub are generating concentrated orders for ISO 14644-1 compliant containment solutions for API handling operations.
- OSHA permissible exposure limit tightening:Stricter operator exposure thresholds for potent compounds are accelerating facility retrofits toward sealed glove-port configurations and automated weighing integrations.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input price swings for 316L-grade enclosure materials and certified filtration media are compressing margins for mid-tier equipment fabricators.
- Validation service provider concentration:A narrow base of accredited third-party certifiers in South Asia is extending commissioning timelines and creating bottlenecks for new installations.
- REACH substance restriction complexity:Evolving chemical bans on specific active pharmaceutical ingredients are forcing engineering redesigns and delaying product certifications for multi-territory suppliers.
Strategic Opportunities
- CDSCO-PIC/S alignment in India:The national regulator's harmonization with international standards is opening audit-ready procurement pathways for certified booth suppliers serving export-oriented pharmaceutical manufacturers.
- Cell and gene therapy manufacturing:Emerging biologics facilities require specialized containment for viral vector handling, creating premium specification demand beyond traditional small-molecule applications.
- Remote validation and digital commissioning:Virtual FAT/SAT protocols are reducing deployment friction and enabling faster geographic expansion for equipment vendors without local service infrastructure.
Industry Challenges
- Cleanroom containment engineering talent scarcity:Shortages of specialists fluent in both ISO 14644-1 airflow modeling and FDA cGMP documentation are extending project timelines and inflating implementation costs.
- Legacy facility retrofit complexity:Integrating negative-pressure dispensing booths into existing HVAC infrastructure without disrupting adjacent classified spaces demands costly ductwork reconfiguration and extended shutdowns.
- Multi-territory certification divergence:Reconciling FDA's risk-based containment approach with EMA's prescriptive barrier classifications requires duplicate testing protocols and fragmented product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Booth Market |
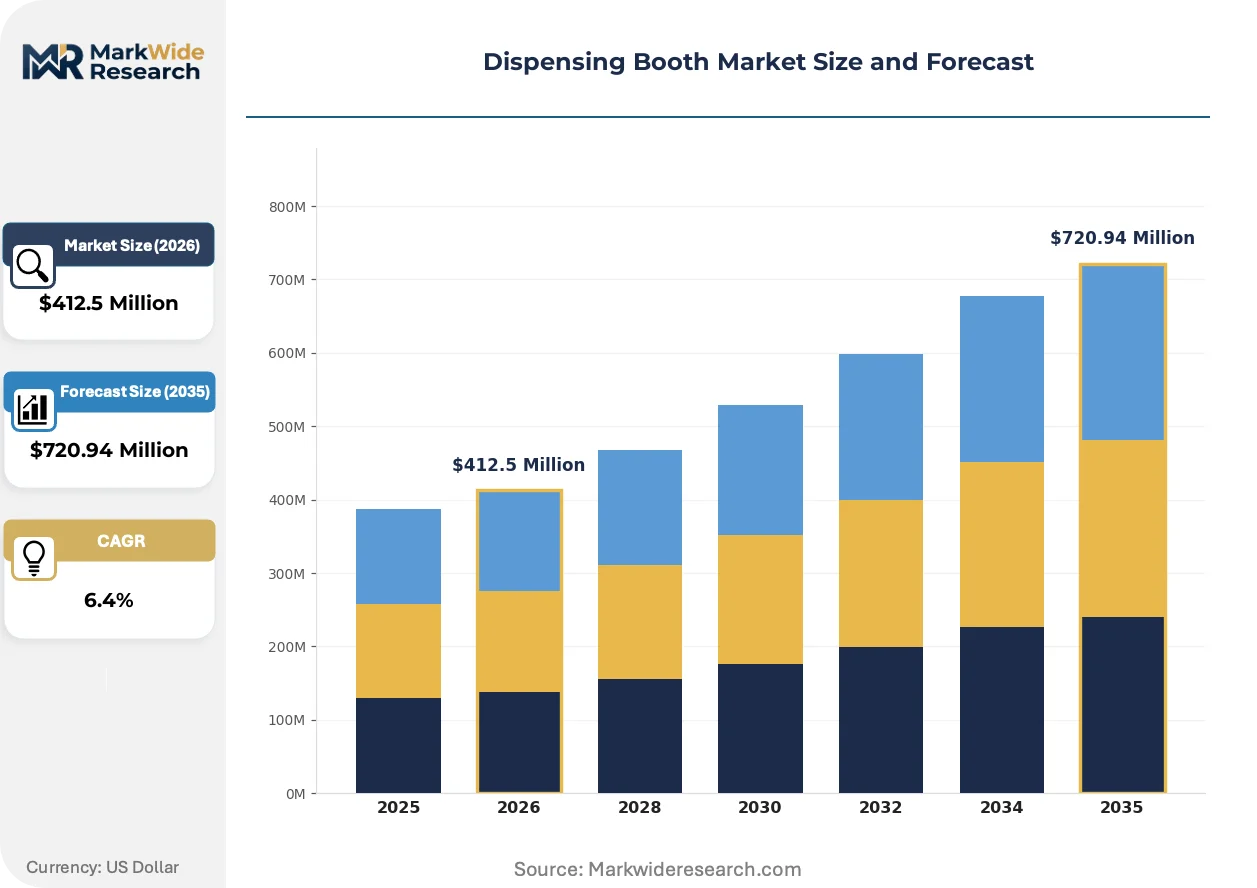
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Dispensing Booth, Pharmaceutical Dispensing Booth, Food Processing Booth, Electronic Component Booth, Cosmetic Material Booth, Industrial Material Booth Technology: Air Curtain System, HEPA Filtration, UV Sterilization, Laminar Flow, Negative Pressure, Exhaust Ventilation Application: Pharmaceutical Manufacturing, Food & Beverage Production, Electronics Assembly, Chemical Processing, Cosmetics Manufacturing, Laboratory Operations End User: Contract Manufacturers, Quality Control Labs, Research Institutions, Packaging Companies, Material Handlers, Processing Units |
| Companies Covered | STERICOX, BIOBASE, Patel Scientific Instrument, Star, Esco Lifesciences, Airtech, Clean Air Products, Hamard, Terasaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Booth Market Trends and Innovations
Active airflow control technologies and sealed containment architectures are displacing conventional open-front designs as regulatory exposure limits tighten and pharmaceutical manufacturing scales toward high-potency compounds.
Real-time particle monitoring and automated pressure differential control systems are electrifying the competitive landscape for premium dispensing enclosures. Large CDMOs operating multi-site networks are specifying these sensor-integrated configurations to reduce manual intervention and generate continuous compliance documentation. The technology is electrifying vendor differentiation as equipment suppliers compete on data integration capabilities rather than base enclosure specifications alone.
India's CDSCO alignment with PIC/S standards is elevating certification requirements for booth suppliers entering regulated pharmaceutical supply chains. The harmonization mandates ISO 14644-1 compliance documentation and third-party validation protocols that previously applied only to export markets. Domestic manufacturers serving both local and international clients are responding by consolidating procurement around pre-certified equipment platforms to reduce duplicate testing burdens.
Buyer concentration among large CDMOs is compressing vendor selection cycles and unbundling after-sales service contracts from equipment purchases. Multi-site operators are standardizing on single-source containment platforms to simplify spare parts logistics and reduce technician training overhead. This consolidation is most visible in India's pharmaceutical clusters around Hyderabad and Ahmedabad, where contract manufacturers prioritize suppliers with established filter replacement and recertification service networks.
Dispensing Booth Market Segmentation
Segmentation in dispensing booth procurement reflects divergent containment requirements across potency classes, regulatory jurisdictions, and facility retrofit constraints. Buyers prioritize ISO 14644-1 compliance tiers, HEPA filtration specifications, and validation documentation depth when matching equipment categories to operational risk profiles.
Product Type:
Cost tier differentiation separates premium-certified pharmaceutical enclosures from standard industrial configurations with basic exhaust ventilation.
- Pharmaceutical Dispensing Booth:Engineered to ISO Class 5-7 with HEPA-filtered laminar airflow at 0.3-0.5 m/s face velocity, sealed glove-port architectures, and automated pressure differential monitoring. Demand concentrates in India's Hyderabad and Ahmedabad CDMO clusters where FDA and EMA audit readiness mandates negative-pressure containment for potent compound handling.
- Chemical Dispensing Booth:Configured for corrosive vapor containment with chemical-resistant 316L stainless steel construction and dedicated exhaust ventilation systems. Procurement accelerates in German and Swiss specialty chemical manufacturing where REACH substance restrictions enforce sealed transfer operations for restricted active ingredients.
- Electronic Component Booth:Mature specification achieving ISO Class 5 through vertical laminar flow for semiconductor wafer handling. Replacement cycles tie to cleanroom expansion in South Korea and Taiwan foundries.
- Food Processing Booth:Moderate containment for allergen segregation and pathogen control during ingredient weighing. USDA and FDA food safety mandates drive adoption in US dairy and bakery ingredient handling facilities.
- Cosmetic Material Booth:Powder containment for pigment and fragrance handling with basic HEPA filtration. Demand tracks EU Cosmetics Regulation compliance requirements for manufacturing facilities in France and Italy.
- Industrial Material Booth:Standard ventilation enclosures for non-potent bulk powder transfer. Price-sensitive procurement dominates mid-tier manufacturing in Eastern European metalworking and coatings sectors.
Pharmaceutical dispensing booths lead volumes today; chemical dispensing configurations are gaining share fastest as REACH substance restrictions expand.
Technology:
Application severity determines technology selection — potent compound handling demands redundant containment layers while standard operations prioritize capital efficiency.
- HEPA Filtration:Core technology deploying H13-H14 grade filters with 99.995% efficiency at 0.3 micron particles, integrated into ceiling plenum arrays with sealed gel-seal mounting frames. Dominates pharmaceutical manufacturing specifications across India, Germany, and Switzerland where EMA GMP Annex 1 mandates validated filtration performance documentation.
- Negative Pressure:Differential pressure control maintaining 10-15 Pa below ambient through variable frequency drive blower modulation, coupled with sealed transfer hatches and glove ports. Fastest-expanding specification as OSHA permissible exposure limits tighten for high-potency API handling in US and European facilities.
- Laminar Flow:Unidirectional airflow delivery through perforated diffuser plates with velocity uniformity testing per ISO 14644-3. Standard for electronics assembly and non-potent pharmaceutical operations.
- Air Curtain System:High-velocity air barrier at access openings without physical enclosure. Limited adoption in food processing where temporary containment suffices.
- UV Sterilization:Supplementary 254 nm germicidal irradiation for surface decontamination between operations. Secondary specification in laboratory and cell therapy applications.
- Exhaust Ventilation:Basic dilution ventilation without filtration for non-hazardous industrial powders. Lowest-cost configuration with minimal regulatory documentation requirements.
HEPA filtration anchors current procurement volumes; negative pressure systems are climbing the fastest as containment regulations intensify.
Application:
Customer type fragmentation separates large CDMO network standardization from isolated quality control laboratory procurement.
- Pharmaceutical Manufacturing:High-potency API weighing, subdivision, and transfer operations requiring validated containment per FDA guidance on potent compounds. Concentrated demand from multi-site CDMOs in India and Eastern Europe retrofitting for EMA GMP Annex 1 compliance.
- Laboratory Operations:Research-scale containment for analytical method development and preclinical material preparation. Specifications emphasize flexibility over maximum containment depth.
- Food & Beverage Production:Allergen segregation and pathogen control during ingredient dispensing. USDA FSIS inspection protocols drive validation documentation requirements in US facilities.
- Electronics Assembly:Semiconductor and display manufacturing cleanroom integration. Specifications prioritize particle control over biological containment.
- Chemical Processing:Specialty and fine chemical handling with corrosion-resistant construction. REACH compliance documentation shapes European procurement criteria.
- Cosmetics Manufacturing:Pigment and fragrance powder containment with moderate occupational exposure controls. EU Cosmetics Regulation GMP drives specification depth.
Pharmaceutical manufacturing dominates current installations; laboratory operations show steepest expansion trajectory as cell and gene therapy research scales.
End User:
Volume concentration among contract manufacturers creates procurement standardization pressure distinct from fragmented quality control laboratory purchasing.
- Contract Manufacturers:Multi-site CDMO networks standardizing on single-source containment platforms to simplify spare parts logistics and technician training. India's export-oriented pharmaceutical manufacturers in Hyderabad and Ahmedabad clusters drive concentrated order volumes for ISO 14644-1 certified configurations.
- Quality Control Labs:Analytical and release testing facilities with dispersed procurement authority and shorter replacement cycles. BIOBASE competes aggressively on lead times for standard HEPA configurations in this mid-tier segment.
- Research Institutions:Academic and government laboratories with biosafety cabinet cross-selling opportunities. Esco Lifesciences leverages existing installed base for dispensing booth specification capture.
- Packaging Companies:Secondary packaging operations with basic powder containment needs. Price-sensitive procurement with minimal validation documentation requirements.
- Material Handlers:Logistics and warehousing operations for bulk ingredient transfer. Industrial-grade specifications predominate.
- Processing Units:In-house manufacturing operations at integrated pharmaceutical companies. Captive procurement with long equipment lifecycles.
Contract manufacturers lead segment volumes today; quality control labs are expanding most quickly as distributed testing networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India outpaces Germany in dispensing booth procurement velocity, though Swiss facilities command the highest specification tiers for potent compound containment. Regulatory divergence between FDA risk-based protocols and EMA prescriptive mandates is fragmenting supplier certification requirements across major pharmaceutical manufacturing hubs.
United States
OSHA permissible exposure limit revisions for high-potency APIs are accelerating facility retrofits toward sealed glove-port configurations. FDA guidance on containment strategies for potent compounds mandates validated engineering controls for contract manufacturers serving domestic and export markets. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical belt are driving premium specification demand for cell and gene therapy manufacturing containment.
Germany
REACH substance restrictions on specific active pharmaceutical ingredients are forcing engineering redesigns for multi-territory equipment suppliers. EMA GMP Annex 1 barrier technology requirements are compelling CDMOs to replace legacy open-front weighing stations with certified dispensing enclosures. The Rhine-Main pharmaceutical cluster around Frankfurt and the Baden-Württemberg chemical corridor anchor replacement demand for corrosion-resistant chemical dispensing configurations.
Switzerland
Swissmedic alignment with EMA standards elevates certification documentation requirements for containment equipment entering regulated supply chains. The country's specialty chemical and biologics manufacturing base demands redundant HEPA filtration and negative-pressure architectures for cytotoxic material handling. Basel's pharmaceutical hub and the greater Zurich life sciences corridor concentrate procurement for premium-tier containment platforms with automated pressure differential monitoring.
India
CDSCO harmonization with PIC/S standards is opening audit-ready procurement pathways for certified booth suppliers serving export-oriented manufacturers. The Hyderabad pharmaceutical cluster generates concentrated orders for ISO 14644-1 compliant containment solutions as contract manufacturers expand API handling capacity. Ahmedabad's CDMO investments and Bangalore's emerging biologics facilities are redirecting procurement budgets toward validated negative-pressure systems for sterile powder operations.
China
NMPA alignment with international GMP standards is elevating documentation requirements for containment equipment in domestic pharmaceutical manufacturing. The Yangtze River Delta pharmaceutical corridor around Shanghai and the Beijing-Tianjin-Hebei biotech cluster are driving demand for HEPA-filtered dispensing enclosures in contract manufacturing facilities. Stricter occupational exposure regulations in Jiangsu and Zhejiang provinces are accelerating retrofits toward sealed containment architectures for potent compound weighing.
Dispensing Booth Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market segments, with equipment fabricators fragmenting by certification depth and service network reach. The vendor base clusters around three strategic archetypes: integrated cleanroom solution providers leveraging cross-selling opportunities, regional fabricators competing on lead times for standard configurations, and premium-tier specialists commanding validation-intensive pharmaceutical contracts. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into automated weighing integrations.
Among Asia-Pacific headquartered fabricators, STERICOX and BIOBASE occupy distinct positioning archetypes, while Esco Lifesciences represents the integrated cleanroom solution provider model. STERICOX exemplifies the regional specialist with established service network density in South Asian pharmaceutical hubs. BIOBASE anchors the mid-tier quality control laboratory segment where lead time compression drives procurement decisions. Esco Lifesciences leverages biosafety cabinet installed bases to cross-sell into dispensing booth specifications at research institutions. The competitive dynamic between these three patterns—service network depth, speed-to-delivery, and cross-product integration—defines vendor selection criteria across end-user segments.
| Leading Market Players |
|---|
| STERICOX |
| BIOBASE |
| Patel Scientific Instrument |
| Star |
| Esco Lifesciences |
| Airtech |
| Clean Air Products |
| Hamard |
| Terasaki |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ISO 14644-1 validated pharmaceutical enclosures and basic industrial ventilation units manifests in both procurement budgets and supplier network configurations across India, Germany, and Switzerland. Premium-tier negative-pressure systems command substantial validation service bundles while commodity configurations compete on 316L stainless steel input costs and regional fabrication lead times.
Pricing Analysis
Capacity additions in India's pharmaceutical manufacturing corridors are reshaping price floors for standard HEPA configurations as domestic fabricators achieve scale economies in filter plenum assembly. Three-tier pricing structure across premium-certified, mid-tier validated, and economy industrial levels reflects divergence in documentation depth and after-sales service bundling. Cost compression in economy-tier metal fabrication is intensifying because Chinese stainless steel suppliers are redirecting excess capacity toward South Asian equipment markets. Mid-tier quality control laboratories exhibit highest price sensitivity while multi-site CDMOs prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale CDMO demand for certified dispensing enclosures while distributor networks serve fragmented laboratory procurement across Eastern Europe and Southeast Asia. Manufacturing concentration centers on India, China, and Germany for enclosure fabrication and HEPA filter media production. Supply chains draw from Taiwanese electronics for automated pressure control systems and Swiss specialty steel for corrosion-resistant chemical booth construction. Single-source vulnerability in third-party validation services across South Asia creates commissioning bottlenecks that extend delivery timelines. Distribution runs through authorized service partners with ISO 14644-1 commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier negative-pressure configurations where validation service bundling and recurring filter replacement contracts offset stainless steel input volatility. Cost-down trajectories in Indian fabrication capacity support mid-tier market penetration without sacrificing certification integrity.
For Market Incumbents: Hedge against margin erosion in standard HEPA configurations by deepening backward integration into filter media production and capturing adjacent automated weighing system integrations. Threat from Chinese equipment fabricators with state-subsidized steel access demands defensive certification investment in FDA and EMA dual-territory validation capabilities. Capacity addition in Ahmedabad and Hyderabad clusters represents the priority lever for service network densification. For New Entrants and Emerging Players: Capture white-space demand in cell and gene therapy manufacturing containment where viral vector handling specifications exceed traditional small-molecule requirements. Laboratory operations in Eastern Europe show lowest incumbent saturation and shortest procurement cycles among regulated segments. Go-to-market angle should emphasize remote validation protocols that bypass South Asia's third-party certifier bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where validation service provider scarcity constrains equipment vendor expansion timelines. Long-term viability favors platform players with integrated filter replacement and recertification networks over pure-play fabricators. Acquisition target archetype: regional specialists with established CDMO relationships in India's export-oriented pharmaceutical clusters. Signal to watch: CDSCO enforcement actions that accelerate PIC/S alignment timelines and compress procurement decision windows.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Validation Protocol Development | Virtual FAT/SAT capabilities reduce deployment friction for vendors lacking local South Asian service infrastructure. |
| Automated Weighing Integration | Sealed glove-port configurations with precision dispensing meet OSHA exposure limit tightening for potent APIs. |
| Filter Media Backward Integration | In-house H13-H14 grade production insulates margin pressure from certified filtration media cost volatility. |
| Cell Therapy Containment Specialization | Viral vector handling specifications open premium pricing tiers beyond traditional pharmaceutical applications. |
| Dual-Territory Certification Investment | Simultaneous FDA risk-based and EMA prescriptive validation reduces duplicate testing burdens for multi-site CDMOs. |
Research Methodology
Multiple input streams — regulatory filing analysis, equipment procurement database tracking, and primary stakeholder interviews — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged cleanroom engineering consultants, CDMO facility managers, validation service providers, and HEPA filter procurement leads across India, Germany, Switzerland, and the United States. Secondary validation drew from FDA 483 observation databases, EMA GMP inspection reports, CDSCO compliance circulars, and ISO 14644-1 certification registries.
Historical shipment patterns were cross-referenced against expert panel assessments of retrofit cycle timing and regulatory enforcement intensity across the projection horizon. Segmentation modeling incorporated product type, technology tier, application severity, and end-user procurement authority dimensions. CAGRs were derived from facility expansion pipelines and replacement demand curves rather than extrapolated trend lines. Forecast inputs included CDMO capital expenditure disclosures and national pharmaceutical regulator harmonization timelines.
Regulatory enforcement acceleration, stainless steel commodity price shocks, and third-party validation service capacity constraints are the dominant revision risks to base case assumptions. Periodic stress-testing of base assumptions against CDSCO audit frequency and REACH substance restriction expansion trajectories is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Container Washing System Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Packer Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Coding and Marking Equipment Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Single Use Mixer Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Packaging Equipment Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Tissue Roll Unwinders Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Global Shrink Sleeve Applicator Market