
 Single Use Mixer Market | 2026-2036
Single Use Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Mixer Market Analytics
Market Context
Multi-source procurement for bioprocessing consumables is pivoting toward qualified secondary suppliers as drug makers buffer against supply shocks. Sartorius AG leverages its membrane and bag portfolio to anchor long-term mixing system contracts. Danaher sustains competitive pressure through its Life Sciences platform breadth. Thermo Fisher Scientific, Inc. dominates distribution reach across North American and European biologics clusters.
Technical Definition and Segment Structure
A single use mixer is a disposable, pre-sterilized fluid handling device that combines powders, liquids, or cell suspensions within a sealed plastic chamber, typically operating at working volumes from ten milliliters to several thousand liters and gamma-irradiated for aseptic assurance. Its primary purpose is to eliminate cleaning validation cycles and cross-batch contamination in multiproduct biopharmaceutical facilities. Magnetic stirring technology leads installed base due to gentle shear profiles for mammalian cell culture, while ultrasonic mixing represents the fastest-expanding segment as lipid nanoparticle and mRNA formulation demand intensifies. Among end users, biotechnology commands the deepest margin pools because process development labs require frequent scale-up iterations with customized mixing parameters.
Regulatory Framework and Outlook
FDA guidance on single-use system validation, EMA Annex 1 revisions on contamination control strategy, and ISO 13485 quality management standards collectively shape equipment qualification protocols and supplier audit intensity. These frameworks compel mixer vendors to maintain extractables and leachables data packages that span full product contact surfaces. Stakeholders must monitor how evolving gene therapy regulatory pathways in the United States and European Union redefine mixing performance specifications for novel vector manufacturing.
Market Dynamics
Biopharmaceutical manufacturers are replacing fixed stainless-steel infrastructure with disposable fluid handling systems to compress facility turnaround times and eliminate cross-contamination validation cycles across multiproduct campaigns.
Growth Catalysts
- EMA Annex 1 Contamination Control Mandate:The 2022 revision compels sterile drug manufacturers to document closed-system processing, accelerating single-use mixer qualification in European fill-finish operations.
- Cell Therapy Manufacturing Scale-Up:Autologous and allogeneic cell therapy producers require rapid batch changeover capabilities that only disposable mixing systems deliver at clinical and commercial scales.
- Lipid Nanoparticle Formulation Demand:mRNA vaccine and gene therapy vector production requires precision low-shear mixing for lipid encapsulation, driving ultrasonic mixer adoption in process development labs.
Market Restraints
- Resin and Film Supply Concentration:Specialized multi-layer polymer films for bioprocess containers concentrate among a limited supplier base in Germany and the United States, exposing mixer vendors to input cost volatility.
- Extractables and Leachables Validation Burden:FDA guidance on single-use system qualification demands comprehensive chemical characterization data that extends mixer vendor development timelines and raises compliance costs.
- Stainless-Steel Hybrid Retention:Large-volume commercial biologics facilities maintain stainless-steel tanks for 10,000+ liter batches, capping disposable mixer penetration at the upper volume threshold.
Strategic Opportunities
- India Biosimilar Manufacturing Expansion:CDSCO streamlined approval pathways for biosimilars are attracting contract manufacturing investment in Hyderabad and Bengaluru, creating demand for mid-scale disposable mixing systems.
- Continuous Bioprocessing Integration:Perfusion cell culture and continuous chromatography convergence requires inline mixing modules that maintain sterile boundaries between unit operations without fixed infrastructure.
- Gene Therapy Vector Production:AAV and lentiviral vector manufacturing for rare disease indications requires small-batch, high-changeover mixing capabilities that favor single-use platforms in United States and European facilities.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Single-use system qualification requires specialized expertise in extractables testing, gamma irradiation validation, and sterile connection technology that outpaces current training program output.
- Legacy Facility Retrofit Complexity:Converting existing stainless-steel infrastructure to accommodate disposable mixing systems requires HVAC modifications, utility reconfiguration, and space reallocation that extends project timelines.
- Supply Chain Reconfiguration Friction:Just-in-time sterile component logistics for gamma-irradiated mix bags demands redundant qualified suppliers and regional warehousing that strains working capital for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Mixer Market |
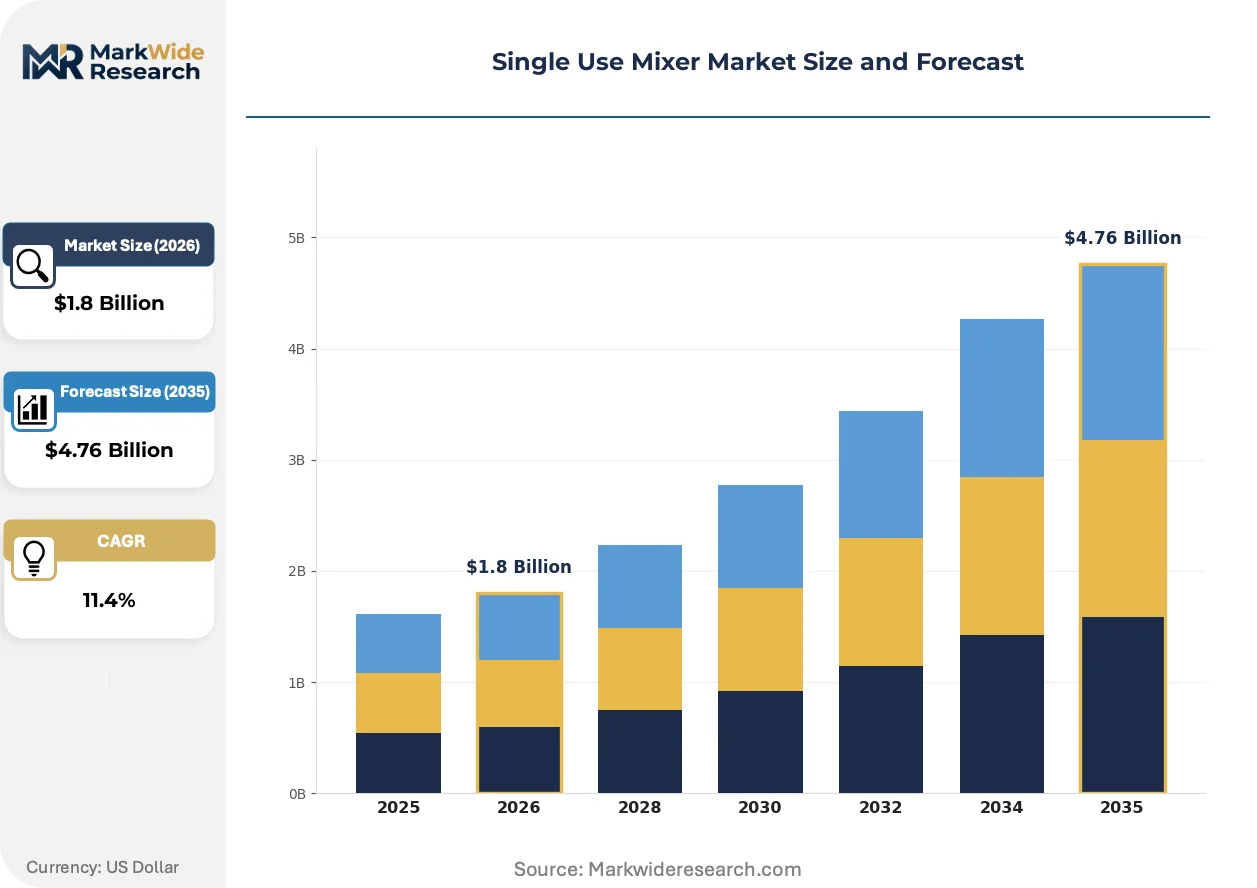
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Homogenizers, Stirring Devices, Dispersers End User: Pharmaceuticals, Biotechnology, Food & Beverage, Chemicals Application: Cell Culture, Bioprocessing, Dissolution, Emulsion Technology: Magnetic Stirring, Mechanical Agitation, Ultrasonic Mixing, Static Mixing |
| Companies Covered | Danaher, DrM Life Science, Sartorius AG, Agilitech, Avantor Inc., Thermo Fisher Scientific, Inc., Meissner Filtration Products, Inc., Kuhner AG, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Mixer Market Evolving Landscape
Disposable fluid handling technology is converging with process analytical technology and closed-system design principles to enable real-time mixing control and automated sterile boundary maintenance across biopharmaceutical manufacturing.
Ultrasonic mixing technology is consolidating position in lipid nanoparticle and mRNA formulation applications where conventional impeller systems generate excessive shear. Gene therapy CDMOs in Massachusetts and North Carolina are adopting these systems at pilot scale to reduce nucleic acid degradation. The technology is consolidating mixing precision and sterile containment into single disposable units that eliminate separate homogenization steps.
EMA Annex 1 revisions on contamination control strategy now require documented evidence of closed processing for sterile medicinal products manufactured in European Union facilities. This regulatory pressure forces mixer vendors to redesign port configurations and sealing mechanisms to demonstrate zero open interventions. Aseptic fill-finish operations in Ireland, Belgium, and Germany are responding by specifying fully closed mixing systems with welded tubing sets rather than traditional tri-clamp connections.
Biopharmaceutical procurement teams are consolidating supplier relationships to reduce audit burden and secure volume commitments for gamma-irradiated consumables. Large molecule developers in the United States are replacing transactional purchasing with multi-year supply agreements that bundle mixing bags, tubing assemblies, and sensors under single vendor accountability. This concentration is most visible among top-20 biologics manufacturers who now specify preferred supplier status as a condition of equipment qualification.
Single Use Mixer Market Segmentation
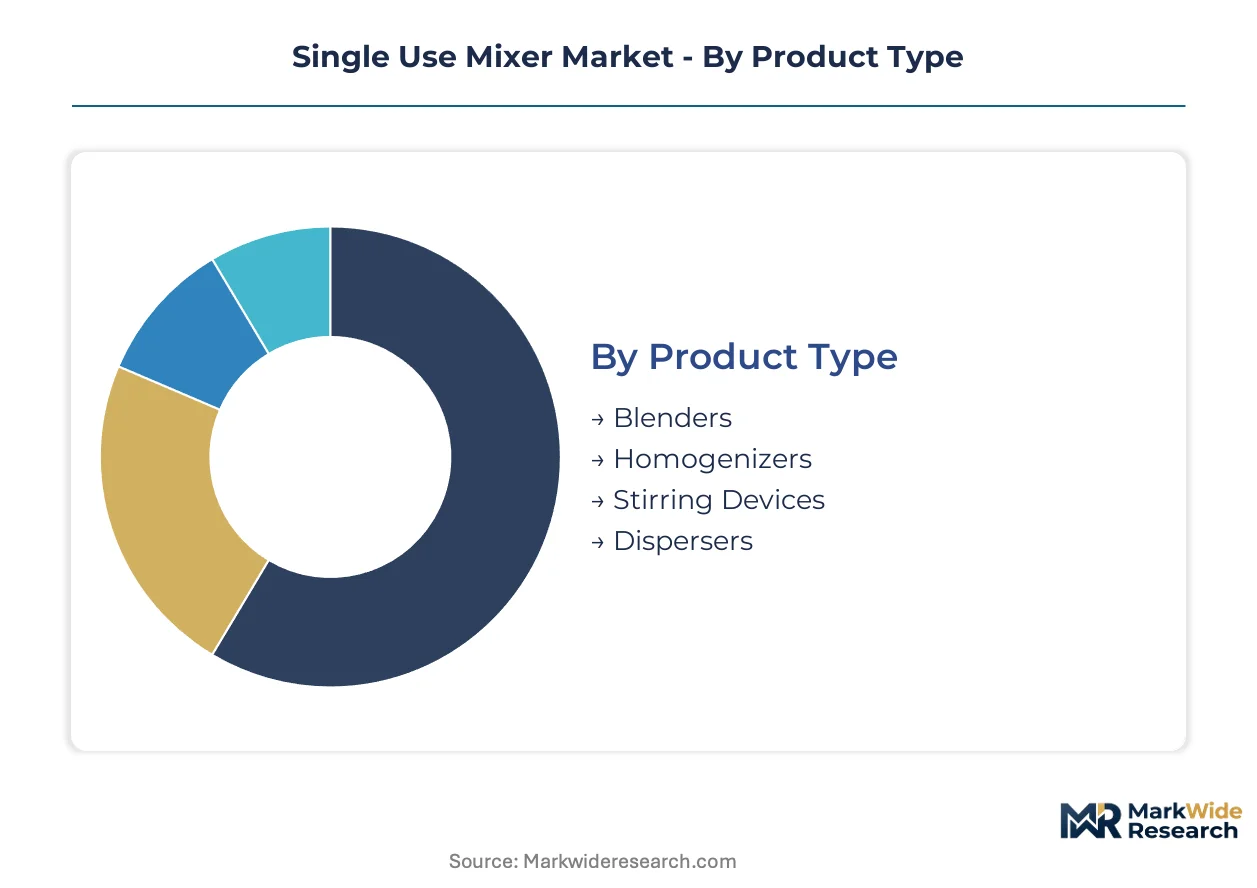
Single-use mixer procurement patterns diverge sharply across product configurations and operational contexts. Biopharmaceutical manufacturers select equipment based on shear sensitivity requirements, batch scale, and regulatory validation burden rather than upfront capital cost alone.
Product Type:
Equipment selection hinges on whether the application demands particle size reduction, uniform suspension maintenance, or rapid powder incorporation into liquid matrices.
- Blenders:Rotary blade systems process high-viscosity cell culture media and buffer preparations at working volumes up to 2,000 liters. Mammalian cell therapy facilities in Massachusetts and North Carolina specify these for gentle mixing of shear-sensitive formulations.
- Homogenizers:High-shear rotor-stator configurations achieve droplet size reduction for lipid nanoparticle encapsulation in mRNA vaccine manufacturing. The technology is gaining share fastest in process development laboratories where rapid scale-up validation is required.
- Stirring Devices:Magnetic levitation impellers dominate standard buffer and media preparation across multiproduct biologics suites.
- Dispersers:High-speed dispersing elements integrate powders into liquids for parenteral formulation applications.
Stirring devices lead volumes today; homogenizers are gaining share fastest.
End User:
Margin structures and qualification intensity vary dramatically by sector, with biotechnology commanding premium pricing for customized validation packages.
- Pharmaceuticals:Large-molecule drug manufacturers deploy disposable mixers across fill-finish operations to satisfy FDA contamination control guidance. Facilities in Ireland and Belgium specify fully closed systems with welded tubing sets to meet EMA Annex 1 requirements for sterile medicinal products.
- Biotechnology:Cell and gene therapy developers require frequent batch changeover with minimal cleaning validation. Autologous therapy producers in the United States favor small-volume magnetic stirring systems that compress campaign turnaround from weeks to days.
- Food & Beverage:Aseptic processing applications for cultured proteins and precision fermentation drive adoption of gamma-irradiated mixing systems.
- Chemicals:Specialty chemical manufacturers utilize disposable mixers for high-potency compound handling where cross-contamination risks outweigh equipment costs.
Pharmaceuticals anchor current demand; biotechnology exhibits the steepest expansion trajectory.
Application:
Process requirements determine whether gentle suspension maintenance or aggressive dissolution kinetics takes priority in equipment specification.
- Cell Culture:Low-shear magnetic stirring preserves viability in mammalian cell suspensions during media preparation and harvest mixing. Perfusion bioreactor operations in Germany and China require inline mixing modules that maintain sterile boundaries without fixed infrastructure.
- Bioprocessing:Buffer preparation and downstream processing steps demand rapid powder dissolution at scales from 50 to 1,000 liters. CDMOs in Hyderabad and Bengaluru are qualifying mid-scale systems for biosimilar manufacturing under streamlined CDSCO approval pathways.
- Dissolution:High-solids powder incorporation into aqueous vehicles for parenteral formulations.
- Emulsion:Oil-in-water and water-in-oil dispersion for sustained-release drug delivery systems.
Bioprocessing dominates installed base; cell culture applications are climbing the fastest.
Technology:
Mixing mechanism selection balances energy input precision against sterile containment requirements and validation complexity.
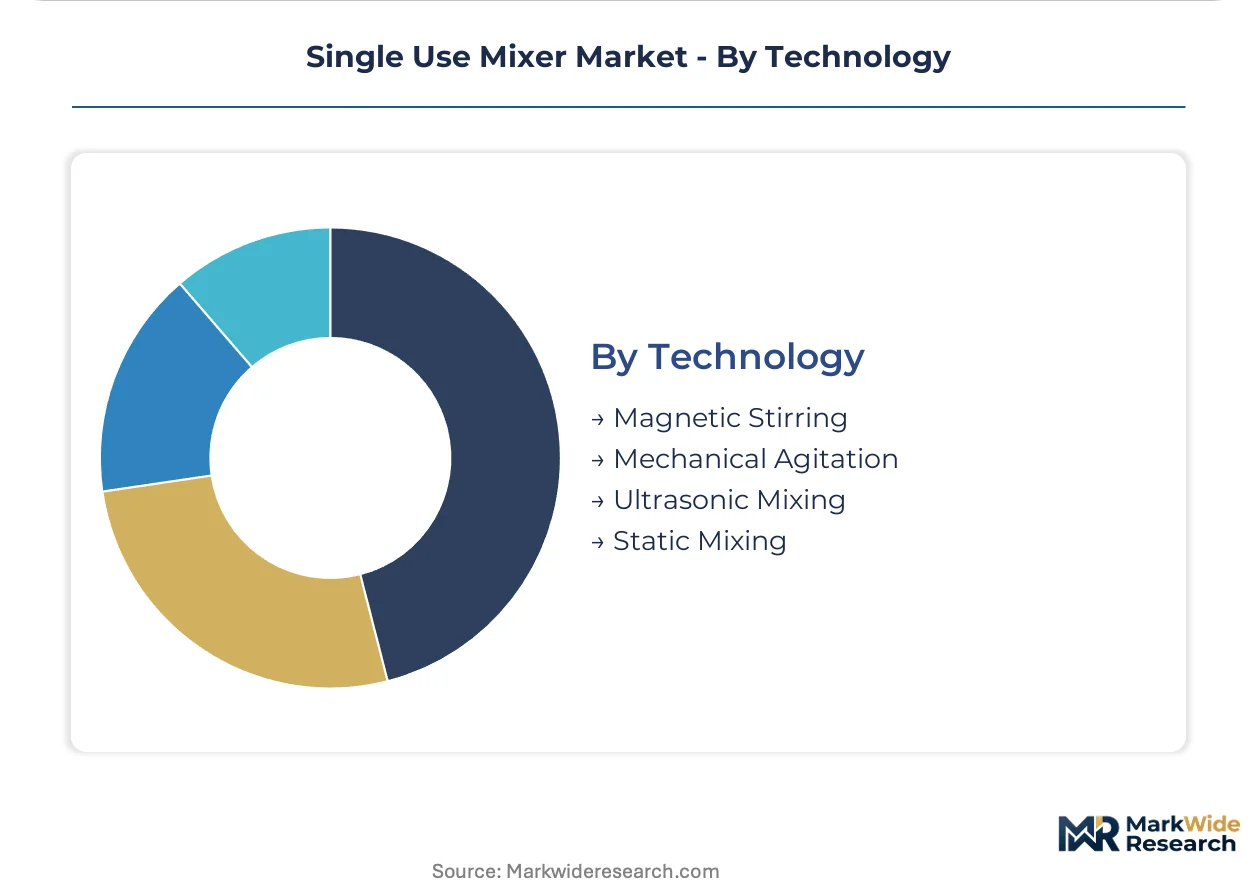
- Magnetic Stirring:Levitated impeller systems eliminate shaft seals and bearing contamination risks in aseptic operations. The technology commands the deepest installed base across mammalian cell culture applications where shear minimization protects product quality.
- Ultrasonic Mixing:Acoustic cavitation achieves nanoscale droplet distribution for lipid nanoparticle formulation without mechanical shear. mRNA vaccine manufacturers in the United States and European Union are adopting these systems to reduce nucleic acid degradation during encapsulation.
- Mechanical Agitation:Direct-drive impeller systems for high-torque applications in viscous media.
- Static Mixing:Passive in-line elements for continuous flow applications with no moving parts.
Magnetic stirring retains volume leadership; ultrasonic mixing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts biopharmaceutical clusters anchor single-use mixer procurement intensity. Cell therapy CDMOs in Cambridge and Worcester specify fully closed disposable mixing systems to compress autologous therapy turnaround times. FDA process validation guidance shapes equipment qualification protocols across United States facilities.
United States
Gene therapy vector manufacturers in North Carolina and Massachusetts drive ultrasonic mixer adoption for lipid nanoparticle encapsulation. FDA guidance on single-use system integrity compels extractables and leachables documentation for all product contact surfaces. Boston-Cambridge biotech corridors concentrate demand for small-volume magnetic stirring systems in autologous cell therapy process development.
Germany
Perfusion bioreactor operations in Bavaria and Baden-Württemberg require inline mixing modules that maintain sterile boundaries without fixed infrastructure. EMA Annex 1 contamination control mandates force fill-finish facilities in Hesse to specify welded tubing sets over traditional tri-clamp connections. Heidelberg and Munich biotech clusters lead European adoption of closed-system disposable mixing for multiproduct biologics suites.
China
Biosimilar manufacturers in Jiangsu and Zhejiang provinces scale mid-scale disposable mixing capacity under NMPA streamlined approval pathways. The country's dual carbon goals accelerate stainless-steel replacement in bioprocessing facilities to reduce cleaning validation energy consumption. Shanghai and Suzhou biopharmaceutical parks attract CDMO investment targeting domestic and export markets for monoclonal antibodies.
India
Contract manufacturers in Hyderabad and Bengaluru qualify single-use mixing systems for biosimilar production under CDSCO streamlined approval frameworks. The PLI scheme for pharmaceuticals attracts foreign bioprocessing investment to Telangana and Karnataka. Genome Valley and Biocon Park clusters concentrate demand for gamma-irradiated mixing bags in mid-scale biologics manufacturing.
Switzerland
Precision biologics manufacturers in Basel and Zurich specify high-integrity disposable mixing for high-potency compound handling. Swissmedic guidelines on contamination control strategy align with EMA Annex 1 requirements for sterile medicinal products. The country's pharmaceutical corridor maintains premium positioning through advanced aseptic processing technology adoption.
Single Use Mixer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gene therapy specialization and continuous bioprocessing integration. The vendor base stratifies across three tiers: diversified life sciences conglomerates with platform breadth, mid-scale specialists with membrane and bag integration capabilities, and regional fabricators serving emerging market price sensitivity. Three archetypes dominate: platform-integrated suppliers bundling mixing systems with filtration and sensor portfolios; application-focused vendors concentrating on cell therapy or mRNA formulation niches; and contract manufacturers offering private-label disposable mixing assemblies. Competitive intensity centers on multi-year supply agreements and preferred supplier qualification status rather than equipment pricing alone.
Among diversified platform operators, Danaher and Thermo Fisher Scientific, Inc. anchor the premium tier through distribution reach across North American and European biologics clusters. Sartorius AG exemplifies the membrane-integrated specialist archetype, leveraging polymer film and bag portfolios to secure long-term mixing system contracts. These three entities represent distinct competitive vectors: Danaher through life sciences platform breadth, Thermo Fisher through channel density in biopharmaceutical clusters, and Sartorius through consumables-to-equipment vertical integration.
| Leading Market Players |
|---|
| Danaher |
| DrM Life Science |
| Sartorius AG |
| Agilitech |
| Avantor Inc. |
| Thermo Fisher Scientific, Inc. |
| Meissner Filtration Products, Inc. |
| Kuhner AG |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Top-20 biologics manufacturers in the United States and Europe anchor procurement volume through multi-year supply agreements, locking in contract-based long-term offtake pricing that bundles gamma-irradiated mixing bags with sensors and tubing assemblies under single-vendor accountability.
Pricing Analysis
Specialized multi-layer polymer film costs pass through directly to mixer system pricing, with German and United States resin suppliers commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP-grade systems for FDA submissions from process-development configurations and emerging-market basic offerings. Price differentiation hinges on extractables documentation depth and gamma irradiation certification tier. Cost compression in standard-tier magnetic stirring systems is intensifying as Indian and Chinese contract manufacturers qualify secondary suppliers.
Supply Chain Analysis
Freight costs for temperature-controlled gamma-irradiated component logistics strain working capital, compelling regional warehousing investments near Boston-Cambridge and Heidelberg biotech clusters. Manufacturing concentrates in Germany, the United States, and Switzerland for polymer film extrusion and sterile assembly. The supply chain draws from specialized fluoropolymer resins, multi-layer coextrusion equipment, and cobalt-60 irradiation facilities. Single-source vulnerability concentrates among qualified gamma irradiation providers. Distribution runs through direct vendor-to-facility channels with just-in-time sterile component logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultrasonic mixing platforms for lipid nanoparticle applications, where premium-tier positioning offsets resin cost volatility through reduced nucleic acid degradation value propositions.
For Market Incumbents: Cement preferred supplier status through captive supply of polymer films and welded tubing sets, locking out emerging entrants from EMA Annex 1 compliant fill-finish qualifications in Ireland and Belgium. Defend against application-focused gene therapy specialists by accelerating R&D in inline mixing modules for continuous bioprocessing integration. Prioritize certification investment in ISO 13485 quality management extensions for extractables data package automation. For New Entrants and Emerging Players: The price-point gap between premium magnetic stirring systems and economy-tier basic configurations opens white-space in mid-scale biosimilar manufacturing for CDMOs in Hyderabad and Bengaluru. Target India biosimilar expansion under CDSCO streamlined pathways with gamma-irradiated mixing bags sourced from regional polymer converters. Pursue private-label contract manufacturing partnerships with European distributors lacking in-house sterile assembly capabilities. For Investors and Strategic Acquirers: Life sciences platform conglomerates are the most active acquirer in this space, consolidating membrane-integrated specialists to complete fluid handling portfolios. Long-term viability rests on gene therapy vector production scale-up and mRNA formulation demand persistence. Target acquisition archetype: mid-scale specialists with validated extractables databases and regional sterile assembly footprints. Watch NMPA biosimilar approval velocity in Jiangsu and Zhejiang provinces as inflection indicator for Asia-Pacific capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Annex 1 compliance documentation accelerates fill-finish qualifications in European facilities. |
| Manufacturing Scale-Up | Ultrasonic mixer capacity expansion captures lipid nanoparticle demand from mRNA vaccine producers. |
| Backward Integration | In-house polymer film extrusion secures supply continuity against German resin supplier concentration. |
| Long-term Supply Agreement | Multi-year contracts with Massachusetts cell therapy CDMOs lock in gamma-irradiated bag volumes. |
| Joint Venture | Regional sterile assembly partnerships in India reduce freight costs for CDSCO-qualified biosimilar manufacturers. |
Research Methodology
Multiple input streams — primary interviews with bioprocess engineering directors, regulatory affairs leads at mixer vendors, and sterile manufacturing procurement managers; secondary validation through FDA guidance documents, EMA Annex 1 revisions, and ISO 13485 certification databases; plus customs records for gamma-irradiated polymer film trade flows — were reconciled through bottom-up equipment shipment analysis and top-down biopharmaceutical capital expenditure triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including mixing technology type, end-user sector qualification intensity, application shear sensitivity, and regional regulatory cluster adoption patterns. CAGRs were derived from installed base growth rates cross-referenced with biologics manufacturing capacity expansion announcements. Forecast inputs incorporated perfusion bioreactor adoption curves and gene therapy CDMO facility buildout pipelines.
Caveats apply where NMPA approval pathway revisions or sudden resin supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding EMA Annex 1 enforcement consistency and stainless-steel hybrid retention thresholds at large-volume facilities. A model refresh is warranted upon material change in lipid nanoparticle formulation technology migration away from ultrasonic platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Shrink Wrap Sealers Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Auger Filler Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Linear Net Weighing Machines Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
Powder Filling Equipment Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Vacuum Sealers Market