
 Medical Whirlpool Market | 2026-2036
Medical Whirlpool Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Whirlpool Market Foresight
Clinical-grade stainless steel construction and ADA-compliant accessibility specifications are redrawing procurement criteria across the medical whirlpool landscape. HydroWorx leverages its underwater treadmill integration to dominate the high-performance rehabilitation niche. Whitehall Manufacturing anchors its position through in-house fabrication of corrosion-resistant tanks for long-term care facilities. Chattanooga Group competes on channel control, sustaining broad distribution through physical therapy equipment dealers.
A medical whirlpool is a temperature-controlled hydrotherapy apparatus featuring turbine-driven water agitation, typically constructed with 304 or 316 stainless steel basins rated for continuous clinical use, designed to deliver thermal and mechanical stimulation for tissue healing and joint mobilization. Stationary units retain the largest installed base in hospital settings, while portable systems represent the fastest-growing configuration as outpatient clinics seek flexible deployment across treatment bays. Physical therapy applications command the deepest margin pools due to insurer reimbursement alignment, whereas pain management protocols are expanding fastest in sports clinic environments.
FDA 510(k) clearance requirements and ISO 13485 quality system standards govern device commercialization, while the EU Medical Device Regulation imposes additional clinical evidence burdens on manufacturers seeking European market access. These frameworks elevate compliance costs but simultaneously filter out non-specialist suppliers, concentrating procurement among validated vendors. Stakeholders must monitor evolving CMS reimbursement codes for hydrotherapy modalities, as coverage determinations will shape capital investment timelines for clinic operators and health system buyers.
Market Dynamics
FDA 510(k) clearance pathways and ISO 13485 quality management requirements are tightening validation standards for therapeutic equipment manufacturers, filtering procurement toward validated vendors and raising barriers for non-specialist suppliers seeking clinical market entry.
Growth Catalysts
- Post-surgical rehabilitation protocols:Health systems are expanding hydrotherapy service lines as orthopedic recovery pathways broaden reimbursement eligibility for water-based joint mobilization therapies.
- EU Medical Device Regulation:MDR clinical evidence requirements are concentrating European procurement among ISO 13485-certified manufacturers with established quality systems.
- Sports medicine infrastructure:Professional athletic training facilities and collegiate programs are driving replacement cycles for high-performance hydrotherapy systems with integrated underwater treadmill capabilities.
Market Restraints
- 316 stainless steel price volatility:Nickel and molybdenum input cost fluctuations compress margins for tank fabricators locked into fixed-price hospital contracts.
- Specialized component concentration:Precision turbine assemblies and temperature control modules rely on a limited supplier base concentrated in German and Japanese industrial clusters.
- Dry hydrotherapy substitution:Fluidized dry floatation beds and compression therapy systems compete for capital allocation in pain management clinics seeking lower maintenance overhead.
Strategic Opportunities
- Outpatient clinic expansion:Ambulatory surgery centers in Texas, Florida, and Arizona represent underpenetrated demand for portable whirlpool configurations deployable across multiple treatment bays.
- CMS reimbursement alignment:Proposed HCPCS code revisions for aquatic therapy modalities could unlock capital investment timelines for health system buyers awaiting coverage certainty.
- Telehealth-integrated monitoring:Convergence of IoT temperature sensors and remote patient monitoring platforms enables outcome documentation for value-based care contracts.
Industry Challenges
- Biomedical equipment technician scarcity:Qualified service personnel for turbine calibration and electrical safety testing command premium wages, extending maintenance response times in rural hospital districts.
- 510(k) submission timelines:FDA review backlogs for modified whirlpool controls and heating elements delay product launches by 8-14 months beyond internal development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Whirlpool Market |
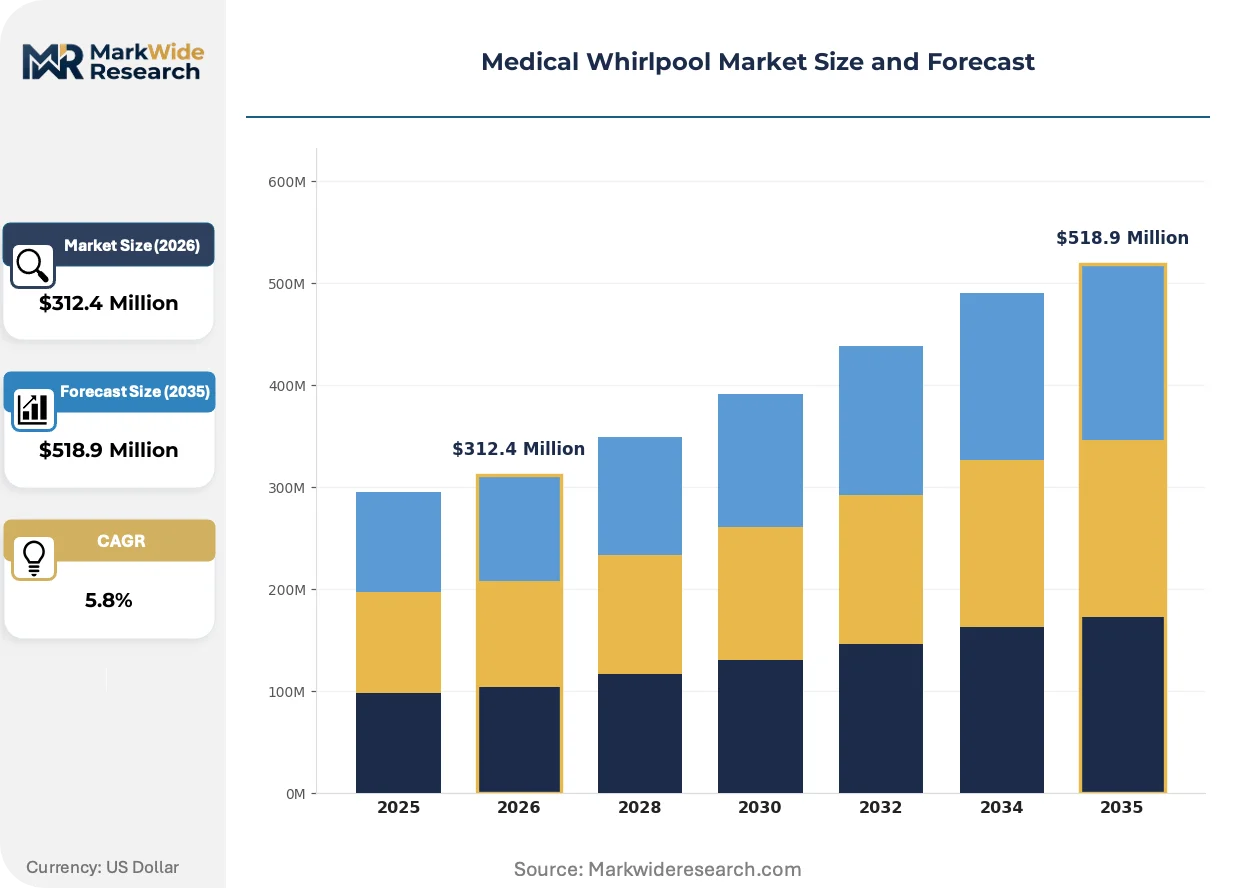
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Stationary Units, Mobile Units, Custom Designs End User: Hospitals, Rehabilitation Centers, Sports Clinics, Home Care Installation Type: In-ground, Above-ground, Modular, Fixed Application: Physical Therapy, Pain Management, Muscle Recovery, Spa Treatments |
| Companies Covered | Meyra Orthopedics, Sruyr Inc, HydroWorx, Meden-Inmed, HTI Hydrotherapy, Patterson Medical (Performance Health), ProHealthcareProducts, Whitehall Manufacturing, Chattanooga Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Whirlpool Market Shifts & Advancements
Digital integration and material science advances are redefining clinical hydrotherapy equipment specifications, with connectivity features and corrosion-resistant alloys displacing legacy mechanical systems in procurement evaluations.
Variable-speed turbine drives with programmable agitation profiles are fragmenting the traditional fixed-speed equipment segment. Outpatient physical therapy chains are adopting these systems to customize treatment protocols for post-operative shoulder and ankle rehabilitation. The technology is fragmenting vendor competitive positions by enabling smaller manufacturers to differentiate through software rather than capital-intensive tank fabrication scale.
EU MDR clinical evidence requirements are reshaping European market access conditions for whirlpool manufacturers. The regulation mandates post-market surveillance systems and risk management documentation that elevate compliance investments. German and Swiss rehabilitation equipment suppliers are absorbing these costs through captive clinical trial partnerships, while smaller competitors withdraw from CE marking applications.
Health system procurement departments are consolidating vendor relationships through multi-year equipment service agreements. Independent physical therapy practices face exclusion from preferred supplier networks as hospital-affiliated clinics negotiate volume commitments with Chattanooga Group and Whitehall Manufacturing. The consolidation is most visible in the southeastern United States, where health system mergers have reduced active vendor panels from twelve to four qualified suppliers per metropolitan market.
Medical Whirlpool Market Segmentation
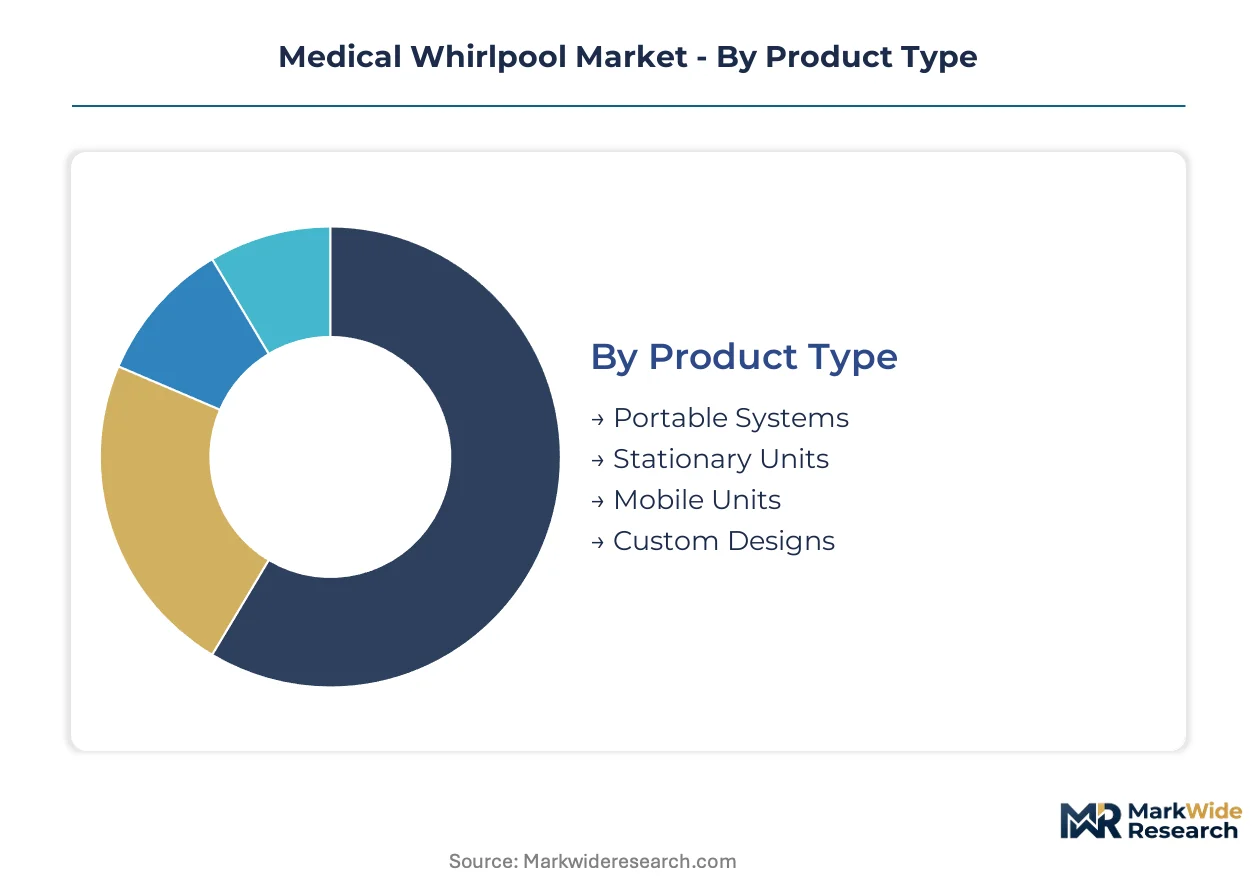
Segmentation in the medical whirlpool market reveals how procurement criteria diverge across clinical settings, from hospital capital budgets prioritizing durability to outpatient clinics seeking deployment flexibility. Understanding these divides enables manufacturers to align product development with margin concentration points.
Product Type:
Margin pools concentrate in systems offering configurability without sacrificing clinical-grade construction standards.
- Portable Systems:Compact turbine-driven units with detachable plumbing connections and caster-mounted frames rated for 500-pound load capacity. Demand concentrates in ambulatory surgery centers across Texas and Florida seeking flexible deployment across multiple treatment bays as outpatient volumes expand. These configurations are climbing the fastest as clinic operators prioritize capital efficiency over permanent infrastructure.
- Stationary Units:Fixed-installation stainless steel basins with integrated temperature control modules and ADA-compliant lift mechanisms. Hospitals in the United States anchor demand here, driven by replacement cycles for aging hydrotherapy infrastructure and alignment with Joint Commission accreditation requirements for accessibility.
- Mobile Units:Self-contained systems with onboard water heating and filtration designed for inter-departmental transport within health systems.
- Custom Designs:Bespoke tank configurations fabricated for specialized rehabilitation protocols or architectural constraints in long-term care facilities.
The dominant share belongs to Stationary Units, while Portable Systems is closing the gap fastest.
End User:
Customer-type segmentation tracks reimbursement alignment and capital allocation authority across care delivery models.
- Hospitals:Acute care facilities with centralized biomedical engineering departments and multi-year capital equipment cycles governed by value analysis committees. United States health systems drive specification standards here, with procurement teams prioritizing ISO 13485-certified vendors and comprehensive service agreements.
- Rehabilitation Centers:Dedicated post-acute facilities expanding hydrotherapy service lines as orthopedic recovery protocols broaden. These sites concentrate demand for variable-speed turbine systems with programmable agitation profiles.
- Sports Clinics:Athletic training facilities and collegiate programs investing in underwater treadmill integration for performance recovery.
- Home Care:Residential settings with limited penetration due to plumbing infrastructure requirements and reimbursement gaps for durable medical equipment classification.
Hospitals command the deepest procurement volumes, though Rehabilitation Centers are gaining share fastest as post-surgical protocols shift toward outpatient settings.
Installation Type:
Volume concentration follows construction cost structures and facility lifecycle planning horizons.
- In-ground:Permanent basin installations with sub-floor plumbing and structural reinforcement for high-frequency clinical use. Long-term care facilities in the United States favor these configurations for durability and aesthetic integration with therapeutic environments.
- Above-ground:Surface-mounted systems with elevated tank walls and external access panels for maintenance. These dominate retrofit installations where structural modifications are cost-prohibitive.
- Modular:Prefabricated panel systems enabling rapid assembly and future reconfiguration.
- Fixed:Welded-frame constructions with integrated mechanical housing and hard-piped utilities.
Above-ground configurations hold the largest installed base, while Modular systems are expanding most quickly as lease-based facility models proliferate.
Application:
Application segmentation maps clinical utility to reimbursement code alignment and outcome documentation requirements.
- Physical Therapy:Joint mobilization and post-operative rehabilitation protocols requiring precise temperature control and variable agitation for tissue healing. This segment aligns with CMS HCPCS coding for aquatic therapy, concentrating demand in Medicare-certified outpatient clinics.
- Pain Management:Thermal and mechanical stimulation for chronic conditions, competing with dry hydrotherapy alternatives in clinics seeking lower maintenance overhead.
- Muscle Recovery:Athletic performance applications emphasizing rapid temperature transition and turbine intensity for lactate clearance.
- Spa Treatments:Wellness-oriented hydrotherapy with reduced clinical documentation requirements and discretionary consumer payment.
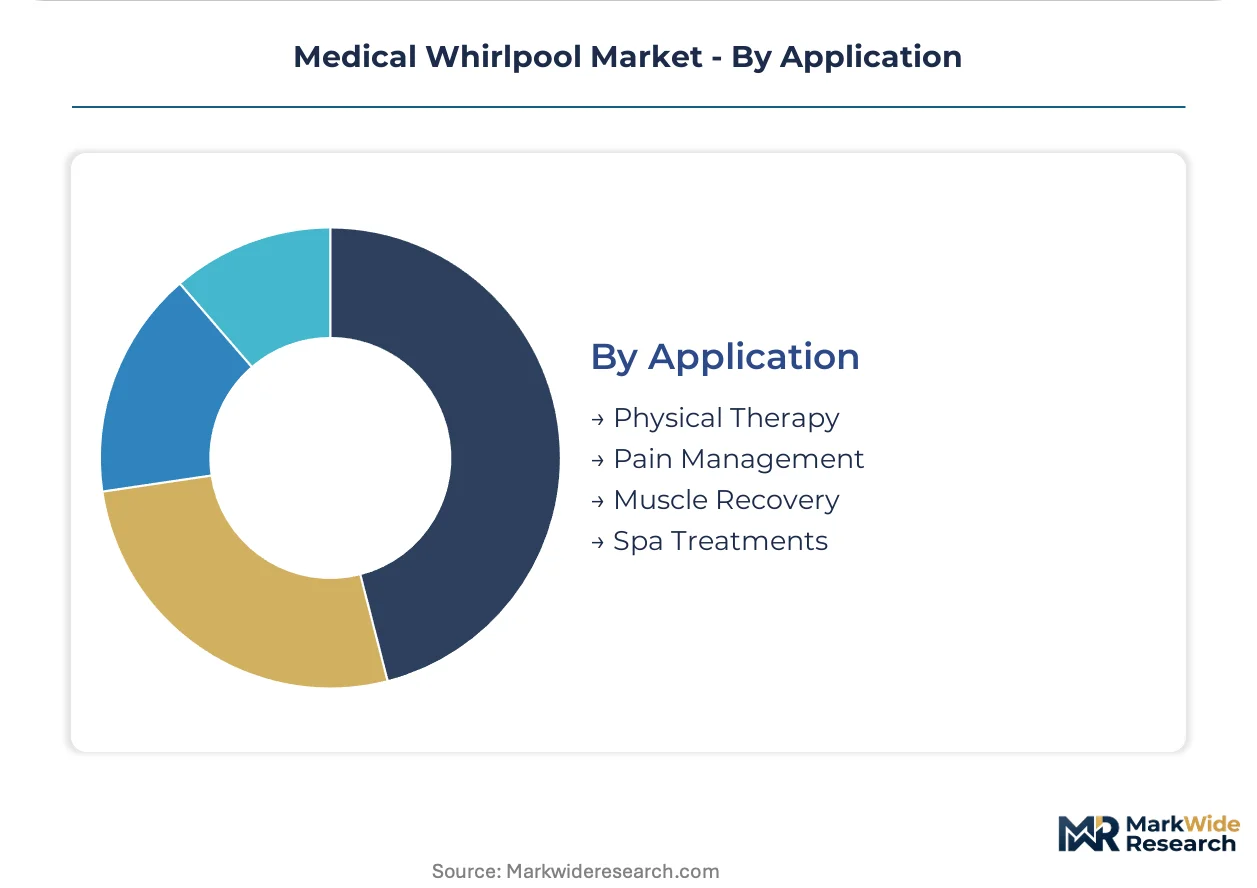
Physical Therapy captures the dominant revenue position, while Pain Management is gaining traction fastest as non-opioid alternatives attract capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of medical whirlpool systems track toward markets with aging demographics and expanding rehabilitation infrastructure. Import dependence concentrates in regions lacking domestic stainless steel fabrication capacity for clinical-grade tank construction.
United States
Medicare reimbursement alignment for aquatic therapy modalities drives hospital capital expenditure cycles. FDA 510(k) clearance requirements filter procurement toward validated domestic and European suppliers. The Southeast corridor from Florida through Georgia concentrates ambulatory surgery center expansion, with Texas and Arizona outpatient clinics adopting portable configurations for flexible deployment.
Germany
EU Medical Device Regulation clinical evidence mandates reshape competitive access conditions for therapeutic equipment. German rehabilitation equipment suppliers absorb compliance costs through established quality management systems. Industrial clusters in Baden-Württemberg and Bavaria anchor precision turbine assembly and temperature control module production for European market supply.
Japan
PMDA medical device registration requirements and JIS standards govern market entry for hydrotherapy apparatus. METI healthcare technology adoption programs accelerate replacement cycles in geriatric care facilities. The Kansai region around Osaka maintains concentration in specialized component manufacturing for turbine-driven water agitation systems.
United Kingdom
NHS procurement frameworks prioritize ISO 13485-certified vendors for hydrotherapy service line expansion. MHRA post-Brexit device registration creates parallel compliance obligations alongside retained EU MDR alignment. London and Southeast England health systems drive specification standards through centralized value analysis committees.
Canada
Health Canada medical device licensing requirements parallel FDA pathways with modified quality system expectations. Provincial health authority capital budgets concentrate procurement in Ontario and Quebec rehabilitation centers. The Pacific Northwest supply chain integration enables cross-border component sourcing for tank fabricators serving North American demand.
Medical Whirlpool Market Competitive Landscape
Concentration sits with diversified rehabilitation equipment manufacturers possessing captive fabrication capabilities and established service networks. The vendor base stratifies across three tiers: integrated healthcare conglomerates with multi-modality portfolios, specialized hydrotherapy equipment fabricators with in-house tank production, and regional assembly operations sourcing precision components from German and Japanese industrial clusters. Dominant competitive moves include multi-year equipment service agreements that consolidate hospital procurement relationships, and backward integration into corrosion-resistant alloy supply chains to buffer nickel and molybdenum price volatility.
Among diversified rehabilitation equipment suppliers, Chattanooga Group and Whitehall Manufacturing anchor positions through channel control and in-house fabrication respectively. HydroWorx occupies a distinct tier through underwater treadmill integration for high-performance athletic applications. These three exemplify the strategic archetypes shaping competitive dynamics: channel-dominant conglomerates, fabrication-specialized manufacturers, and technology-integrated performance specialists.
| Leading Market Players |
|---|
| Meyra Orthopedics |
| Sruyr Inc |
| HydroWorx |
| Meden-Inmed |
| HTI Hydrotherapy |
| Patterson Medical (Performance Health) |
| ProHealthcareProducts |
| Whitehall Manufacturing |
| Chattanooga Group |
| Others |
Supply & Pricing Matrix
Capacity utilization at German and Japanese precision turbine manufacturers shapes both supply concentration and price floors for clinical-grade hydrotherapy equipment. Stainless steel tank fabricators in the United States absorb nickel and molybdenum volatility through captive alloy sourcing, while outpatient clinic buyers face widening spreads between premium ADA-compliant systems and economy portable configurations.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers, with ISO 13485 certification and comprehensive service agreements commanding material premiums over non-validated alternatives. Price differentiation rests on FDA 510(k) clearance status and Joint Commission accreditation alignment, with rehabilitation centers showing highest sensitivity to capital outlay and sports clinics least sensitive to performance-integrated premiums. Cost compression in the standard tier is intensifying as outpatient surgery centers prioritize deployable configurations over permanent infrastructure.
Supply Chain Analysis
Strategic stockpiling of 316 stainless steel dominates procurement strategy among tank fabricators facing nickel price volatility, while just-in-time component flows persist for precision turbine assemblies. Supply concentrates in Germany for temperature control modules, Japan for agitation drive systems, and the United States for basin fabrication serving North American demand. Raw material dependencies span nickel-molybdenum alloys, medical-grade silicone seals, and programmable logic controllers. Single-source vulnerability in precision turbine supply creates structural exposure to logistics disruptions. Distribution runs through physical therapy equipment dealers and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance backlogs and EU MDR clinical evidence mandates are accelerating vendor consolidation, rewarding manufacturers with established quality systems and captive fabrication capabilities.
For Market Incumbents: Consolidate procurement relationships through multi-year equipment service agreements that embed biomedical technician training and preventive maintenance schedules. Deepen backward integration into corrosion-resistant alloy supply chains to buffer nickel price volatility, while accelerating CE marking investments to capture European rehabilitation center demand before smaller competitors withdraw from MDR compliance. For New Entrants and Emerging Players: Anchor in ambulatory surgery center expansion corridors across Texas, Florida, and Arizona where portable whirlpool deployment flexibility meets underpenetrated demand. Target variable-speed turbine systems with programmable agitation profiles as the most penetrable segment, exploiting software differentiation to circumvent capital-intensive tank fabrication scale requirements. Pursue direct-to-clinic sales models bypassing established dealer networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with installed base service contracts and GPO-embedded procurement relationships, offering superior cash flow predictability across replacement cycles. Long-term viability favors ISO 13485-certified fabricators with in-house stainless steel production and FDA submission track records. Watch FDA 510(k) review timeline compression as the signal for accelerated product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Reduces time-to-revenue for modified turbine controls and heating elements in United States markets. |
| EU MDR Clinical Evidence Partnership | Enables German and Swiss suppliers to absorb post-market surveillance costs through captive trial networks. |
| Hospital System Partnership | Locks in volume commitments through value analysis committee alignment and multi-year service agreements. |
| Software Companion Development | Supports IoT temperature sensor integration for telehealth-integrated monitoring and value-based care documentation. |
| Reimbursement Strategy | Aligns aquatic therapy modalities with proposed HCPCS code revisions to unlock capital investment timelines. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation, and hospital procurement contract filings preceded structured interviews with biomedical engineers, physical therapy clinic operators, health system value analysis committee members, and GPO contracts managers. Secondary validation drew from ISO 13485 certification registries, CMS HCPCS coding determinations, and stainless steel trade flow data. Bottom-up demand modeling from clinic installation counts and replacement cycles was triangulated against top-down health system capital expenditure surveys.
Variance decomposition across product type, end user, installation configuration, and application dimensions informed the analytical framework over the projection horizon. CAGRs were derived from segmented demand growth rates weighted by reimbursement alignment and capital allocation authority. Industry-specific forecast inputs included orthopedic surgery volume projections and Medicare aquatic therapy coverage determinations.
Decision-makers should treat outputs as directional under assumptions of stable FDA review timelines and sustained nickel price ranges; material deviation would warrant model refresh. Revision becomes warranted when EU MDR enforcement intensity or CMS reimbursement code finalization crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Autopsy Equipment Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Autoclaves Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
ECG Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Contact Lens Inspection Equipment Market