
 Hospital Foodservice Equipment Market | 2026-2036
Hospital Foodservice Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Foodservice Equipment Market Outlook
Market Context
The capital-intensity divergence between full-line manufacturers and specialized equipment vendors is rotating competitive dynamics across the hospital foodservice landscape. Illinois Tool Works Inc. leverages its diversified industrial portfolio to sustain cross-sector engineering capabilities that lower per-unit development costs for healthcare-specific applications. Electrolux Professional AB anchors its position through deep European channel relationships and institutional-grade product reliability. Middleby Corporation competes by extending its commercial kitchen expertise into hospital environments with scalable thermal cooking platforms.
Technical Definition and Segments
Hospital foodservice equipment encompasses electrically or gas-powered appliances, temperature-controlled storage systems, and meal distribution infrastructure engineered to prepare, hold, and deliver therapeutic diets within regulated healthcare environments, typically operating within HACCP-critical temperature bands of 40°F to 140°F for food safety compliance. Cooking Equipment commands the largest installed base due to centralized kitchen requirements, while Refrigeration Systems carries premium margin pools driven by precision temperature logging and redundancy specifications. Serving Equipment represents the fastest-growing category as hospitals adopt automated tray delivery and room-service models to replace traditional bulk cart systems.
Regulatory Frame and Outlook
The FDA Food Code, OSHA workplace safety standards, and The Joint Commission accreditation requirements collectively mandate stainless-steel construction, cleanable joint designs, and documented temperature monitoring across all hospital food handling zones. These frameworks elevate replacement cycles and disqualify commercial-grade alternatives that lack healthcare-specific certifications. Stakeholders must monitor evolving CMS reimbursement rules tied to patient satisfaction metrics, as these increasingly influence capital allocation toward meal service modernization rather than purely clinical equipment.
Market Dynamics
Acute care hospitals are consolidating kitchen operations into centralized commissary models, forcing equipment vendors to engineer modular platforms that retrofit legacy infrastructure while meeting Joint Commission sanitation mandates.
Growth Catalysts
- CMS Reimbursement Ties:Medicare's Hospital Consumer Assessment of Healthcare Providers and Systems (HCAHPS) scores now weight patient meal satisfaction, compelling capital investment in automated tray delivery and room-service infrastructure.
- FDA Food Code Alignment:State health departments are adopting the 2022 FDA Food Code provisions requiring continuous temperature monitoring with digital logging, accelerating replacement of analog refrigeration systems in licensed healthcare kitchens.
- Robotic Tray Assembly:Vision-guided robotic cells for portioning and tray assembly are cutting labor dependency in high-volume acute care facilities, with early adopters reporting throughput gains above manual benchmarks.
Market Restraints
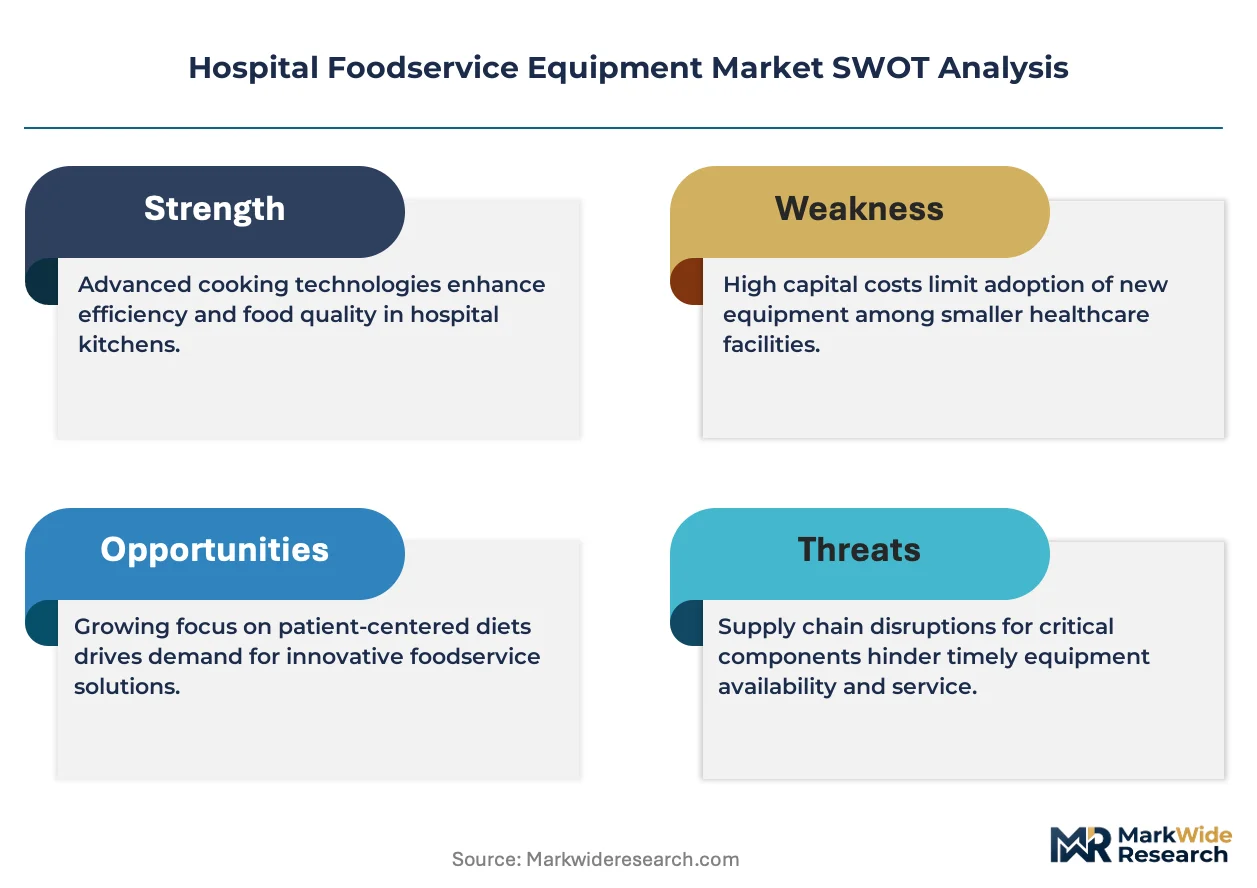
- Stainless Steel Input Volatility:Grade 304 stainless price swings tied to Indonesian nickel export policies are compressing fabrication margins for domestic equipment manufacturers.
- Certification Bottlenecks:NSF International healthcare equipment listings require 14-18 month validation cycles, freezing product refresh rates below commercial kitchen equipment norms.
- Specialized Service Networks:Factory-authorized technician density concentrates in metropolitan hospital clusters, leaving rural critical access hospitals with 72-hour mean time to repair for thermal holding cabinets.
Strategic Opportunities
- Behavioral Health Expansion:Psychiatric and substance abuse treatment facilities represent an underserved vertical with distinct equipment needs—smaller batch cooking, anti-ligature design, and extended holding tolerance for irregular meal schedules.
- Cloud-Connected Asset Management:IoT-enabled refrigeration with predictive failure analytics creates recurring revenue streams through subscription-based remote monitoring contracts.
- Energy Efficiency Incentives:The Inflation Reduction Act's commercial building deduction is covering up to $5.00 per square foot for kitchen electrification retrofits, shortening payback periods for induction cooking platforms.
Industry Challenges
- HACCP-Certified Technician Shortage:Field service engineers capable of calibrating integrated cooking-chilling systems to FDA variance standards command 40% wage premiums above commercial appliance technicians, constraining OEM service expansion.
- Legacy Control System Integration:Automated tray delivery robots must interface with 1990s-era building management systems through custom protocol bridges, extending commissioning timelines.
- Clean-in-Place Validation:USDA-accepted CIP chemistries for healthcare applications require separate efficacy studies from food processing norms, duplicating regulatory spend for multi-sector suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Foodservice Equipment Market |
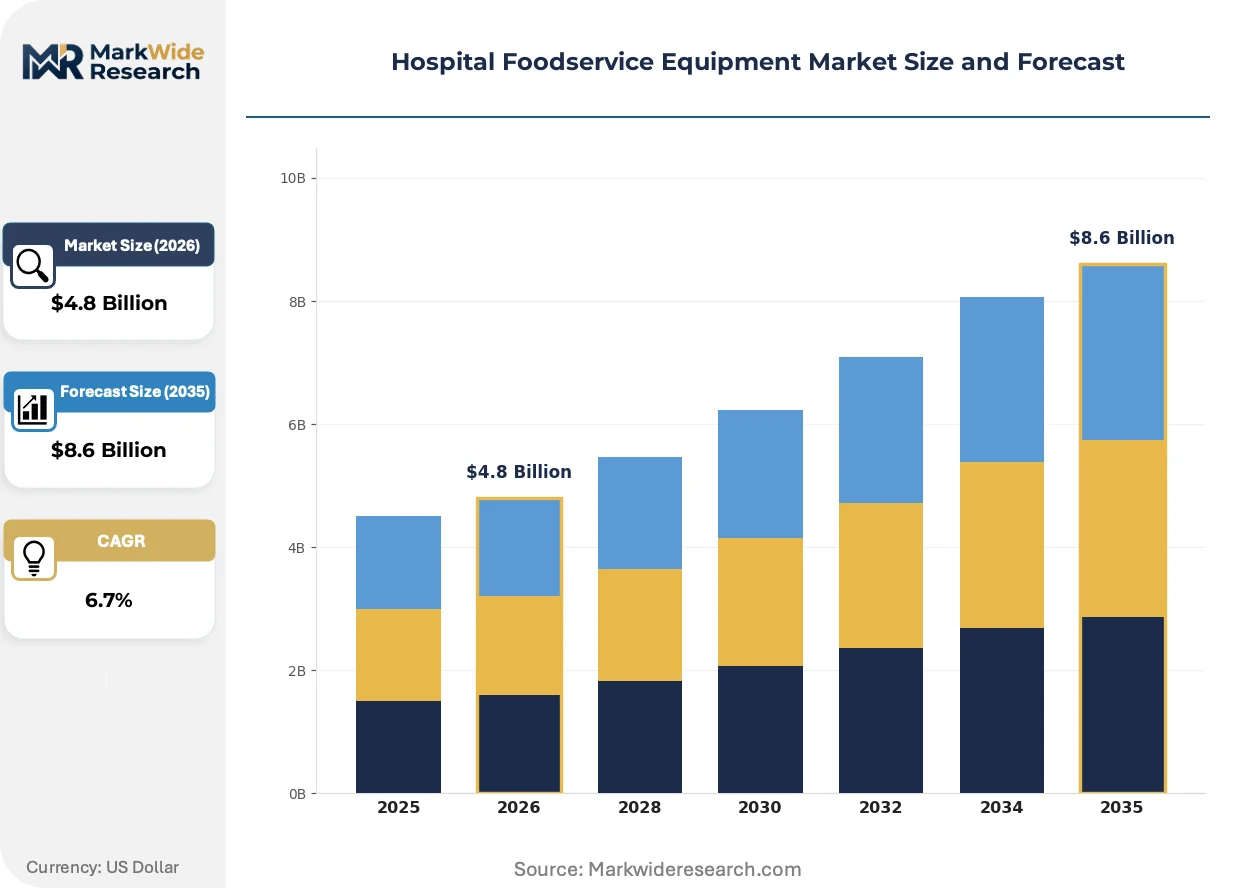
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Cooking Equipment, Refrigeration Systems, Serving Equipment, Preparation Equipment End User: Hospitals, Clinics, Long-term Care Facilities, Emergency Medical Services Material: Stainless Steel, Aluminum, Plastic, Glass Functionality: Food Storage, Meal Preparation, Food Transport, Serving Solutions |
| Companies Covered | Illinois Tool Works Inc., Electrolux Professional AB, Middleby Corporation, MKN GmbH, Hoshizaki Corporation, Welbilt Inc., Rational AG, Alto-Shaam Inc., Ali Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Foodservice Equipment Market Strategic Shifts
Equipment form factors and control architectures are compressing to fit decentralized micro-kitchen concepts, while connectivity standards and procurement models are rewiring how hospitals acquire and operate foodservice assets.
Induction cooking modules with sub-200mm depth profiles are miniaturizing to fit corridor-mounted satellite pantries in renovated patient towers. Cleveland Clinic and Kaiser Permanente are specifying these slimline platforms for 2024-2026 infrastructure projects. The technology is miniaturizing centralized production footprints, enabling point-of-service cooking on clinical floors previously limited to rethermalization.
The EPA's Significant New Alternatives Policy (SNAP) program is phasing R-404A and R-507A refrigerants from commercial applications, forcing compressor redesigns for healthcare refrigeration. Equipment OEMs are pivoting to R-448A and R-449A drop-in replacements with minimal glide penalty. Cold chain redundancy specifications in The Joint Commission environment of care standards are tightening, accelerating dual-circuit system adoption in blood bank and nutrition storage applications.
Hospital procurement departments are consolidating foodservice equipment under integrated facilities management contracts, unbundling capital purchase from lifecycle service. Aramark and Compass Group are capturing multi-year kitchen asset management agreements that shift OEM relationships to indirect channel structures. This concentration is most visible in the United States, where health system mergers have created ten buyers controlling 28% of acute care bed capacity.
Hospital Foodservice Equipment Market Segmentation
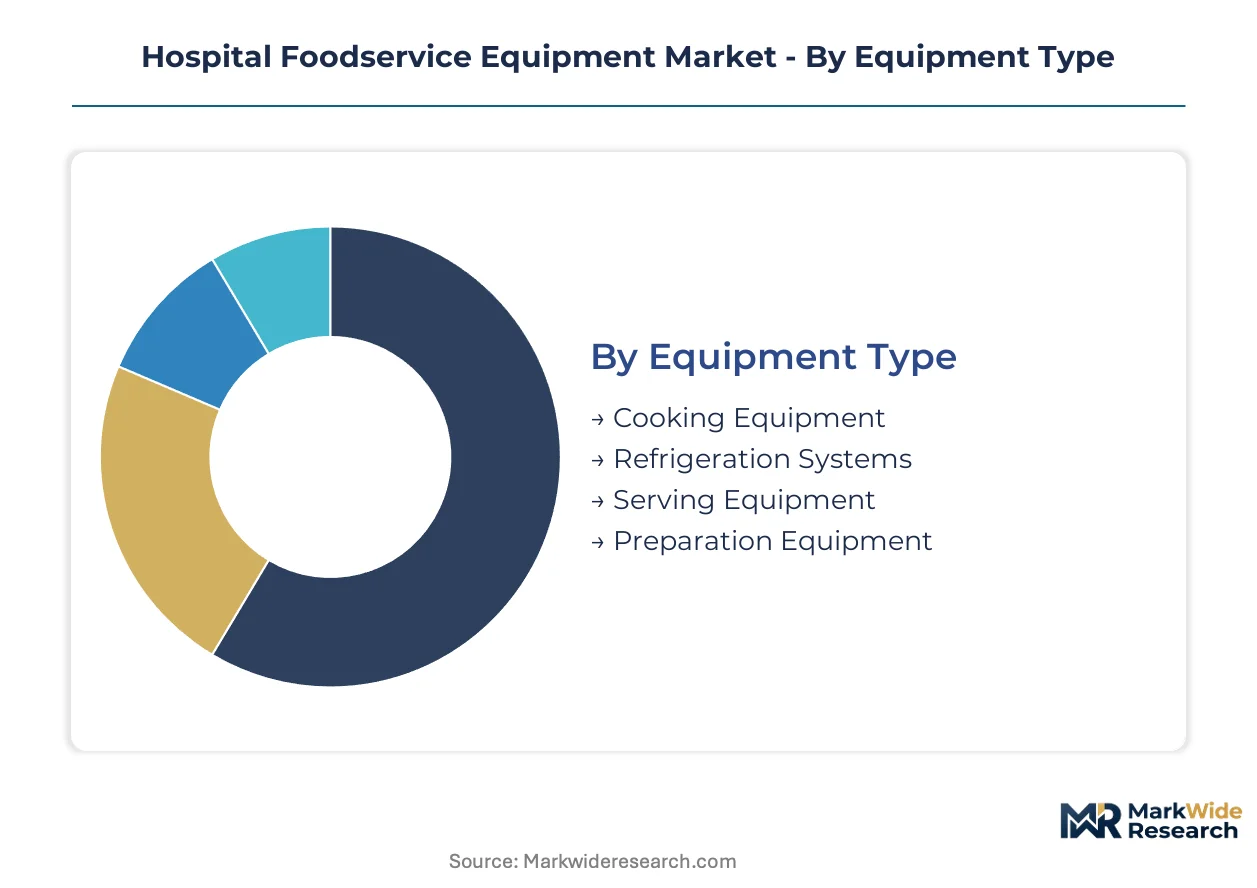
Hospital foodservice equipment segmentation reveals how regulatory pressure, material science, and care delivery models reshape procurement priorities. Each dimension exposes distinct margin pools and compliance burdens that vendors must navigate.
Equipment Type:
FDA Food Code temperature mandates and Joint Commission sanitation standards create divergent certification requirements across equipment categories.
- Cooking Equipment:Gas and electric ranges, steamers, and combi-ovens engineered for centralized production kitchens. Acute care hospitals in the United States anchor replacement cycles as they consolidate into commissary models requiring high-volume thermal platforms.
- Refrigeration Systems:Reach-in coolers, walk-in freezers, and blast chillers with digital temperature logging for HACCP documentation. Precision redundancy specifications for nutrition storage and blood bank applications command premium margins in tertiary care facilities.
- Serving Equipment:Heated cabinets, tray delivery carts, and automated distribution systems. Vision-guided robotic tray assembly and room-service infrastructure are expanding most quickly as HCAHPS scores weight patient meal satisfaction.
- Preparation Equipment:Mixers, slicers, and portioning devices for therapeutic diet production. Smaller batch capabilities serve behavioral health and long-term care environments with irregular meal schedules.
Established volume favors Cooking Equipment; emerging adoption favors Serving Equipment.
End User:
Capital allocation intensity varies sharply across care settings, with reimbursement structures dictating modernization timelines.
- Hospitals:Acute care facilities with centralized kitchens and automated tray lines. Infrastructure modernization programs in the United States are accelerating kitchen and tray line investments tied to patient satisfaction metrics.
- Clinics:Outpatient and ambulatory surgical centers with limited foodservice footprints. Compact rethermalization and satellite pantry configurations dominate procurement specifications.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities with extended resident stays. Texture-modified diet production and anti-choking preparation protocols drive equipment selection.
- Emergency Medical Services:Mobile and field-based nutrition support units. Ruggedized transport containers and field kitchen systems serve disaster response and military applications.
Hospitals concentrate procurement volume; behavioral health and substance abuse treatment facilities represent the steepest expansion trajectory for specialized equipment needs.
Material:
Surface chemistry and cleanability standards from NSF International and FDA frameworks elevate certain substrates over commercial alternatives.
- Stainless Steel:Grade 304 and 316 alloys for food contact surfaces, welded joints, and cleanable designs. Indonesian nickel export policies are compressing fabrication margins for domestic manufacturers.
- Aluminum:Lightweight structural components and heat transfer elements in cooking equipment. Lower thermal mass enables faster temperature response in induction-compatible platforms.
- Plastic:Food-safe polymers for trayware, utensil caddies, and non-contact housing components. Anti-ligature specifications in psychiatric facilities constrain material selection.
- Glass:Tempered viewing panels and display merchandising in retail-style cafeteria concepts. Thermal shock resistance limits applications in high-temperature zones.
Stainless Steel dominates specification sheets; Aluminum is gaining share fastest in slimline induction modules for corridor-mounted satellite pantries.
Functionality:
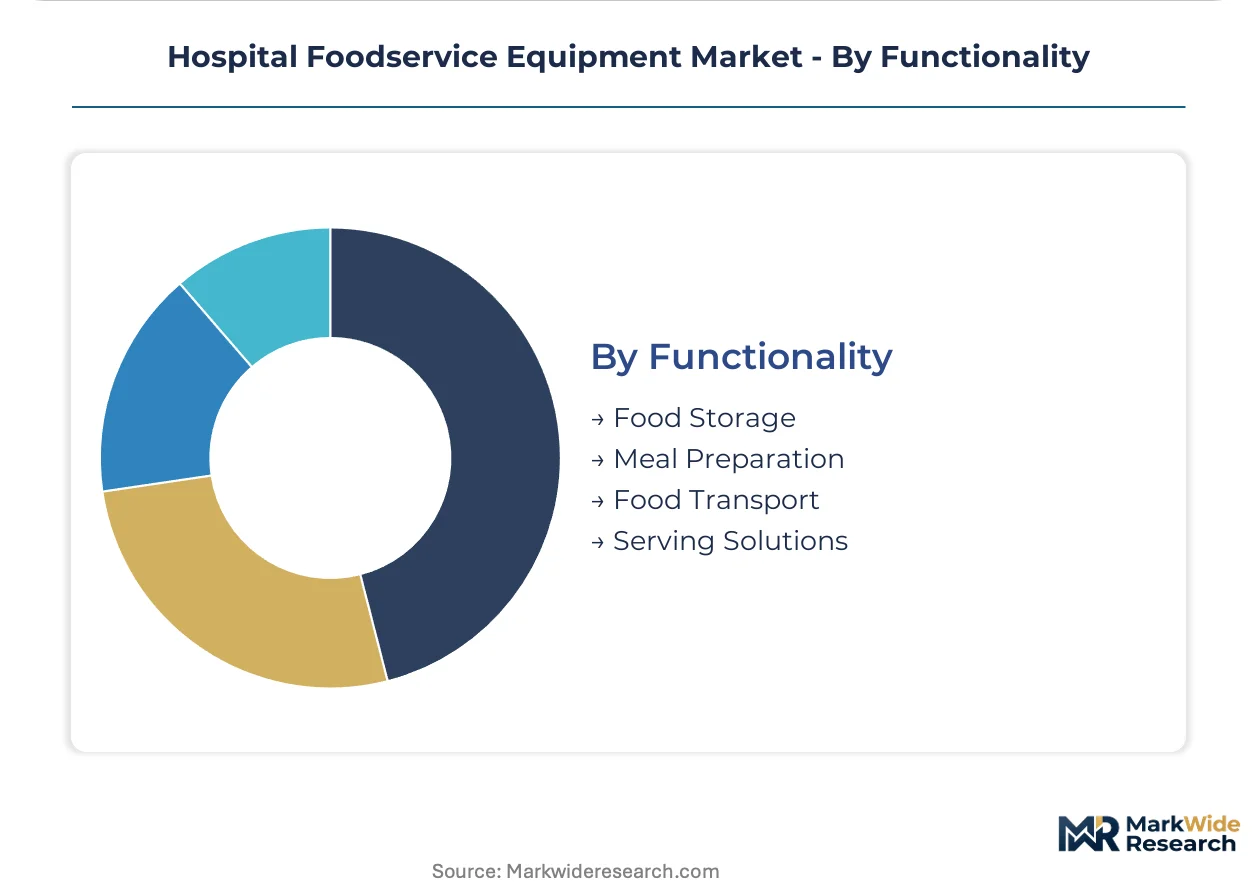
Workflow integration and temperature band compliance segment equipment by operational role within the HACCP-critical 40°F to 140°F range.
- Food Storage:Cold chain infrastructure with continuous monitoring and digital logging. EPA SNAP refrigerant phaseouts are forcing compressor redesigns toward R-448A and R-449A drop-in replacements.
- Meal Preparation:Cooking and assembly platforms for therapeutic and texture-modified diets. Robotic portioning cells are cutting labor dependency in high-volume acute care facilities.
- Food Transport:Insulated carts, pneumatic tube systems, and automated guided vehicles for tray delivery. Legacy building management system integration extends commissioning timelines for robotic implementations.
- Serving Solutions:Patient room service infrastructure and decentralized micro-kitchen concepts. Cleveland Clinic and Kaiser Permanente specifications for sub-200mm depth induction modules are compressing form factors.
Food Storage commands replacement urgency from regulatory compliance; Serving Solutions climbs the fastest as room-service models displace bulk cart systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision refrigeration compressors and stainless steel fabrication equipment tilts the trade balance toward manufacturing economies with established healthcare infrastructure supply chains. Capital deployment patterns reveal acute care modernization cycles concentrated in North American and Western European hospital networks, while procurement growth accelerates in select Asia-Pacific tertiary care markets.
United States
Hospital infrastructure modernization programs across integrated delivery networks are accelerating kitchen and tray line investments tied to HCAHPS patient satisfaction metrics. The FDA's 2022 Food Code provisions for continuous temperature monitoring with digital logging are forcing replacement of analog refrigeration systems in licensed healthcare kitchens. The Cleveland Clinic and Kaiser Permanente specifications for slimline induction modules are compressing form factors in corridor-mounted satellite pantries across renovated patient towers in Ohio and California.
Germany
Electrolux Professional AB anchors European channel relationships through institutional-grade product reliability serving centralized commissary models. The EU F-Gas Regulation phasing R-404A and R-507A refrigerants from commercial applications is forcing compressor redesigns toward R-448A and R-449A drop-in replacements. Industrial clusters in Baden-Württemberg and Bavaria concentrate fabrication capacity for precision temperature logging systems serving tertiary care facilities.
China
Domestic hospital construction programs in tier-one cities are expanding automated meal delivery infrastructure for centralized kitchen operations. The country's national healthcare regulator mandates stainless-steel construction and cleanable joint designs across all food handling zones. Manufacturing concentrations in the Yangtze River Delta supply modular thermal platforms retrofitting legacy infrastructure in Shanghai and Beijing acute care facilities.
Japan
Hoshizaki Corporation exemplifies precision refrigeration engineering serving HACCP-critical temperature band compliance in compact healthcare footprints. METI energy efficiency standards for commercial kitchen equipment are shortening payback periods for induction cooking platform adoption. The Kansai region around Osaka maintains specialized fabrication capacity for dual-circuit redundancy systems in blood bank and nutrition storage applications.
United Kingdom
NHS infrastructure investment programs are consolidating foodservice equipment procurement under integrated facilities management contracts unbundling capital purchase from lifecycle service. The Health and Safety Executive workplace safety standards mandate documented temperature monitoring across all hospital food handling zones. London and Southeast England health system mergers are creating concentrated buyer power controlling substantial acute care bed capacity procurement decisions.
Hospital Foodservice Equipment Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized commercial kitchen equipment vendors competing through cross-sector engineering capabilities and institutional-grade product reliability. The vendor base spans full-line manufacturers sustaining lower per-unit development costs through diversified portfolios alongside focused specialists capturing premium margins in precision temperature applications. Two strategic archetypes dominate: diversified industrial groups leveraging cross-sector engineering scale, and specialized commercial kitchen equipment vendors extending institutional expertise into healthcare environments. Competitive moves center on modular platform engineering for legacy infrastructure retrofit and cloud-connected asset management subscriptions creating recurring revenue streams.
Within the diversified industrial tier, Illinois Tool Works Inc. and Electrolux Professional AB exemplify archetypes sustaining engineering capabilities across multiple sectors while anchoring healthcare-specific applications. Middleby Corporation occupies a position representing commercial kitchen expertise extension into hospital environments with scalable thermal platforms. Among specialized European fabricators, MKN GmbH and Rational AG represent precision engineering concentrations serving HACCP-critical compliance requirements. Hoshizaki Corporation anchors Japanese refrigeration specialization for compact healthcare footprints with dual-circuit redundancy specifications.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Electrolux Professional AB |
| Middleby Corporation |
| MKN GmbH |
| Hoshizaki Corporation |
| Welbilt Inc. |
| Rational AG |
| Alto-Shaam Inc. |
| Ali Group S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts between hospital systems and equipment OEMs lock in stainless steel supply access while fixing fabrication costs against Indonesian nickel export volatility. These agreements bundle preventive maintenance subscriptions with capital purchases, creating price visibility across multi-year replacement cycles.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. NSF healthcare certification tier and volume scale drive price differentiation, with tertiary care facilities absorbing premium margins for precision temperature logging. Cost compression in standard-grade thermal platforms is intensifying because domestic fabricators face margin pressure from nickel price swings. Critical access hospitals exhibit highest price sensitivity, while integrated delivery networks leverage consolidated procurement for least sensitivity.
Supply Chain Analysis
Strategic stockpiling of Grade 304 stainless steel dominates procurement strategy among domestic fabricators, insulating against Indonesian export policy disruptions. Manufacturing concentrates in the United States, Germany, and China, drawing from nickel mining in Indonesia, compressor production in Japan, and precision electronics from South Korea. Single-source vulnerability in refrigerant compressor supply creates exposure to EPA SNAP phaseout timelines. Distribution runs through factory-authorized service networks concentrated in metropolitan hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cloud-connected asset management subscriptions are rewiring vendor-customer relationships from transactional equipment sales toward recurring revenue ecosystems.
For Market Incumbents: Shield installed base relationships by embedding IoT predictive analytics into service contracts before emerging robotics vendors capture tray assembly automation accounts. Prioritize backward integration into refrigerant compressor supply to insulate margins from EPA SNAP redesign cycles. Consolidate metropolitan service technician density to close the 72-hour repair gap plaguing rural critical access hospitals. For New Entrants and Emerging Players: Differentiate on behavioral health specialization, where anti-ligature design requirements and irregular meal schedule tolerance create specification gaps incumbent vendors overlook. Penetrate psychiatric and substance abuse treatment facilities first, then ladder into long-term care networks. Pursue direct GPO contracting bypassing integrated facilities management intermediaries. For Investors and Strategic Acquirers: Cloud-native equipment startups with FDA-validated temperature logging software represent the most defensible acquisition archetype against incumbent hardware bundling. Long-term viability hinges on recurring revenue attachment rates exceeding traditional equipment depreciation cycles. Monitor CMS reimbursement rule shifts linking HCAHPS meal satisfaction scores to capital allocation priority as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Asset Management Subscription | Transforms OEM economics from capital sales toward recurring remote monitoring revenue streams. |
| Behavioral Health Equipment Specialization | Captures underserved vertical with anti-ligature specifications distinct from acute care norms. |
| Refrigerant Compressor Backward Integration | Insulates fabrication margins from EPA SNAP phaseout-driven supply disruptions. |
| Metropolitan Service Network Expansion | Closes 72-hour mean repair gap for rural critical access hospitals. |
| GPO Direct Contracting Bypass | Disintermediates Aramark and Compass Group facilities management concentration. |
Study Parameters
The analysis maps cooking equipment, refrigeration systems, serving equipment, and preparation equipment segments, each validated through hospital foodservice directors, biomedical engineers, GPO contracts managers, and aftermarket service heads. Primary interviews combined with secondary validation from FDA Food Code provisions, CMS Medicare reimbursement databases, hospital procurement records, and SEC equipment manufacturer filings. Bottom-up equipment unit economics and top-down health system capital expenditure patterns were triangulated.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include equipment type, end user category, material specification, and functionality role. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and reimbursement incentive alignment. Forecast inputs incorporated HCAHPS score weighting effects and EPA SNAP refrigerant phaseout timelines.
Forecasts assume regulatory continuity in FDA Food Code enforcement and CMS reimbursement structures; material policy shifts would require re-modeling. Stainless steel commodity volatility and NSF certification bottleneck durations represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as Indonesian nickel export policies and Joint Commission sanitation standard evolutions unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market