
 Food Warmer Machines Market | 2026-2036
Food Warmer Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Food Warmer Machines Market Foresight
CE marking under the EU Machinery Directive is decoupling low-cost imports from premium European distribution channels. Hatco Corporation leverages its vertical manufacturing footprint in Wisconsin to sustain price stability across North American foodservice channels. Alto-Shaam, Inc. anchors its competitive position through low-temperature holding technology that extends product shelf life without dehydration. The Vollrath Company, LLC dominates stainless fabrication capacity, allowing it to control lead times for custom institutional contracts.
Food warmer machines are electromechanical or gas-fired thermal holding devices engineered to maintain prepared food between 60°C and 85°C through controlled heat transfer, with cabinet variants incorporating humidity injection to prevent moisture loss. Their primary commercial purpose is bridging the production-service gap in high-throughput kitchens where synchronous cooking and consumption is operationally impossible. Electric warmers occupy the largest installed base across quick-service and full-service restaurants, though induction warmers are gaining traction where energy efficiency mandates tighten operating cost structures. Steam warmers retain dominant share in institutional cafeteria settings where batch volume and food safety compliance converge, while infrared warmers compete for countertop and buffet line applications demanding rapid recovery without drying.
The US FDA Food Code and state-level health department inspections shape equipment specification across American foodservice, mandating calibrated temperature logging that favors digital control platforms. Ecodesign requirements under the EU F-Gas Regulation and national efficiency standards in Japan's METI framework are narrowing the field to manufacturers with certified test lab partnerships. Stakeholders must monitor how dual carbon goals in China's MEE and India's BIS energy labeling converge on heating element efficiency thresholds, as these will determine which product architectures remain import-viable across the largest growth corridors.
Market Dynamics
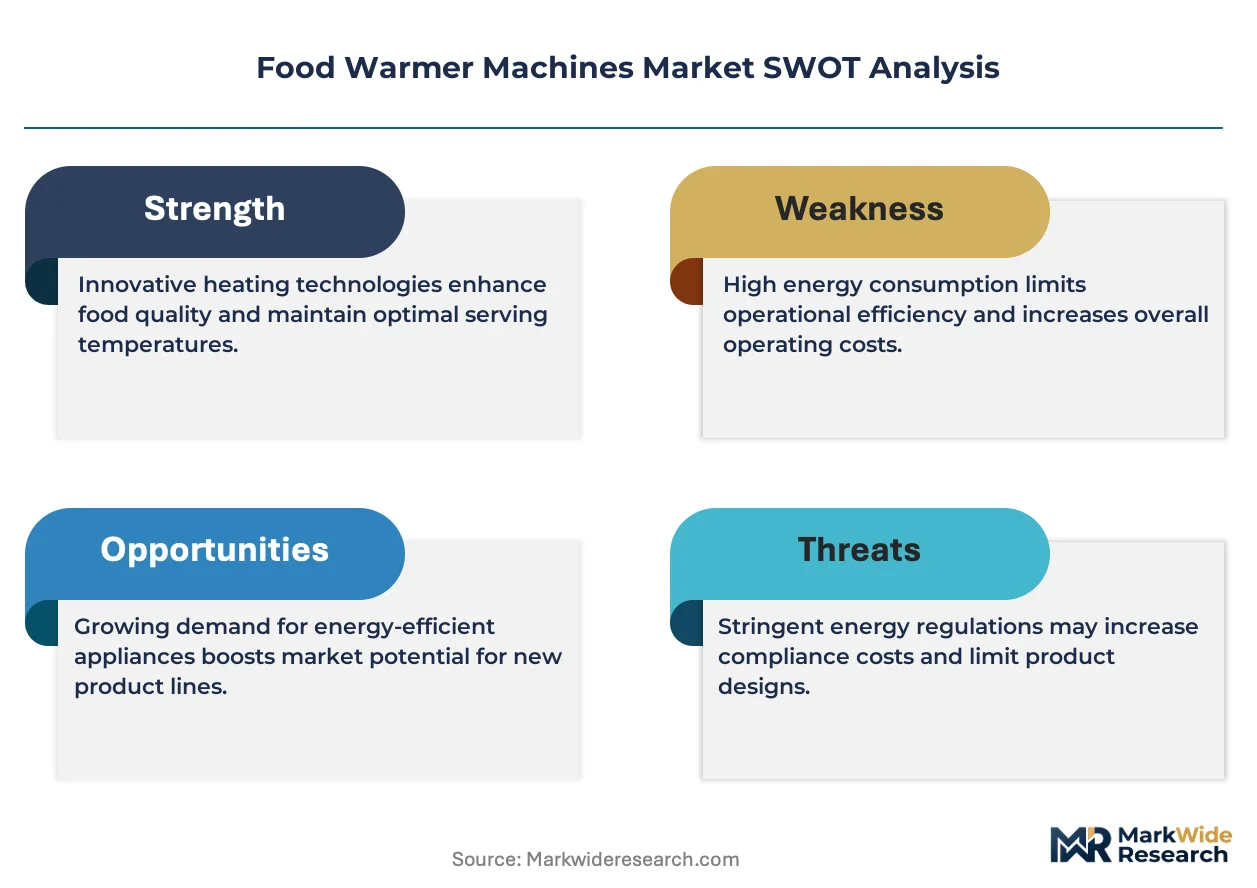
Precision digital control systems are displacing analog thermostats across commercial foodservice, driven by FDA Food Code enforcement on time-temperature documentation and cloud kitchen operators' need for remote monitoring capabilities. This shift compresses replacement cycles while elevating certification requirements for equipment vendors.
Growth Catalysts
- Delivery infrastructure expansion:Full-service restaurant chains across Southeast Asia are scaling heated holding capacity to synchronize production with third-party delivery surge windows. Cloud kitchen construction in Vietnam's Ho Chi Minh City corridor is absorbing conveyor and cabinet warmers at accelerated rates.
- Energy efficiency mandates:Japan's METI framework and EU F-Gas Regulation are narrowing equipment specifications toward induction and infrared technologies that reduce operating cost structures. Certified test lab partnerships are becoming mandatory for market access.
- Food safety digitization:The US FDA Food Code updates on time-temperature controls are pushing operators toward precision digital warmer systems with calibrated logging capabilities. State-level health department inspections favor platforms with automated documentation.
Market Restraints
- Stainless steel input volatility:The Vollrath Company's fabrication dominance and raw material concentration create lead time uncertainty for custom institutional contracts. Price instability in nickel and chromium alloys compresses margin buffers for mid-tier manufacturers.
- CE marking decoupling:Low-cost imports from non-EU origins face distribution channel exclusion under EU Machinery Directive compliance requirements. Premium European channels now require certified manufacturing footprints that Asian producers lack.
- Induction infrastructure gaps:Electrical panel upgrades and three-phase power availability limit induction warmer penetration in legacy quick-service locations. Gas-fired alternatives retain installed base protection where utility reconfiguration costs exceed equipment replacement economics.
Strategic Opportunities
- Cloud kitchen densification:India's BIS energy labeling convergence with China's MEE dual carbon goals is creating import-viable product architectures for heating element efficiency. Manufacturers with certified Asian test partnerships can capture corridor construction demand.
- Humidity injection retrofit:Low-temperature holding technology convergence with IoT moisture sensors enables shelf-life extension without dehydration. Full-service operators are piloting upgrade kits for existing cabinet installations.
- Aftermarket service unbundling:Digital control platforms enable predictive maintenance contracts separate from equipment sales. Quick-service franchise networks are consolidating vendor relationships around remote diagnostics capabilities.
Industry Challenges
- Calibration technician scarcity:FDA-mandated temperature logging requires certified service personnel that foodservice distributors lack. Training pipelines for digital control diagnostics remain underdeveloped relative to equipment deployment rates.
- Legacy system integration friction:Analog-era kitchen infrastructure lacks data ports for IoT-enabled warmer connectivity. Retrofit cabling and gateway installation costs often exceed 40% of equipment replacement value in institutional settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Warmer Machines Market |
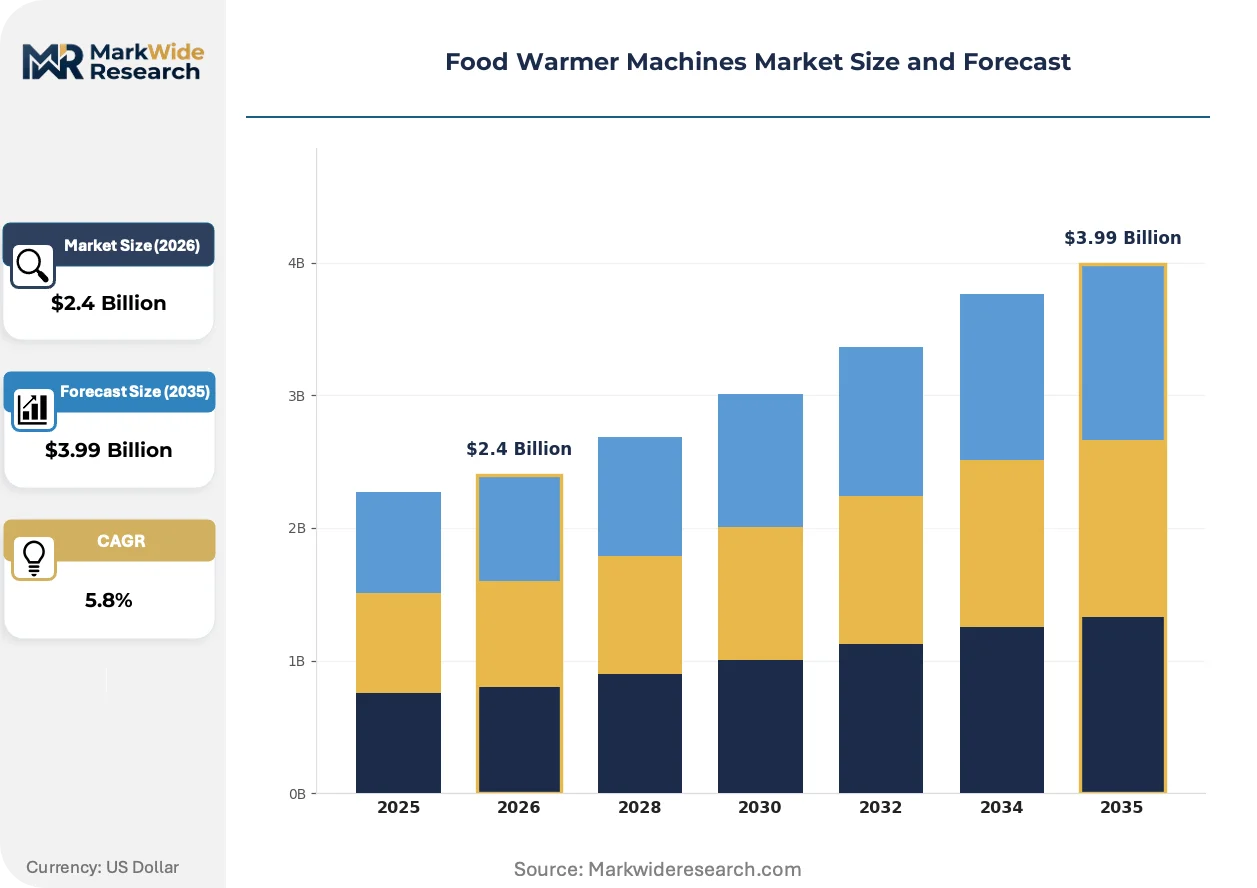
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Warmers, Gas Warmers, Infrared Warmers, Induction Warmers, Steam Warmers Heating Technology: Conduction, Convection, Radiation, Steam Heating, Water Bath Application: Restaurants, Catering Services, Hotels, Cafeterias, Food Trucks End User: Foodservice Providers, Hospitality Chains, Event Organizers, Institutional Kitchens, Retail Food Outlets |
| Companies Covered | Hatco Corporation, Alto-Shaam, Inc., The Vollrath Company, LLC, APW Wyott Foodservice Equipment Company, Duke Manufacturing Co., Cres Cor, Globe Food Equipment Company, Star Manufacturing International, Inc., Admiral Craft Equipment Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Warmer Machines Market Shifts & Advancements
Active unification of thermal management with data infrastructure is compressing the traditional separation between cooking equipment and kitchen information systems. Vendors are embedding connectivity as a standard feature rather than a premium tier.
IoT-enabled warmer platforms are unifying temperature control, humidity management, and energy monitoring into single-dashboard architectures. Cloud kitchen operators and multi-unit franchise groups are adopting these systems fastest, with deployment cycles compressing from 18-month pilot phases to 6-month rollouts. This convergence is enabling outcome-based equipment financing models that tie payments to verified energy savings and uptime performance.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based heating elements from import-eligible product lines. Manufacturers with in-house refrigerant engineering capabilities are pivoting toward natural convection and infrared alternatives. The institutional cafeteria segment faces the steepest compliance timeline, with 2027 certification deadlines forcing premature replacement of steam warmer inventories.
Consolidated procurement through national foodservice distribution networks is displacing direct manufacturer relationships for mid-scale operators. Sysco and US Foods are bundling warmer specifications into equipment allowance programs that lock in multi-year vendor commitments. This channel concentration is most visible in the US quick-service segment, where franchise development agreements now mandate approved supplier lists that exclude regional equipment specialists.
Food Warmer Machines Market Segmentation
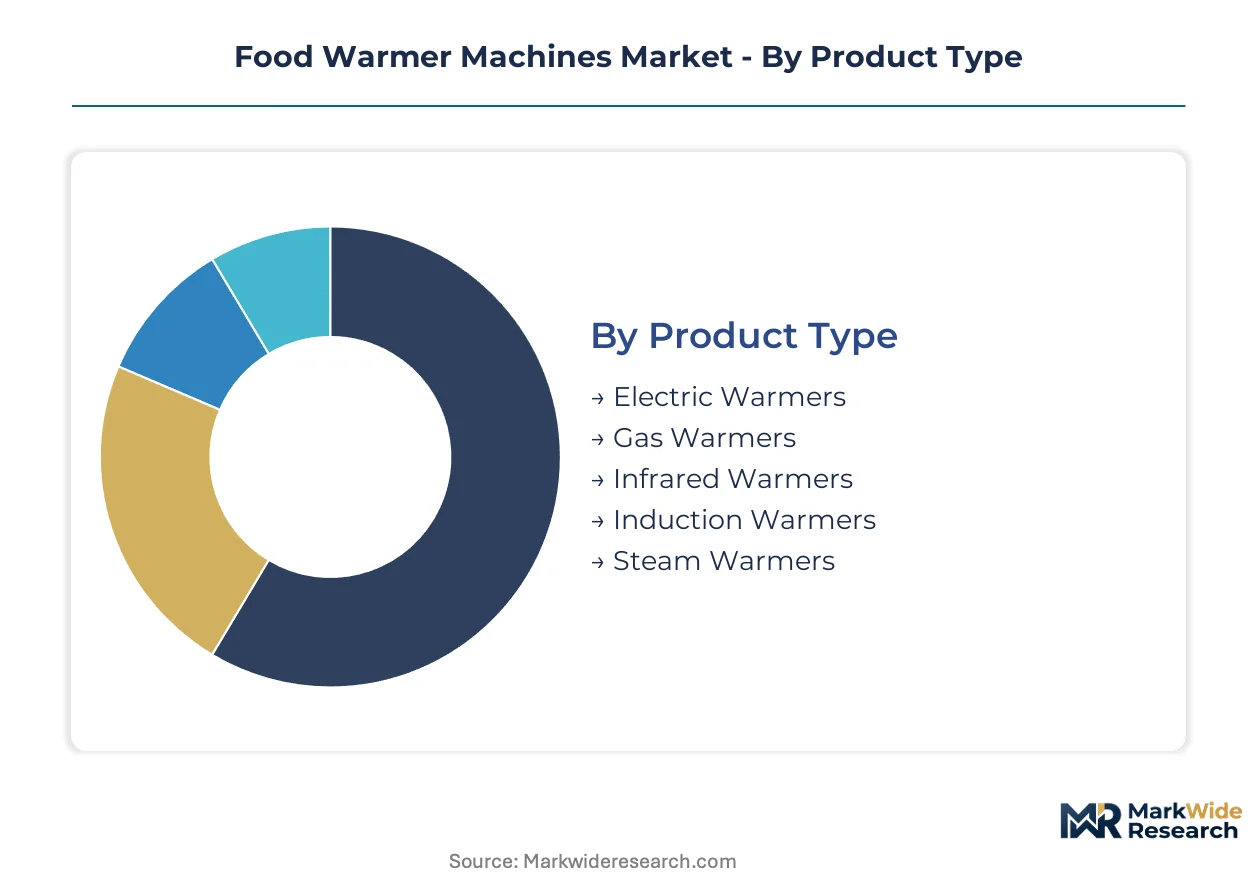
Food warmer machines fragment across multiple technical and commercial dimensions, each creating distinct specification requirements and procurement channels. Understanding these segment boundaries clarifies where technology investments concentrate and which customer types drive replacement cycles.
Product Type:
Standalone warming units dominate high-throughput independent kitchens, while embedded modules integrate into line configurations for synchronized service.
- Electric Warmers:Resistive heating elements deliver precise temperature control through calibrated thermostats or digital PID controllers. Quick-service chains across Vietnam's Ho Chi Minh City corridor specify these for cloud kitchen densification where three-phase power infrastructure supports high-density installations.
- Steam Warmers:Pressurized water reservoirs generate saturated steam that transfers heat without surface dehydration, preserving moisture in batch-held proteins and starches. Institutional cafeterias in Japan's METI-regulated environments favor these for energy efficiency compliance, though EU F-Gas Regulation phase-downs are forcing refrigerant engineering pivots toward natural convection alternatives.
- Gas Warmers:Open-flame or sealed-burner configurations provide thermal output where electrical panel upgrades prove cost-prohibitive.
- Infrared Warmers:Quartz or ceramic emitters deliver rapid surface heating without convective air movement.
- Induction Warmers:Electromagnetic field generation heats ferromagnetic vessels directly, eliminating thermal mass losses.
Electric warmers lead volumes today; induction warmers are gaining share fastest where utility reconfiguration economics favor infrastructure-light deployment.
Heating Technology:
Cost tier differentiation separates premium precision systems from standard thermal maintenance equipment across procurement specifications.
- Conduction:Direct surface-to-food contact through heated platens or shelves provides consistent thermal transfer for solid items. Budget-conscious food trucks and mobile catering operators specify these for mechanical simplicity and field repairability.
- Convection:Forced-air circulation distributes heat across cabinet volumes, reducing cold spots in multi-tray configurations. Full-service restaurant chains deploying heated holding for delivery surge windows prioritize these for temperature uniformity across batch volumes.
- Radiation:Electromagnetic energy transfer enables rapid recovery without drying.
- Steam Heating:Latent heat release from phase-change moisture preserves food quality in extended holding.
- Water Bath:Immersion or jacketed vessels maintain precise temperatures for sauce-based preparations.
Convection systems anchor the mid-market; radiation technology is climbing the fastest as buffet and display applications expand.
Application:
Volume concentration varies sharply by operational model, with synchronous cooking-service gaps determining holding capacity requirements.
- Restaurants:Full-service and quick-service operators deploy cabinet, drawer, and countertop configurations to bridge production-service timing mismatches. Southeast Asian chains expanding delivery infrastructure are scaling conveyor warmers for third-party platform synchronization.
- Catering Services:Mobile and off-premise event specialists require portable, rapid-deployment warming equipment with generator or propane compatibility.
- Hotels:Breakfast buffet and banquet operations demand display-oriented warming with humidity control for extended holding periods.
- Cafeterias:Institutional feeding operations prioritize batch capacity and food safety documentation.
- Food Trucks:Space-constrained mobile kitchens specify compact, multi-fuel warming solutions.
Restaurant applications dominate current procurement; catering services are expanding most quickly as off-premise dining normalizes.
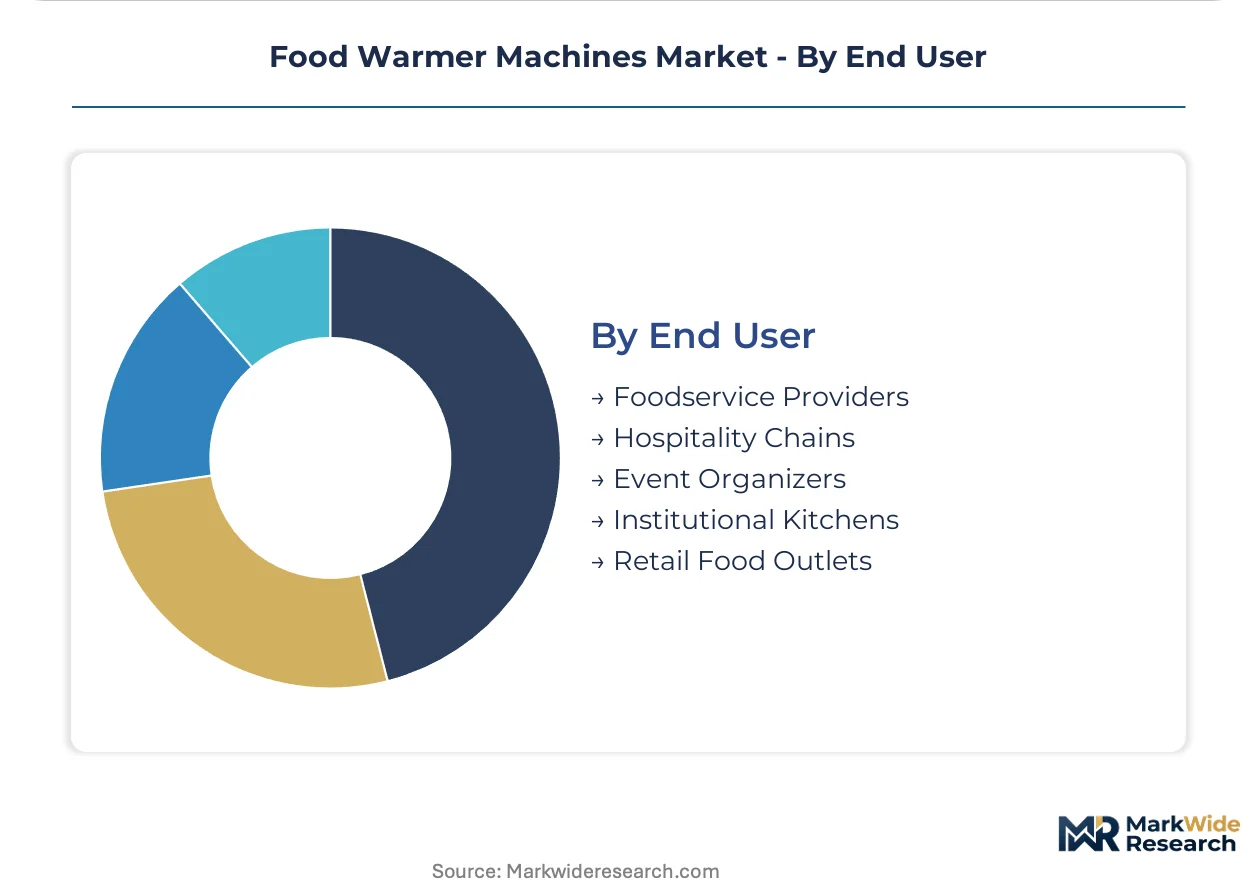
End User:
Customer type determines specification complexity, with consolidated procurement power reshaping vendor relationships across scale tiers.
- Foodservice Providers:Independent operators and multi-unit franchisees balance equipment cost against operating efficiency. US FDA Food Code compliance requirements are pushing these users toward digital logging platforms with automated documentation.
- Hospitality Chains:National and regional hotel groups leverage centralized procurement through foodservice distribution networks. Sysco and US Foods equipment allowance programs are consolidating vendor specifications across franchise development agreements.
- Event Organizers:Temporary and seasonal demand patterns favor rental and lease-based equipment access.
- Institutional Kitchens:Schools, hospitals, and correctional facilities mandate certified safety features and extended warranty terms.
- Retail Food Outlets:Convenience stores and grab-and-go markets integrate warming into broader foodservice equipment portfolios.
Foodservice providers account for the largest installed base; hospitality chains are driving the steepest specification upgrades through consolidated purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing workforces in Wisconsin, Wisconsin-based fabrication clusters, and precision engineering talent in Germany anchor production capacity for thermal holding equipment. These concentrations shape regional supply capabilities and influence specification standards across export markets.
United States
Full-service restaurant chains and cloud kitchen operators drive equipment procurement across Texas, California, and the Southeast corridor. FDA Food Code enforcement on time-temperature documentation mandates digital control platforms with calibrated logging. Wisconsin hosts concentrated stainless fabrication capacity serving North American institutional and commercial channels.
Germany
EU Ecodesign requirements and F-Gas Regulation phase-downs narrow eligible equipment specifications toward energy-efficient architectures. CE marking under the EU Machinery Directive decouples low-cost imports from premium distribution channels. Industrial equipment specialists in Baden-Württemberg and North Rhine-Westphalia anchor precision manufacturing for continental foodservice.
Japan
METI framework efficiency standards tighten operating cost structures for institutional cafeteria operators. Induction and infrared technologies gain specification share where energy mandates converge with three-phase power availability. Tokyo-Osaka corridor concentration of quick-service chains drives replacement cycles for precision digital systems.
Vietnam
Cloud kitchen construction in the Ho Chi Minh City corridor absorbs conveyor and cabinet warmers at accelerated rates. Full-service restaurant chains expand heated holding capacity to synchronize production with third-party delivery surge windows. Southeast Asian delivery infrastructure expansion concentrates procurement in southern industrial zones.
China
Dual carbon goals under MEE and BIS energy labeling convergence determine import-viable heating element efficiency thresholds. Domestic manufacturers with certified test lab partnerships capture corridor construction demand. Yangtze River Delta and Pearl River Delta clusters supply regional cloud kitchen densification with standardized electric warming equipment.
Food Warmer Machines Market Competitive Landscape
The competitive structure tilts toward vertically integrated fabricators with captive stainless steel processing and digital control engineering capabilities. Mid-tier specialists compete on lead time compression for custom institutional contracts, while scale-driven manufacturers anchor North American distribution through foodservice allowance programs. Strategic moves center on test lab certification partnerships for regulatory access and predictive maintenance service unbundling from equipment sales.
Among North American-based manufacturers, Hatco Corporation, Alto-Shaam, Inc., and The Vollrath Company, LLC occupy positions across distinct competitive vectors. Hatco exemplifies vertical manufacturing footprint control sustaining price stability. Alto-Shaam represents low-temperature holding technology specialization. Vollrath anchors stainless fabrication capacity dominance enabling custom contract lead time management. These three manufacturers illustrate how geographic concentration, process control, and specification engineering separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Hatco Corporation |
| Alto-Shaam, Inc. |
| The Vollrath Company, LLC |
| APW Wyott Foodservice Equipment Company |
| Duke Manufacturing Co. |
| Cres Cor |
| Globe Food Equipment Company |
| Star Manufacturing International, Inc. |
| Admiral Craft Equipment Corp. |
| Others |
Supply & Pricing Matrix
US FDA Food Code mandates for calibrated temperature logging are forcing operators toward precision digital platforms, compelling manufacturers to absorb certification costs and recalibrate pricing models around bundled service contracts. This specification shift concentrates purchasing power among distributors capable of underwriting compliance documentation.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning. Equipment vendors increasingly separate hardware transactions from predictive maintenance subscriptions, with digital control platforms enabling outcome-based financing tied to uptime performance. Price differentiation hinges on CE marking tier and remote diagnostics capability, with premium European channels commanding substantial premiums over non-certified alternatives. Cost compression in the mid-tier intensifies as stainless steel input volatility erodes margin buffers, while institutional buyers demonstrate lowest price sensitivity due to mandated safety specifications.
Supply Chain Analysis
Local-content-rule momentum in India's BIS framework and China's MEE dual carbon goals is reshaping sourcing toward certified Asian test partnerships. Manufacturing gravity centers on Wisconsin-based fabrication clusters, German precision engineering hubs in Baden-Württemberg, and Yangtze River Delta production zones. Supply chains draw from nickel and chromium alloy feedstocks, digital control component ecosystems, and refrigerant engineering capabilities. Single-source vulnerability concentrates in stainless steel processing capacity controlled by dominant fabricators. Distribution runs through national foodservice allowance programs that bundle specifications into multi-year vendor commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA Food Code enforcement on time-temperature documentation driving replacement cycles and elevating certification barriers for equipment vendors.
For Market Incumbents: Anticipate margin compression from consolidated procurement through Sysco and US Foods equipment allowance programs by deepening captive stainless fabrication capacity and accelerating predictive maintenance service unbundling. Prioritize CE marking investment to defend European channel access against low-cost import exclusion under Machinery Directive enforcement. For New Entrants and Emerging Players: Launch via cloud kitchen operator direct relationships in Vietnam's Ho Chi Minh City corridor, where delivery infrastructure expansion outpaces established vendor coverage. Target humidity injection retrofit kits for existing cabinet installations as the most penetrable white space, leveraging IoT moisture sensor convergence with low-temperature holding technology. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated fabricators possessing captive test lab partnerships for regulatory access across multiple jurisdictions. Five-to-ten year viability favors manufacturers with backward integration into stainless processing and digital control engineering. Watch calibration technician training pipeline development as the inflection signal for service revenue scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Test Lab Certification Partnership | Unlocks EU Machinery Directive compliance and CE marking eligibility for Asian manufacturing footprints. |
| Predictive Maintenance Unbundling | Enables recurring revenue streams tied to FDA-mandated temperature logging and remote diagnostics capabilities. |
| Humidity Injection Retrofit Development | Captures shelf-life extension demand from full-service operators piloting IoT-enabled upgrade kits. |
| Stainless Fabrication Capacity Expansion | Secures lead time control for custom institutional contracts amid raw material volatility. |
| Induction Technology Platform Launch | Addresses METI framework efficiency mandates and EU F-Gas Regulation phase-down timelines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with foodservice equipment procurement directors, cloud kitchen operations managers, institutional cafeteria maintenance heads, and aftermarket service technicians. Secondary validation draws from FDA Food Code documentation, EU Machinery Directive regulatory filings, METI efficiency standard publications, and customs trade data. Bottom-up equipment shipment analysis triangulates against top-down foodservice construction spending patterns.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include product type, heating technology, application, and end-user procurement scale. CAGRs derive from regression analysis against regulatory milestone timelines and cloud kitchen construction permits. Industry-specific forecast inputs incorporate three-phase power infrastructure availability and certified technician training pipeline development.
Several conditions sit outside the modeled scope, including macroeconomic recession scenarios, abrupt tariff regime changes, and technological substitution beyond induction and infrared platforms. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Hospital Foodservice Equipment Market