
 Africa Foodservice Market | 2026-2036
Africa Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Foodservice Market Outlook
Nigeria's Lagos-Ibadan corridor is reconfiguring supply chain logistics for foodservice distribution across West Africa. Famous Brands Limited leverages its vertically integrated manufacturing and franchise network to sustain market presence across multiple African countries. Spur Corporation Limited anchors its competitive position through family-oriented dine-in concepts with localized menu adaptation. Nando's Group Holdings differentiates through peri-peri chicken specialization and controlled supply chain sourcing from Southern Africa.
Foodservice encompasses the commercial preparation, service, and delivery of meals outside residential settings, operating through establishments ranging from centralized kitchens producing standardized portions to decentralized quick-service outlets with throughput rates exceeding 300 orders per hour. The sector serves institutional feeding, commercial hospitality, and consumer convenience needs across urban and peri-urban populations. Quick Service Restaurants capture the dominant volume share due to affordability alignment with mass-market purchasing power and operational scalability in high-footfall locations. Full-Service Restaurants concentrate margin pools in premium urban centers and business districts where experiential dining commands higher per-cover spending. Delivery channels are expanding fastest as third-party logistics platforms and proprietary rider networks reduce friction in last-mile food distribution across congested metropolitan areas.
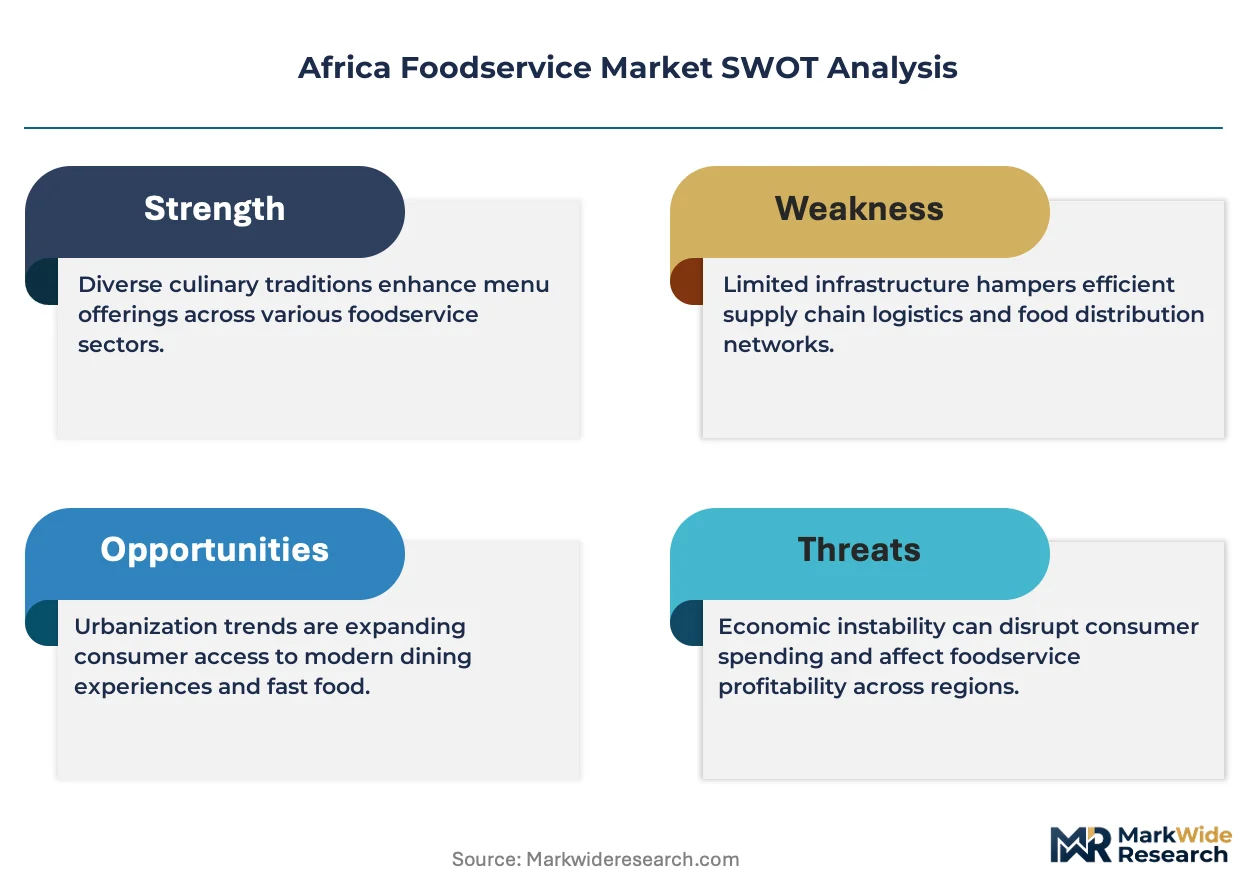
FSSC 22000 certification requirements in South Africa, Nigeria's NAFDAC food establishment registration protocols, and Kenya's Kenya Bureau of Standards food hygiene regulations collectively elevate compliance costs while creating barriers against informal competitors. These frameworks mandate HACCP implementation, traceability documentation, and periodic facility audits that reshape capital deployment toward standardized kitchen infrastructure. Stakeholders must monitor regulatory harmonization progress across the African Continental Free Trade Area to anticipate cross-border operational expansion requirements and preempt compliance fragmentation.
Market Dynamics
Quick service restaurant chains are compressing order fulfillment cycles through centralized kitchen automation and proprietary rider networks, restructuring how foodservice operators deploy capital across African metropolitan corridors.
Growth Catalysts
- FSSC 22000 Certification:South Africa's mandatory food safety framework is accelerating HACCP adoption across commercial kitchens, forcing standardized infrastructure investment that elevates operational quality thresholds.
- Lagos-Ibadan Corridor Concentration:Nigeria's southwestern urban cluster is aggregating delivery demand density, enabling third-party logistics platforms to achieve route economics previously unavailable in West African food distribution.
- Peri-Urban Institutional Feeding:Corporate cafeteria outsourcing and school meal programs are expanding addressable demand beyond traditional restaurant formats into centralized production contracts.
Market Restraints
- Import-Dependent Equipment Supply:Cold chain infrastructure and commercial kitchen fabrication rely on European and Asian manufacturing origins, exposing operators to currency volatility and extended replacement timelines.
- NAFDAC Registration Friction:Nigeria's food establishment protocols impose multi-month approval windows for new facility openings, constraining rapid geographic expansion by standardized chains.
- Informal Sector Price Floors:Unregistered street vendors and unlicensed kitchens operate outside compliance cost structures, creating persistent margin compression for formal operators in mass-market segments.
Strategic Opportunities
- Kenya Bureau of Standards Alignment:East African regulatory harmonization under AfCFTA protocols is creating cross-border operational templates for chains with Nairobi manufacturing anchors.
- Dark Kitchen Proliferation:Delivery-only production facilities without dine-in footprints are reducing real estate intensity and enabling rapid market entry in secondary cities.
- Mobile Payment Integration:Convergence of USSD interfaces and QR-code wallets is collapsing payment friction for unbanked consumer segments previously excluded from formal foodservice.
Industry Challenges
- Certified Food Safety Officer Scarcity:HACCP implementation requires trained personnel that outstrip supply in markets like Ghana and Ethiopia, extending facility commissioning timelines.
- Legacy POS Integration:Inventory management and kitchen display systems from established vendors resist API connectivity with emerging delivery platform aggregators, forcing middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Foodservice Market |
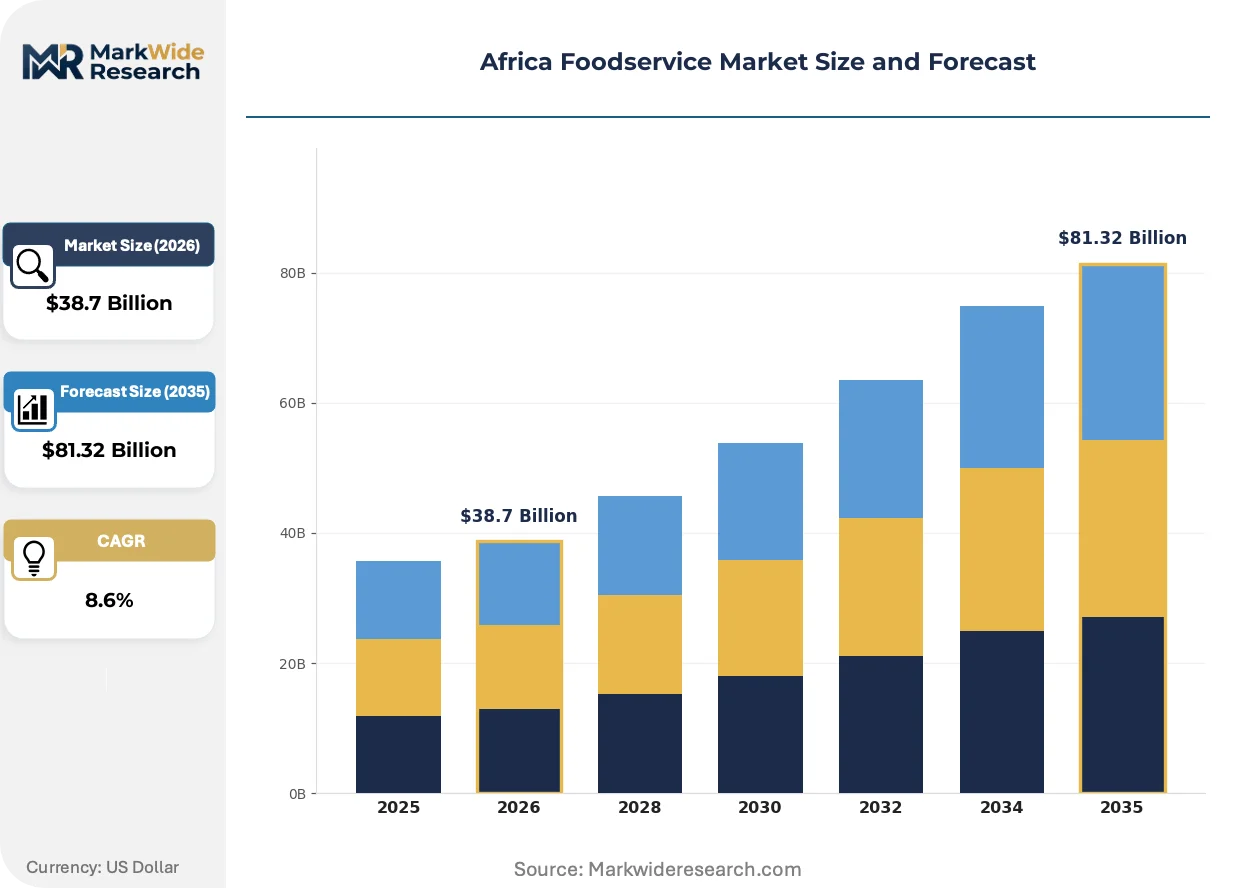
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafés, Buffets Customer Type: Corporate Clients, Individual Consumers, Institutions, Event Planners Food Type: Vegetarian, Fast Food, Ethnic Cuisine, Organic Distribution Channel: Dine-in, Delivery, Takeaway, Catering |
| Companies Covered | Famous Brands Limited, McDonald's Corporation, Restaurant Brands International, Yum! Brands Inc., Nando's Group Holdings, Spur Corporation Limited, Domino's Pizza Inc., Chicken Licken, Burger King, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Foodservice Market Strategic Shifts
Automation in kitchen workflows and last-mile logistics is compressing the traditional tradeoff between throughput volume and product consistency that has constrained African foodservice scaling.
Cloud-based kitchen management systems are collapsing the coordination costs between centralized production facilities and dispersed delivery endpoints. Quick service operators in Johannesburg and Cape Town are deploying these platforms to synchronize inventory across thirty-plus locations in real time. The technology is collapsing the minimum viable scale for multi-unit operational control, enabling mid-cap chains to approximate enterprise-grade coordination without dedicated IT infrastructure.
Kenya's Bureau of Standards food hygiene regulations are mandating digital traceability documentation for all licensed establishments, forcing paper-based operators into compliance investments. The industrial consequence is accelerated vendor consolidation as smaller kitchens lack capital for integrated logging systems. Full-service restaurants in Nairobi's Westlands district are most affected, responding through collective procurement consortia to share certification and auditing costs.
Consumption patterns are fragmenting across occasion-based need states rather than traditional daypart structures. The breakfast-lunch-dinner segmentation is dissolving as all-day snacking and meal-replacement occasions expand share, particularly among urban professionals aged 25-40. This shift is most visible in Lagos, where delivery platforms report afternoon and late-evening order spikes that defy conventional restaurant operating hours, forcing operators to reconfigure labor scheduling and menu availability windows.
Africa Foodservice Market Segmentation
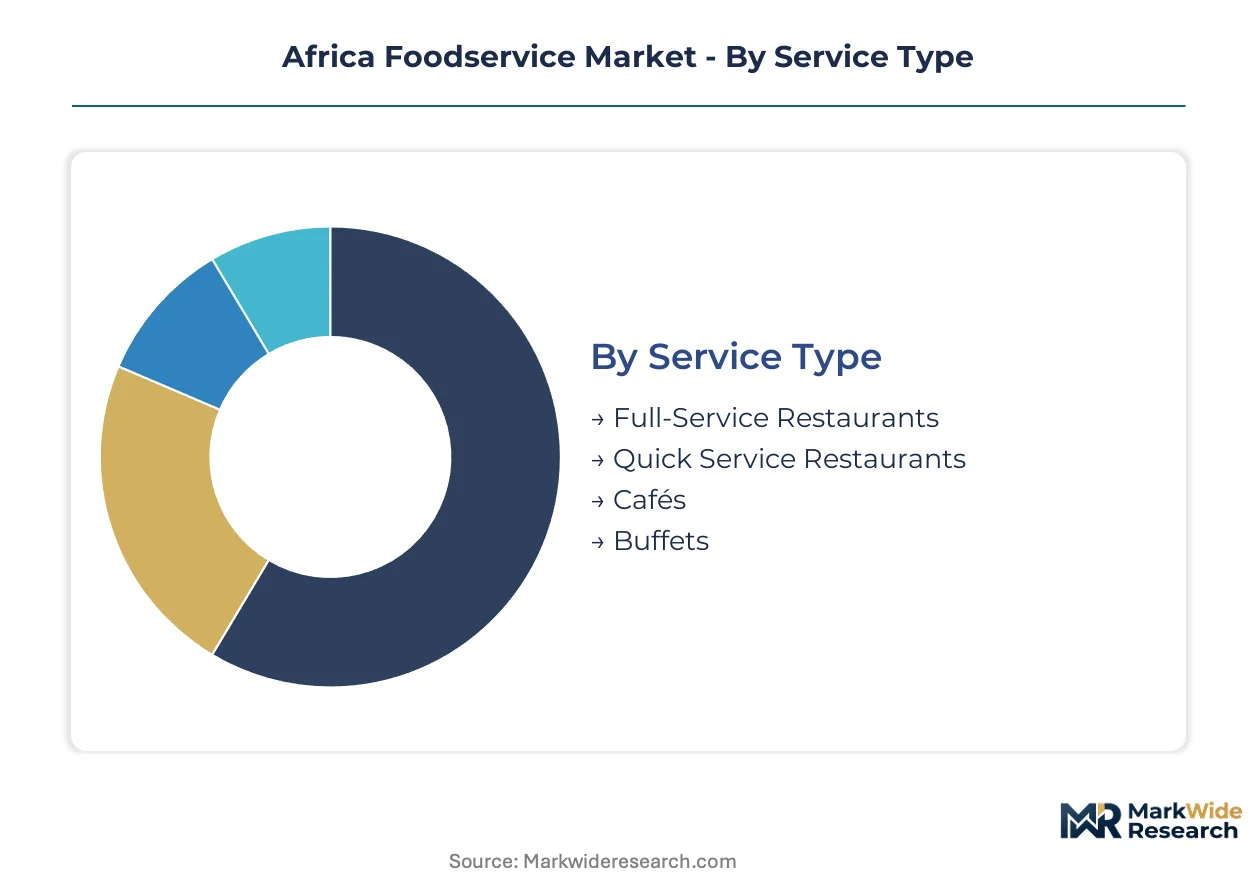
Foodservice segmentation across Africa reveals how consumption occasions fragment across income tiers, urban density gradients, and regulatory compliance thresholds. Understanding these divides enables operators to match capital deployment with addressable demand pools.
Service Type:
Service formats span experiential dine-in to high-throughput production, each demanding distinct real estate footprints and labor skill profiles.
- Full-Service Restaurants:Table-service establishments with extended meal durations and higher per-cover spending. Demand concentrates in Johannesburg's Sandton district and Lagos's Victoria Island, where corporate entertainment and premium family occasions sustain cover charges above mass-market tiers. FSSC 22000 certification requirements in South Africa elevate operational barriers.
- Quick Service Restaurants:Limited-service formats with standardized menus and throughput rates exceeding 300 orders per hour. Urban corridors in Nairobi and Accra are absorbing the fastest expansion as young professionals prioritize convenience and predictable pricing over experiential dining.
- Cafés:Beverage-forward formats with light meal accompaniment, targeting remote work and social meeting occasions.
- Buffets:Self-service formats with fixed pricing, concentrated in hotel foodservice and institutional catering contracts.
The dominant share belongs to Quick Service Restaurants, while Full-Service Restaurants command the highest margin pools per transaction.
Customer Type:
Customer economics vary sharply across contract stability, price sensitivity, and volume predictability.
- Corporate Clients:B2B contracts for staff cafeterias, executive dining, and event catering with negotiated annual terms. Mining sector operations in Zambia's Copperbelt and Ghana's Ashanti region anchor institutional demand with captive workforce feeding requirements.
- Individual Consumers:Discretionary spenders making occasion-based purchase decisions. Mobile payment penetration in Kenya and Nigeria is collapsing friction for this segment previously excluded by cash-only informal alternatives.
- Institutions:Schools, hospitals, and government facilities outsourcing meal production to specialized operators.
- Event Planners:Occasion-driven demand for weddings, conferences, and cultural celebrations with high per-event revenue concentration.
Individual Consumers generate the highest transaction frequency, while Corporate Clients deliver the most predictable revenue baselines.
Food Type:
Menu positioning responds to religious dietary requirements, health consciousness gradients, and diaspora-driven authenticity demands.
- Fast Food:Standardized, speed-optimized offerings with global brand recognition and localized protein adaptations. Chains are compressing supply chains through peri-urban production hubs in Egypt's 6th of October City and Morocco's Casablanca outskirts.
- Ethnic Cuisine:Regionally specific preparations leveraging diaspora networks and imported ingredient sourcing. West African jollof variants and East African injera-based formats command premium positioning in urban centers with expatriate populations.
- Vegetarian:Plant-forward menus responding to religious observance and emerging health positioning.
- Organic:Certified ingredient sourcing with traceability documentation, currently limited to premium urban enclaves.
Fast Food captures volume leadership, though Ethnic Cuisine is climbing fastest as diaspora populations expand and authenticity signaling gains commercial value.
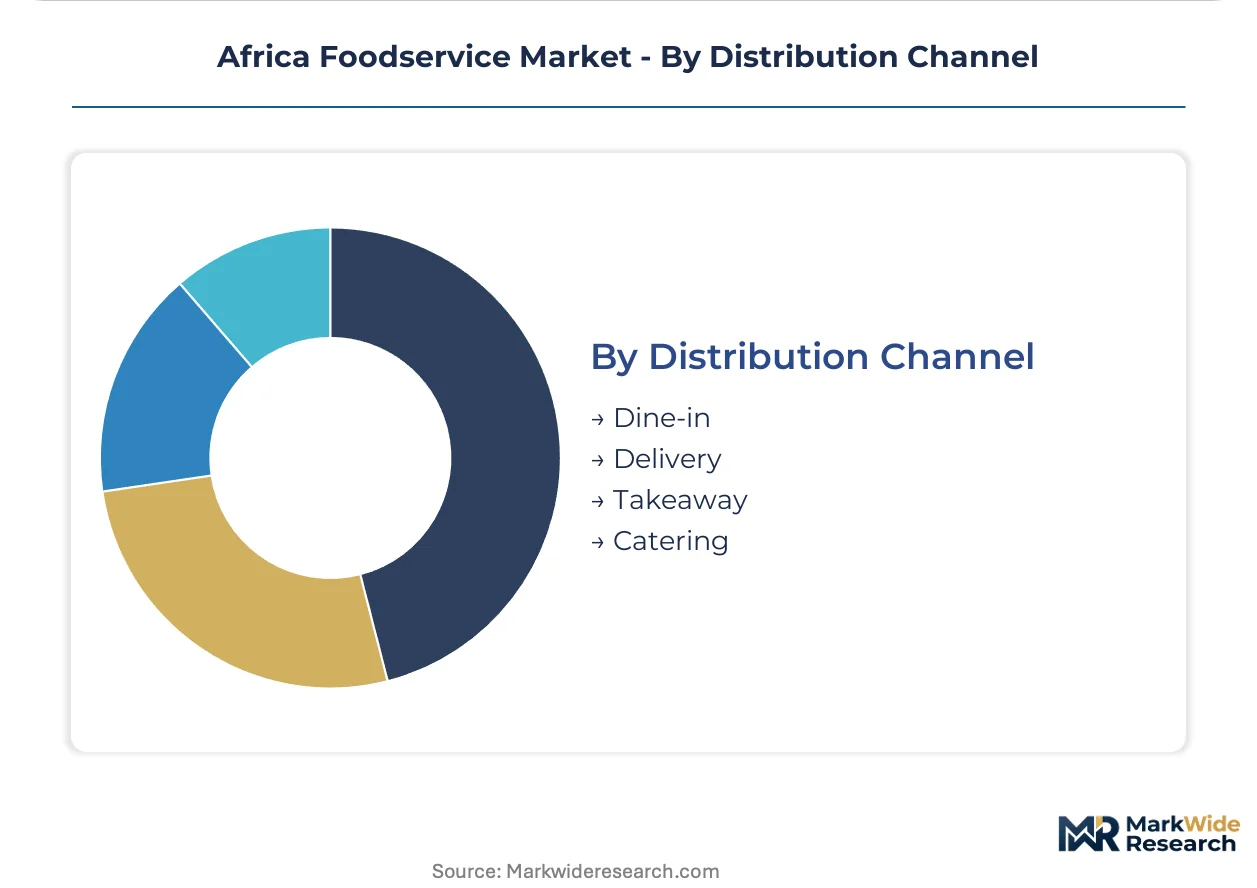
Distribution Channel:
Channel mix determines real estate intensity, labor scheduling, and technology infrastructure requirements.
- Delivery:Third-party platform and proprietary rider networks connecting kitchens to residential and office endpoints. Lagos-Ibadan corridor density is enabling route economics previously unavailable in West African logistics, with afternoon and late-evening order spikes reconfiguring traditional daypart structures.
- Dine-in:On-premise consumption with experiential and service components. Full-service operators in Nairobi's Westlands district are consolidating through collective procurement to share Kenya Bureau of Standards compliance costs.
- Takeaway:Counter-service collection without on-premise consumption, common in Quick Service formats.
- Catering:Off-premise production for events and institutional contracts with advance scheduling and volume concentration.
Delivery is expanding most quickly, while Dine-in retains the highest revenue per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa consumes foodservice through formal quick-service channels at rates exceeding West African markets, where informal street vendors still capture significant share despite regulatory pressure.
South Africa
Johannesburg's Sandton district and Cape Town's Atlantic Seaboard concentrate premium full-service demand driven by corporate entertainment budgets. FSSC 22000 certification mandates from the Department of Health reshape capital deployment toward standardized kitchen infrastructure. Durban's manufacturing corridor anchors Famous Brands Limited's vertically integrated production network supplying franchise locations across multiple provinces.
Nigeria
The Lagos-Ibadan corridor aggregates delivery demand density sufficient to sustain third-party logistics route economics previously unavailable in West Africa. NAFDAC food establishment registration protocols impose multi-month approval windows that constrain rapid chain expansion. Victoria Island and Lekki Phase 1 sub-markets command per-cover spending premiums that subsidize mass-market format development elsewhere.
Kenya
Nairobi's Westlands district hosts full-service restaurant consolidation through collective procurement consortia sharing Kenya Bureau of Standards compliance costs. Mobile payment penetration via M-Pesa integration collapses friction for unbanked consumer segments. The Konza Technopolis corridor is attracting centralized kitchen investments targeting institutional feeding contracts.
Egypt
Cairo's 6th of October City peri-urban manufacturing hubs compress supply chains for quick-service chains serving Greater Cairo's twenty million population. The country's national food safety regulator mandates HACCP documentation that accelerates vendor consolidation. Alexandria's Mediterranean corridor is reconfiguring as a distribution anchor for North African cross-border expansion.
Ghana
Accra's Airport City and Cantonments districts concentrate expatriate-driven demand for ethnic cuisine formats. The country's national standards authority food hygiene protocols create compliance barriers against informal competitors. Tema's industrial zone is emerging as a production hub for quick-service supply chains serving the broader West African sub-region.
Africa Foodservice Market Competitive Environment
Capability concentration sits with integrated manufacturing-and-franchise operators; scale advantage sits with global quick-service brands with standardized format replication. The vendor base spans three tiers: global chains with proprietary supply chains, regional African operators with manufacturing integration, and single-market specialists with localized menu depth. Competitive moves center on backward integration into captive supply and dark kitchen proliferation reducing real estate intensity.
Within the regional manufacturing-integrated tier, Famous Brands Limited and Spur Corporation Limited exemplify South Africa-anchored operators combining production facilities with franchise network control. Nando's Group Holdings occupies a specialization position around peri-peri chicken formats with Southern African supply chain sourcing. Global quick-service chains including McDonald's Corporation, Yum! Brands Inc., and Restaurant Brands International leverage format standardization and marketing scale across multiple African markets without equivalent manufacturing depth.
| Leading Market Players |
|---|
| Famous Brands Limited |
| McDonald's Corporation |
| Restaurant Brands International |
| Yum! Brands Inc. |
| Nando's Group Holdings |
| Spur Corporation Limited |
| Domino's Pizza Inc. |
| Chicken Licken |
| Burger King |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South Africa's certified cold chain infrastructure is forcing operators into premium equipment sourcing from European manufacturers, compressing margins while elevating compliance-driven pricing tiers across formal foodservice channels. This utilization squeeze simultaneously limits supplier bargaining power and accelerates cost pass-through to corporate and institutional buyers.
Pricing Analysis
Long-term offtake contracts between quick-service chains and peri-urban production facilities dominate pricing structures, with Famous Brands Limited and Spur Corporation Limited anchoring volume commitments that secure input cost stability. Price differentiation hinges on FSSC 22000 certification tier and geographic delivery radius, with Johannesburg Sandton district operators commanding premiums over peri-urban formats. Cost compression in mass-market segments is intensifying because informal street vendors operate outside compliance cost structures. Corporate cafeteria contracts exhibit lowest price sensitivity due to captive workforce feeding requirements, while individual delivery consumers in Lagos show highest elasticity to menu price adjustments.
Supply Chain Analysis
Upstream feedstock for commercial kitchen equipment and cold chain infrastructure draws from China, Germany, and Italy, with stainless steel fabrication and refrigeration compressors representing concentrated import dependencies. African operators source poultry and vegetable inputs from South Africa's KwaZulu-Natal agricultural corridor and Egypt's Nile Delta farming zones. Single-source vulnerability sits with European HACCP-certified equipment suppliers exposed to euro currency volatility. Distribution runs through Durban's manufacturing corridor for southern African markets and Tema's industrial zone for West African logistics, with third-party platform aggregators collapsing last-mile friction in Lagos-Ibadan corridor density zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained HACCP personnel scarcity across Ghana and Ethiopia extends facility commissioning timelines, creating competitive moats for operators with established certification pipelines and in-house training academies.
For Market Incumbents: Insulate margin pools by backward integration into captive poultry processing and peri-urban vegetable cultivation, reducing exposure to agricultural input volatility. Lock in FSSC 22000 certification pipelines through dedicated training academies before regulatory harmonization across AfCFTA protocols raises compliance barriers. Channel control through proprietary rider networks in Lagos-Ibadan corridor density zones limits third-party platform commission erosion. For New Entrants and Emerging Players: Build out dark kitchen footprints in secondary cities like Ibadan, Accra, and Mombasa where real estate intensity remains below Johannesburg and Lagos thresholds. Target institutional feeding contracts in Kenya's Konza Technopolis corridor and Zambia's Copperbelt mining operations, where corporate outsourcing trends accelerate addressable demand. Go-to-market leverage rests on mobile payment integration via M-Pesa or USSD interfaces that collapse friction for unbanked consumer segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturing-and-franchise operators with captive supply chains spanning multiple provinces. Long-term viability across the analysis window favors targets with Nairobi or Johannesburg manufacturing anchors capable of cross-border format replication under AfCFTA regulatory alignment. The signal to watch is Kenya Bureau of Standards digital traceability mandate enforcement pace, which will accelerate vendor consolidation and create acquisition opportunities among paper-based compliance laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Proliferation | Reduces real estate intensity and enables rapid entry in Ibadan and Mombasa secondary markets. |
| Backward Integration into Poultry | Cuts input cost volatility for Nando's Group Holdings and Spur Corporation Limited supply chains. |
| FSSC 22000 Certification Pipeline | Creates compliance moats against informal competitors before AfCFTA harmonization raises barriers. |
| Mobile Payment Platform Integration | Collapses friction for unbanked segments via M-Pesa or USSD wallet convergence in Kenya and Nigeria. |
| Cross-Border Manufacturing Anchor | Positions Famous Brands Limited for East African expansion under Kenya Bureau of Standards alignment. |
Study Parameters
Operator-level perspectives from quick-service franchise operations managers, full-service restaurant procurement directors, third-party logistics platform executives, and Kenya Bureau of Standards compliance officers anchored the qualitative base. Secondary validation drew from NAFDAC food establishment registration databases, South African Department of Health FSSC 22000 audit records, AfCFTA regulatory harmonization progress reports, and customs import data for commercial kitchen equipment. Bottom-up demand modeling across service type, customer type, and distribution channel segments was triangulated against top-down macroeconomic consumption indicators.
Scenario-bracketing around regulatory enforcement pace, currency volatility bands, and urbanization trajectory variations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included service format, customer contract stability, food type positioning, and distribution channel technology intensity. CAGRs were derived from installed base growth rates, same-store sales trajectories, and delivery platform order volume expansion. Industry-specific inputs incorporated Lagos-Ibadan corridor logistics density metrics and peri-urban institutional feeding contract award pipelines.
Stress conditions across naira and rand exchange rate volatility, NAFDAC registration timeline extensions, and informal sector competitive intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about AfCFTA regulatory harmonization progress and mobile payment penetration curves. Cross-checking against South African Restaurant Association membership growth and Nigerian Logistics and Supply Chain Industry Association delivery volume benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Lunch Takeout Market
Food Service
Haute Cuisine Market
Food Service
Japan Foodservice Market
Food Service
Catering Food Warmers Market
Food Service
Contract Blending Services Market
Food Service
Commercial Steam Table Market
Food Service
Europe Food Service Market
Food Service
India Foodservice Market
Food Service
North America Food Service Disposable Market
Food Service
Malaysia Food Service Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
GCC Online Grocery Market
Food Service
Steam Stew Pot Market