
 Bacon Slicers Market | 2026-2036
Bacon Slicers Market Size, Share, and Industry Trends Forecast 2026-2036
Bacon Slicers Market Outlook
Stainless steel is recalibrating bacon slicer economics as processors abandon aluminum frames to meet stricter sanitation audits. Weber Maschinenbau leverages its Osnabrück engineering heritage to dominate precision blade systems for high-throughput operations. Marel sustains R&D intensity across automated portioning lines that integrate slicing with downstream packaging. TREIF Maschinenbau specializes in modular platforms that let mid-size processors scale capacity without full line replacement.
A bacon slicer is a food processing machine that employs rotating or reciprocating blades to cut pork belly into uniform strips or rashers with thickness tolerances typically between 0.5 mm and 5.0 mm, designed for continuous operation in commercial and industrial settings. Electric slicers lead the product type category by installed base, though vertical slicers represent the fastest-growing configuration as processors seek gravity-fed designs that reduce mechanical complexity and improve yield recovery. Food processing units anchor end-user demand by volume, while adjustable thickness features command the widest margin pool as buyers prioritize recipe flexibility across breakfast, sandwich, and retail-pack formats.
NSF International standards govern equipment sanitation in North American foodservice, while EU Regulation 1935/2004 frames food contact material compliance across European installations. FDA food safety modernization requirements shape U.S. processor procurement timelines, pushing buyers toward validated clean-in-place designs. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking will reshape stainless steel sourcing costs and equipment lifecycle accounting.
Market Dynamics
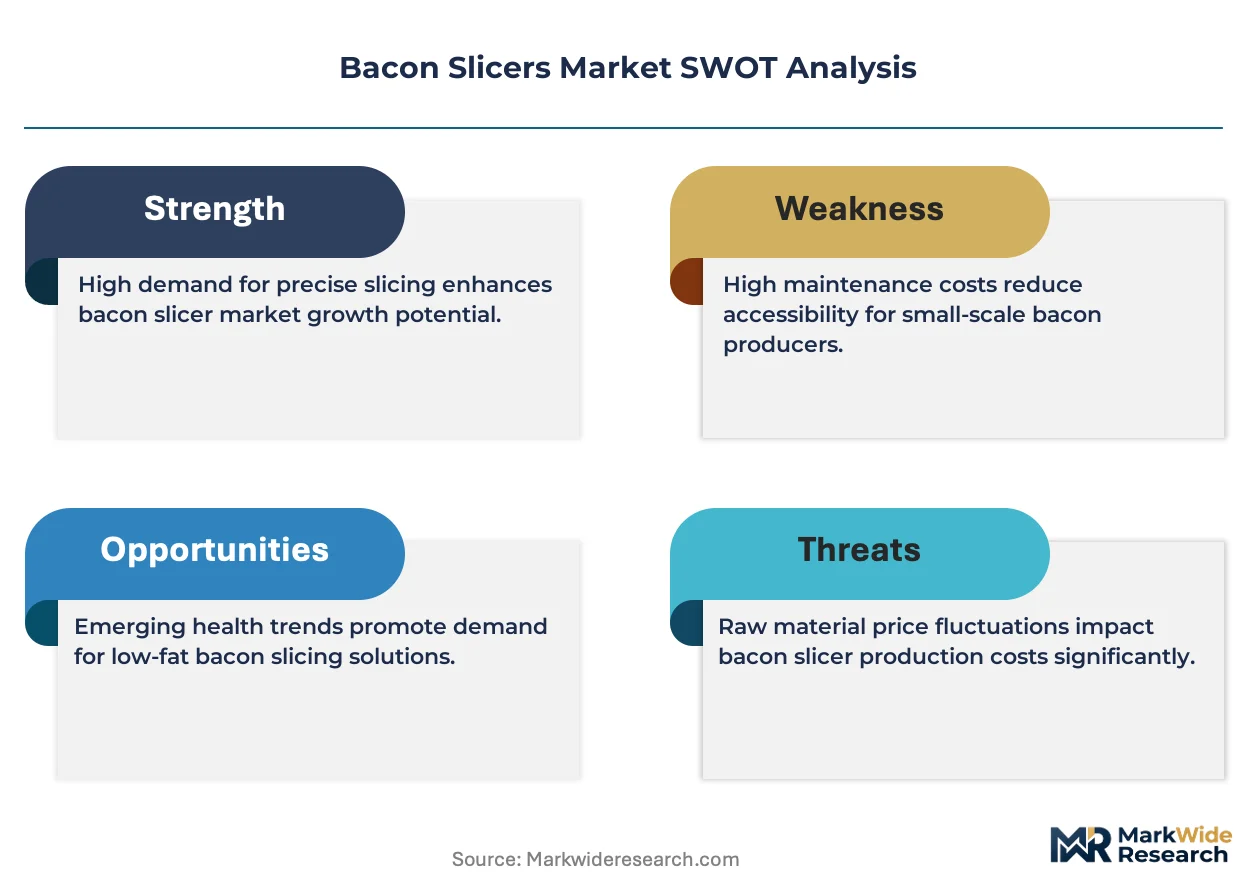
Stainless steel hygiene mandates from NSF International and EU food contact regulations are forcing equipment replacement cycles across commercial kitchens and food processing plants. Processors face immediate capital deployment decisions as aluminum-frame equipment loses certification eligibility.
Growth Catalysts
- Automated portioning integration:Food processing units are demanding slicer lines that feed directly into vacuum packaging and labeling systems, eliminating manual transfer steps and reducing contamination risk.
- EU Green Deal embodied-carbon tracking:Equipment lifecycle accounting requirements are accelerating demand for energy-efficient motor systems and recyclable stainless steel construction in European installations.
- Quick-service chain standardization:North American fast-casual and quick-service restaurant chains are mandating identical slicing equipment across franchise locations to ensure product consistency.
Market Restraints
- Nickel price volatility:Stainless steel 304 and 316 grades depend on nickel content, and London Metal Exchange price swings directly compress equipment manufacturer margins.
- German engineering cluster concentration:Precision blade system production concentrates around Osnabrück, creating single-source risk for high-throughput slicing components.
- Clean-in-place validation timelines:FDA food safety modernization requirements extend equipment approval cycles, delaying revenue recognition for manufacturers.
Strategic Opportunities
- Gravity-fed vertical slicer expansion:Mid-size processors in the United States are retrofitting horizontal lines with vertical configurations to improve yield recovery and reduce mechanical complexity.
- India food processing infrastructure:FSSAI modernization and cold chain expansion are creating first-time equipment demand among domestic pork processors and hotel chains.
- CE marking harmonization:Streamlined EU machinery directive compliance is reducing certification costs for manufacturers seeking cross-border sales within Europe.
Industry Challenges
- Mechatronics technician scarcity:Automated slicer maintenance requires combined mechanical and programmable logic controller expertise that vocational programs are not producing at sufficient rates.
- Legacy equipment integration:Retrofitting existing processing lines with modern slicing modules requires custom mechanical interfaces that extend project timelines and inflate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacon Slicers Market |
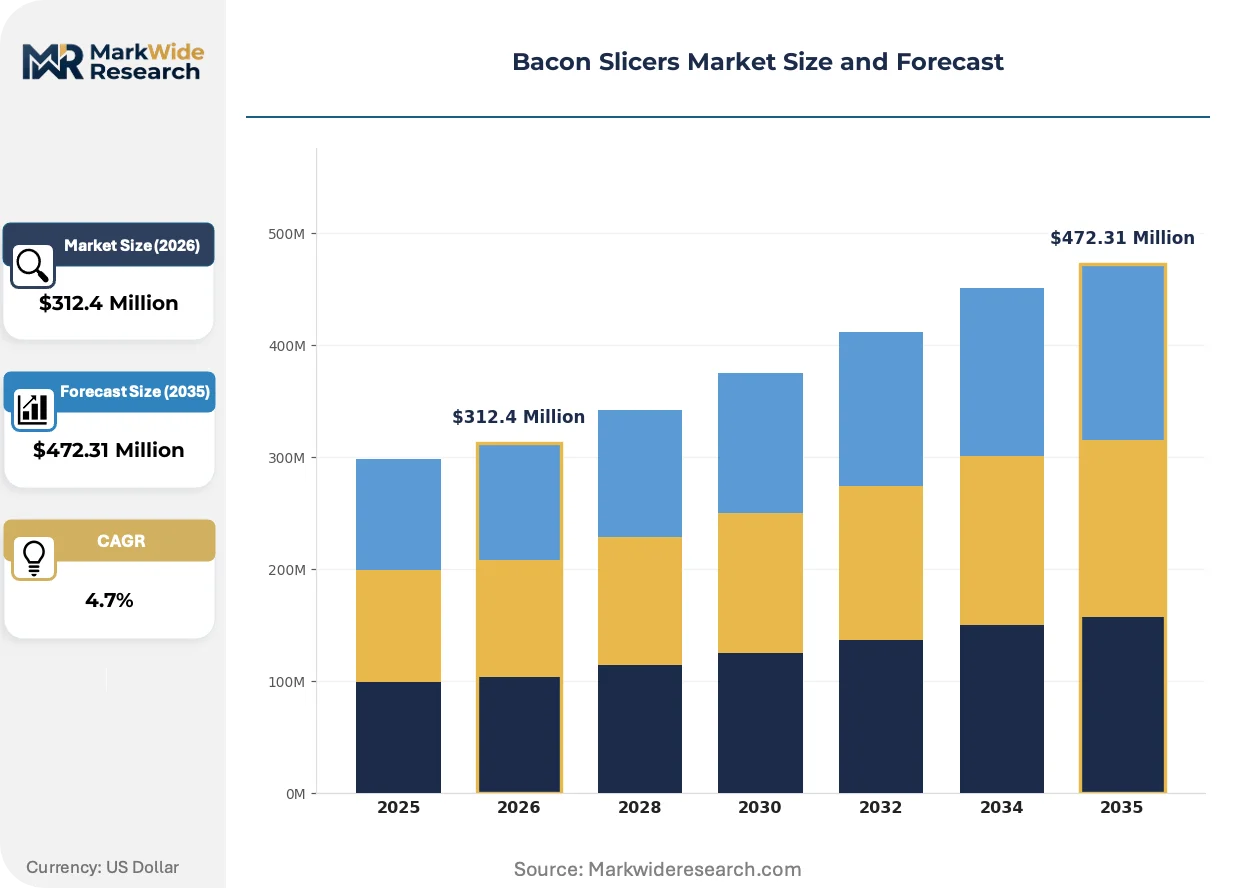
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Slicers, Electric Slicers, Vertical Slicers, Horizontal Slicers End User: Households, Restaurants, Deli Shops, Food Processing Units Material: Stainless Steel, Plastic, Aluminum, Composite Materials Feature: Adjustable Thickness, Safety Lock, Easy Clean, Noise Reduction |
| Companies Covered | Marel, Weber Maschinenbau, TREIF Maschinenbau, Bizerba, Grote Company, GEA Group, Provisur Technologies, Maja-Maschinenfabrik Hermann Schill GmbH, Food Technology Thielemann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacon Slicers Market Strategic Shifts
Equipment architecture is converging around modular platforms that separate slicing mechanics from control systems, enabling independent upgrade paths. This structural shift is compressing replacement cycles while extending functional lifespans of capital assets.
Ultrasonic blade cleaning systems are unifying sanitation and production workflows by eliminating separate washdown cycles. High-throughput processors in Germany and the United States are adopting these systems to maintain NSF International compliance without stopping production lines. The technology is unifying previously separate maintenance and operations teams under unified throughput metrics.
EU Regulation 1935/2004 food contact material compliance is tightening traceability requirements for all surfaces touching sliced product. Manufacturers must now document stainless steel alloy composition and surface finish certification across supply chains. European food processing units are responding by specifying equipment with pre-validated material certificates to accelerate installation approvals.
After-sales service contracts are fragmenting into component-level subscriptions rather than comprehensive maintenance agreements. Mid-size processors are purchasing blade sharpening and motor monitoring services separately, selecting providers based on specific technical competence rather than brand loyalty. This unbundling is most visible in North American independent meat processing operations seeking to reduce fixed cost structures.
Bacon Slicers Market Segmentation
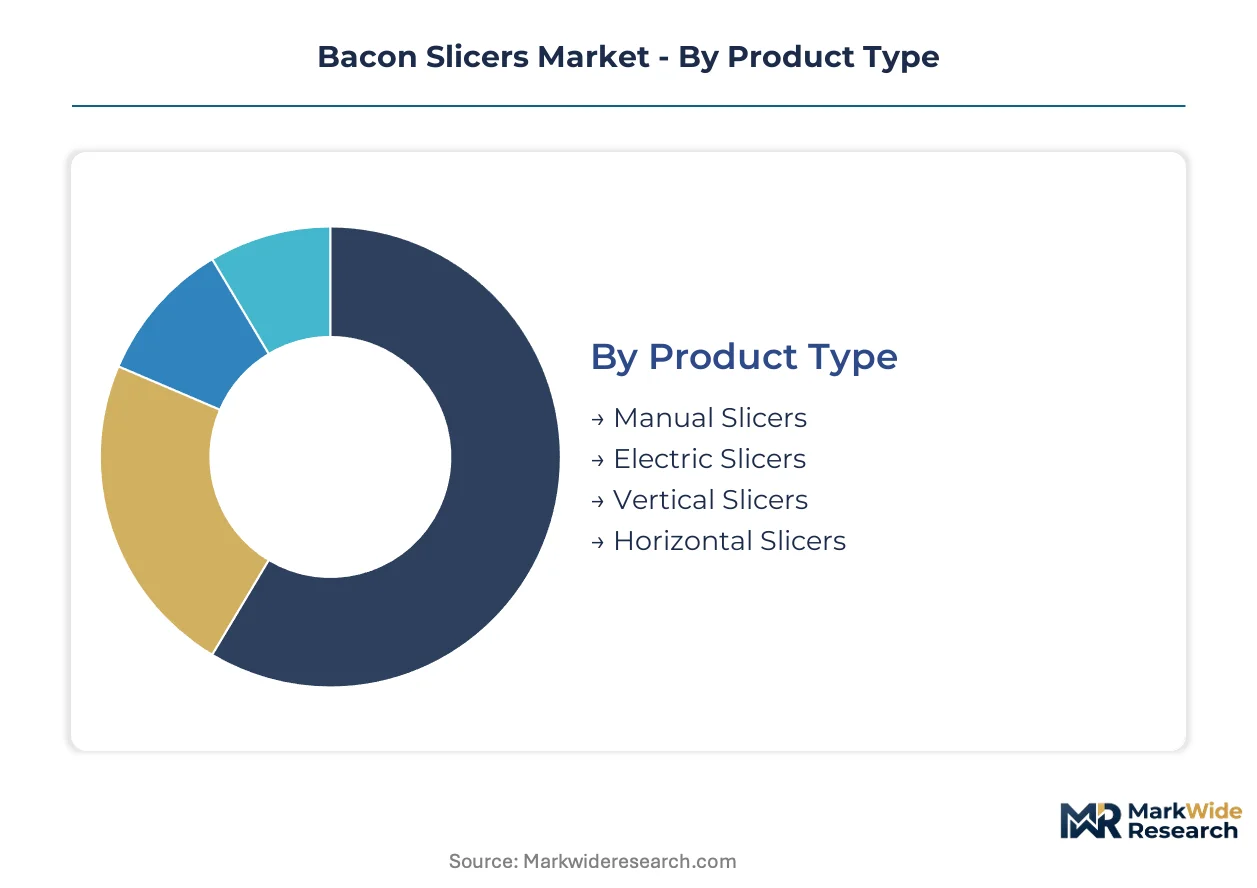
Equipment buyers in the bacon slicer market face divergent capital allocation pressures across product configurations, end-use applications, and material specifications. Segmentation reveals how stainless steel mandates and automated integration requirements are splitting procurement budgets between legacy replacement and capability expansion.
Product Type:
Volume deployment still favors established electric configurations, while gravity-fed designs capture premium positioning for yield-sensitive operations.
- Electric Slicers:Rotary blade systems powered by continuous-duty motors dominate installed base across North American quick-service chains and German processing plants. Demand concentrates in high-throughput facilities seeking validated clean-in-place compatibility for NSF International compliance audits.
- Vertical Slicers:Gravity-fed configurations reduce mechanical complexity by eliminating product push mechanisms. Mid-size processors in the United States are retrofitting horizontal lines with vertical designs to improve yield recovery and simplify maintenance protocols.
- Manual Slicers:Hand-cranked units persist in artisanal delis and small-batch operations where batch sizes fall below automated line economic thresholds.
- Horizontal Slicers:Traditional push-feed designs retain presence in legacy installations where capital constraints delay full line replacement.
Mature deployment sits with Electric Slicers. Newer deployment is concentrated in Vertical Slicers.
End User:
Procurement scale and technical specification intensity diverge sharply between industrial processors and foodservice operators.
- Food Processing Units:Industrial bacon processors require continuous-duty equipment with blade tolerances below 0.5 mm for retail-pack consistency. German precision-engineering clusters around Osnabrück anchor supply relationships for these high-specification buyers.
- Restaurants:Fast-casual and quick-service chains mandate identical slicing equipment across franchise locations to ensure product consistency. Standardization contracts favor manufacturers with continental service networks.
- Deli Shops:Counter-top configurations with rapid blade changeover dominate this segment. Buyers prioritize footprint reduction over throughput maximization.
- Households:Consumer-grade units with simplified safety interlocks serve occasional-use applications with limited duty-cycle requirements.
Volume concentration rests with Food Processing Units. Margin expansion is most visible in Restaurants.
Material:
Regulatory pressure on food contact surfaces is accelerating material substitution timelines across equipment replacement cycles.
- Stainless Steel:Grades 304 and 316 dominate new equipment specifications as EU Regulation 1935/2004 traceability requirements and NSF International sanitation standards eliminate aluminum eligibility. Surface finish certification now travels with alloy documentation through supply chains.
- Aluminum:Once-standard frame material faces certification withdrawal across European and North American markets. Remaining demand concentrates in price-sensitive regions with deferred regulatory adoption.
- Plastic:Polymer components persist in non-contact housings and safety guards where weight reduction and corrosion immunity provide functional advantage.
- Composite Materials:Hybrid constructions combining metal blades with polymer frames serve niche applications requiring specific vibration damping or thermal insulation properties.
Certification-compliant deployment concentrates in Stainless Steel. Cost-driven retention persists in Aluminum.
Feature:
Functional differentiation increasingly determines price realization rather than base equipment configuration.
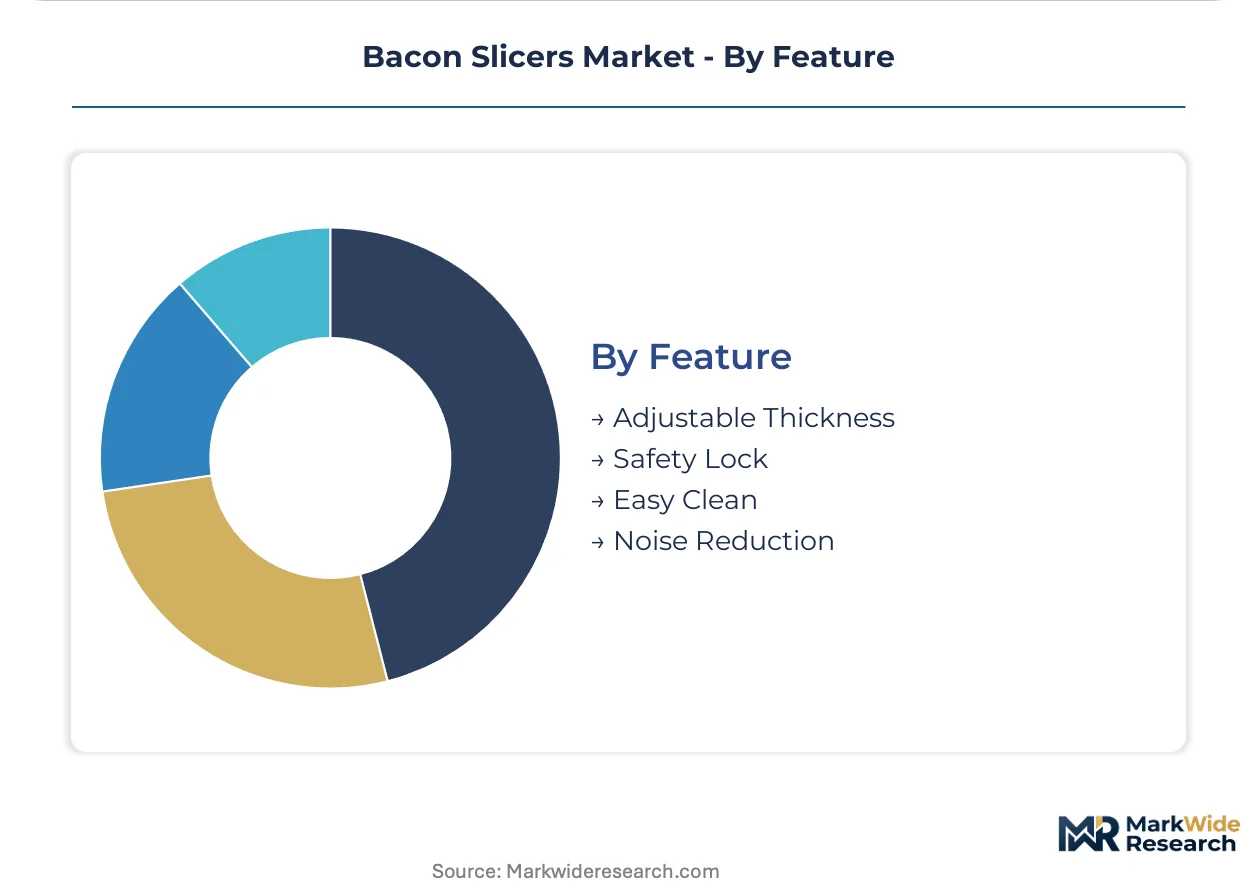
- Adjustable Thickness:Micro-stepping motors enabling 0.1 mm increment control command widest margin pools. Recipe flexibility across breakfast, sandwich, and retail-pack formats justifies premium positioning for processors serving multiple downstream channels.
- Easy Clean:Tool-free disassembly and validated clean-in-place designs address FDA food safety modernization requirements. Extended approval cycles for these configurations delay revenue recognition but lock in long-term replacement demand.
- Safety Lock:Blade interlock mechanisms satisfy OSHA and EU machinery directive requirements for operator protection during maintenance access.
- Noise Reduction:Acoustic dampening packages serve urban processing facilities facing municipal noise ordinances and 24-hour operational permits.
Baseline specification sits with Safety Lock. Capability expansion is concentrated in Adjustable Thickness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in industrialized meat-processing corridors where regulatory pressure and automation investment intersect. Germany's precision-engineering cluster anchors European supply relationships, while North American quick-service chains drive standardization contracts across franchise networks. Asian markets are emerging as first-time equipment demand centers as cold chain infrastructure modernizes.
United States
Quick-service restaurant chains mandate identical slicing equipment across franchise locations to ensure product consistency. FDA food safety modernization requirements push processors toward validated clean-in-place designs with extended approval cycles. Chicago and Omaha anchor Midwest meat-processing corridors where automated portioning integration commands capital allocation priority.
Germany
Industrial bacon processors require continuous-duty equipment with blade tolerances below 0.5 mm for retail-pack consistency. EU Regulation 1935/2004 traceability requirements eliminate aluminum eligibility and mandate stainless steel alloy documentation. The Osnabrück precision-engineering cluster hosts Weber Maschinenbau and TREIF Maschinenbau, anchoring regional supply for high-throughput blade systems.
China
Domestic pork processors are retrofitting legacy lines as dual carbon goals reshape stainless steel sourcing costs and equipment lifecycle accounting. The national food safety regulator tightens traceability requirements for food contact surfaces in processing equipment. Shandong and Sichuan provinces concentrate meat-processing infrastructure where first-time automated slicing demand is accelerating.
India
FSSAI modernization and cold chain expansion create first-time equipment demand among domestic pork processors and hotel chains. The country's food regulator mandates stricter sanitation protocols that displace manual cutting operations. Maharashtra and Karnataka host emerging food-processing infrastructure where mid-scale processors evaluate vertical slicer configurations for yield improvement.
Canada
Health Canada and PMRA sanitation standards align with NSF International protocols, streamlining equipment certification for cross-border suppliers. Pork processing cooperatives in Manitoba and Quebec prioritize adjustable thickness features for recipe flexibility across breakfast and retail-pack formats. Toronto and Montreal anchor distribution networks serving integrated processor-packer operations.
Bacon Slicers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with precision-engineering heritage conferring pricing power in high-throughput installations. The vendor base organizes around three strategic archetypes: German precision specialists leveraging regional engineering clusters, diversified food-equipment conglomerates with integrated portfolio breadth, and mid-scale fabricators serving price-sensitive retrofit demand. Competitive moves concentrate on automated portioning integration partnerships and gravity-fed vertical configuration launches.
Among German precision-engineering specialists, Weber Maschinenbau GmbH and TREIF Maschinenbau GmbH exemplify the heritage-driven tier where Osnabrück regional concentration anchors blade system expertise. Marel occupies a position within the diversified equipment conglomerate archetype, representing integrated portfolio strategies that span slicing through downstream packaging automation. These three entities collectively illustrate how geographic clustering and capability breadth define competitive positioning in equipment procurement decisions.
| Leading Market Players |
|---|
| Marel |
| Weber Maschinenbau |
| TREIF Maschinenbau |
| Bizerba |
| Grote Company |
| GEA Group |
| Provisur Technologies |
| Maja-Maschinenfabrik Hermann Schill GmbH |
| Food Technology Thielemann |
| Others |
Value Chain & Pricing Dynamics
Captive blade system production within the Osnabrück precision-engineering cluster anchors both supply security and premium pricing power for German manufacturers serving NSF International and EU Regulation 1935/2004 compliant installations. This geographic concentration of high-tolerance machining capability creates natural price stratification between heritage-equipped specialists and retrofit-focused fabricators.
Pricing Analysis
Volume concentration in electric slicers for quick-service chains compresses per-unit margins, while adjustable thickness configurations with micro-stepping motors command premium positioning. Price differentiation rests on NSF International certification tier and clean-in-place validation status, with unvalidated aluminum-frame equipment facing price erosion as certification withdrawal eliminates buyer pools. Food processing units demonstrate lowest price sensitivity due to throughput-dependent total cost of ownership calculations, whereas independent deli operators retain acute cost consciousness.
Supply Chain Analysis
Refurbishment flows for legacy horizontal slicers create secondary market circulation that tempers new equipment demand among mid-scale processors. Component supply concentrates in Germany, China, and the United States, with precision blade systems drawing from Osnabrück engineering networks and motor assemblies sourcing from Chinese manufacturing bases. Nickel price volatility in stainless steel 304 and 316 grades presents single-source vulnerability for alloy-dependent fabricators. Distribution runs through OEM-direct contracts for large processing units and regional equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bacon slicer market functions as a cost-of-compliance arena where EU Regulation 1935/2004 traceability mandates and NSF International sanitation standards erect capital-intensive barriers that favor incumbent specialists with pre-validated supply chains.
For Market Incumbents: Cement certification moats by accelerating clean-in-place validation investments ahead of FDA food safety modernization enforcement waves. Deepen backward integration into precision blade forging within the Osnabrück cluster to insulate margin structures from nickel price volatility transmitted through stainless steel supply contracts. For New Entrants and Emerging Players: Direct-to-processor digital sales channels bypass established distributor networks that incumbent German specialists dominate. Target India's emerging food processing infrastructure in Maharashtra and Karnataka where FSSAI modernization creates first-time equipment demand without entrenched supplier relationships. Lead with vertical slicer configurations that reduce mechanical complexity and appeal to yield-focused mid-scale operators. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified food equipment conglomerates seeking precision slicing capability. Long-term viability favors specialists with validated material certification infrastructure and continental service networks. Monitor FDA clean-in-place validation timeline acceleration as inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Portioning Integration | Weber Maschinenbau and Marel lead vacuum packaging line partnerships that eliminate manual transfer contamination risk. |
| Gravity-Fed Vertical Configuration Launch | Mid-scale U.S. processors retrofit horizontal lines to improve yield recovery and reduce maintenance complexity. |
| Stainless Steel Alloy Documentation | EU Regulation 1935/2004 traceability requirements mandate surface finish certification traveling with supply chains. |
| Component-Level Service Unbundling | North American independent processors purchase blade sharpening separately to reduce fixed cost structures. |
| India Market Entry Partnership | FSSAI modernization and cold chain expansion create first-time demand among domestic pork processors. |
Study Parameters
Multi-period observation of equipment certification timelines, stainless steel alloy pricing, and quick-service chain standardization contracts anchored the trend analysis, supplemented by interviews with plant engineers at food processing units, maintenance directors overseeing slicing line operations, OEM procurement teams at diversified equipment manufacturers, and aftermarket service heads managing blade sharpening contracts. Secondary validation drew from NSF International equipment listings, FDA food safety modernization guidance documents, EU machinery directive compliance databases, and customs records of stainless steel processing equipment trade flows. Bottom-up installation base estimates triangulated against top-down meat processing capacity assessments.
Segment-weighting applied product type, end user scale, material specification grade, and feature configuration dimensions across the projection horizon. CAGRs derived from installed base turnover rates, replacement cycle compression from regulatory mandates, and penetration modeling for vertical slicer configurations. Forecast inputs incorporated nickel price scenario sensitivity and clean-in-place validation pipeline visibility from FDA pre-submission meetings.
The model holds under stable regulatory enforcement timelines; deviation in FDA approval acceleration or EU Green Deal embodied-carbon tracking implementation would shift replacement demand recognition. Practitioners should monitor London Metal Exchange nickel price volatility and German engineering cluster labor availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Edible Meat Market
Meat Products
Meat Paste Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Ham Slicers Market
Meat Products
United States Frozen Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Chicken Buckets Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Meat Mincers Market
Meat Products
Bacon Flavors Market
Meat Products
Blended Meat Market
Meat Products
Smokehouse Market
Meat Products
Middle East Red Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
Pork Meat Market
Meat Products
Europe Canned Meat Market