
 Beverage Refrigeration Market | 2026-2036
Beverage Refrigeration Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Refrigeration Market Intelligence
Premium beverage refrigeration is decoupling from commodity tiers on energy efficiency, connectivity, and display quality. Whirlpool Corporation leverages its North American manufacturing scale to anchor the mid-premium residential segment. Liebherr differentiates through precision engineering for European hospitality specifications. Panasonic Corporation competes on compressor technology leadership across Asian commercial channels.
Beverage refrigeration encompasses thermally insulated cabinets and display systems engineered to maintain temperatures between 1°C and 10°C for commercial drink preservation and merchandising. These units employ vapor-compression, thermoelectric, or absorption cycles with polyurethane foam insulation and forced-air or gravity-coil heat exchange architectures. Glass door coolers dominate installed base across convenience stores and retail outlets due to visual merchandising requirements. Compressor-based systems sustain the largest technology share while thermoelectric units gain traction in countertop and portable formats where noise and vibration constraints matter. Under-counter coolers command premium placement in bars and hotels where floor space commands measurable opportunity cost.
EPA SNAP program rules and DOE commercial refrigeration standards shape product efficiency mandates in the United States. Ecodesign requirements and F-Gas Regulation in Europe restrict high-GWP refrigerants and mandate energy labeling disclosure. Stakeholders must monitor refrigerant transition timelines and efficiency tier migrations to align procurement and R&D roadmaps with compliance windows.
Market Dynamics
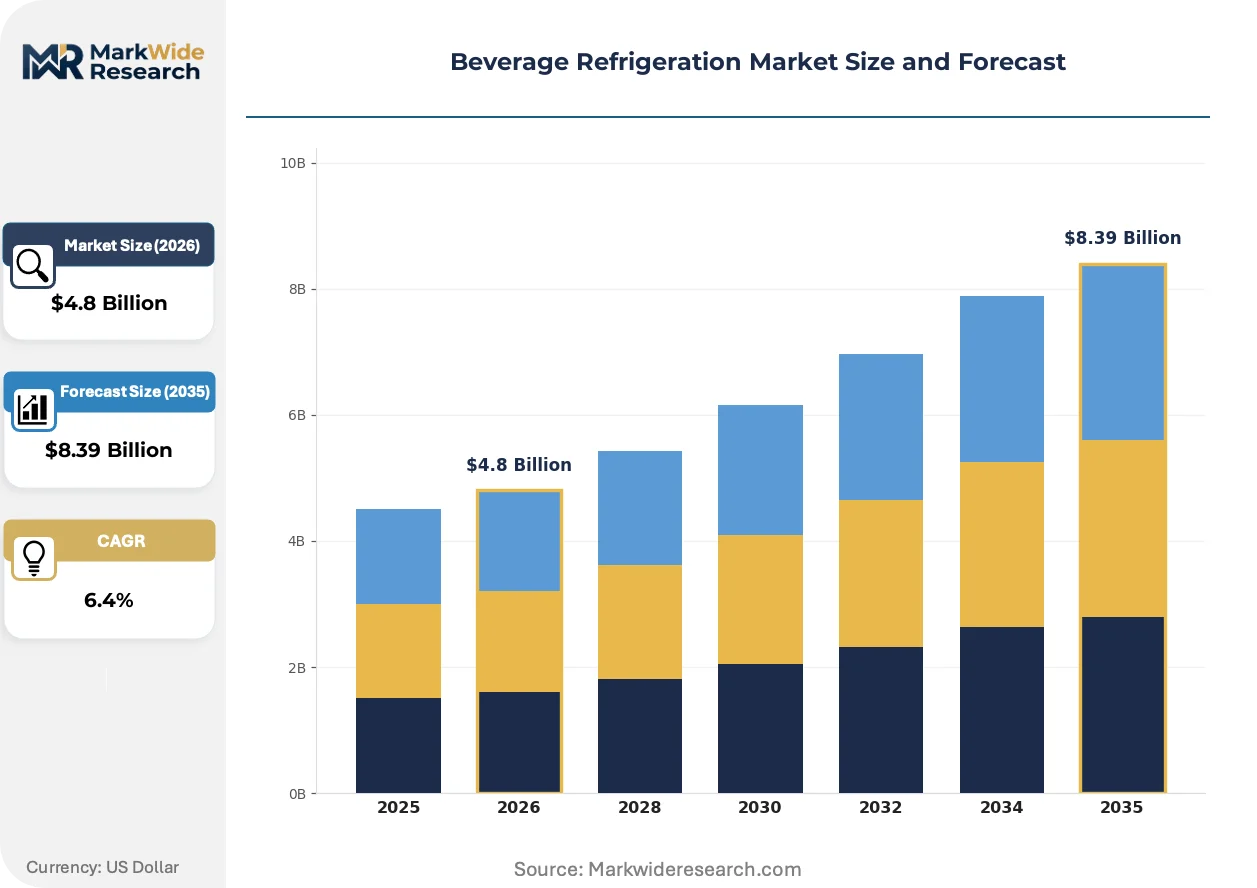
The EPA SNAP program and EU F-Gas Regulation are forcing simultaneous refrigerant transitions and compressor redesigns, compressing product development cycles while opening efficiency tiers for premium positioning.
Growth Catalysts
- EPA Energy-Efficiency Standards:DOE commercial refrigeration mandates in the United States accelerate replacement cycles for legacy cooler fleets in convenience stores and quick-service restaurants.
- Hospitality Chain Expansion:Hotel and resort operators in Dubai, Miami, and Singapore are standardizing under-counter and back-bar cooler specifications across property portfolios.
- Thermoelectric Miniaturization:Solid-state cooling advances enable countertop wine preservation and portable beverage chilling without compressor noise or vibration.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger and tubing costs fluctuate with commodity markets, squeezing margin on mid-tier compressor-based units.
- Compressor Supply Concentration:Asian manufacturing clusters dominate rotary and scroll compressor production, creating single-source risk for European and North American OEMs.
- Natural Refrigerant Technical Limits:CO2 and hydrocarbon systems face pressure envelope and charge-size constraints that restrict deployment in high-ambient-temperature environments.
Strategic Opportunities
- India Food Service Modernization:Quick-service restaurant chains in Mumbai, Delhi, and Bangalore are adopting Western-format beverage merchandising for the first time.
- Connected Cooler Telemetry:IoT-enabled temperature logging and predictive maintenance contracts create recurring revenue streams from installed commercial bases.
- EU Ecodesign Labeling Mandate:Mandatory energy disclosure creates premium positioning for A+++ rated glass-door merchandisers in German and French retail.
Industry Challenges
- Refrigerant Certification Timeline:EPA SNAP approval delays for low-GWP alternatives compress window for compliant product launches ahead of phase-out deadlines.
- Legacy Control System Integration:Building management system protocols in aged hospitality properties resist seamless connectivity with smart cooler diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Refrigeration Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Door Coolers, Bottle Coolers, Chest Freezers, Under-counter Coolers, Display Refrigerators, Countertop Coolers Application: Bars & Pubs, Cafes & Coffee Shops, Convenience Stores, Hotels & Resorts, Sports Facilities, Event Venues End User: Hospitality Chains, Retail Outlets, Food Service Providers, Entertainment Complexes, Wholesale Distributors, Event Organizers Technology: Thermoelectric, Compressor-based, Absorption, Magnetic, Solar-powered, Hybrid Systems |
| Companies Covered | Whirlpool Corporation, Liebherr, Panasonic Corporation, Haier Group, Hoshizaki Corporation, LG Electronics Inc., Samsung Electronics Co., Ltd, Daikin Industries Ltd., Electrolux AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Refrigeration Market Strategic Shifts & Innovations
Refrigeration architecture is fragmenting into application-specific formats while regulatory pressure fuses hardware design with energy accounting and digital monitoring capabilities.
Variable-speed inverter compressor technology is modularizing unit configuration for mixed-load applications. Convenience store operators in Texas and Florida are specifying dual-temperature zones within single footprints to accommodate craft beer, wine, and energy drinks simultaneously. This flexibility is modularizing procurement patterns away from single-purpose units toward configurable platforms that reduce SKU proliferation for chain buyers.
The EU F-Gas Regulation is banning refrigerants with GWP above 150 in new commercial equipment from 2025. OEMs in Italy and Spain are accelerating CO2 transcritical and hydrocarbon propane system qualification to maintain market access. Small-format urban retailers face the steepest compliance cost due to space constraints on cascade system footprints.
After-sales service unbundling is separating warranty, maintenance, and refrigerant management into discrete contracts. Large casino and stadium operators in Las Vegas and Macau now procure coolers without bundled service, sourcing technical support through third-party facilities management providers. This disintermediation compresses OEM service margins while expanding independent technician certification demand.
Beverage Refrigeration Market Segmentation
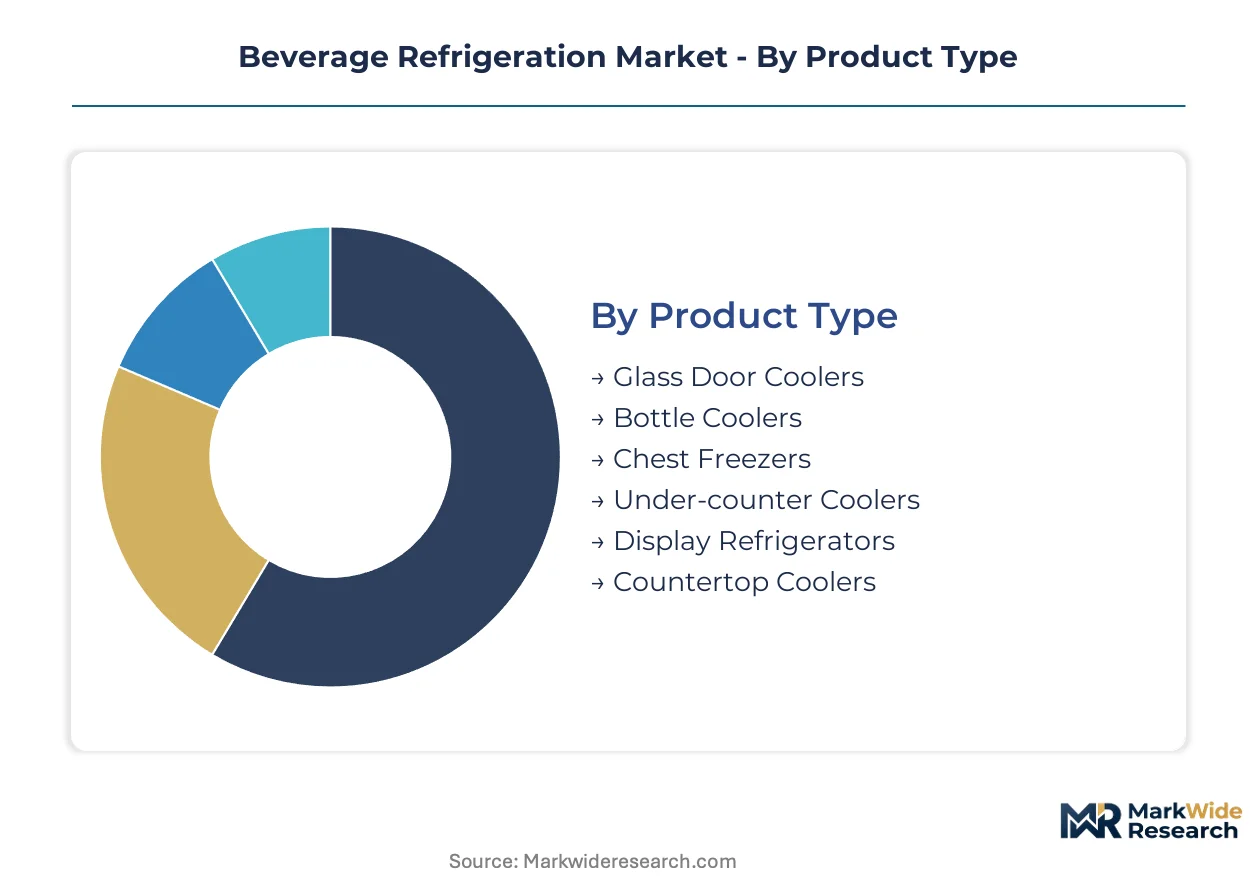
Beverage refrigeration procurement splits sharply between visual merchandising priorities in retail and space-efficiency imperatives in hospitality. Equipment specifications diverge on door configuration, temperature zoning, and connectivity requirements. Buyers in each segment trade off capital cost against energy lifecycle expense and compliance pathway certainty.
Product Type:
Buyers differentiate primarily on floor space economics versus impulse visibility trade-offs.
- Glass Door Coolers:Vertical merchandising cabinets with heated low-E glass and LED illumination dominate convenience store aisles and supermarket beverage alcoves. C-store operators in Texas and Florida specify these for energy drink and craft beer portfolios where sightline capture drives basket attachment.
- Under-counter Coolers:Built-in units with front-venting compressors and stainless steel interiors command premium placement in hotel bars and back-bar installations. Miami and Singapore hospitality chains standardize these across property portfolios where square footage carries measurable opportunity cost.
- Bottle Coolers:Solid-door horizontal units with sliding lids serve high-volume beer service in pubs and sports facilities.
- Chest Freezers:Top-opening insulated bins handle bagged ice and frozen beverage storage for event venues and wholesale operations.
- Display Refrigerators:Open-air vertical cases with air curtain technology suit grab-and-go retail formats requiring continuous access.
- Countertop Coolers:Compact thermoelectric or compressor units occupy point-of-sale positions in cafes and coffee shops with severe space constraints.
Volume sits with glass door configurations; growth tilts toward under-counter formats.
Application:
End-use environments impose distinct thermal load profiles and access frequency patterns.
- Convenience Stores:High-traffic 24-hour operations with frequent door cycles drive demand for inverter compressors and anti-condensation glass. EPA energy-efficiency standards accelerate replacement schedules for legacy fleets in this channel.
- Hotels & Resorts:Property-wide standardization programs in Dubai and Las Vegas create bulk procurement opportunities for under-counter and minibar formats. F-Gas Regulation compliance timelines shape specification decisions for new-build properties.
- Bars & Pubs:Back-bar installations prioritize rapid bottle cooling and noise suppression for customer-facing environments.
- Cafes & Coffee Shops:Countertop footprints and silent operation favor thermoelectric units for bottled water and refrigerated display cases.
- Sports Facilities:Concession stands require high-capacity bottle coolers and chest freezers for peak-event surge demand.
- Event Venues:Temporary and seasonal deployments favor portable and rental-configured equipment with rapid deployment capabilities.
Convenience stores anchor installed base; hospitality applications expand most quickly.
End User:
Procurement sophistication varies with scale and service integration requirements.
- Hospitality Chains:Multi-property operators in Singapore and Miami leverage volume purchasing to dictate custom specifications and IoT telemetry integration. These buyers unbundle service contracts from equipment procurement, compressing OEM margins while expanding third-party technician certification demand.
- Retail Outlets:Independent convenience stores and supermarkets prioritize first-cost minimization and rapid availability through distribution channels.
- Food Service Providers:Contract catering and institutional feeding operations specify durability and ease of sanitation over aesthetic refinement.
- Entertainment Complexes:Casinos and stadium operators in Macau and Las Vegas demand predictive maintenance contracts and 24-hour response guarantees.
- Wholesale Distributors:Equipment resellers and rental houses inventory standard configurations for rapid fulfillment to fragmented end markets.
- Event Organizers:Temporary deployment specialists prioritize equipment mobility, rapid commissioning, and flexible rental terms.
Procurement concentration sits with hospitality chains; contract complexity climbs fastest among entertainment complexes.
Technology:
Regulatory phase-outs and efficiency mandates are fragmenting technology adoption by application scale and ambient environment.
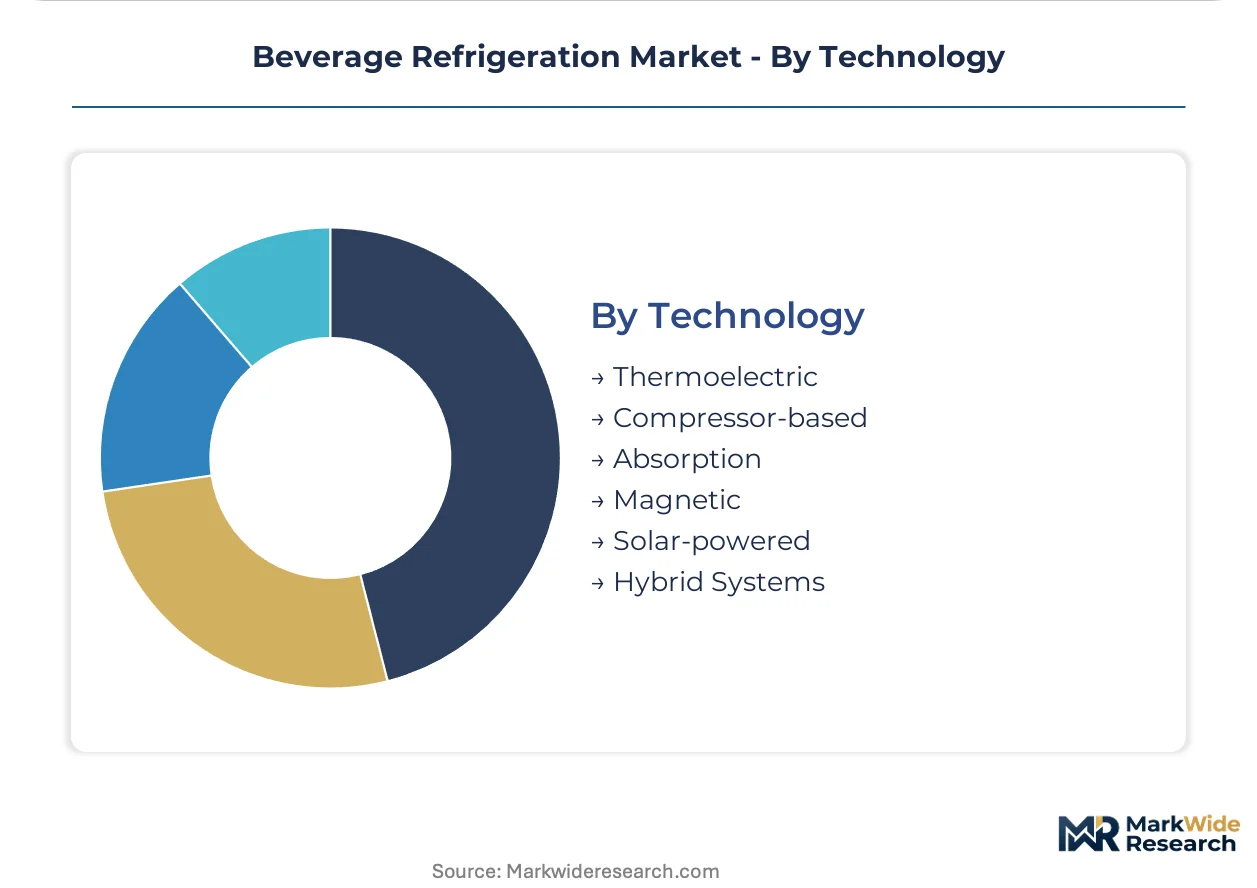
- Compressor-based:Vapor-compression cycles with rotary or scroll compressors sustain dominant share across commercial formats. DOE commercial refrigeration standards and F-Gas Regulation force simultaneous refrigerant transitions and compressor redesigns, compressing product development cycles.
- Thermoelectric:Solid-state Peltier cooling enables silent, vibration-free operation in countertop wine preservation and portable formats. Advances in semiconductor materials expand viable cooling capacity for premium residential and light commercial applications.
- Absorption:Heat-driven cycles suit off-grid and propane-fueled deployments in remote hospitality locations without reliable electrical infrastructure.
- Magnetic:Emerging magnetocaloric systems promise refrigerant-free operation with precise temperature control for laboratory and specialty beverage applications.
- Solar-powered:Photovoltaic-driven absorption or DC compressor systems serve outdoor events and developing-market installations with intermittent grid access.
- Hybrid Systems:Combined thermoelectric and compressor architectures optimize efficiency across variable load conditions in mixed-beverage deployments.
Compressor platforms retain volume leadership; thermoelectric formats gain share fastest in premium countertop segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor drives premium cooler specifications across hotel and resort properties. The United States, China, and Germany concentrate procurement volume while regulatory divergence shapes local product requirements.
United States
Convenience store chains in Texas and Florida accelerate cooler replacement cycles under DOE commercial refrigeration mandates. EPA SNAP program rules compress timelines for low-GWP refrigerant transitions. Miami's hotel operators standardize under-counter specifications across property portfolios.
Germany
Retail operators in Bavaria and North Rhine-Westphalia prioritize A+++ rated glass-door merchandisers under mandatory EU Ecodesign labeling. F-Gas Regulation bans refrigerants above 150 GWP from 2025, forcing CO2 transcritical system adoption. Stuttgart's engineering clusters specialize in compressor redesigns for hydrocarbon compliance.
China
Quick-service restaurant expansion in Shanghai and Beijing drives demand for Western-format beverage merchandising. National dual carbon goals accelerate efficiency tier migrations across commercial refrigeration. Shenzhen's manufacturing bases supply rotary and scroll compressors to domestic and export markets.
Japan
Precision engineering requirements from Tokyo's hospitality sector favor silent, vibration-free cooling technologies. METI efficiency standards push inverter compressor adoption in convenience store deployments. Osaka's industrial corridor hosts specialized fabrication for premium residential and light commercial formats.
India
Food service modernization in Mumbai, Delhi, and Bangalore introduces first-time beverage cooler procurement for quick-service chains. BIS energy labeling creates compliance benchmarks for imported equipment. Gujarat's manufacturing zones develop localized assembly capacity for cost-sensitive commercial segments.
Beverage Refrigeration Market Key Industry Players
Premium-margin players sit above commodity-margin players across energy efficiency certification tiers and IoT integration depth. The vendor base spans diversified appliance conglomerates, specialized refrigeration engineering houses, and component-focused compressor manufacturers. Three archetypes dominate: North American residential-scale fabricators, European precision-engineering specialists, and Asian integrated electronics-industrial conglomerates. Capacity expansion and refrigerant platform licensing constitute the primary competitive moves as compliance deadlines compress product development windows.
Among the diversified appliance conglomerates, Whirlpool Corporation and Haier Group occupy positions spanning residential through light-commercial segments. Liebherr exemplifies the European precision-engineering archetype with specialized hospitality specifications. Panasonic Corporation anchors the Asian integrated technology tier, representing compressor technology leadership across commercial channel structures.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Liebherr |
| Panasonic Corporation |
| Haier Group |
| Hoshizaki Corporation |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd |
| Daikin Industries Ltd. |
| Electrolux AB |
| Others |
Cost & Logistics Intelligence
Backward integration into compressor manufacturing anchors supply position and pricing power for beverage refrigeration OEMs facing refrigerant transition deadlines. Captive production of rotary and scroll compressor cores insulates tier-one vendors from Asian supply concentration while supporting premium positioning on efficiency certification tiers.
Pricing Analysis
Outcome-based pricing tied to energy savings certification anchors the beverage refrigeration market. Three-tier pricing structure across premium, standard, and economy levels separates A+++ rated EU Ecodesign units from baseline compliance models. Price differentiation stems from F-Gas Regulation certification tier and IoT telemetry integration depth. Cost compression in mid-tier compressor units is intensifying because copper and aluminum input volatility squeezes heat exchanger margins. Independent convenience stores exhibit highest price sensitivity; hospitality chains in Dubai and Singapore demonstrate lowest sensitivity due to lifecycle cost optimization mandates.
Supply Chain Analysis
Copper tubing supply rests on Chilean mining operations and Chinese semi-fabricated processing capacity. Rotary compressor cores draw from manufacturing clusters in China, Japan, and South Korea. Polyurethane foam insulation feeds from petrochemical complexes in Germany and the United States. Single-source vulnerability concentrates in Asian scroll compressor production for European and North American OEM assembly. Distribution runs through specialized refrigeration equipment distributors serving convenience store chains and hospitality procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage refrigeration sits in a refrigerant-transition phase as CO2 transcritical and hydrocarbon systems displace legacy high-GWP vapor-compression platforms.
For Market Incumbents: Acquire compressor technology IP and refrigerant platform licenses to secure compliance pathway certainty ahead of EPA SNAP phase-out deadlines. Build captive testing capacity for natural refrigerant charge-size optimization in high-ambient-temperature environments. Deepen backward integration into compressor core production to reduce single-source exposure from Asian manufacturing clusters. Anchor defensive positioning through A+++ efficiency certification pre-emption in German and French retail channels. For New Entrants and Emerging Players: Facilities management providers represent the most accessible channel partner type for aftermarket service disintermediation. Target unbundled maintenance contracts for casino and stadium operators in Las Vegas and Macau seeking predictive diagnostics capabilities. Penetrate India's quick-service restaurant modernization wave through localized assembly partnerships in Gujarat manufacturing zones. Deploy thermoelectric miniaturization expertise for silent countertop wine preservation in Tokyo's precision hospitality sector. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified appliance conglomerates seeking refrigerant-compliant product platforms. Long-term viability favors vendors with demonstrated CO2 transcritical system qualification and IoT telemetry integration depth. Acquisition target archetype: European precision-engineering specialists with hospitality chain specification relationships. Watch EPA SNAP approval velocity for low-GWP alternatives as inflection indicator for compliant product launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Licensing | Secures EPA SNAP and EU F-Gas Regulation compliance pathway for compressor redesign cycles. |
| IoT Telemetry Integration | Enables predictive maintenance contracts with casino operators in Macau and Las Vegas. |
| CO2 Transcritical Qualification | Maintains market access under EU F-Gas Regulation GWP 150 ban from 2025. |
| Backward Integration into Compressors | Reduces single-source risk from Asian rotary and scroll manufacturing concentration. |
| India Localized Assembly Partnership | Captures quick-service restaurant modernization demand in Mumbai and Bangalore. |
Research Approach
Trade association filings, customs and trade flow databases, and regulatory submission records formed the secondary backbone for this analysis. Primary interviews with commercial refrigeration OEM product managers, hospitality chain procurement directors, convenience store fleet operators, and compressor manufacturing engineers combined with secondary validation. Bottom-up unit shipment modeling and top-down value triangulation across product type, application, technology, and regional regulatory clusters anchored segmentation integrity.
Historical trendline analysis of replacement cycle timing, efficiency tier migration patterns, and refrigerant phase-out compliance windows informed projection methodology. Segmentation dimensions modeled include product format, end-use environment, cooling technology architecture, and regional energy standard cluster across the analysis window. CAGR derivation incorporated unit economics of copper and aluminum input cost trajectories, hospitality chain expansion velocity, and thermoelectric semiconductor material cost curves.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration, breakthrough magnetocaloric commercialization, and macroeconomic disruption to hospitality construction pipelines. Forecasts reflect documented assumptions on refrigerant approval timelines and efficiency standard enforcement consistency. Supply chain disruption from commodity volatility, compressor manufacturing concentration, and logistics chokepoint vulnerability warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Commercial Microwaves Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Commercial Slush Machine Market