
 Draught Beer Chiller Market | 2026-2036
Draught Beer Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Draught Beer Chiller Market Foresight
Buyer concentration is shifting as independent craft breweries multiply across North America and Europe while legacy pub chains consolidate purchasing through centralized procurement platforms. Micro Matic leverages its European dispensing heritage to dominate specification-heavy brewery projects. Perlick Corporation sustains premium positioning in US sports stadium and hotel installations through stainless steel fabrication expertise. Zhongde Equipment competes on manufacturing scale for cost-sensitive Asian markets.
Draught beer chillers are self-contained refrigeration systems that cool beverage lines or keg reservoirs to serving temperature, typically employing glycol circulation loops, forced-air evaporators, or direct-draw configurations to maintain precise thermal stability. The primary commercial purpose centers on preserving carbonation integrity and flavor profile from keg to tap in high-volume on-premise consumption settings. Undercounter installations lead product type demand in space-constrained urban bars where floor space commands premium lease rates. Glycol-cooled technology anchors brewery-direct applications requiring extended line runs from cold room to tap tower. Portable installation types represent the fastest-growing segment as pop-up events and seasonal outdoor service expand.
The US Department of Energy sets minimum efficiency standards for commercial refrigeration equipment through federal regulation, while the EPA's SNAP program governs acceptable refrigerants in beer cooling systems. Europe's F-Gas Regulation progressively restricts hydrofluorocarbon use, compelling manufacturers to redesign cooling circuits around natural refrigerants or lower-GWP alternatives. China's GB standards for commercial appliance energy labeling create compliance thresholds for imported equipment. Stakeholders must monitor refrigerant phase-down timelines and efficiency tier upgrades to avoid stranded inventory and redesign cycles.
Market Dynamics
Europe's F-Gas Regulation is forcing rapid refrigerant transitions across draught beer chiller manufacturing, compressing design cycles and redrawing competitive positioning around natural coolant expertise.
Growth Catalysts
- Independent craft brewery proliferation:North American and European microbreweries are expanding taproom footprints, creating concentrated demand for compact glycol-cooled systems with precise temperature control.
- US DOE efficiency standards:Tightening federal energy consumption mandates for commercial refrigeration are accelerating replacement cycles in legacy bar and stadium installations.
- Outdoor event service expansion:Portable chiller configurations are capturing pop-up and seasonal service applications previously served by ice-based cooling.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margin predictability for mid-tier manufacturers.
- German component supply concentration:Precision compressor and valve sourcing clusters in Bavaria and Baden-Württemberg, creating geographic single-point vulnerability.
- Hydrofluorocarbon phase-down friction:Europe's F-Gas Regulation timeline outpaces alternative refrigerant availability, stranding some equipment designs.
Strategic Opportunities
- India's underpenetrated on-premise channel:Urban microbrewery licensing liberalization in Maharashtra and Karnataka is opening greenfield installation demand.
- IoT-enabled predictive maintenance:Sensor-integrated chillers are creating recurring revenue streams through remote monitoring subscriptions.
- China GB standards alignment:Energy labeling compliance for imported equipment creates first-mover positioning for efficient natural refrigerant designs.
Industry Challenges
- Refrigerant technician certification gaps:Natural coolant handling requires specialized training that outpaces vocational program updates in several markets.
- Legacy glycol system integration:Retrofit compatibility with existing bar infrastructure demands custom engineering, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Draught Beer Chiller Market |
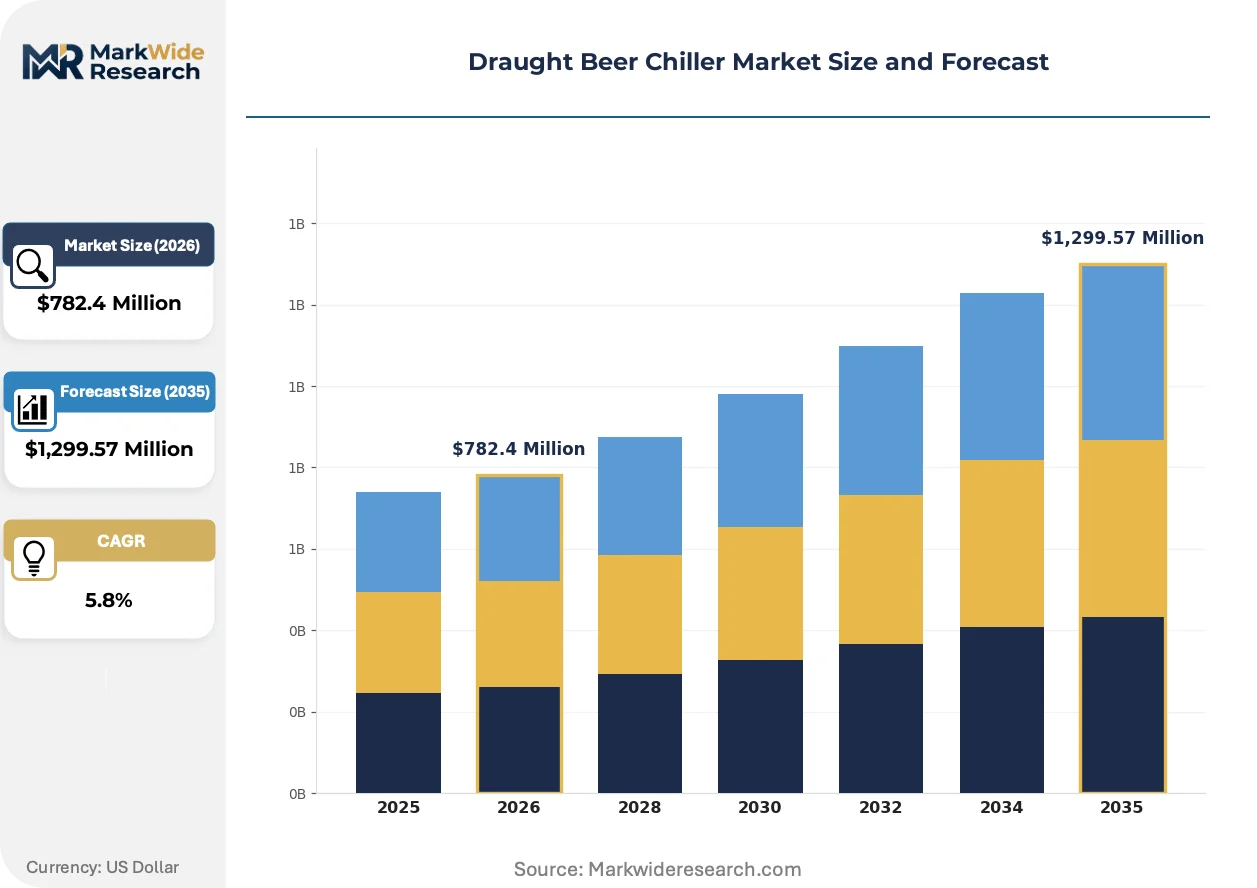
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Wall-mounted, Undercounter, Commercial Technology: Air-cooled, Water-cooled, Glycol-cooled, Electric End User: Bars, Restaurants, Breweries, Events Installation Type: Permanent, Portable, Integrated, Modular |
| Companies Covered | Micro Matic, Perlick Corporation, Beverage-Air Corporation, Zhongde Equipment Co., Ltd., CELLI S.p.A., Hoshizaki Corporation, True Manufacturing Company, Inc., Beerjet GmbH, KegWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Draught Beer Chiller Market Shifts & Advancements
Carbon dioxide transcritical cooling is absorbing investment priority as manufacturers navigate refrigerant transitions while preserving thermal performance in high-ambient environments.
CO2 transcritical refrigeration is absorbing engineering resources across European and North American manufacturing lines. Craft breweries with extended line-run requirements are adopting these systems fastest. The technology is absorbing market share from traditional HFC-based units in regions with aggressive phase-down timelines.
Europe's F-Gas Regulation mandates 79% hydrofluorocarbon reduction by 2030, forcing complete cooling circuit redesigns. Manufacturers are compressing product development cycles to meet interim GWP thresholds. Brewery-direct specification processes now prioritize natural refrigerant compliance over legacy performance benchmarks.
Specification authority is migrating from general contractors to brewery technical directors with direct equipment knowledge. This shift is compressing distributor influence in project bidding. Bavaria and Oregon represent the clearest geographies where buyer technical sophistication has accelerated this transition.
Draught Beer Chiller Market Segmentation
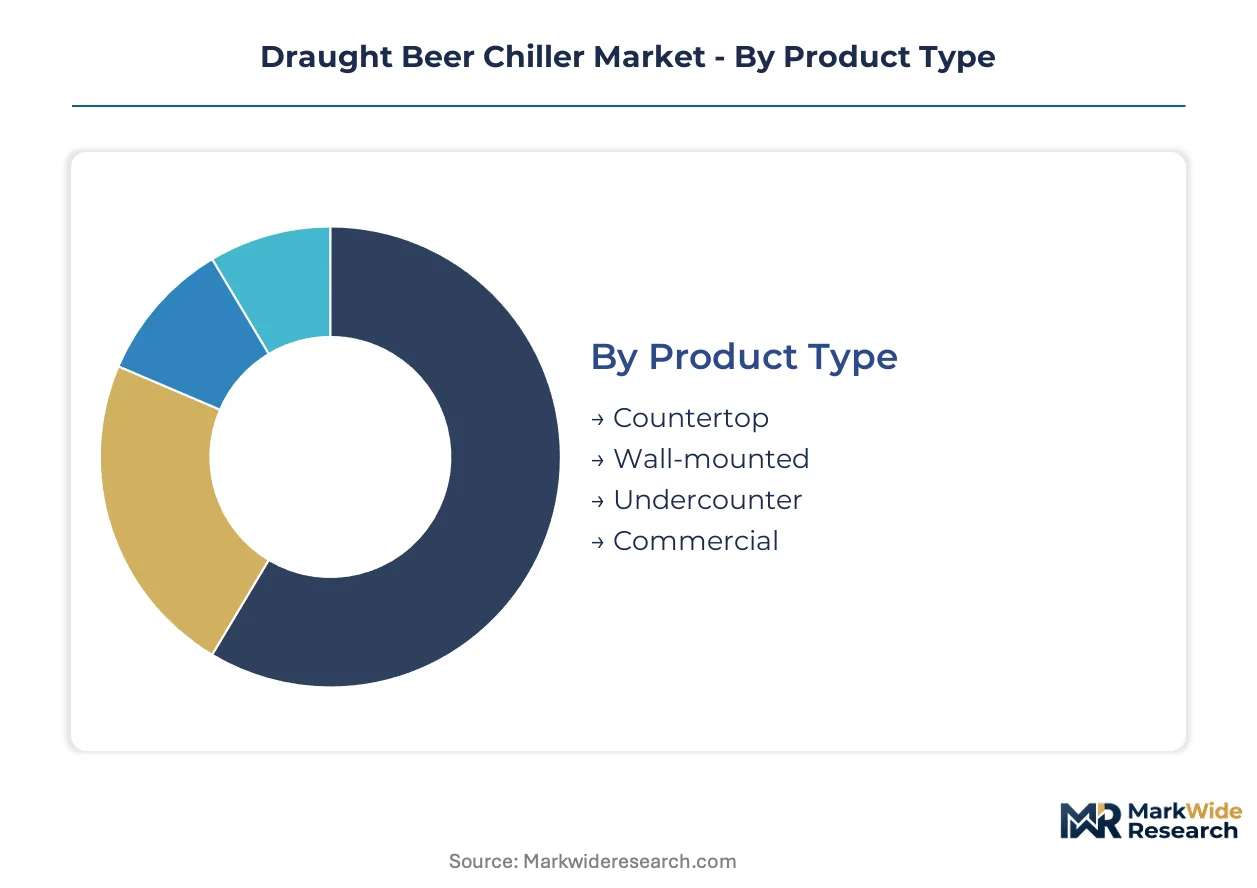
Draught beer chiller segmentation reveals divergent engineering priorities across venue footprints and cooling distances. Product configuration and installation flexibility determine specification authority in brewery-direct versus distributor-channel procurement.
Product Type:
Volume installations favor space-optimized formats, while premium positioning demands visible stainless fabrication and tap tower integration.
- Undercounter:These self-contained units slide beneath bar surfaces to preserve floor space in high-rent urban districts. Demand concentrates in Manhattan, London, and Tokyo where lease rates per square foot exceed cooling equipment capital costs within 18 months. Munich beer halls specify these for server ergonomics during peak service hours.
- Countertop:Compact forced-air evaporators sit atop bar structures for immediate access in low-volume tasting rooms. Portland, Oregon and Copenhagen microbreweries favor these for flexible tap rotation and minimal glycol infrastructure. The format sacrifices cooling capacity for installation simplicity.
- Wall-mounted:Vertical units anchor to structural surfaces in narrow corridor service areas.
- Commercial:High-capacity remote systems serve stadium concourses and festival grounds with multiple tap towers.
Today's leader: Undercounter. Tomorrow's challenger: Countertop.
Technology:
Refrigerant chemistry and heat exchange architecture separate specification tiers as F-Gas Regulation deadlines approach.
- Glycol-cooled:Circulating propylene glycol loops maintain thermal stability across extended line runs from cold rooms to distant tap towers. Bavarian breweries and Oregon craft producers specify these for 50+ meter distances where direct-draw fails. The technology anchors brewery-direct procurement with precise temperature control requirements.
- Air-cooled:Forced-air evaporators dominate compact installations with limited ventilation constraints. Mumbai and São Paulo bars adopt these where water scarcity or drainage limitations preclude alternative configurations. Energy efficiency varies sharply with ambient temperature fluctuations.
- Water-cooled:Heat rejection through water loops suits coastal installations with stable supply.
- Electric:Thermoelectric modules serve ultra-compact portable units with minimal cooling loads.
Current specification dominance: Glycol-cooled. Steepest expansion trajectory: Air-cooled.
End User:
Procurement authority migrates from general contractors to technical directors as brewery sophistication deepens.
- Breweries:Taproom and production facility installations demand precise temperature control for brand integrity from tank to tap. Technical directors in Fort Collins, Colorado and Bamberg, Germany now specify equipment directly, compressing distributor influence. Extended glycol runs and multi-tower configurations dominate these projects.
- Bars:Independent urban establishments prioritize footprint minimization and rapid installation turnaround. Brooklyn and Berlin operators favor undercounter formats with plug-and-play commissioning. Replacement cycles accelerate under US DOE efficiency standards.
- Restaurants:Full-service venues integrate chillers with back-of-house refrigeration infrastructure.
- Events:Temporary installations require portable configurations with rapid deployment capability.
Specification control: Breweries. Volume concentration: Bars.
Installation Type:
Permanence versus mobility defines capital deployment and service revenue models.
- Portable:Self-contained units on casters capture pop-up beer gardens, music festivals, and seasonal outdoor service. Melbourne and Austin event operators rent these rather than owning, creating recurring revenue for equipment lessors. Battery and solar-compatible variants are gaining share in off-grid applications.
- Permanent:Hard-piped installations anchor long-term venue commitments with integrated glycol infrastructure. Traditional Munich beer halls and Dublin pubs specify these for decades-long service life. Retrofit compatibility with legacy systems extends sales cycles.
- Integrated:Built-in formats merge with custom millwork and bar architecture.
- Modular:Scalable configurations allow capacity expansion without full replacement.
Revenue stability: Permanent. Share momentum: Portable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Bavaria region sustains denser draught beer chiller installations per capita than any comparable US market, while India's Maharashtra state is opening faster licensing pathways for microbrewery taprooms.
Germany
Bavarian beer halls and Franconian craft breweries drive specification demand for extended glycol-cooled systems. The F-Gas Regulation mandates progressive hydrofluorocarbon phase-down through 2030, compelling cooling circuit redesigns. Munich and Bamberg anchor brewery-direct procurement clusters where technical directors now specify equipment directly.
United States
Independent craft brewery proliferation across Colorado and Oregon concentrates demand for compact undercounter units. The Department of Energy's commercial refrigeration efficiency standards accelerate replacement cycles in legacy bar installations. Fort Collins and Portland represent the densest brewery-direct specification geographies.
India
Maharashtra and Karnataka state licensing liberalization for urban microbreweries creates greenfield installation demand. The Bureau of Indian Standards' commercial appliance energy labeling creates compliance thresholds for imported equipment. Bangalore and Mumbai microbrewery clusters favor portable configurations for flexible taproom layouts.
China
GB standards for commercial appliance energy labeling shape import compliance for bar equipment. Manufacturing scale in Guangdong and Zhejiang provinces supplies cost-sensitive Asian markets. Zhongshan and Ningbo industrial zones concentrate fabrication capacity for glycol-cooled system components.
Japan
High-ambient urban bar environments in Tokyo and Osaka favor air-cooled configurations with stable ventilation. METI efficiency guidelines influence commercial refrigeration procurement in premium hospitality venues. Yokohama's brewery cluster adopts compact countertop formats for tasting room flexibility.
Draught Beer Chiller Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers. The vendor base organizes around three strategic archetypes: European heritage brands with brewery-direct relationships, North American fabricators serving stadium and hotel chains, and Asian manufacturers competing on production scale. Consolidation pressure intensifies as refrigerant transitions compress design cycles. Geographic expansion and technology licensing represent the dominant competitive moves as players navigate F-Gas Regulation compliance deadlines.
Within the heritage specialist tier, Micro Matic leverages its Danish dispensing lineage to anchor brewery-direct specification processes. Perlick Corporation occupies a position among North American premium fabricators serving sports and hospitality venues. Zhongde Equipment Co., Ltd. exemplifies the scale-driven Asian manufacturing archetype competing on cost-sensitive regional tenders. These three players represent divergent strategic postures: specification authority through technical heritage, premium positioning through stainless fabrication expertise, and volume capture through manufacturing scale.
| Leading Market Players |
|---|
| Micro Matic |
| Perlick Corporation |
| Beverage-Air Corporation |
| Zhongde Equipment Co., Ltd. |
| CELLI S.p.A. |
| Hoshizaki Corporation |
| True Manufacturing Company, Inc. |
| Beerjet GmbH |
| KegWorks |
| Others |
Supply & Pricing Matrix
Family-owned Bavarian compressor specialists anchor supply-side discipline, compressing margin volatility for mid-tier manufacturers while premium fabricators in North America and Asia maintain pricing power through stainless steel differentiation and manufacturing scale.
Pricing Analysis
Capacity additions in China's Zhejiang and Guangdong provinces are reshaping price floors for standard glycol-cooled units. Three-tier pricing structure across premium, standard, and economy levels separates Perlick's stadium-grade fabrication from Micro Matic's brewery-direct specification authority and Zhongde's cost-sensitive Asian tenders. Price differentiation hinges on CE/F-Gas compliance certification and after-sales service bundling. Cost compression in the economy tier is intensifying because copper and aluminum input volatility feeds through heat exchanger fabrication. Craft brewery technical directors show least price sensitivity; independent urban bars in high-rent districts exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with precision compressor and electronic expansion valve sourcing from Bavaria and Baden-Württemberg. Manufacturing gravity centers on Germany, China, and the United States for finished systems; copper tubing, aluminum heat exchangers, and refrigeration compressors constitute critical input dependencies. Supply chain risk stems from tariff exposure on Chinese-manufactured components entering European and North American assembly plants. Distribution runs through brewery-direct specification channels for glycol-cooled projects and beverage equipment distributors for retrofit bar installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural refrigerant transition costs are compressing for early movers, expanding premium-tier capture as F-Gas Regulation deadlines harden specification requirements and technical directors prioritize compliance over legacy performance benchmarks.
For Market Incumbents: Deploy CO2 transcritical engineering resources to defend specification authority against emerging Asian competitors with natural refrigerant expertise. Consolidate backward integration into precision valve sourcing to offset Bavarian supply concentration risk. Deepen brewery-direct relationships in Oregon and Colorado before distributor influence erodes further. For New Entrants and Emerging Players: Beverage equipment lessors represent the most penetrable channel partner type for portable configuration market share. Target India's Maharashtra and Karnataka microbrewery licensing liberalization for greenfield installation demand. Pursue IoT-enabled predictive maintenance subscriptions as a recurring revenue wedge against capital-equipment-only incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers stranded between heritage specification authority and Asian manufacturing scale. Five-to-ten-year viability favors players with F-Gas-compliant natural refrigerant portfolios and established brewery-direct technical relationships. Monitor refrigerant technician certification program expansion as the signal to watch for alternative coolant adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Transition | CO2 transcritical engineering investment secures specification authority under Europe's F-Gas Regulation deadlines. |
| IoT Platform Integration | Sensor-integrated chillers generate recurring revenue through remote monitoring subscriptions in craft brewery taprooms. |
| Backward Integration | In-house production of precision compressors reduces dependency on Bavarian and Baden-Württemberg component suppliers. |
| Geographic Expansion | First-mover positioning in India's Maharashtra and Karnataka microbrewery clusters captures licensing liberalization demand. |
| Certification Investment | CE marking and GB standards alignment unlocks European and Chinese import compliance for efficient natural refrigerant designs. |
Research Methodology
Multiple input streams — technical director interviews at Fort Collins and Bamberg breweries, distributor channel assessments in Brooklyn and Berlin, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary conversations engaged brewery technical directors, bar operations managers, beverage equipment distributors, and refrigeration service technicians. Secondary validation drew from EPA SNAP program filings, EU F-Gas Regulation implementation documents, China's GB standards energy labeling databases, and US DOE commercial refrigeration efficiency rulemakings.
Data-stream reconciliation across product type, cooling technology, end-user vertical, and installation permanence dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, craft brewery taproom expansion rates, and outdoor event service penetration trajectories. Forecast inputs incorporated F-Gas Regulation phase-down timelines, US DOE efficiency standard adoption curves, and India's microbrewery licensing velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant technician certification program rollout speed and copper-aluminum commodity price volatility. Forecasts reflect documented assumptions around regulatory compliance deadlines and buyer specification authority migration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Food Thermos Market