
 Sheet Pan Racks Market | 2026-2036
Sheet Pan Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Pan Racks Market Outlook
North American stainless steel fabrication capacity is shifting toward food-grade specifications as commercial kitchen equipment standards tighten. Vollrath Company leverages its Wisconsin manufacturing base to sustain domestic supply of NSF-certified sheet pan racks. Nordic Ware competes through specialized aluminum construction for residential and light commercial segments. Chicago Metallic anchors the premium tier with heavy-gauge aluminized steel designs targeting industrial bakeries.
Sheet pan racks are vertical storage and cooling frameworks, typically constructed from 18- to 20-gauge stainless steel or aluminum tubing with welded wire shelves spaced on 1.5- to 3-inch centers, designed to hold standardized half-size or full-size sheet pans in commercial food production environments. Stainless steel mobile racks dominate institutional procurement due to corrosion resistance and load ratings exceeding 800 pounds, while aluminum stackable units capture cost-sensitive bakery startups seeking modularity without floor-space commitment. The end-user split shows restaurants prioritizing mobile units for kitchen workflow efficiency, whereas bakeries favor fixed and stackable configurations for proofing and cooling stages.
FDA food-contact surface regulations and NSF/ANSI Standard 2 certification requirements shape material selection and welding finish standards across all domestic production. State health departments in California, Texas, and New York enforce additional inspection protocols for rack sanitation in commercial kitchens. Buyers should monitor evolving energy-efficiency standards for refrigerated rack integration and assess supplier compliance documentation before capital commitments.
Market Dynamics
Commercial bakery chains in the United States are expanding cooling and storage infrastructure faster than equipment replacement cycles, compressing lead times for NSF-certified stainless steel fabrication and reshaping supplier capacity allocation across domestic manufacturing bases.
Growth Catalysts
- NSF/ANSI Standard 2 Certification Mandates:State health departments in California, Texas, and New York enforce rigorous inspection protocols for rack sanitation, compelling institutional buyers toward certified suppliers and locking in specification premiums.
- High-Volume Bread Production:Commercial bakery chains are scaling proofing and cooling stages, driving fixed and stackable rack configurations into greenfield facilities.
- Stainless Steel Corrosion Resistance:Food-contact surface regulations under FDA standards favor 18- to 20-gauge welded construction for load ratings exceeding 800 pounds in mobile institutional procurement.
Market Restraints
- Food-Grade Stainless Steel Input Volatility:Nickel and chromium price swings compress fabrication margins for Wisconsin-based domestic suppliers serving NSF-certified demand.
- Aluminum Substitution in Light Commercial:Residential and startup bakery segments favor stackable aluminum units for modularity without floor-space commitment, capping stainless steel volume in cost-sensitive tiers.
- Welding Finish Compliance Friction:FDA food-contact surface regulations impose additional grinding and passivation steps, extending production cycles for custom rack orders.
Strategic Opportunities
- Refrigerated Rack Integration:Energy-efficiency standards for cold-chain bakery infrastructure create specification white space for suppliers offering combined cooling-storage systems.
- Texas and Florida Bakery Clusters:Population-driven bread demand in Sun Belt states concentrates greenfield investment, favoring regional fabrication capacity proximity.
- Mobile Workflow Efficiency:Restaurant kitchens are prioritizing castor-mounted units for line flexibility, opening displacement potential against fixed bakery-dominant configurations.
Industry Challenges
- Sanitation Certification Timelines:NSF documentation and state health department inspection protocols delay capital equipment approvals for new market entrants.
- Legacy Fixed Rack Integration:Industrial bakeries face workflow disruption when retrofitting mobile units into established proofing-cooling sequences.
- Welder Skill Scarcity:Food-grade TIG certification requirements constrain fabrication capacity expansion at domestic stainless steel suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Pan Racks Market |
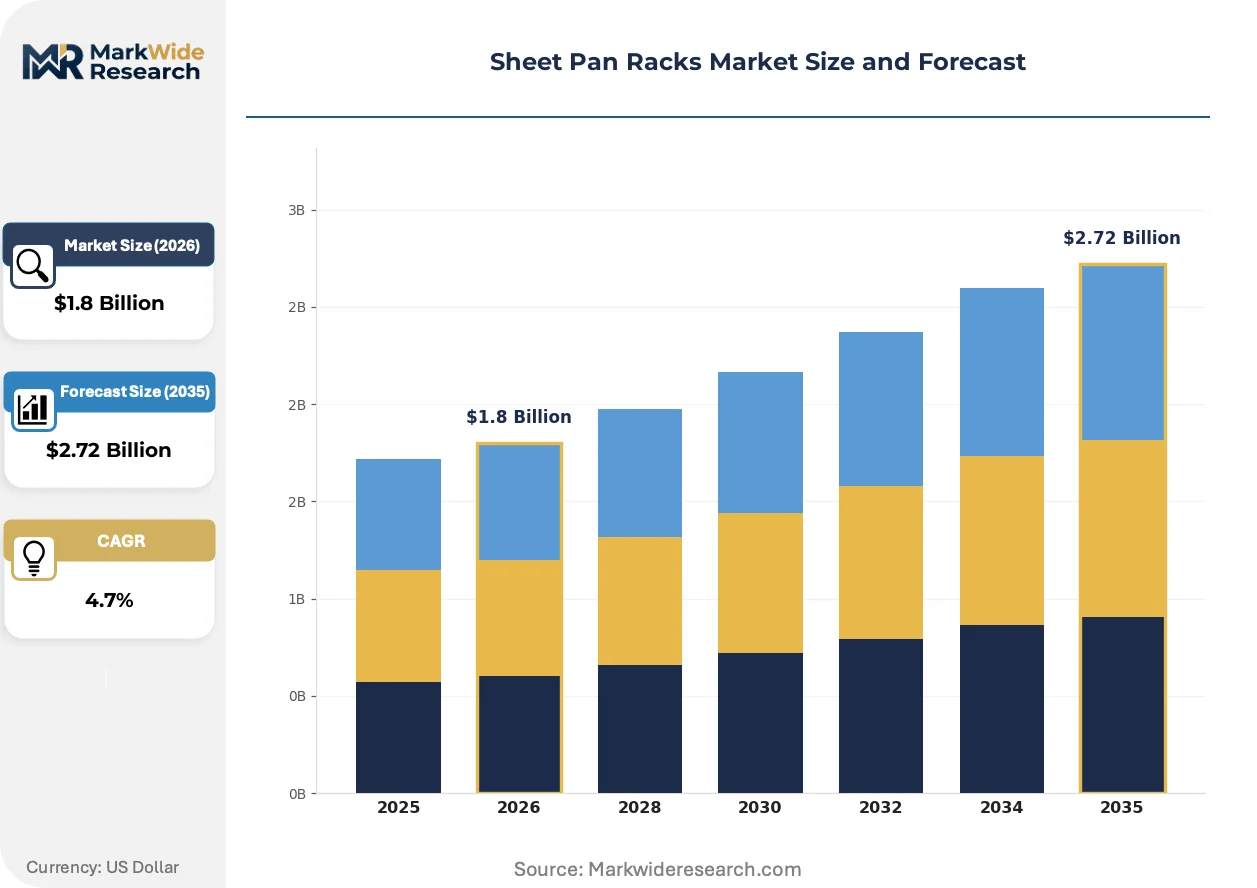
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Stainless Steel, Plastic Type: Mobile, Fixed, Stackable, Wall-Mounted End User: Restaurants, Bakeries, Catering Services, Food Trucks Size: Single, Double, Triple, Custom |
| Companies Covered | Vollrath Company, Nordic Ware, USA Pan, Chicago Metallic, Wilton Brands, Browne Foodservice, Matfer Bourgeat, Schaumburg Specialties, AmGood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Pan Racks Market Strategic Shifts
Material science advances and regulatory tightening are compressing product lifecycles while opening specification tiers for hybrid construction and smart monitoring integration in commercial food production environments.
Modular aluminum-stainless hybrid racks are expanding into high-volume bakery chains seeking load capacity without full steel weight penalties. Regional producers in the Southeast are piloting these configurations for proofing-stage flexibility. This construction approach is expanding into price-sensitive tiers previously captured by pure aluminum stackables.
EPA energy-efficiency guidelines for commercial refrigeration equipment are pressuring rack suppliers to pre-integrate thermal monitoring and airflow optimization. Cold-chain bakery operators in California face the strictest compliance timelines. Fixed rack configurations with embedded sensor channels are capturing specification share in refrigerated storage retrofits.
Bakery procurement teams are consolidating vendor relationships around single-source NSF certification documentation to streamline state health department inspections. Multi-site operators are displacing fragmented local supplier networks with regional fabrication contracts. This concentration pattern is most visible among bread and pastry producers in the Midwest and Mid-Atlantic corridor.
Sheet Pan Racks Market Segmentation
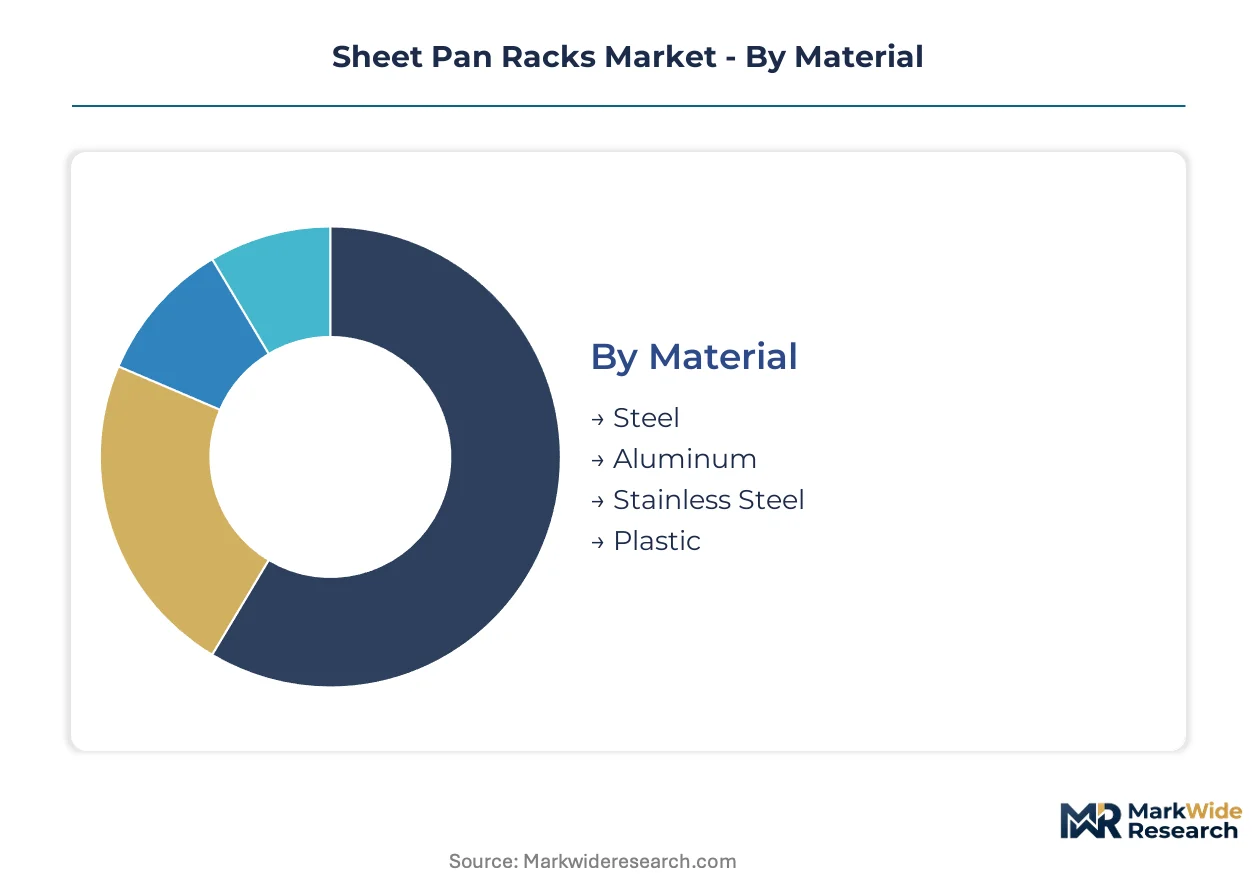
Sheet pan rack segmentation reflects divergent operational demands across commercial food production environments. Material specifications determine regulatory compliance pathways, while mobility configurations align with floor-space economics and workflow sequencing. Procurement teams segment purchases by end-use intensity and pan-volume throughput rather than generic equipment categories.
Material:
Material selection pivots on food-contact surface regulations and load-bearing requirements, with fabrication standards tightening across institutional procurement.
- Stainless Steel:18- to 20-gauge welded construction delivers corrosion resistance and load ratings exceeding 800 pounds for mobile institutional units. Commercial bakery chains in the United States concentrate NSF-certified demand here, driven by FDA food-contact surface mandates and state health department inspection protocols in California, Texas, and New York.
- Aluminum:Tubing construction offers weight reduction and modularity for stackable configurations without floor-space commitment. Residential and startup bakery segments favor this tier, though nickel and chromium price volatility in stainless steel inputs periodically narrows the cost gap.
- Steel:Heavy-gauge aluminized designs anchor premium industrial applications requiring thermal stability across proofing-cooling sequences.
- Plastic:Polymer construction serves light-duty residential storage and temporary catering deployments with minimal load requirements.
Stainless steel leads on scale; aluminum leads on momentum.
Type:
Mobility configuration determines capital allocation patterns across kitchen workflow stages and greenfield facility planning.
- Mobile:Castor-mounted units enable line flexibility and rapid reconfiguration in restaurant kitchens prioritizing workflow efficiency. Castor hardware and brake specifications add cost but displace fixed configurations where spatial adaptability commands premium pricing.
- Fixed:Bolted or welded stationary racks dominate proofing and cooling stages in high-volume bread production. Commercial bakery chains scaling greenfield facilities specify these for load concentration and stability across multi-rack sequences.
- Stackable:Modular aluminum units capture cost-sensitive bakery startups seeking capacity expansion without permanent floor-space commitment.
- Wall-Mounted:Vertical space utilization for compact kitchen footprints, common in food trucks and urban restaurant back-of-house constraints.
Fixed configurations dominate bakery capital expenditure; mobile units are expanding most quickly into restaurant retrofit cycles.
End User:
End-use intensity shapes specification tiers, with sanitation certification requirements and volume throughput creating distinct procurement behaviors.
- Bakeries:High-volume bread and pastry producers drive fixed and stackable rack demand for proofing-cooling infrastructure. Multi-site operators consolidate vendor relationships around single-source NSF certification documentation to streamline state health department inspections.
- Restaurants:Kitchen workflow efficiency prioritizes mobile units with castor mounting for line flexibility. Front-of-house visibility in open-kitchen concepts occasionally drives premium finish specifications.
- Catering Services:Event-driven volume spikes favor stackable aluminum configurations for transport logistics and temporary deployment.
- Food Trucks:Severe space constraints concentrate demand on wall-mounted and compact mobile units with minimal footprint.
Bakeries lead on scale; restaurants lead on momentum.
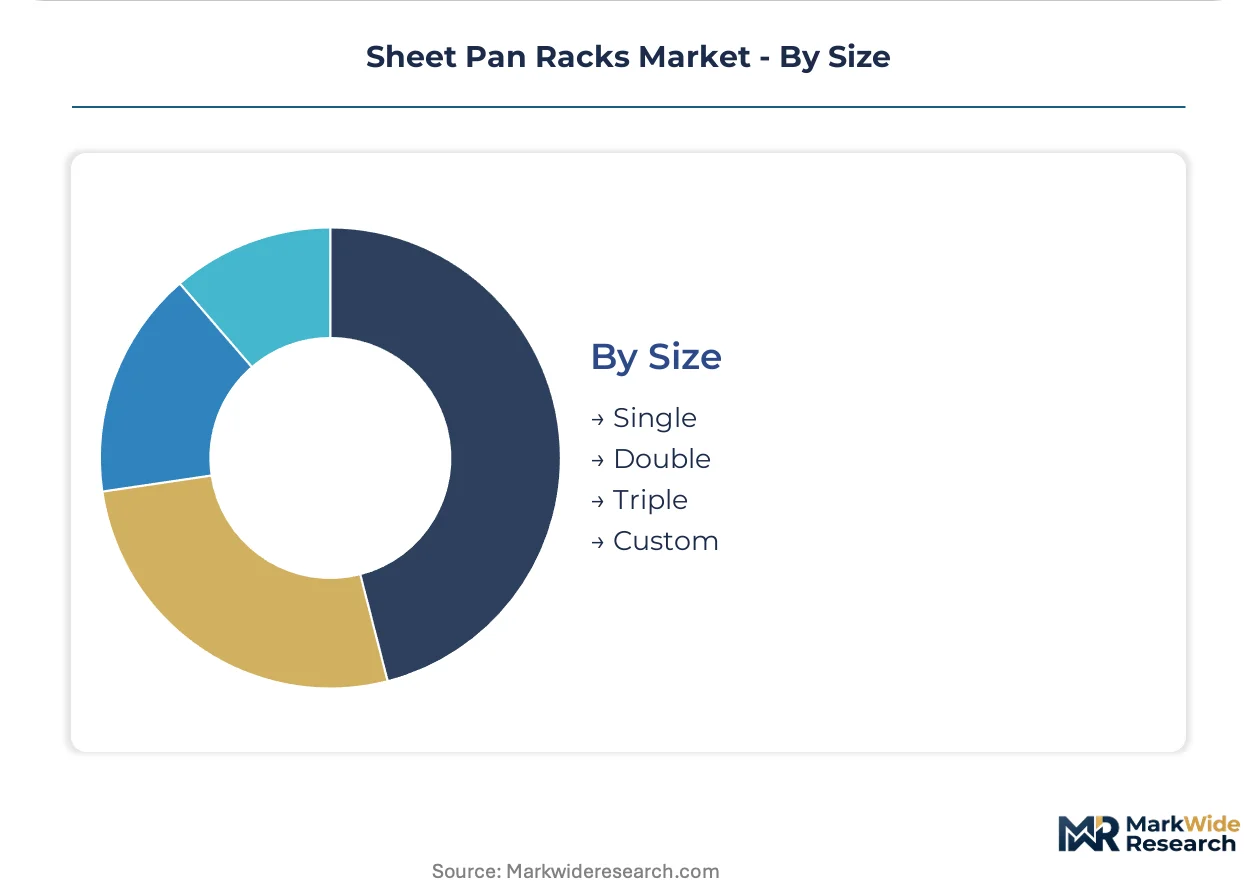
Size:
Pan-capacity configuration aligns with production batch economics and facility vertical clearance constraints.
- Double:Standard configuration balancing capacity against maneuverability for mixed-use commercial kitchens. Most common specification in institutional procurement.
- Single:Compact footprint for low-volume operations and auxiliary storage in space-constrained environments.
- Triple:Maximum density for high-throughput industrial bakeries with adequate ceiling clearance and automated retrieval systems.
- Custom:Non-standard dimensions for specialized pan formats or architectural constraints in retrofit installations.
Double racks lead on scale; custom configurations lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates commercial bakery infrastructure investment while Germany anchors European stainless steel fabrication standards for food-contact equipment.
United States
Commercial bakery chains in Texas and Florida are scaling proofing-cooling capacity faster than equipment replacement cycles. FDA food-contact surface regulations and NSF/ANSI Standard 2 certification tighten material compliance for 18- to 20-gauge welded construction. The Midwest manufacturing corridor, particularly Wisconsin-based fabricators, is reallocating capacity toward NSF-certified stainless steel rack production.
Germany
Industrial bakery equipment exports drive demand for heavy-gauge aluminized steel configurations with thermal stability across production sequences. REACH regulations and EU food-contact material standards shape welding finish and passivation protocols. The Baden-Württemberg precision engineering cluster specializes in automated rack retrieval systems for high-throughput facilities.
China
Domestic bakery chain expansion is absorbing modular aluminum-stainless hybrid rack configurations for cost-sensitive volume production. GB standards for food-contact metal surfaces and SAMR market supervision guidelines govern material certification. The Yangtze River Delta manufacturing base is scaling welded wire shelf production for export-oriented commercial kitchen equipment.
Italy
Artisan bread and pastry producers favor fixed rack configurations for traditional proofing stages in regional baking cultures. EU hygiene regulations and national health ministry inspection protocols enforce sanitation documentation across multi-site operations. The Emilia-Romagna food machinery district concentrates specialty fabrication for Mediterranean market specifications.
France
Premium bakery segments prioritize corrosion-resistant mobile units for open-kitchen visibility in retail concepts. ANSM food-contact material oversight and CNIL data governance frameworks affect sensor-integrated refrigerated rack pilots. The Île-de-France commercial kitchen equipment distribution hub channels specification demand from Paris-based bakery chain headquarters.
Sheet Pan Racks Market Competitive Environment
Wisconsin-based producers anchor the NSF-certified institutional tier; European specialists hold premium positions in thermal-stable industrial configurations. The vendor base separates into three functional tiers: domestic stainless steel fabricators serving high-volume bread producers, aluminum construction specialists capturing residential and startup bakery demand, and hybrid-format innovators testing modular combinations. Consolidation pressure is building around single-source certification documentation, while regional fabrication contracts displace fragmented local supplier networks.
Among Wisconsin-based fabricators, Vollrath Company exemplifies the domestic NSF-certified archetype through its manufacturing base proximity to Midwest bakery demand. Nordic Ware occupies a position within aluminum construction specialists serving residential and light commercial segments where weight reduction commands specification priority. Chicago Metallic anchors the premium industrial tier with heavy-gauge designs targeting high-throughput proofing-cooling infrastructure. These three represent distinct competitive vectors: certification compliance, material substitution, and load-capacity engineering.
| Leading Market Players |
|---|
| Vollrath Company |
| Nordic Ware |
| USA Pan |
| Chicago Metallic |
| Wilton Brands |
| Browne Foodservice |
| Matfer Bourgeat |
| Schaumburg Specialties |
| AmGood |
| Others |
Value Chain & Pricing Dynamics
Food-grade TIG welding certification requirements across Wisconsin fabrication clusters are simultaneously extending production cycles and concentrating supplier pricing power among NSF-certified domestic producers. Nickel and chromium input volatility feeds directly into fabrication margin compression, forcing buyers toward longer-term contract structures or aluminum substitution in cost-sensitive tiers.
Pricing Analysis
Capacity additions in Texas and Florida bakery clusters are reshaping price floors for fixed rack configurations as regional demand outpaces qualified domestic supply. Three-tier pricing structure across NSF-premium, standard-certified, and non-certified economy levels separates institutional procurement from startup bakery budgets. Pricing pressure stems from raw material volatility in 18- to 20-gauge stainless inputs, with commercial bakery chains least sensitive and residential buyers most responsive to aluminum alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin-based fabrication capacity for NSF/ANSI Standard 2 certified welding. Raw material flows draw from domestic steel mills, Chinese aluminum extrusion, and Canadian nickel processing. Tariff exposure on imported aluminum tubing threatens stackable unit cost structures. Distribution runs through regional commercial kitchen equipment distributors and direct contracts with multi-site bakery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sheet pan racks market reads as a late-cycle quality story where NSF certification documentation and food-grade welding finish standards displace commodity suppliers. Demand is concentrating toward premium specifications as state health departments in California, Texas, and New York tighten inspection protocols.
For Market Incumbents: Acquire TIG-certified welder talent pools and captive passivation capacity to defend against aluminum hybrid entrants. Consolidate fragmented regional distributor networks into single-source certification documentation contracts. Lock in multi-year offtake agreements with Texas and Florida bakery chains before greenfield capacity saturates pricing power. For New Entrants and Emerging Players: Capture refrigerated rack integration white space as EPA energy-efficiency guidelines compress cold-chain equipment replacement cycles. Target Southeast regional bakery clusters with modular aluminum-stainless hybrid configurations that bridge cost and load capacity. Lead with sensor-embedded fixed rack pilots for California compliance timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional NSF-certified fabricators because state health department inspection protocols create documentation moats that resist price competition. Five-to-ten year viability hinges on refrigerated system integration capabilities rather than standalone rack production. Watch for EPA cold-chain equipment rulemaking as the inflection signal for combined cooling-storage specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Investment | Documentation moats lock in California, Texas, and New York institutional procurement. |
| Refrigerated Rack Development | EPA energy-efficiency guidelines create specification white space for integrated systems. |
| Welder Talent Acquisition | Food-grade TIG certification scarcity constrains domestic fabrication capacity expansion. |
| Hybrid Material Configuration | Aluminum-stainless construction bridges cost-sensitive and load-capacity requirements. |
| Regional Distributor Consolidation | Single-source documentation contracts streamline multi-site bakery procurement. |
Study Parameters
Multiple input streams — primary interviews with bakery operations directors, commercial kitchen equipment procurement managers, and NSF certification auditors, alongside secondary validation through FDA food-contact surface guidance, state health department inspection protocols, and domestic steel trade association data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across material specifications, mobility configurations, and end-use intensity dimensions anchored volume and value modeling throughout the forecast period. CAGRs were derived from production capacity trajectories at Wisconsin fabrication clusters and greenfield bakery investment patterns in Sun Belt states.
Raw material price volatility, regulatory inspection timeline extensions, and welder certification bottlenecks are the dominant revision risks that could compress or extend equipment replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Ice Maker Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market