
 Commercial Panini Grills Market | 2026-2036
Commercial Panini Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Panini Grills Market Outlook
Multi-source component procurement is pivoting toward vertically integrated manufacturing among leading equipment makers. The Middleby Corporation leverages captive production of heating elements and control systems to protect margin pools. Hatco Corporation anchors its competitive stance through specialized conveyor configurations for high-throughput environments. Nemco Food Equipment differentiates via compact tabletop designs targeted at food trucks and mobile operators.
Commercial panini grills are electrically or gas-powered heated platen devices designed to apply simultaneous top and bottom contact heat at temperatures typically ranging from 175°C to 300°C, pressing and toasting bread-encased food items for rapid service. The equipment serves cafes, restaurants, and catering operations requiring consistent throughput of grilled sandwiches without dedicated kitchen ventilation infrastructure. Contact grills occupy the core volume position due to universal applicability across end-user tiers, while conveyor configurations capture premium pricing in high-throughput chains where labor minimization drives equipment selection. Electric power source variants lead unit shipments in urban settings with strict emissions codes, though gas models sustain demand in regions with lower utility costs and established natural gas hookups.
The US Department of Energy sets minimum efficiency standards for commercial kitchen equipment under its appliance and equipment standards program, while the EU Ecodesign Directive and CE marking requirements govern energy consumption and electrical safety for units sold across member states. NSF International certification shapes product access in North American foodservice by validating sanitation and materials safety for commercial kitchen equipment. Stakeholders must monitor evolving efficiency thresholds and electrification incentives as regulatory pressure intensifies on gas-powered alternatives.
Market Dynamics
Energy-efficiency mandates from the US Department of Energy and the EU Ecodesign Directive are compressing equipment replacement cycles and favoring electric-powered platen systems over legacy gas configurations across commercial foodservice operations.
Growth Catalysts
- EU Ecodesign Directive:Stringent energy consumption thresholds for commercial kitchen equipment are accelerating equipment turnover in member state cafes and quick-service restaurants, creating replacement demand for compliant electric panini grills.
- Artisanal panini culture in Italy:Independent cafes and small restaurant chains in Milan, Rome, and Florence are driving premium equipment upgrades, with operators prioritizing dual-platen precision and aesthetic stainless-steel finishes for front-of-house visibility.
- Quick-service restaurant expansion:Grilled sandwich menu proliferation across North American and European chains is expanding installed base requirements for high-throughput contact and conveyor configurations.
Market Restraints
- Heating element supply concentration:Captive production of ceramic and quartz heating elements concentrates among vertically integrated equipment manufacturers, limiting second-source options for mid-tier assemblers and creating input bottlenecks.
- Stainless steel price volatility:Food-grade 304 and 316 stainless steel inputs expose equipment margins to commodity swings, with sheet metal representing substantial bill-of-materials weight in premium platen assemblies.
- Natural gas infrastructure lock-in:Established gas hookups in older urban buildings and regions with subsidized utility rates create switching friction against electrification, delaying compliance-driven replacement timelines.
Strategic Opportunities
- Mobile foodservice channel:Compact tabletop designs targeting food trucks, stadium kiosks, and festival catering operations represent underpenetrated volume, with operators prioritizing portability and rapid heat-up over throughput maximization.
- US Inflation Reduction Act electrification incentives:Commercial kitchen equipment tax credits for electric alternatives are improving total-cost-of-ownership calculations for independent restaurant operators considering gas-to-electric conversions.
- Induction platen convergence:Integration of induction heating elements with traditional contact grill architectures offers precision temperature control and energy recovery, appealing to high-end cafe segments in Germany and France.
Industry Challenges
- NSF International certification timelines:Sanitation and materials safety validation for commercial kitchen equipment creates extended product launch cycles, compressing competitive response windows for new feature introductions.
- Control system integration complexity:Legacy kitchen management platforms in established restaurant chains resist seamless connectivity with smart grill diagnostics, limiting IoT-enabled predictive maintenance adoption.
- Skilled technician scarcity:Field service capacity for platen calibration, heating element replacement, and control board repair concentrates in metropolitan clusters, extending downtime for rural and secondary-market operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Panini Grills Market |
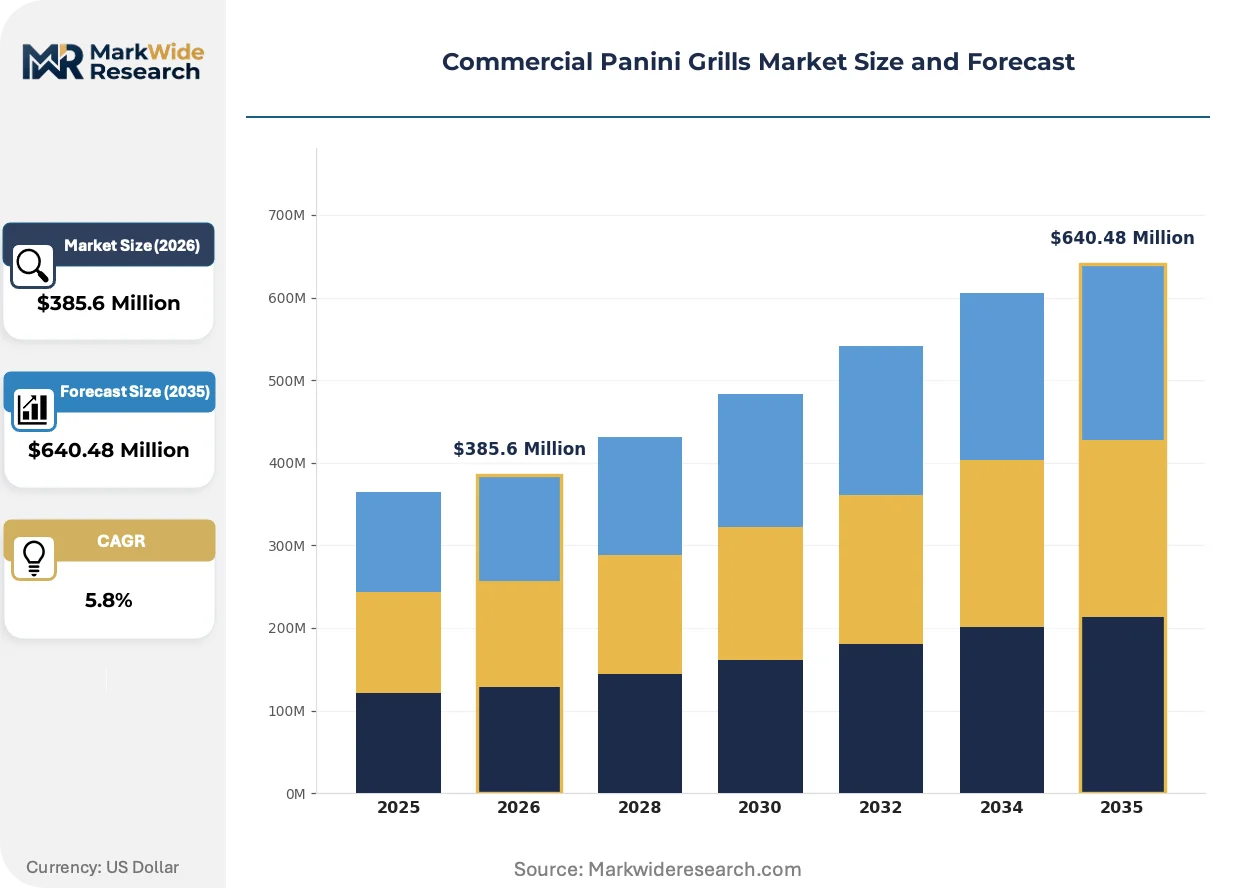
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Contact, Conveyor, Multi-Function End User: Cafes, Restaurants, Food Trucks, Caterers Power Source: Electric, Gas, Dual Fuel, Charcoal Size: Small, Medium, Large, Extra Large |
| Companies Covered | The Middleby Corporation, Welbilt, Inc., The Manitowoc Company, Inc., Hamilton Beach Brands Holding Company, Inc., Hatco Corporation, Nemco Food Equipment Company, The Vollrath Company, LLC, Sammic, S.L., Unox S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Panini Grills Market Strategic Shifts
Equipment architecture is pivoting toward modularity and connectivity, with manufacturers embedding sensors and software to differentiate commodity hardware and capture recurring service revenue streams.
Smart temperature control systems with embedded thermocouples and programmable logic controllers are consolidating operational consistency across multi-unit restaurant chains. Quick-service operators in the United States are adopting these systems to reduce training variance and standardize output across franchise locations. The technology is consolidating vendor relationships by tying equipment purchases to software subscription ecosystems.
The EU Ecodesign Directive's escalating efficiency thresholds are mandating standby power limits and heat recovery specifications for commercial contact grills sold across member states. Equipment manufacturers must redesign platen insulation and control electronics to maintain CE marking eligibility. Italian and Spanish cafe operators face compressed equipment amortization periods as non-compliant legacy units lose resale value.
Foodservice distributors are unbundling after-sales service from capital equipment transactions, shifting toward subscription-based maintenance and parts replacement models. Independent restaurant operators in France and Germany are accepting per-month service fees in exchange for guaranteed uptime and rapid technician dispatch. This restructuring is most visible in urban clusters where labor costs and equipment utilization rates justify premium service tiers.
Commercial Panini Grills Market Segmentation
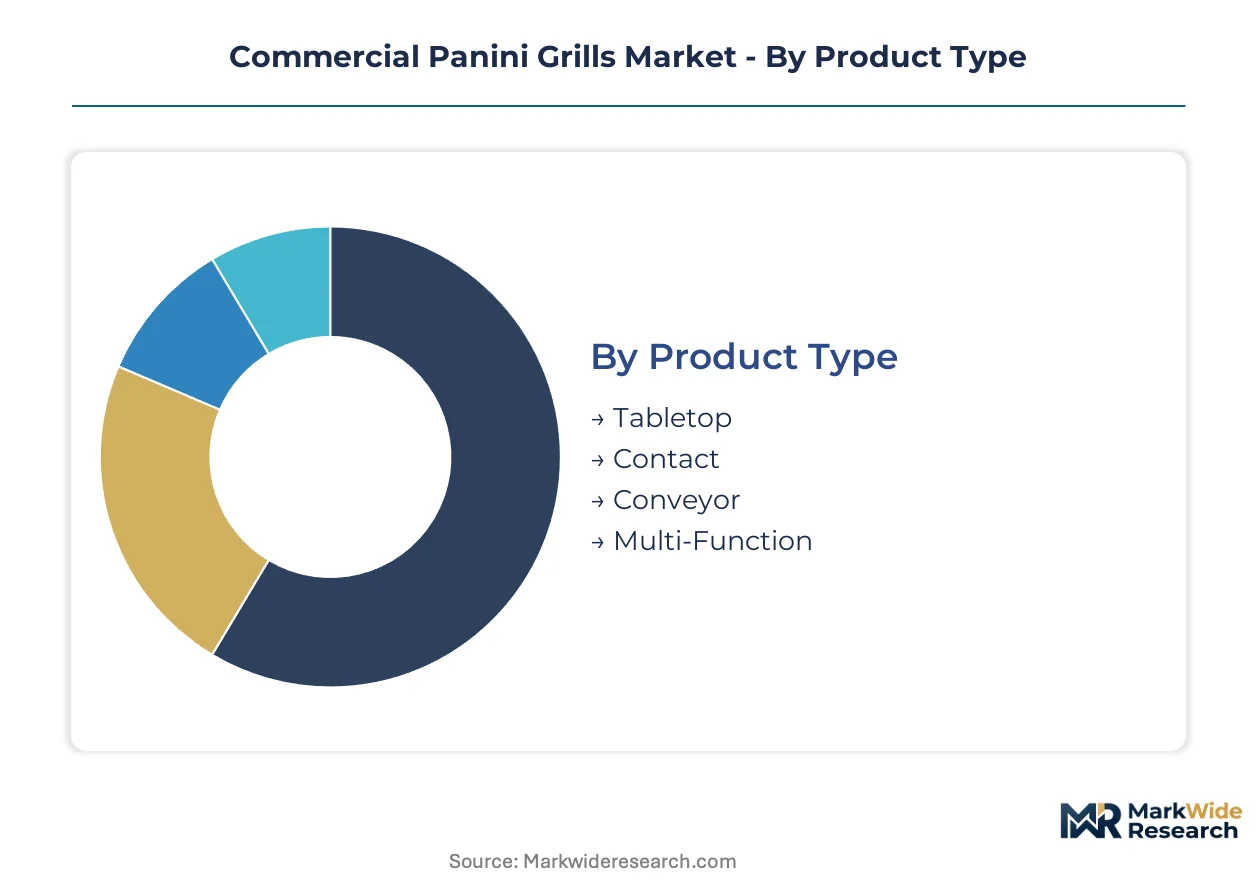
Segmentation in commercial panini grills reveals how equipment specifications align with distinct operational constraints. Kitchen footprint, power infrastructure, and throughput requirements drive divergent procurement patterns across foodservice tiers.
Product Type:
Heating architecture and platen configuration determine equipment utility across service formats.
- Contact:Dual-platen systems apply simultaneous top-bottom heat at 175°C to 300°C, delivering rapid cook times for bread-encased items. Demand concentrates in Italian independent cafes and small restaurant chains where front-of-house visibility and dual-platen precision justify premium positioning.
- Conveyor:Continuous belt configurations automate throughput for high-volume environments. Quick-service restaurant chains across the United States and Europe deploy these units to minimize labor touchpoints and standardize output consistency.
- Tabletop:Compact footprints suit mobile and space-constrained operations.
- Multi-Function:Modular attachments expand beyond sandwiches to proteins and flatbreads.
Contact configurations lead on scale; conveyor configurations lead on momentum.
End User:
Operational intensity and mobility requirements shape equipment selection priorities.
- Restaurants:Full-service establishments prioritize durable platen assemblies and NSF International certification compliance. Urban locations in Milan, Rome, and Florence drive premium stainless-steel finishes for open-kitchen visibility.
- Food Trucks:Mobile operators demand rapid heat-up and portability over throughput. Compact tabletop designs from specialized manufacturers target this channel with reduced electrical draw for generator compatibility.
- Cafes:Limited menus favor single-purpose contact units.
- Caterers:Event-based service requires rapid deployment and breakdown capabilities.
Restaurants anchor volume commitment; food trucks are climbing the fastest.
Power Source:
Energy infrastructure and regulatory pressure are reconfiguring procurement criteria.
- Electric:Platen systems with embedded thermocouples and programmable logic controllers dominate urban deployments. US Department of Energy efficiency mandates and EU Ecodesign Directive thresholds accelerate displacement of legacy alternatives in member state commercial kitchens.
- Gas:Natural gas hookups in older buildings and subsidized utility regions sustain residual demand. Established infrastructure in specific North American and Southern European markets creates switching friction against electrification timelines.
- Dual Fuel:Flexibility hedges against utility price volatility.
- Charcoal:Niche applications in specialty smoke-flavor segments.
Electric variants command installed base share; dual fuel options gain share fastest.
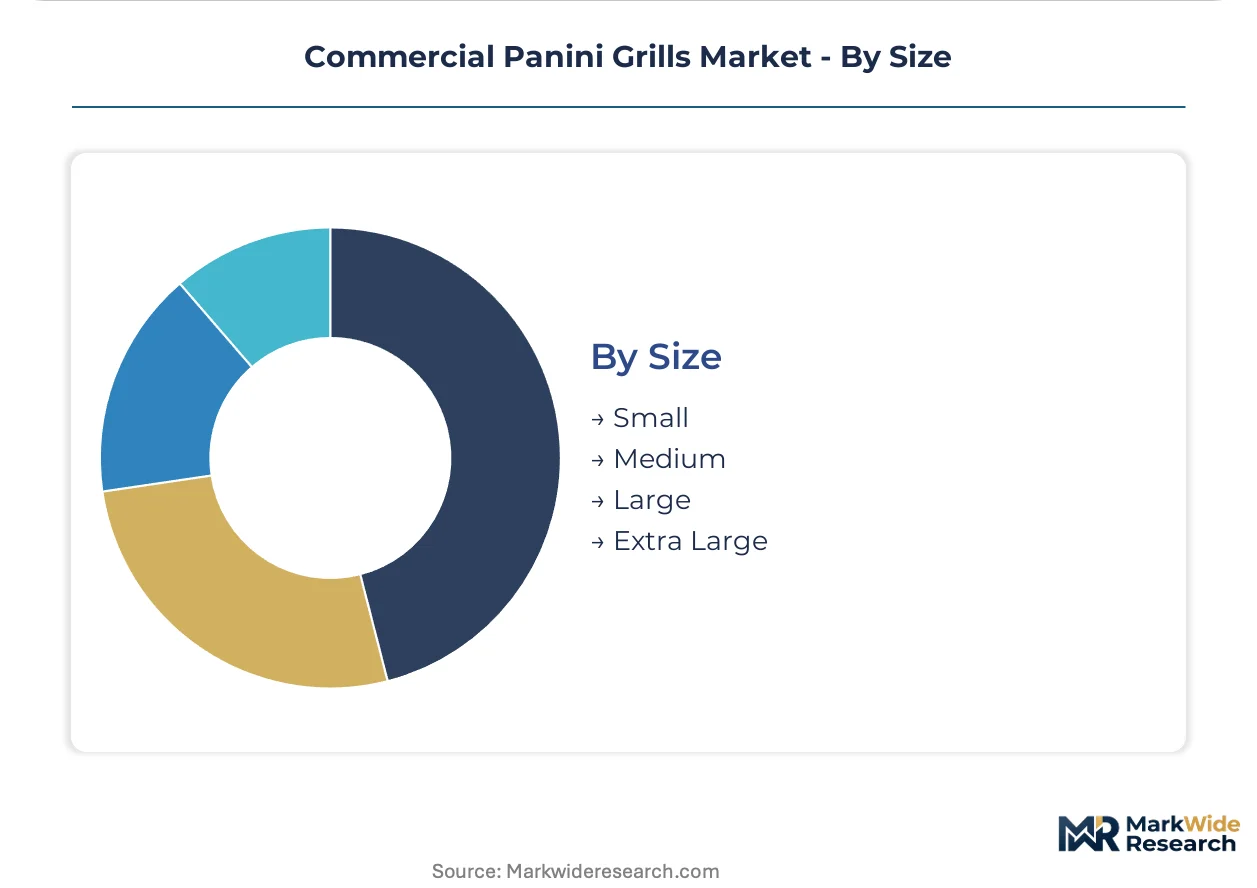
Size:
Platen dimensions correlate directly with throughput capacity and kitchen spatial economics.
- Large:Extended cooking surfaces serve high-throughput quick-service chains. Stadium kiosks and airport concession clusters in the United States deploy these units to manage peak-demand windows with minimal equipment footprint.
- Small:Reduced dimensions target independent operators with constrained prep lines. Food trucks and festival catering operations in France and Germany prioritize these configurations for rapid heat-up and storage efficiency.
- Medium:Balanced specifications serve mid-tier cafes and casual dining.
- Extra Large:Industrial-scale configurations for central commissary operations.
Large formats dominate capital deployment; small formats show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply across national regulatory regimes, with compliance cost differentials reshaping manufacturing footprints and export flows for commercial panini grill producers.
United States
Quick-service restaurant chains in Chicago, Atlanta, and Dallas-Fort Worth are expanding grilled sandwich menus, driving installed base growth for high-throughput conveyor configurations. US Department of Energy appliance standards mandate escalating efficiency thresholds for commercial kitchen equipment, compressing replacement cycles for legacy gas-powered units. California's Title 24 building codes and electrification incentives in New York State accelerate displacement of natural gas hookups in urban foodservice operations.
Italy
Independent cafes in Milan, Rome, and Florence sustain premium demand for dual-platen contact grills with aesthetic stainless-steel finishes suited to open-kitchen visibility. EU Ecodesign Directive energy consumption thresholds govern equipment eligibility for CE marking across member states, forcing redesign of platen insulation and control electronics. Artisanal panini culture in Emilia-Romagna and Tuscany drives recurring equipment upgrade cycles among small restaurant chains prioritizing front-of-house presentation.
Germany
Cafe operators in Berlin, Munich, and Hamburg are piloting induction platen convergence technologies that integrate precision temperature control with traditional contact grill architectures. The EU Ecodesign Directive's standby power limits and heat recovery specifications mandate compliance investments from equipment manufacturers serving German commercial kitchens. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate distributor networks unbundling after-sales service into subscription-based maintenance models.
France
Independent restaurant operators in Paris, Lyon, and Marseille are accepting per-month service fees for guaranteed uptime and rapid technician dispatch on panini grill fleets. CE marking requirements under EU electrical safety regulations shape product access for domestic and imported equipment. Food truck and festival catering operations in Provence-Alpes-Côte d'Azur prioritize compact tabletop configurations with reduced electrical draw for generator compatibility.
United Kingdom
Post-Brexit regulatory divergence complicates equipment certification for manufacturers serving UK and EU markets simultaneously, extending product launch timelines. London's dense urban foodservice sector favors electric-powered platen systems to comply with strict emissions codes and building ventilation constraints. NSF International certification remains a procurement criterion for chains with North American parent companies operating UK franchise locations.
Commercial Panini Grills Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized configurations for mobile and compact applications. The vendor base clusters around three maturity tiers: diversified kitchen equipment conglomerates with captive component production, mid-scale specialists concentrating on conveyor or contact architectures, and regional fabricators serving price-sensitive institutional accounts. Strategic differentiation hinges on backward integration into heating element supply, control system software ecosystems, and service revenue attachment rates. Capacity expansion and geographic licensing partnerships constitute the dominant competitive moves.
Among diversified equipment conglomerates, The Middleby Corporation, Welbilt, Inc., and The Manitowoc Company, Inc. exemplify scale-driven positions anchored in multi-product kitchen portfolios. These entities represent archetypes of vertical integration strategies, with in-house production of heating elements and control systems protecting margin pools against input volatility. Their market presence reflects consolidation patterns across commercial foodservice equipment, where breadth of offering and service network density determine procurement decisions from multi-unit restaurant chains.
| Leading Market Players |
|---|
| The Middleby Corporation |
| Welbilt, Inc. |
| The Manitowoc Company, Inc. |
| Hamilton Beach Brands Holding Company, Inc. |
| Hatco Corporation |
| Nemco Food Equipment Company |
| The Vollrath Company, LLC |
| Sammic, S.L. |
| Unox S.p.A. |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign Directive efficiency mandates are forcing rapid redesign of platen insulation and control electronics, compelling manufacturers to absorb compliance costs or pass them downstream and compressing margin pools for mid-tier assemblers lacking captive component supply.
Pricing Analysis
Input-cost pass-through from food-grade 304 and 316 stainless steel volatility shapes equipment pricing across tiers. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified conveyor systems for quick-service chains from basic contact units for institutional accounts. Pricing pressure stems from heating element supply concentration among vertically integrated conglomerates. Independent cafes in Italy exhibit lowest price sensitivity due to front-of-house visibility requirements; food truck operators in France and Germany face acute cost compression.
Supply Chain Analysis
Skilled technician availability in Baden-Württemberg, Emilia-Romagna, and Ohio manufacturing clusters constrains output scaling for precision platen assembly. Ceramic and quartz heating elements draw from captive production networks; stainless steel sheet metal feeds from commodity spot markets. Single-source vulnerability concentrates in control system microcontrollers. Distribution runs through foodservice equipment distributors unbundling after-sales service into subscription tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial panini grills market functions as a stable compounder anchored by regulatory-driven replacement cycles that ensure steady equipment turnover regardless of macroeconomic volatility.
For Market Incumbents: Acquire field service capacity in secondary metropolitan clusters to counter technician scarcity extending rural operator downtime. Deepen backward integration into thermocouple and programmable logic controller supply to defend margin pools against mid-tier assemblers. Prioritize CE marking pre-certification for redesigned platen architectures ahead of escalating EU standby power limits.
For New Entrants and Emerging Players: Induction platen convergence technology offers entry wedge into German and French high-end cafe segments underserved by legacy gas-to-electric conversion friction. Target compact tabletop configurations for food truck and festival catering channels where portability commands premium positioning. Pursue distributor partnerships with subscription-based maintenance unbundlers rather than capital equipment resellers.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing conveyor architecture expertise and nascent software subscription attachment. Long-term viability rests on service revenue capture rates exceeding hardware margin erosion. Monitor US Inflation Reduction Act electrification incentive uptake velocity as inflection signal for gas-to-electric conversion demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Middleby Corporation's captive ceramic element production protects margin pools against input bottlenecks. |
| Smart Temperature Control Platform Launch | Welbilt's embedded thermocouple ecosystems reduce training variance across US quick-service franchise locations. |
| Compact Tabletop Product Line Extension | Nemco Food Equipment's food truck-targeted designs capture underpenetrated mobile foodservice volume. |
| Subscription-Based Maintenance Unbundling | Hatco Corporation's per-month service fees guarantee uptime for French independent restaurant operators. |
| Induction Platen Convergence R&D | Unox S.p.A.'s precision temperature control appeals to German cafe segments prioritizing energy recovery. |
Study Parameters
Bottom-up foodservice operator modeling reconciled against top-down equipment manufacturer shipment tracking forms the analytical core of this study. Primary interviews with commercial kitchen procurement managers, restaurant chain equipment directors, foodservice distributor category buyers, and aftermarket service technicians combined with secondary validation from NSF International certification databases, US Department of Energy appliance standards filings, EU Ecodesign Directive compliance registries, and food-grade stainless steel commodity price indices. Triangulation across these sources ensures convergence between demand-side adoption patterns and supply-side capacity utilization.
Historical trendline analysis of replacement cycle compression and efficiency mandate phase-in schedules anchors the projection framework. Segmentation modeling spans product type, end user archetype, power source, and platen size dimensions across the analysis window. CAGRs derive from installed base turnover velocity, regulatory compliance deadlines, and electrification incentive uptake curves. Industry-specific inputs include EU member state cafe equipment upgrade frequencies and US quick-service grilled sandwich menu expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel commodity volatility, heating element supply disruptions, and skilled technician labor market tightness. Forecasts reflect documented assumptions regarding regulatory timeline adherence and infrastructure electrification pace. Material deviation in EU Ecodesign Directive enforcement stringency or US Inflation Reduction Act credit permanence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Restaurant Equipment Market