
 Rapid Cook-High Speed Ovens Market | 2026-2036
Rapid Cook-High Speed Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Cook-High Speed Ovens Market Analytics
Leasing and equipment-as-a-service arrangements is fragmenting capital barriers for mid-sized foodservice operators. TurboChef Technologies leverages its impingement patent portfolio to sustain premium positioning in North American quick-service chains. Rational AG anchors European demand through combi-oven technology leadership and deep channel relationships with institutional kitchens.
Rapid cook-high speed ovens integrate multiple heat transfer methods—convection airflow, microwave energy, and infrared radiation—to achieve cook times of one-tenth conventional cycles while maintaining surface browning and internal moisture retention. Combination ovens lead product type demand due to their versatility across proteins, baked goods, and rethermalization tasks, though impingement ovens are gaining share in high-throughput quick-service environments where throughput per square foot determines kitchen design. Countertop installations dominate new deployments as urban real estate costs force operators to minimize back-of-house footprints.
The US Department of Energy sets minimum efficiency standards for commercial cooking equipment, while the EU Ecodesign Directive and F-Gas Regulation constrain refrigerant-based cooling systems in combination units. China's GB standards and MIIT energy-labeling programs impose parallel efficiency thresholds on imported and domestically manufactured ovens. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid compliance-driven product fragmentation that could inflate certification costs and delay market entry.
Market Dynamics
Equipment-as-a-service financing models are collapsing capital barriers for mid-sized foodservice operators who previously deferred high-efficiency oven upgrades due to upfront cost constraints.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in combination oven cooling systems is accelerating replacement cycles across European institutional kitchens.
- Urban real estate compression:Quick-service restaurants in tier-one Chinese cities are prioritizing countertop installations to minimize back-of-house footprints as commercial rents escalate.
- Impingement airflow engineering:Jet-focused heat transfer technology is reducing cook times by an order of magnitude while preserving moisture profiles in protein applications.
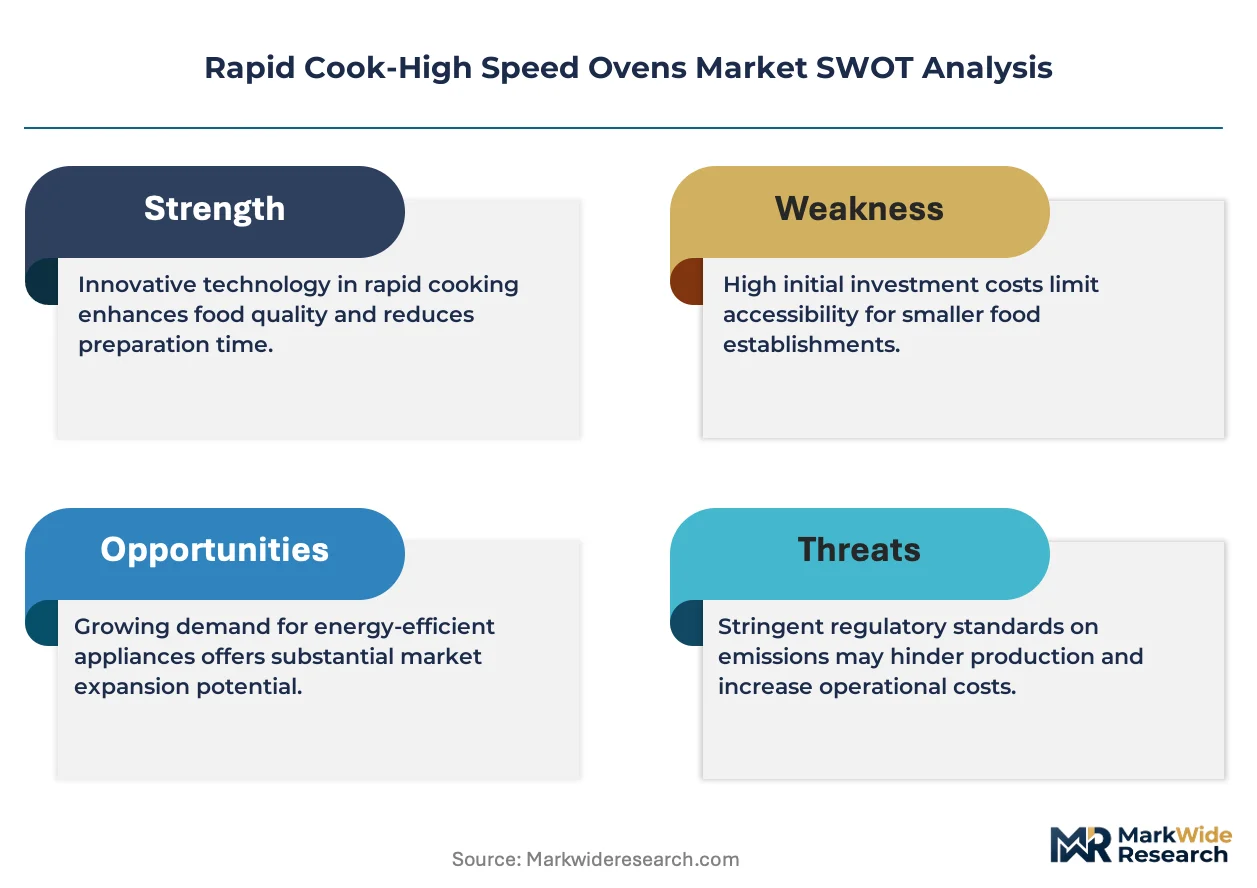
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium commodity pricing are compressing margins for oven chassis fabrication.
- Magnetron supply concentration:Microwave component sourcing remains geographically concentrated in East Asian manufacturing clusters, exposing buyers to single-region disruption risk.
- Electrical infrastructure retrofit costs:Three-phase power requirements for high-wattage units impose structural barriers in older commercial buildings lacking adequate utility capacity.
Strategic Opportunities
- India's QSR expansion:Standardized kitchen formats in Mumbai, Delhi, and Bangalore present undeveloped demand for compact rapid-cook solutions as Western fast-casual chains enter the market.
- Cloud kitchen proliferation:Delivery-only foodservice facilities are optimizing for throughput density and equipment modularity.
- US Department of Energy efficiency mandates:Tightening operational thresholds create regulatory tailwinds for manufacturers with advanced heat-recovery and insulation technologies.
Industry Challenges
- Multi-physics calibration expertise:Technicians capable of integrating convection, microwave, and infrared systems in field installations remain scarce relative to deployment timelines.
- Cross-jurisdictional certification timelines:Divergent efficiency testing protocols between US DOE, EU Ecodesign, and China MIIT requirements extend product launch windows.
- Legacy POS integration friction:Kitchen display system connectivity with existing restaurant technology stacks requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Cook-High Speed Ovens Market |
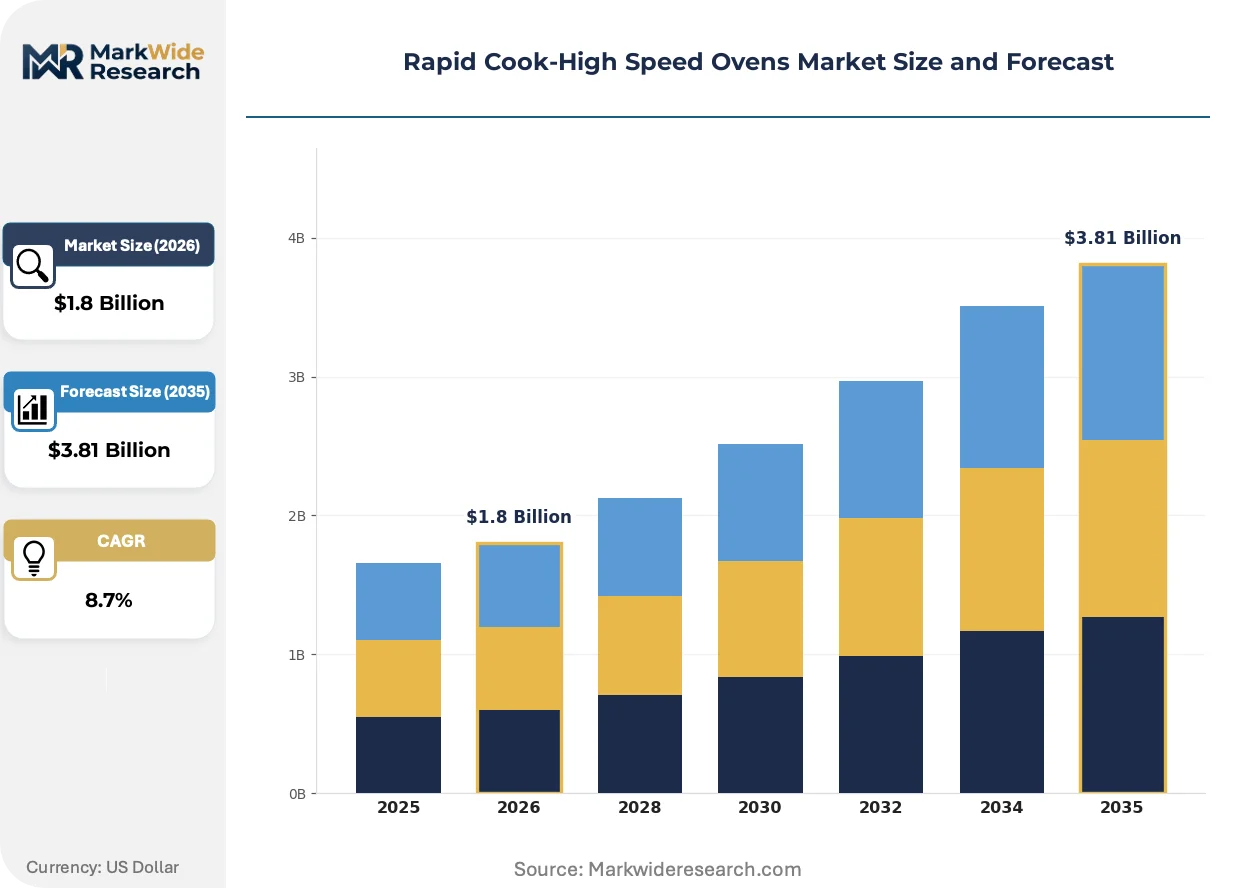
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Microwave Ovens, Combination Ovens, Impingement Ovens End User: Restaurants, Cafés, Catering Services, Food Trucks Technology: Infrared, Microwave, Radiant, Convection Installation: Built-in, Countertop, Standalone, Wall-mounted |
| Companies Covered | TurboChef Technologies, Merrychef, Electrolux Professional, Panasonic Corporation, Alto-Shaam, Rational AG, UNOX, Miele, Ali Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Cook-High Speed Ovens Market Evolving Landscape
Active thermal management and predictive maintenance algorithms are transforming oven lifecycle economics from capital depreciation models toward uptime-guaranteed service contracts.
Impingement airflow technology with jet-array nozzles is collapsing the performance gap between compact countertop units and full-size convection decks. Quick-service chains in high-throughput environments are adopting these systems to achieve protein throughput rates previously requiring double the kitchen footprint. The structural consequence is collapsing equipment redundancy requirements in new store builds.
The EU Ecodesign Directive's 2024 amendments impose standby power limits and mandatory heat-loss disclosures for commercial cooking equipment. Manufacturers serving European institutional buyers must redesign insulation packages and control board architectures to maintain market access. Combi-oven suppliers with integrated heat-recovery systems are capturing preferential positioning in German and French public procurement tenders.
Foodservice operators are unbundling after-sales service from initial equipment purchases, negotiating uptime guarantees and predictive maintenance subscriptions as separate line items. Distributor channels face margin compression as OEMs establish direct digital service platforms. This behavioral shift is most pronounced in North American quick-service franchise networks where corporate procurement offices centralize fleet-wide service agreements.
Rapid Cook-High Speed Ovens Market Segmentation
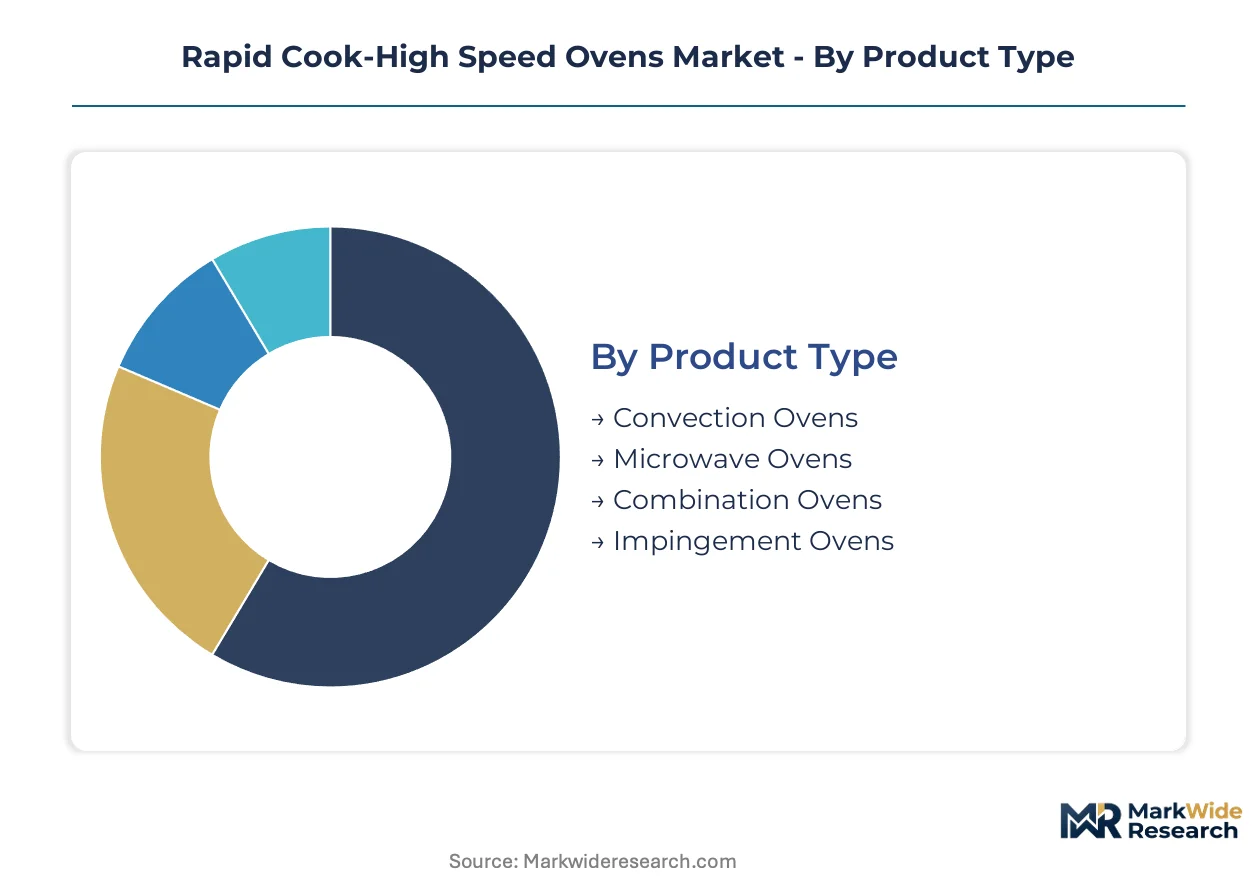
Segmentation in rapid cook-high speed ovens reveals how heat transfer physics, operational footprint constraints, and end-use workflow intensity create distinct product-positioning corridors. Each dimension below maps to specific procurement criteria that manufacturers must address to capture share across diverging foodservice environments.
Product Type:
Cost tier differentiation separates equipment categories by capital outlay, energy consumption profile, and versatility range across menu applications.
- Combination Ovens:These units integrate convection airflow, microwave energy, and infrared radiation in programmable sequences. Quick-service chains in China prioritize these systems for protein-bakery-rethermalization versatility across standardized kitchen formats in tier-one cities.
- Impingement Ovens:Jet-focused heat transfer arrays achieve cook times of one-tenth conventional cycles through forced convection. North American quick-service restaurants deploy these for throughput density where ticket compression determines kitchen design.
- Convection Ovens:Circulating heated air systems dominate entry-level installations in independent cafés with limited menu complexity and moderate volume requirements.
- Microwave Ovens:Magnetron-based units serve rethermalization-focused applications in catering services with pre-prepared meal workflows.
Combination ovens command the established base. The steepest expansion runs through impingement ovens.
End User:
Application intensity varies dramatically across customer types, with throughput volume and real estate flexibility driving diverging equipment specifications.
- Restaurants:Full-service and quick-service operators demand multi-functional units with programmable recipe storage. US Department of Energy efficiency mandates accelerate replacement cycles in corporate franchise networks seeking operational threshold compliance.
- Food Trucks:Mobile operators prioritize electrical load compatibility and compact footprints over maximum throughput. Three-phase power constraints in older urban infrastructure limit deployment of high-wattage units in this segment.
- Cafés:Limited-service formats favor countertop installations with rapid pastry warming and light meal preparation capabilities.
- Catering Services:Volume-batch operations require holding-capacity integration and transport-rack compatibility for off-site service logistics.
Restaurants anchor volume demand. Food trucks are gaining share fastest among emerging deployment categories.
Technology:
Heat transfer modality determines energy efficiency certification trajectories and technician calibration requirements across regulatory jurisdictions.
- Convection:Forced-air circulation with variable-speed fans enables precise temperature control. EU Ecodesign Directive standby power limits push manufacturers toward heat-recovery insulation packages in institutional procurement.
- Microwave:Magnetron-generated electromagnetic radiation penetrates food matrices for rapid internal heating. East Asian component supply concentration creates sourcing vulnerability for oven assemblers.
- Infrared:Radiant heat transfer achieves surface browning without convective drying. Premium protein applications in full-service restaurants leverage this for moisture retention.
- Radiant:Direct thermal radiation from heating elements supports simple, durable configurations in high-turnover environments with limited maintenance access.
Convection technology holds the installed base. Microwave integration is climbing the fastest as combination oven demand accelerates.
Installation:
Physical deployment configuration directly correlates with real estate cost pressure and kitchen workflow architecture decisions.
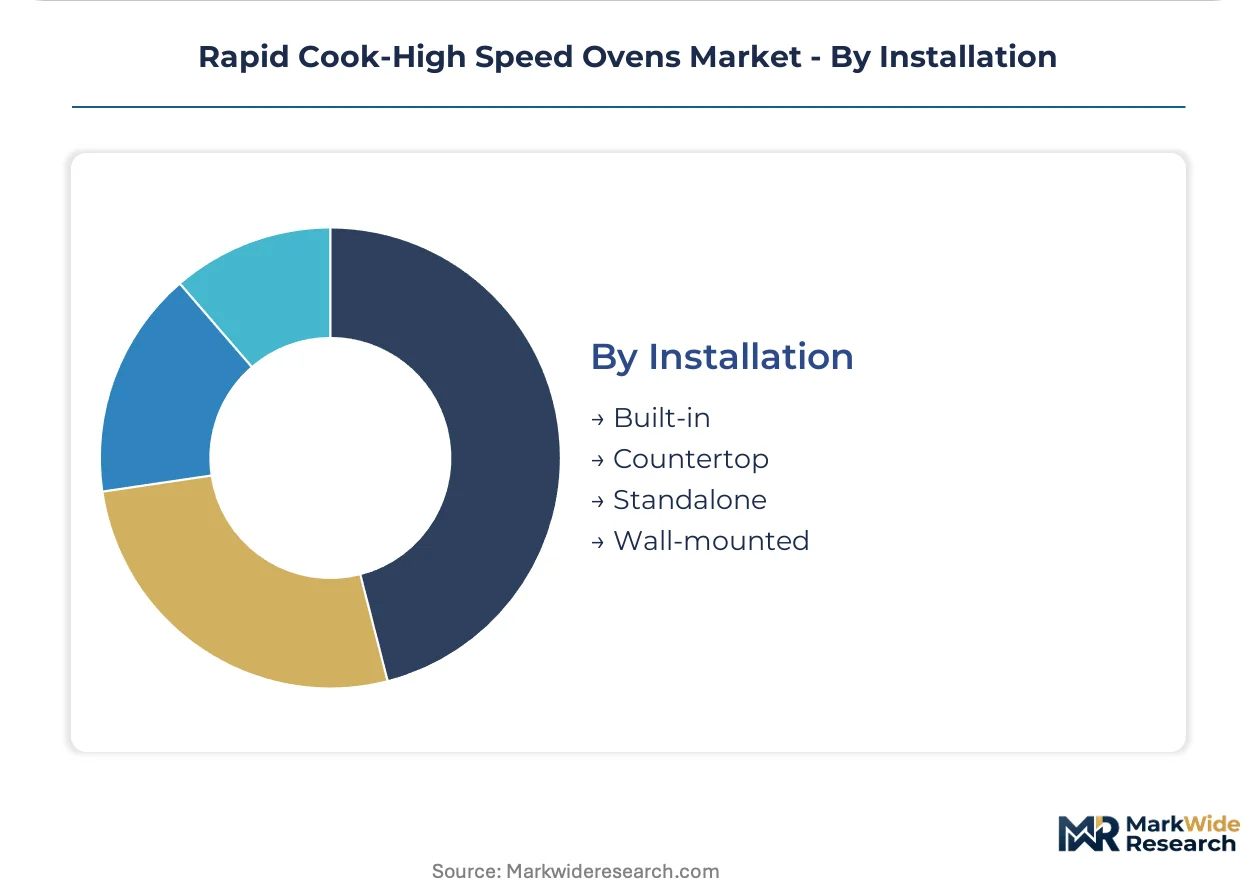
- Countertop:Compact units minimize back-of-house footprint in urban locations with escalating commercial rents. Tier-one Chinese cities prioritize these formats for standardized kitchen scaling.
- Built-in:Integrated cabinet installations align with front-of-house visibility requirements in fast-casual formats where equipment aesthetics influence customer perception.
- Standalone:Floor-mounted units with caster mobility serve catering and commissary operations requiring equipment repositioning across production shifts.
- Wall-mounted:Elevated installations recover vertical space in constrained kitchen geometries common in historic European building stock.
Countertop configurations dominate new deployments. Built-in installations are expanding most quickly as fast-casual chains emphasize visual kitchen design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German institutional procurement channels while Chinese operators extract volume discounts through centralized franchise purchasing. Japanese buyers absorb premium tiers for compact precision engineering. Indian QSR expansion creates price-discovery tension between imported and domestic assembly options.
United States
Quick-service franchise networks drive replacement cycles through corporate procurement offices seeking DOE compliance. The US Department of Energy tightens operational thresholds annually, forcing equipment turnover in legacy kitchens. Texas and Florida QSR clusters deploy countertop configurations to compress back-of-house footprints in high-rent urban corridors.
Germany
Institutional kitchens in public-sector catering anchor European demand for heat-recovery combi systems. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, accelerating replacement of cooling-integrated combination ovens. Bavarian equipment distributors capture preferential positioning in municipal tender processes through Ecodesign Directive pre-certification.
China
Standardized kitchen formats propagate across tier-one and tier-two cities as domestic chains scale franchise operations. MIIT energy-labeling programs impose parallel efficiency thresholds on imported and domestically manufactured units. Shanghai and Beijing operators prioritize countertop installations to minimize real estate costs in premium commercial zones.
Japan
Compact equipment engineering serves space-constrained urban foodservice in Tokyo and Osaka metro areas. METI efficiency standards and JIS certification requirements filter market access for foreign manufacturers. Kansai region quick-service operators adopt impingement systems for throughput density in narrow retail formats.
India
Western fast-casual chains entering Mumbai, Delhi, and Bangalore create undeveloped demand for rapid-cook solutions in standardized kitchen builds. The country's national food safety regulator enforces equipment hygiene standards that favor stainless-steel chassis suppliers. Cloud kitchen proliferation in Bengaluru accelerates procurement of modular, high-throughput equipment configurations.
Rapid Cook-High Speed Ovens Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in magnetron supply and airflow engineering. The vendor base stratifies between premium patent-holders, mid-market regional assemblers, and volume-driven contract manufacturers. Three archetypes dominate: technology licensors with impingement IP, combi-oven specialists with institutional channel depth, and diversified appliance conglomerates with captive distribution. Competitive moves concentrate on strategic partnerships for localized assembly and technology licensing to bypass import tariff exposure.
Within the technology licensor tier, TurboChef Technologies exemplifies premium positioning through patent-protected impingement architectures. Merrychef occupies a comparable position in European quick-service channels. Rational AG anchors the institutional-combi segment through deep relationships with German and French public procurement frameworks. These three represent divergent geographic anchoring and channel specialization strategies without overlapping customer segments.
| Leading Market Players |
|---|
| TurboChef Technologies |
| Merrychef |
| Electrolux Professional |
| Panasonic Corporation |
| Alto-Shaam |
| Rational AG |
| UNOX |
| Miele |
| Ali Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese microwave magnetron foundries is compressing component pricing and enabling aggressive equipment bundling by downstream assemblers serving cost-sensitive foodservice operators. This utilization slack simultaneously erodes supplier bargaining power and accelerates migration toward subscription-based equipment procurement models across North American quick-service franchise networks.
Pricing Analysis
The customization-premium spread separates configured-to-order combi-ovens with programmable recipe architectures from standard impingement units with fixed airflow patterns. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UL/CE certification grade and after-sales service bundling intensity. Pricing pressure stems from stainless steel input volatility as nickel and chromium commodity fluctuations compress fabrication margins. Independent café operators exhibit highest price sensitivity, while corporate QSR procurement offices absorb premium tiers for fleet-wide standardization.
Supply Chain Analysis
Contract-manufacturing concentration rests with EMS providers in China, South Korea, and Mexico that assemble magnetron housings and control board architectures for multiple OEM brands. Raw material dependencies center on nickel-alloy stainless steels, ceramic magnetron cores, and high-temperature insulation composites. Single-source vulnerability concentrates in East Asian microwave component clusters exposed to regional logistics disruption. Distribution runs through authorized dealer networks with captive service capabilities rather than direct OEM fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid cook-high speed ovens face substitution defense imperatives as conventional convection deck manufacturers integrate basic microwave modules at entry price points, threatening to commoditize the mid-market.
For Market Incumbents: Entrench patent-protected impingement architectures through aggressive licensing to regional assemblers, denying emerging competitors clean-room design pathways. Deepen backward integration into magnetron supply chains to insulate margin structures from East Asian component volatility. TurboChef Technologies exemplifies this posture through its captive IP enforcement and selective technology partnerships with institutional kitchen distributors. For New Entrants and Emerging Players: Establish a beachhead in India's cloud kitchen segment where Western fast-casual chains demand compact, modular equipment configurations without entrenched supplier relationships. Target Bangalore and Mumbai commissary operators with equipment-as-a-service financing that collapses capital barriers. Pursue white-label manufacturing partnerships with Chinese EMS providers to bypass import tariff exposure and accelerate price-competitive positioning. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory tailwind play because tightening DOE efficiency mandates and EU F-Gas phasedowns accelerate replacement cycles irrespective of macroeconomic softness. Target acquisition candidates with pre-certified heat-recovery combi platforms and established municipal procurement channel relationships in Germany and France. Monitor MIIT energy-labeling enforcement intensity in China as the critical inflection signal for import substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Patent holders monetize impingement IP through regional assembler agreements, expanding addressable market without capital deployment. |
| Equipment-as-a-Service Platform | Subscription financing collapses upfront barriers for mid-sized operators while generating recurring revenue streams. |
| Heat-Recovery System Integration | Pre-certified platforms capture preferential positioning in EU Ecodesign-compliant institutional procurement tenders. |
| Magnetron Supply Diversification | Multi-source component strategies mitigate single-region disruption risk exposed by East Asian manufacturing concentration. |
| Cloud Kitchen Channel Development | Direct relationships with delivery-only operators in Bengaluru and Mumbai bypass traditional distributor margin extraction. |
Research Methodology
Cross-validation between equipment distributor sales data and foodservice operator procurement records anchors the qualitative findings in documented transaction patterns. Primary interviews with commercial kitchen design consultants, QSR franchise development officers, and aftermarket service technicians combine with secondary validation through DOE efficiency certification databases, EU Ecodesign Directive compliance registries, and customs trade flow records. Bottom-up unit deployment estimates and top-down market size triangulation reconcile discrepancies across data sources.
Calibration against historical replacement cycle patterns and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include heat transfer modality, installation configuration, end-use intensity tier, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for policy-driven step changes in equipment turnover. Forecast inputs incorporate MIIT energy-labeling adoption curves and F-Gas Regulation phasedown schedules.
Sensitivities concentrate around stainless steel commodity volatility, magnetron supply disruption scenarios, and divergence in cross-jurisdictional certification timelines. Forecasts embed assumptions regarding regulatory enforcement consistency and franchise network standardization velocity. Quarterly review of DOE rulemaking dockets, EU Ecodesign amendment proposals, and China MIIT label expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Reach-In Refrigerators Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Specialty Commercial Deep Fryers Market