
 Warewashing Professional Equipment Market | 2026-2036
Warewashing Professional Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Warewashing Professional Equipment Market Outlook
Energy Star certification tiers and NSF/ANSI 3 sanitation benchmarks is bifurcating the competitive landscape into specification-grade and baseline equipment camps. Hobart GmbH leverages its captive stainless-steel fabrication network to control component quality from melt to final assembly. MEIKO Maschinenbau GmbH & Co. KG anchors its position through intensive R&D spending on heat-recovery architectures. Winterhalter competes by specializing in modular rack-conveyor systems tailored to high-throughput hotel kitchens.
Warewashing professional equipment encompasses commercial-grade machines engineered to sanitize dishware, glassware, and utensils through controlled cycles of pre-rinse, wash, rinse, and dry stages operating at temperatures between 82°C and 90°C for final sanitization. These systems serve institutional and foodservice operators where manual washing fails health-code throughput requirements. Conveyor washers dominate capital expenditure budgets in high-volume catering and hospital sectors where continuous-feed architecture minimizes labor touchpoints. Hybrid systems integrating heat-pump water recovery are capturing the fastest expansion trajectory as operators face escalating utility tariffs. Chemical-free cleaning technology remains nascent but occupies the highest margin pool due to consumable elimination and reduced wastewater treatment burdens.
NSF International standards govern machine construction and cleanability in North American jurisdictions, while the EU Ecodesign Directive mandates minimum energy and water efficiency thresholds for units sold across member states. The U.S. EPA ENERGY STAR program and EU F-Gas Regulation collectively pressure refrigerant-based drying systems toward lower-GWP alternatives, reshaping supplier R&D roadmaps. Stakeholders must monitor divergence between regional efficiency test protocols and refrigerant phase-down schedules when configuring product platforms for multi-territory deployment.
Market Dynamics
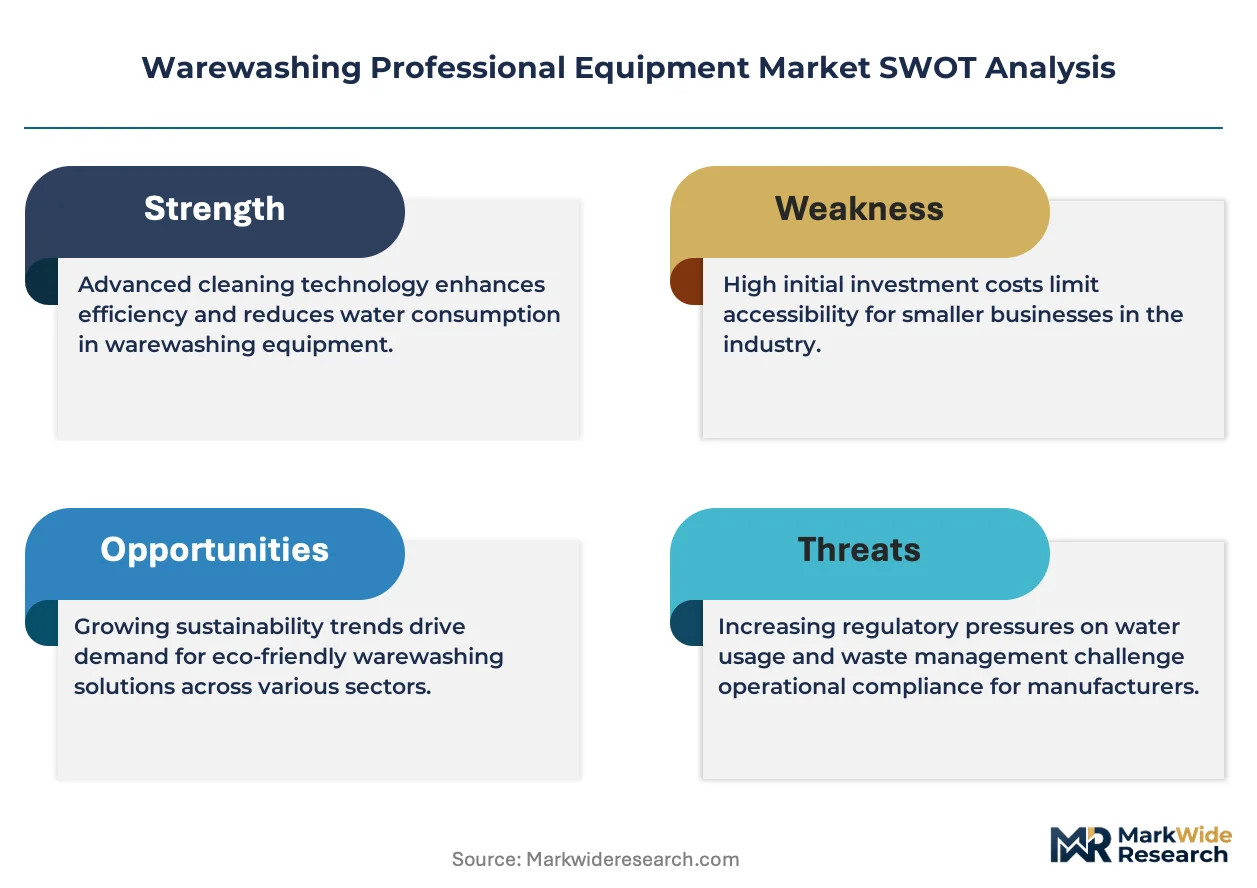
Regulatory tiering around ENERGY STAR 8.0 and EU Ecodesign is compressing equipment replacement cycles while fragmenting supplier capabilities between specification-grade and baseline production tiers.
Growth Catalysts
- Heat-pump water recovery:Full-service restaurant chains deploy hybrid architectures to neutralize escalating utility tariffs across high-throughput operations.
- EU F-Gas Regulation:Refrigerant phase-down mandates accelerate R&D investment in lower-GWP drying systems for multi-territory product platforms.
- Germany:Commercial kitchen density intersects with regulatory stringency to concentrate replacement demand in Central European markets.
Market Restraints
- Stainless steel input volatility:Captive fabrication networks face margin pressure from commodity price swings in melt-to-assembly supply chains.
- NSF/ANSI 3 certification friction:North American sanitation benchmarks create divergent test protocols that complicate unified product development.
- Manual washing substitution:Low-volume institutional operators retain hand-washing protocols where health-code throughput thresholds remain unenforced.
Strategic Opportunities
- Chemical-free cleaning:Consumable elimination and reduced wastewater treatment burdens open premium margin pools in environmentally sensitive jurisdictions.
- Modular rack-conveyor specialization:Hotel kitchen segments seek configurable throughput architectures adaptable to seasonal occupancy swings.
- EU Green Deal alignment:Efficiency incentive programs accelerate capital deployment cycles for Ecodesign-compliant equipment retrofits.
Industry Challenges
- Heat-recovery engineering scarcity:Specialized thermal architecture expertise concentrates among limited R&D-intensive suppliers.
- Legacy system integration:Conveyor washer retrofits face spatial and utility reconfiguration barriers in aged commercial kitchen infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warewashing Professional Equipment Market |
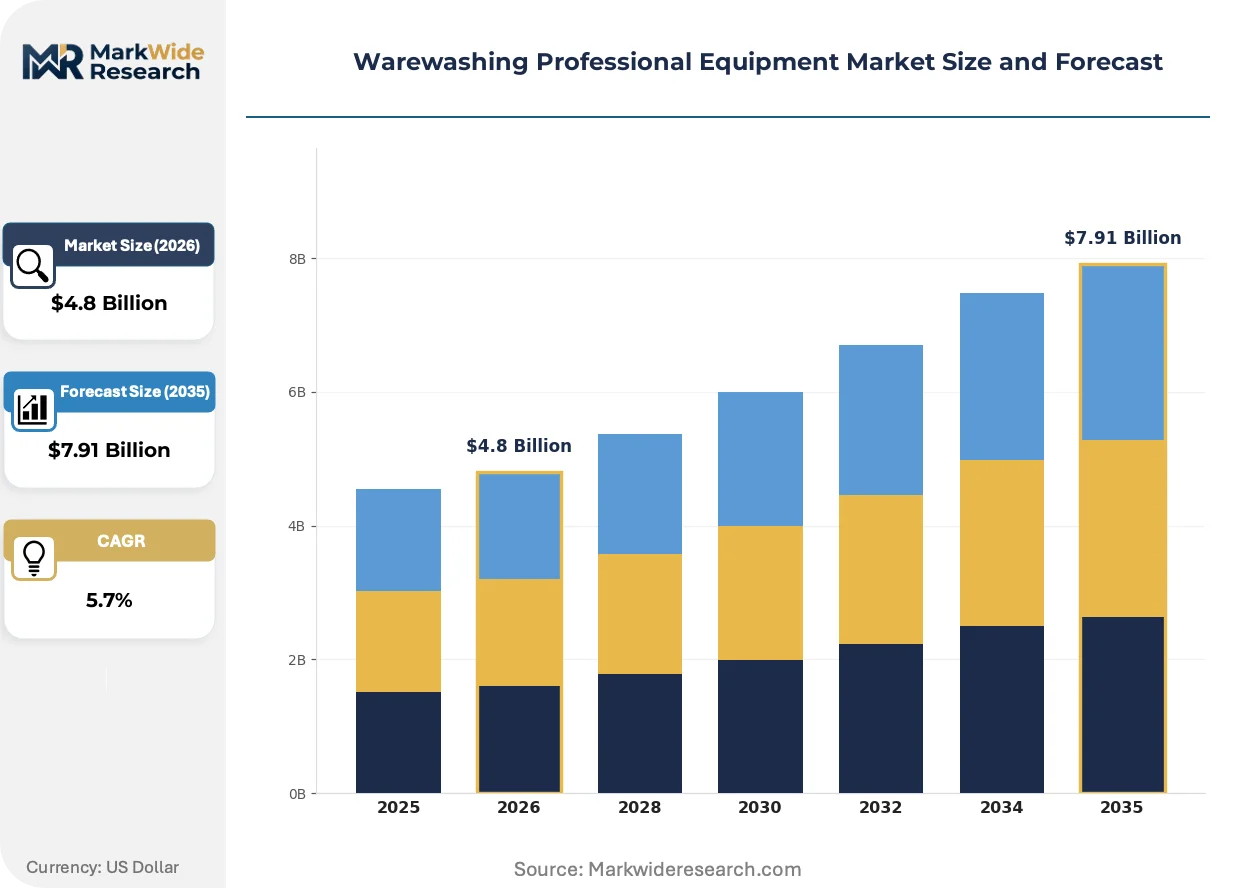
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
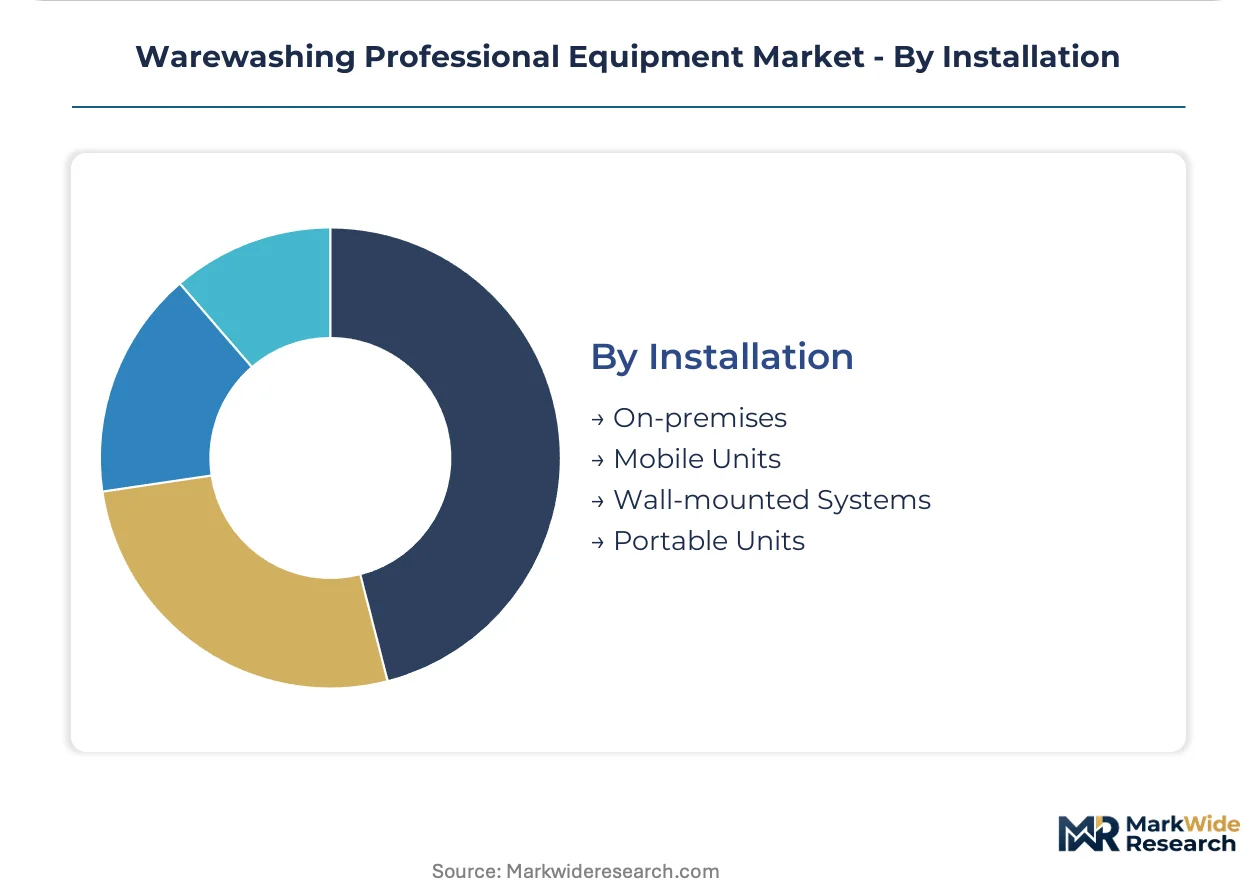
| Segmentation | Product Type: Dishwashers, Glass Washers, Under-counter Washers, Conveyor Washers Technology: Hybrid Systems, High-Efficiency Water Heating, Chemical-Free Cleaning, Automated Operations End User: Restaurants, Hotels, Catering Services, Institutions Installation: On-premises, Mobile Units, Wall-mounted Systems, Portable Units |
| Companies Covered | Hobart GmbH, MEIKO Maschinenbau GmbH & Co. KG, Miele & Cie. KG, Winterhalter, Ali Group, Electrolux, Jackson WWS, The Middleby Corporation, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warewashing Professional Equipment Market Strategic Shifts
Equipment architecture is pivoting toward resource-recovery systems while regulatory divergence between efficiency test protocols forces multi-platform engineering strategies.
Heat-pump water recovery technology is fragmenting competitive positioning between suppliers with captive thermal engineering capabilities and those dependent on outsourced component sourcing. Hospital and high-volume catering operators adopt these systems fastest where continuous-feed architectures minimize labor touchpoints. The technology is fragmenting capital expenditure planning as operators weigh upfront premium against tariff-driven operating cost compression.
EPA ENERGY STAR 8.0 specifications tighten minimum efficiency thresholds for final rinse and drying stages in United States jurisdictions. Equipment replacement cycles compress as operators face compliance deadlines for fleet standardization. Specification-grade suppliers capture disproportionate share of retrofit demand while baseline manufacturers retreat to price-sensitive segments.
After-sales service unbundling accelerates as institutional buyers separate equipment procurement from maintenance contracting. Third-party service networks displace manufacturer-captive technician deployment in mid-scale foodservice operations. Germany and Nordic markets exhibit fastest adoption where labor cost structures favor outsourced technical specialization over in-house engineering staff.
Warewashing Professional Equipment Market Segmentation
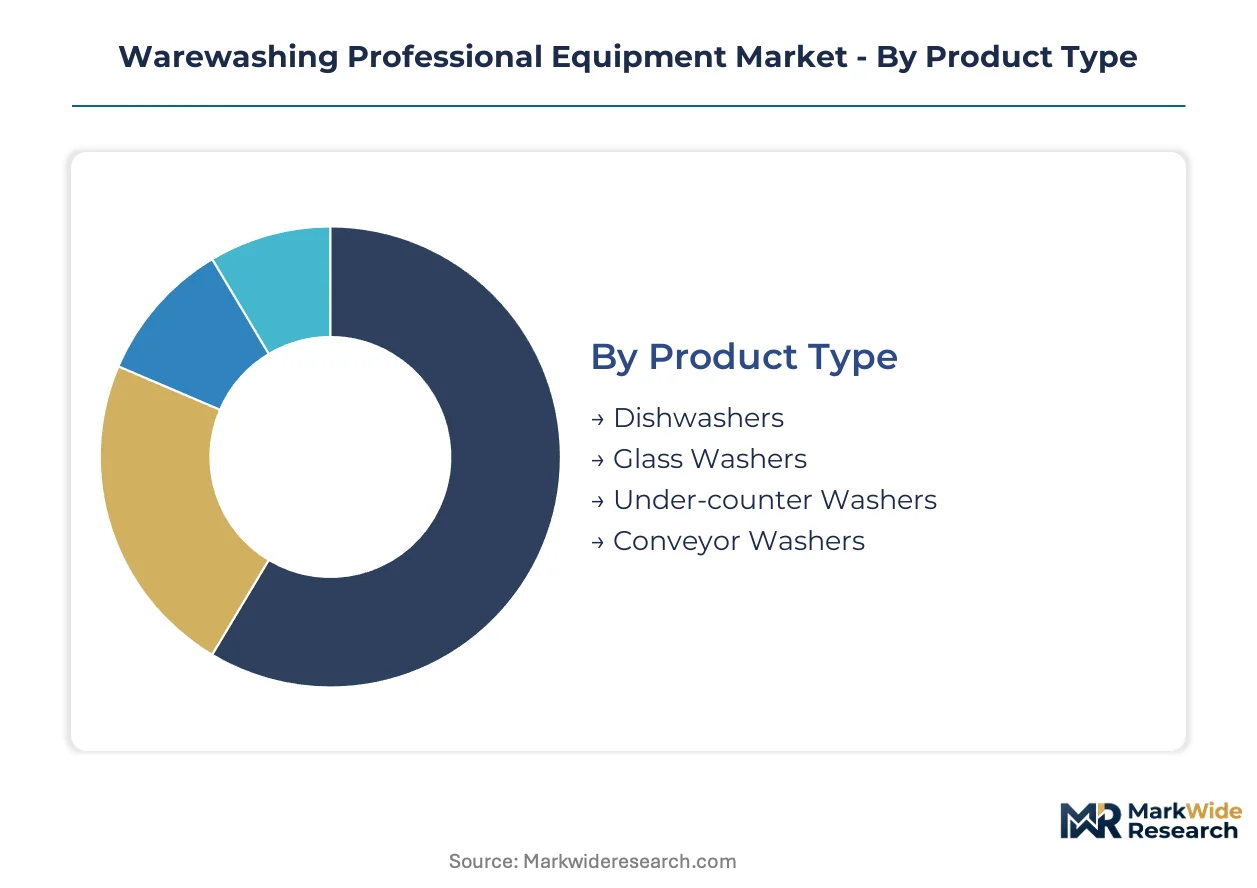
Segmentation in warewashing professional equipment reveals how procurement channels bifurcate between specification-grade distributors serving institutional buyers and general foodservice suppliers handling mid-scale operators. Channel alignment determines pricing leverage, certification requirements, and after-sales service bundling across each segment cluster.
Product Type:
Channel concentration varies sharply by equipment scale, with conveyor systems flowing through specialized dealers while under-counter units penetrate broadline foodservice distribution.
- Conveyor Washers:Continuous-feed architecture processes 200-400 racks per hour through multi-stage wash tunnels. Hospital and high-volume catering procurement concentrates in Germany and the United States where labor cost pressure justifies capital-intensive automation.
- Dishwashers:Door-type and rack-based configurations dominate full-service restaurant replacement cycles. EPA ENERGY STAR 8.0 compliance deadlines in the United States accelerate fleet standardization among multi-unit chains.
- Glass Washers:Specialized low-temperature chemistry preserves stemware integrity in hotel bars and tasting rooms.
- Under-counter Washers:Compact footprint suits independent restaurants and coffee shops with space-constrained kitchens.
By volume, dishwashers lead. By growth pace, conveyor washers are climbing the fastest.
Technology:
Margin stratification follows energy recovery sophistication, with heat-pump architectures commanding premium positioning against baseline electric-resistance systems.
- Hybrid Systems:Heat-pump water recovery captures exhaust thermal energy to pre-heat incoming supply water. Full-service restaurant chains in Germany deploy these units fastest where utility tariffs compress operating economics.
- Chemical-Free Cleaning:Ozonation and electrolyzed water systems eliminate detergent and rinse aid consumables. Scandinavian hotel operators adopt these systems where wastewater discharge regulations impose treatment cost burdens.
- High-Efficiency Water Heating:On-demand electric and gas-fired boosters reduce standby thermal losses compared to tank-based architectures.
- Automated Operations:Soil sensors and adaptive cycle programming minimize water and energy use per rack through real-time load detection.
By installed base, high-efficiency water heating dominates. By margin expansion, chemical-free cleaning is gaining share fastest.
End User:
Procurement authority concentrates differently across operator types, with institutional buyers leveraging centralized purchasing while independent restaurants rely on dealer recommendations.
- Restaurants:Full-service chains deploy automated warewashing fleets to neutralize escalating labor costs, while quick-service operators prioritize speed and footprint minimization.
- Hotels:Seasonal occupancy swings drive demand for modular rack-conveyor systems with configurable throughput. MEIKO and Winterhalter compete intensely in this segment across German-speaking markets.
- Catering Services:Mobile and temporary kitchen setups require rapid-deployment equipment with minimal utility connections.
- Institutions:Hospitals and universities mandate NSF/ANSI 3 sanitation certification and ENERGY STAR compliance in North American jurisdictions.
By unit shipments, restaurants lead. By specification intensity, institutions command the steepest certification requirements.
Installation:
Physical configuration determines retrofit feasibility in aged commercial kitchen infrastructure, with wall-mounted and portable options addressing spatial constraints that block conveyor washer deployment.
- On-premises:Fixed utility connections anchor high-throughput operations in purpose-built facilities with adequate floor drainage and ventilation.
- Mobile Units:Self-contained water and power systems serve outdoor catering, military field kitchens, and disaster relief operations.
- Wall-mounted Systems:Vertical orientation preserves floor space in compact urban kitchens where real estate costs constrain equipment footprints.
- Portable Units:Castor-mounted under-counter machines relocate between prep stations in multi-purpose foodservice environments.
By capital deployment, on-premises systems absorb the largest share. By flexibility premium, mobile units show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in warewashing equipment tilt toward net-exporting precision manufacturers in Central Europe and capital-importing foodservice operators across Asia-Pacific. Germany and Switzerland maintain structural surpluses in specification-grade machinery, while the United States and China absorb the largest import volumes for fleet replacement and new commercial kitchen construction respectively.
United States
Full-service restaurant chains drive replacement demand as ENERGY STAR 8.0 compliance deadlines compress equipment procurement cycles. The EPA program tightens efficiency thresholds for final rinse and drying stages, forcing multi-unit operators toward specification-grade suppliers. Chicago and Dallas-Fort Worth anchor the highest commercial kitchen density, with hospital and catering procurement concentrating in these metropolitan corridors.
Germany
Commercial kitchen density intersects with regulatory stringency to concentrate replacement demand in the largest European market. The EU Ecodesign Directive mandates minimum energy and water efficiency thresholds, accelerating retrofit cycles in institutional foodservice. Bavaria and North Rhine-Westphalia host the densest clusters of high-throughput hotel and hospital kitchens, driving specification-grade conveyor washer deployment.
China
Rapid foodservice expansion in tier-one cities absorbs imported specification-grade equipment alongside domestically manufactured baseline units. The country's national efficiency standards for commercial kitchen equipment tighten periodically, creating compliance-driven replacement windows. Shanghai and Beijing metropolitan areas concentrate the highest-value procurement for international hotel chains and central kitchen facilities.
Japan
Compact kitchen footprints in urban foodservice drive demand for space-efficient under-counter and wall-mounted configurations. METI-administered efficiency labeling programs for commercial equipment create tiered procurement incentives. The Kanto region around Tokyo anchors volume demand, while Osaka-Kobe industrial corridors concentrate domestic fabrication of precision wash systems.
United Kingdom
Post-pandemic hospitality recovery accelerates equipment refresh cycles in London and Southeast England hotel markets. The country's building regulations for commercial kitchen energy performance tighten enforcement timelines, compressing replacement decisions. Scotland and Northern England exhibit faster growth trajectories from lower installed-base saturation in institutional foodservice sectors.
Warewashing Professional Equipment Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized commercial kitchen engineering groups. The vendor base splits between specification-grade suppliers commanding premium positioning through certification depth and volume manufacturers competing on fleet standardization contracts. Two strategic archetypes dominate: captive fabrication networks controlling stainless-steel supply chains from melt to assembly, and R&D-intensive thermal engineering specialists commercializing heat-recovery architectures. Competitive moves center on backward integration into component manufacturing and geographic expansion through distributor acquisition in high-growth foodservice corridors.
Among German-based engineering groups, Hobart GmbH, MEIKO Maschinenbau GmbH & Co. KG, and Winterhalter occupy positions spanning the specification-grade tier. These entities exemplify divergent specialization vectors within premium market strata—captive metallurgical control, intensive thermal architecture development, and modular system configuration respectively. Their collective presence anchors Central European export competitiveness in institutional and hospitality procurement channels globally.
| Leading Market Players |
|---|
| Hobart GmbH |
| MEIKO Maschinenbau GmbH & Co. KG |
| Miele & Cie. KG |
| Winterhalter |
| Ali Group |
| Electrolux |
| Jackson WWS |
| The Middleby Corporation |
| Ecolab Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day stainless steel inventory cycles in captive fabrication networks compress pricing power for specification-grade suppliers when commodity melt costs spike. This lead-time exposure ties directly to how ENERGY STAR 8.0 compliance premiums propagate through distributor markups in the United States and EU Ecodesign-mandated retrofits across Germany.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in warewashing equipment procurement. Certification grade under ENERGY STAR and EU Ecodesign tiers, alongside volume scale in fleet replacement contracts, drive price differentiation between specification-grade and baseline manufacturers. Cost compression in standard-tier equipment is intensifying because stainless steel input volatility erodes captive fabrication margins. Quick-service restaurant chains exhibit highest price sensitivity due to footprint-constrained capex budgets, while hospital procurement committees show lowest sensitivity given NSF/ANSI 3 mandate compliance requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate German and Swiss specification-grade manufacturers facing stainless steel coil availability constraints from melt-to-assembly integration. Component sourcing draws from Germany, Italy, and China for precision pumps, heat exchangers, and control systems. Supply chain risk centers on single-source vulnerability in specialized thermal architecture engineering for heat-pump recovery systems. Distribution runs through specification-grade dealers serving institutional buyers and broadline foodservice distributors handling mid-scale restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-pump water recovery technology is reshaping competitive positioning in warewashing equipment as regulatory efficiency mandates compress replacement cycles across foodservice and institutional sectors.
For Market Incumbents: Shield specification-grade positioning by deepening captive stainless steel fabrication control and accelerating ENERGY STAR 8.0 certification depth ahead of compliance deadlines. Baseline manufacturers threaten margin compression through fleet standardization contracts with price-sensitive quick-service chains. Prioritize backward integration into heat-exchanger component manufacturing to secure thermal engineering scarcity premiums.
For New Entrants and Emerging Players: Lead with chemical-free cleaning technology deployment in Scandinavian hotel markets where wastewater discharge regulations impose treatment cost burdens on incumbent detergent-dependent systems. Chemical-free systems remain underpenetrated relative to their margin potential. Pursue direct partnerships with environmental certification bodies to accelerate credibility building against established ENERGY STAR-compliant suppliers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because efficiency mandate tightening across EPA and EU Ecodesign jurisdictions structurally advantages specification-grade engineering capabilities over commodity manufacturing. Target acquisition profiles should emphasize R&D-intensive thermal architecture specialists with proven heat-recovery commercialization track records. Watch for EU F-Gas Regulation phase-down acceleration as signal for lower-GWP drying system inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Technology Commercialization | Captures premium positioning as ENERGY STAR 8.0 tightens efficiency thresholds for final rinse stages. |
| Captive Stainless Steel Fabrication Expansion | Insulates margin structure from commodity coil price volatility in melt-to-assembly supply chains. |
| Third-Party Service Network Partnership | Aligns with after-sales unbundling trends in Germany and Nordic markets favoring outsourced technical specialization. |
| Chemical-Free Cleaning Platform Development | Opens premium margin pools through consumable elimination in environmentally sensitive Scandinavian jurisdictions. |
| Modular Rack-Conveyor System Configuration | Addresses hotel kitchen demand for seasonal throughput adaptability in German-speaking markets. |
Study Parameters
A standing panel of foodservice equipment procurement directors, commercial kitchen engineering consultants, NSF/ANSI certification specialists, and aftermarket service network managers provided ongoing calibration against secondary validation from EPA ENERGY STAR program filings, EU Ecodesign Directive technical documentation, SEC 10-K disclosures from diversified industrial conglomerates, and customs trade data for stainless steel component flows. Bottom-up shipment modeling triangulated against top-down replacement cycle analysis across institutional and foodservice operator segments.
Consistency checks validated volume and value outputs against external efficiency program enrollment databases and commercial kitchen construction permit series across the analysis window. Segmentation dimensions modeled include equipment type, technology tier, end-user category, and installation configuration. CAGRs derived from regression analysis of replacement cycle compression rates and regulatory compliance deadline clustering. Industry-specific inputs incorporated utility tariff trajectories and stainless steel price index movements.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of ENERGY STAR 8.0 and EU Ecodesign efficiency thresholds would require recalibration. Forecasts reflect assumptions regarding commercial kitchen density growth and institutional procurement centralization patterns. Revision becomes warranted when F-Gas Regulation phase-down schedules accelerate or stainless steel input volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Food Service Equipment Market