
 900 Series Cooking Equipment Market | 2026-2036
900 Series Cooking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
900 Series Cooking Equipment Market Outlook
Modular bundling of 900 Series platforms is recalibrating how commercial kitchens configure cooking lines, moving buyers away from standalone purchases toward integrated workstation packages. Ali Group S.r.l leverages its portfolio breadth to anchor European supply relationships with large catering contractors. The Middleby Corporation sustains North American dominance through captive distribution and in-house production of combustion systems. Illinois Tool Works Inc. differentiates via precision temperature control technology embedded across its fryer and griddle lines.
900 Series cooking equipment denotes professional-grade appliances built to a standardized 900mm width, typically fabricated from AISI 304 stainless steel with burner outputs ranging from 7 kW to 28 kW, designed for high-throughput commercial food preparation in continuous-service environments. The equipment serves restaurants, institutional kitchens, and hospitality operations requiring durable, standardized platforms that integrate into ergonomic cooking suites. Fryers and hybrid technology configurations capture expanding margin pools as operators prioritize oil-efficiency and dual-fuel flexibility. Electric induction segments within the technology dimension are gaining share where grid infrastructure supports high-amperage drops, while gas variants retain cost advantages in markets with pipeline density.
The U.S. Department of Energy enforces minimum efficiency standards for commercial cooking equipment, directly shaping product development timelines and certification costs for manufacturers accessing the American market. In Europe, the Ecodesign Directive and CE marking requirements under the EU's F-Gas Regulation constrain refrigerant-based equipment configurations and drive R&D toward alternative thermal systems. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building-code electrification mandates that will determine viable technology mixes in key procurement regions.
Market Dynamics
Modular workstation bundling is compressing standalone equipment demand as full-service restaurant chains consolidate vendor relationships around integrated 900mm cooking suites. This structural shift rewards manufacturers with portfolio breadth and captive combustion technology.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates under this framework are accelerating replacement cycles for gas-fired equipment across German and UK commercial kitchens.
- Hybrid fuel flexibility:Dual-fuel configurations are capturing margin expansion as operators seek operational hedging against volatile utility tariffs.
- Premium hotel refurbishment:The United Kingdom's hospitality segment is driving above-average equipment turnover with standardized 900mm platform specifications.
Market Restraints
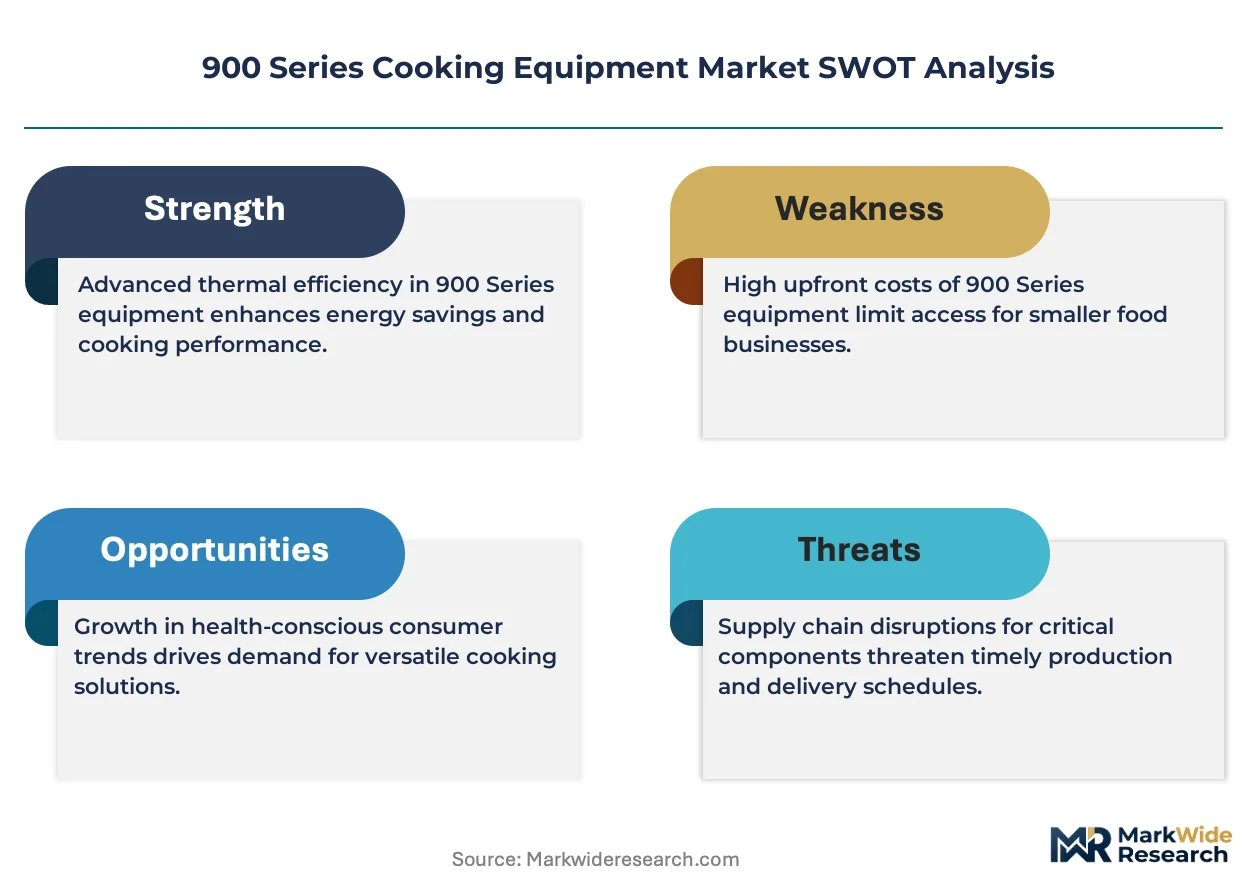
- AISI 304 stainless steel volatility:Input cost swings for nickel-alloy sheet metal compress fabrication margins and destabilize contract pricing.
- High-amperage infrastructure gaps:Electric induction variants face deployment constraints where grid capacity lags in secondary urban markets.
- F-Gas Regulation compliance:Refrigerant-based thermal systems face phase-down timelines that strand R&D investment in legacy configurations.
Strategic Opportunities
- Electrification mandates in new construction:Building code revisions in California and New York are creating specification pull for all-electric cooking lines.
- Oil-efficiency technology convergence:Advanced filtration integrated with fryer controls opens premium positioning in QSR and fast-casual segments.
- Cloud kitchen density:Ghost kitchen operators in London and Berlin are adopting compact modular suites for rapid deployment.
Industry Challenges
- Combustion systems engineering talent:Specialized expertise for burner optimization and emissions tuning is concentrating at legacy manufacturers.
- UL and CE dual certification timelines:Parallel safety testing for North American and European market access extends product launch cycles.
- Legacy kitchen integration complexity:Retrofit installations face spatial constraints and utility reconfiguration costs in established restaurants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 900 Series Cooking Equipment Market |
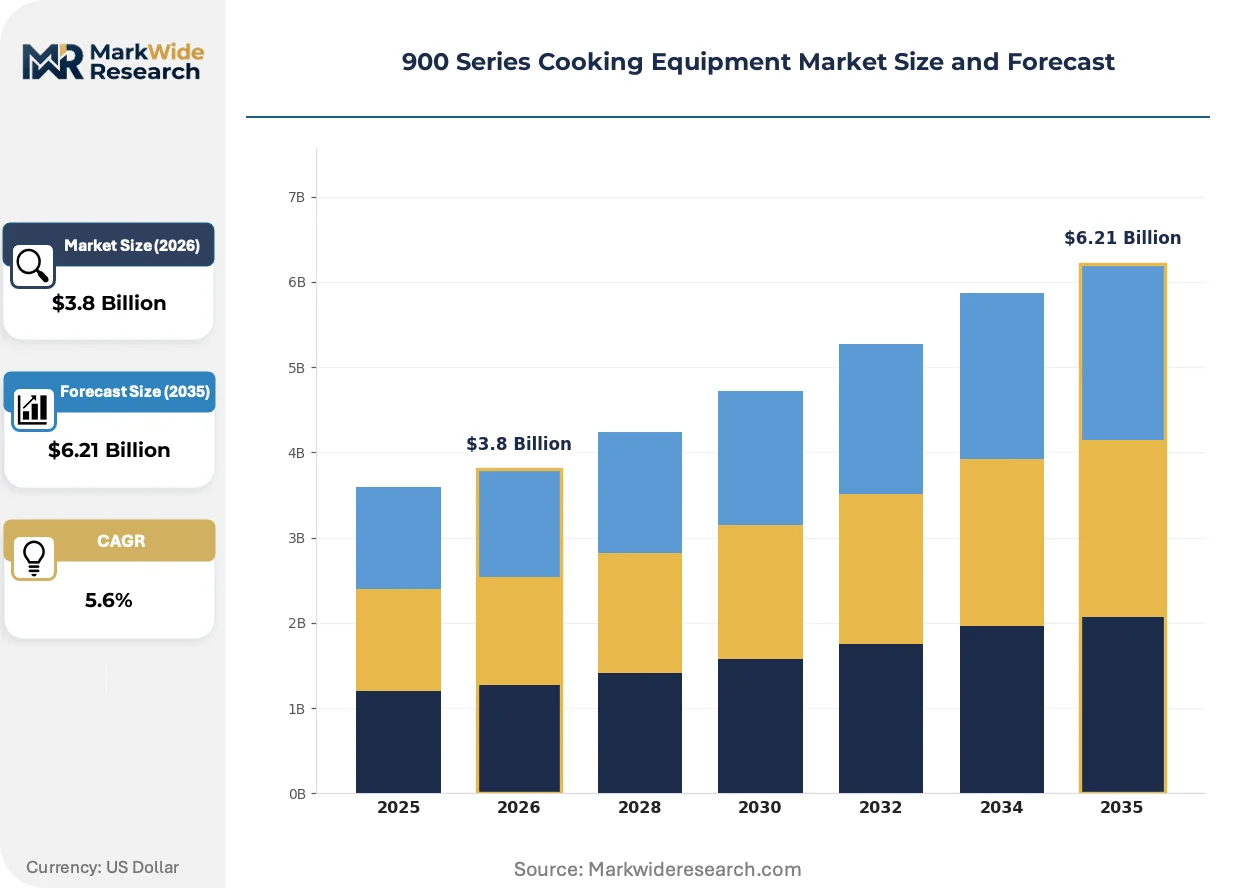
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fryers, Grills, Ovens, Steamers End User: Restaurants, Cafes, Catering Services, Hotels Installation: Built-in, Modular, Portable, Custom Technology: Gas, Electric, Induction, Hybrid |
| Companies Covered | Charvet, Capic, Ali Group S.r.l, AB Electrolux, ATA Srl, Fagor Professional, Illinois Tool Works Inc., MKN Maschinenfabrik Kurt Neubauer GmbH & Co. KG, The Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
900 Series Cooking Equipment Market Strategic Shifts
Active thermal management and connectivity integration are redefining equipment value propositions. Manufacturers are embedding precision control systems and data capture capabilities that transform capital goods into networked kitchen infrastructure.
Induction technology is electrifying commercial cooking lines by delivering instantaneous thermal response without combustion byproducts. Full-service restaurant chains in Germany and the Netherlands are specifying induction ranges for new flagship locations. This shift is compressing demand for conventional gas burner assemblies and redirecting R&D investment toward power electronics and coil design.
The U.S. Department of Energy's amended commercial cooking equipment standards are tightening minimum efficiency thresholds for fryers and griddles. Manufacturers must redesign heat exchangers and insulation systems to maintain market access. Electric variants are gaining specification share in California and Massachusetts where state-level electrification incentives layer atop federal mandates.
Equipment-as-a-service contracting is displacing traditional capital purchase models among multi-unit operators. Large catering contractors are unbundling maintenance and performance guarantees from hardware acquisition. This pattern is most pronounced in the United Kingdom's contract foodservice sector, where kitchen refurbishment programs favor operational expenditure structures over upfront equipment investment.
900 Series Cooking Equipment Market Segmentation
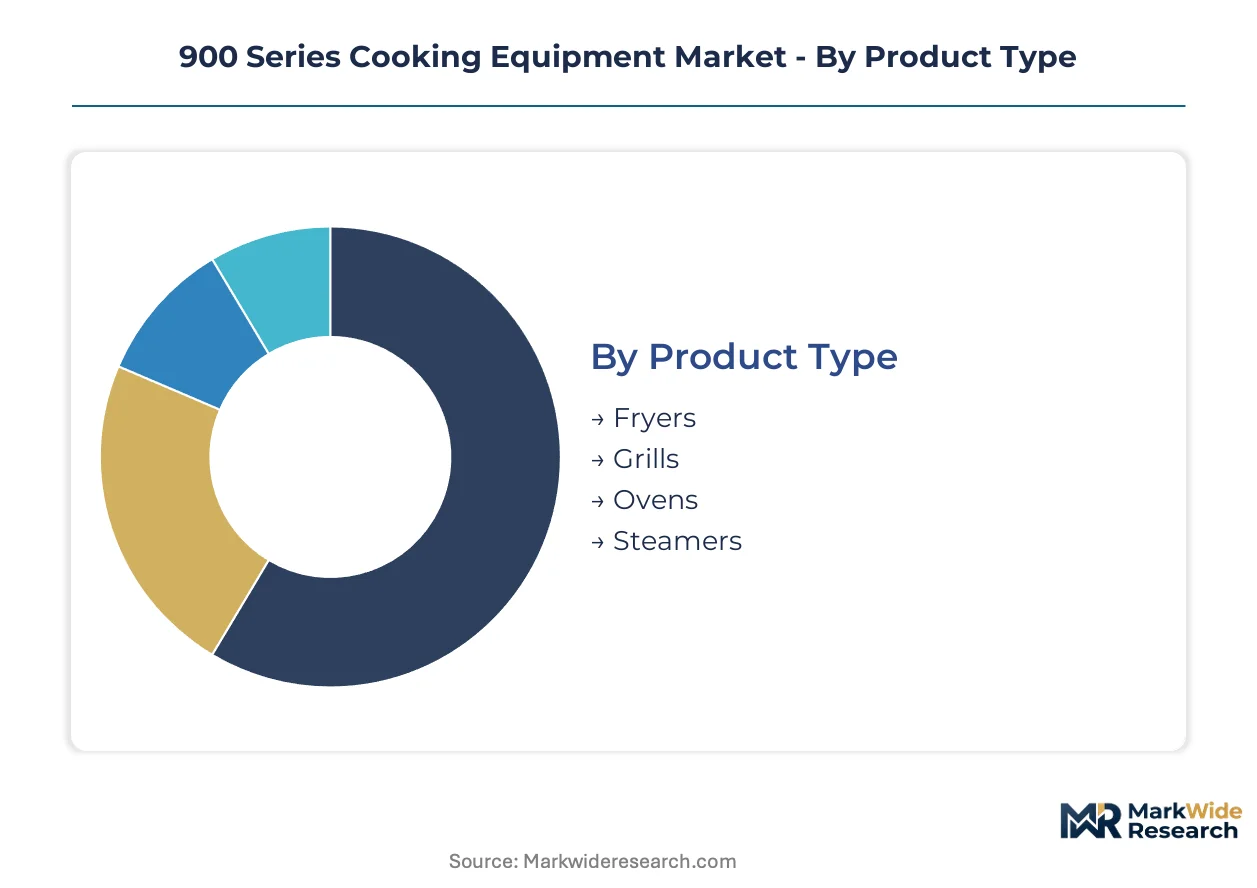
Commercial kitchen operators select 900 Series platforms through divergent procurement lenses. Product specifications vary sharply between high-volume frying operations and precision baking environments. Installation constraints and utility infrastructure further fragment purchasing criteria across end-use categories.
Product Type:
Volume buyers differentiate equipment by thermal output requirements and oil management intensity.
- Fryers:Heavy-gauge tank construction with 20-40 liter oil capacity dominates QSR and fast-casual specifications. German full-service chains are retrofitting locations with automated filtration systems to extend oil cycles and reduce labor.
- Grills:Cast-iron or chrome-plated griddle surfaces deliver 300-400°C searing temperatures for protein-heavy menus. UK premium hotels specify 900mm chargrills for open-kitchen theater configurations.
- Ovens:Convection and combi-steam variants serve institutional catering with programmable humidity control.
- Steamers:Pressure and atmospheric models support health-focused menu development in contract foodservice.
Volume sits with fryers; growth tilts toward hybrid oven configurations integrating convection and steam.
End User:
Operational scale and menu complexity determine equipment durability requirements and technology preferences.
- Restaurants:Full-service chains in North America prioritize modular 900mm lines that standardize training and maintenance protocols across 50-plus unit footprints. California electrification mandates are pushing new construction toward all-electric induction suites.
- Catering Services:Mobile and event-focused operators demand rapid-deployment cooking suites with dual-fuel flexibility. Cloud kitchen density in London and Berlin is accelerating specification of compact modular packages.
- Cafes:Limited-menu operators favor countertop and under-counter configurations with reduced burner counts.
- Hotels:UK hospitality refurbishment cycles favor premium-grade AISI 304 construction with extended warranty terms.
Procurement scale concentrates with restaurant chains; specification innovation is climbing fastest in catering services.
Installation:
Spatial constraints and lease structures shape capital deployment flexibility.
- Modular:Standardized 900mm width enables linear cooking suite assembly with shared utility connections. Large catering contractors in the United Kingdom are consolidating vendor relationships around integrated workstation packages.
- Built-in:Custom millwork integration serves flagship locations and premium hotel properties where kitchen aesthetics drive guest experience.
- Portable:Castor-mounted units support temporary kitchen configurations and disaster relief operations.
- Custom:Non-standard dimensions address retrofit constraints in historic building conversions.
Deployment flexibility favors modular; bespoke margins concentrate in custom fabrication.
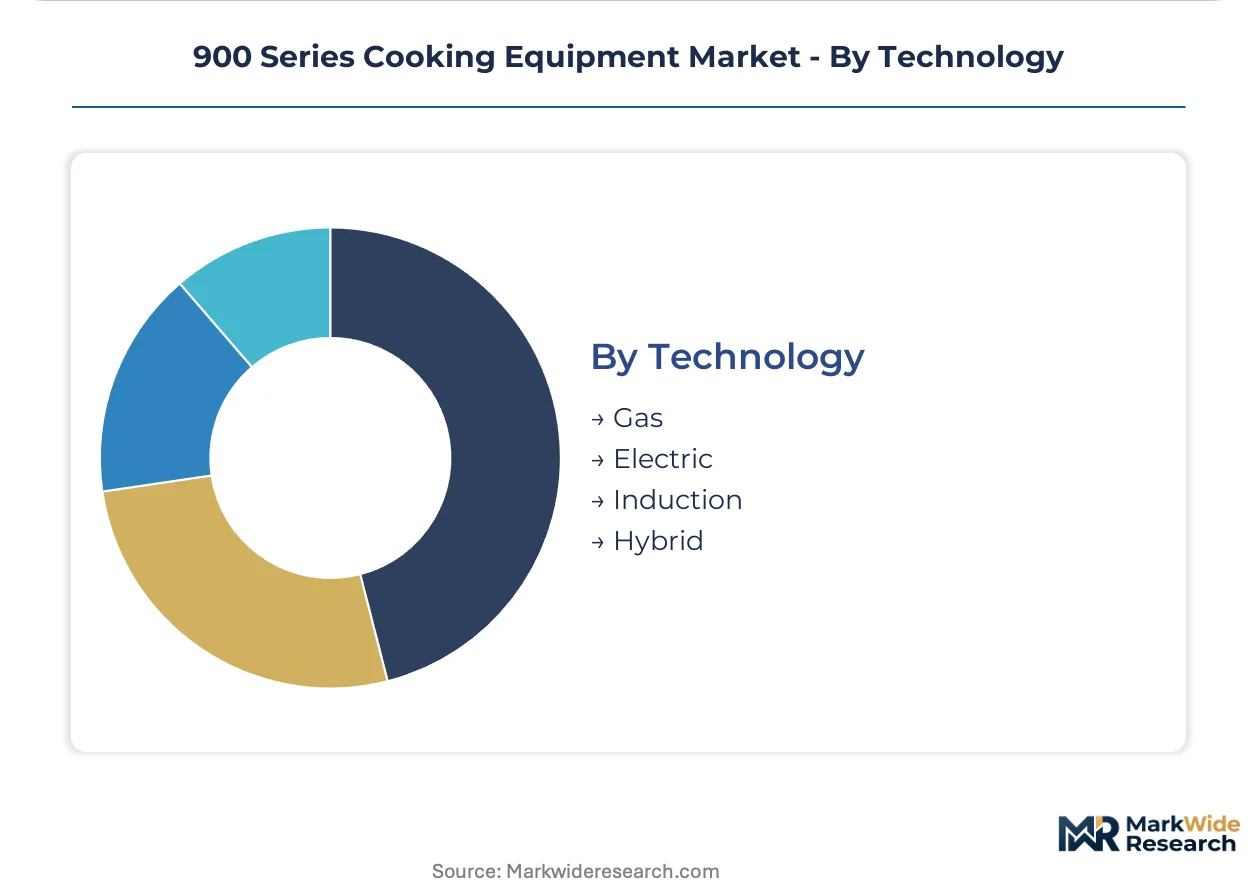
Technology:
Utility infrastructure density and carbon regulation stringency determine fuel selection.
- Induction:Power electronics deliver instantaneous thermal response without combustion byproducts. Netherlands full-service chains are specifying induction ranges for new flagship locations where grid capacity supports 400V three-phase drops.
- Hybrid:Dual-fuel configurations combine gas backup with electric precision for operational hedging against volatile utility tariffs.
- Gas:Pipeline-dense markets retain cost advantages for high-BTU applications.
- Electric:Resistance heating serves secondary markets where induction infrastructure remains cost-prohibitive.
Installed base remains gas-weighted; specification momentum is shifting fastest toward induction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for 900 Series cooking equipment clusters in Germany and Italy, while consumption concentrates in the United States, Germany, and the United Kingdom. This geographic split creates distinct supply chain configurations across Atlantic markets.
United States
Full-service restaurant chains drive equipment turnover through standardized 900mm platform specifications across multi-unit footprints. The U.S. Department of Energy enforces minimum efficiency standards that compress product development timelines for fryers and griddles. California's building code electrification mandates are pulling specification toward all-electric induction suites in new construction.
Germany
Commercial kitchen refurbishment rates exceed regional averages as institutional operators modernize aging infrastructure. The EU Ecodesign Directive accelerates replacement cycles for gas-fired equipment through mandatory efficiency thresholds. Bavaria's manufacturing corridor hosts precision fabrication clusters supplying AISI 304 stainless steel components to European integrators.
United Kingdom
Premium hotel refurbishment programs favor extended warranty terms and standardized 900mm widths for kitchen suite integration. F-Gas Regulation compliance timelines constrain refrigerant-based thermal system configurations. London's cloud kitchen density is accelerating compact modular suite adoption among ghost kitchen operators.
Netherlands
Grid infrastructure density supports high-amperage three-phase drops enabling induction range deployment in flagship locations. CE marking requirements under EU safety frameworks shape certification costs for equipment imports. Rotterdam's port logistics cluster facilitates component sourcing from German and Italian fabrication centers.
Italy
Specialized combustion systems engineering concentrates among legacy manufacturers serving Mediterranean export markets. REACH chemical safety protocols govern surface treatment processes for food-contact stainless steel. Emilia-Romagna's metalworking districts supply precision burner assemblies to modular platform integrators.
900 Series Cooking Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the 900 Series cooking equipment market. The vendor base organizes into three tiers: multinational portfolio players with captive combustion technology, regional fabricators with modular integration expertise, and component specialists supplying burners and control systems. Consolidation pressure rewards manufacturers with backward integration into thermal systems and in-house certification capabilities. Strategic moves center on portfolio breadth expansion and geographic footprint extension through distribution partnerships.
Within the diversified conglomerate tier, Ali Group S.r.l and The Middleby Corporation exemplify scale-driven competitive positioning. Illinois Tool Works Inc. represents the precision technology archetype with embedded control systems expertise. MKN Maschinenfabrik Kurt Neubauer GmbH & Co. KG anchors the German engineering specialist segment. These named entities illustrate how competitive advantage accrues to manufacturers combining portfolio breadth with captive technology development.
| Leading Market Players |
|---|
| Charvet |
| Capic |
| Ali Group S.r.l |
| AB Electrolux |
| ATA Srl |
| Fagor Professional |
| Illinois Tool Works Inc. |
| MKN Maschinenfabrik Kurt Neubauer GmbH & Co. KG |
| The Middleby Corporation |
| Others |
Value Chain & Pricing Dynamics
Nickel-alloy price indices on the London Metal Exchange cascade through AISI 304 stainless steel procurement contracts, compressing fabrication margins for European modular platform manufacturers and forcing three-tier pricing stratification across premium certified, standard CE-marked, and economy-grade equipment tiers.
Pricing Analysis
Margin tightening in standard-grade equipment reflects raw-material pass-through clauses and volume discounting demanded by large catering contractors. Three-tier pricing structure across premium, standard, and economy levels differentiates by UL/CE certification tier and after-sales service bundling. Cost-down pressure on economy segments accelerates because cloud kitchen operators prioritize capital deployment flexibility over durability specifications. Full-service restaurant chains exhibit lowest price sensitivity; ghost kitchen startups show highest.
Supply Chain Analysis
Domestic-content mandates under the EU's F-Gas Regulation and Buy American provisions in federal procurement are reshaping component sourcing toward regional fabrication clusters. Manufacturing gravity centers on Germany, Italy, and the United States, with precision burner assemblies drawing from Emilia-Romagna's metalworking districts and control systems sourcing from Bavarian electronics clusters. Supply chain risk concentrates in single-source dependency for high-amperage induction coil windings. Distribution runs through captive dealer networks for multinational portfolio players and independent foodservice equipment distributors for regional specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized combustion systems engineering talent scarcity props pricing power for incumbent manufacturers with captive burner technology development. Capacity bottlenecks in certified coil winding for induction platforms constrain supply expansion.
For Market Incumbents: Deepen backward integration into AISI 304 stainless steel component fabrication to defend against nickel price volatility and Asian import competition. Anchor European supply relationships through extended warranty terms and equipment-as-a-service contracting structures that lock in multi-year maintenance revenue streams. For New Entrants and Emerging Players: Capture specification share in California's electrification-mandated new construction segment where incumbent gas-fired portfolios face regulatory displacement. Target cloud kitchen operators in London and Berlin with compact modular suites emphasizing rapid deployment and dual-fuel flexibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German engineering specialists with captive CE marking capabilities and established relationships with institutional catering contractors. Long-term viability hinges on induction technology transition readiness and grid infrastructure partnership positioning. Watch California and New York building code electrification mandate expansion as the inflection signal for technology mix rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Combustion Systems | Captive burner technology insulates margin from specialized engineering talent scarcity. |
| Equipment-as-a-Service Contracting | UK contract foodservice sector's preference for opex structures locks in recurring revenue. |
| Induction Platform Certification Investment | UL and CE dual certification accelerates access to California electrification-mandated projects. |
| Cloud Kitchen Distribution Partnership | London and Berlin ghost kitchen density creates rapid-deployment specification pull. |
| Grid Infrastructure Collaboration | Netherlands three-phase capacity partnerships enable flagship induction range deployment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with commercial kitchen equipment procurement directors, foodservice contractor operations executives, OEM burner engineering leads, and aftermarket service heads. Secondary sources incorporated U.S. Department of Energy efficiency standard filings, EU Ecodesign Directive implementation reports, CE marking registration databases, and stainless steel import statistics. Bottom-up equipment shipment analysis triangulated against top-down commercial kitchen construction permits.
Granularity-level modeling deployed product-type, end-user, installation configuration, and technology fuel-source dimensions at the country level across the projection horizon. CAGRs derived from regression analysis against commercial kitchen refurbishment cycle data and regulatory mandate phase-in schedules. Forecast inputs incorporated utility tariff volatility scenarios and grid infrastructure expansion timelines for induction deployment feasibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon-border adjustment mechanism implementation and building code electrification mandate geographic expansion. Forecasts reflect documented assumptions regarding replacement cycle acceleration and technology transition rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market