
 Gas Smoker Market | 2026-2036
Gas Smoker Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Smoker Market Analytics
Stainless steel is decoupling from traditional carbon steel in cabinet construction, lowering long-term corrosion costs for buyers. Masterbuilt leverages captive manufacturing in its vertical smoker lines to protect margin pools. Char-Broil anchors its position through broad retail channel control across big-box hardware networks. Pit Boss competes aggressively on price in the entry-level propane segment while sustaining R&D intensity in digital temperature controls.
A gas smoker is a thermally insulated cooking chamber that burns gaseous fuel—typically propane or natural gas—to generate controlled heat and smoke for flavoring and preserving proteins, operating at temperatures between 225°F and 275°F through burner-fed wood chip trays. Vertical smokers dominate residential installations due to footprint efficiency and thermal stacking, while horizontal and offset configurations command premium positioning among Texas-style barbecue operators. The propane fuel type occupies the largest volume share given infrastructure ubiquity, though natural gas variants are gaining traction in permanent outdoor kitchen builds. Commercial end users and catering services concentrate margin pools through equipment durability requirements and repeat purchase contracts.
The US EPA and CSA Group standards govern combustion efficiency and emissions testing for residential gas-fired cooking equipment, while the EU F-Gas Regulation shapes refrigerant-adjacent thermal system imports. These frameworks elevate compliance costs for entry-tier manufacturers while creating certification barriers that favor established suppliers with in-house testing laboratories. Stakeholders must monitor evolving municipal fire codes and outdoor appliance ordinances as urban outdoor cooking infrastructure expands.
Market Dynamics
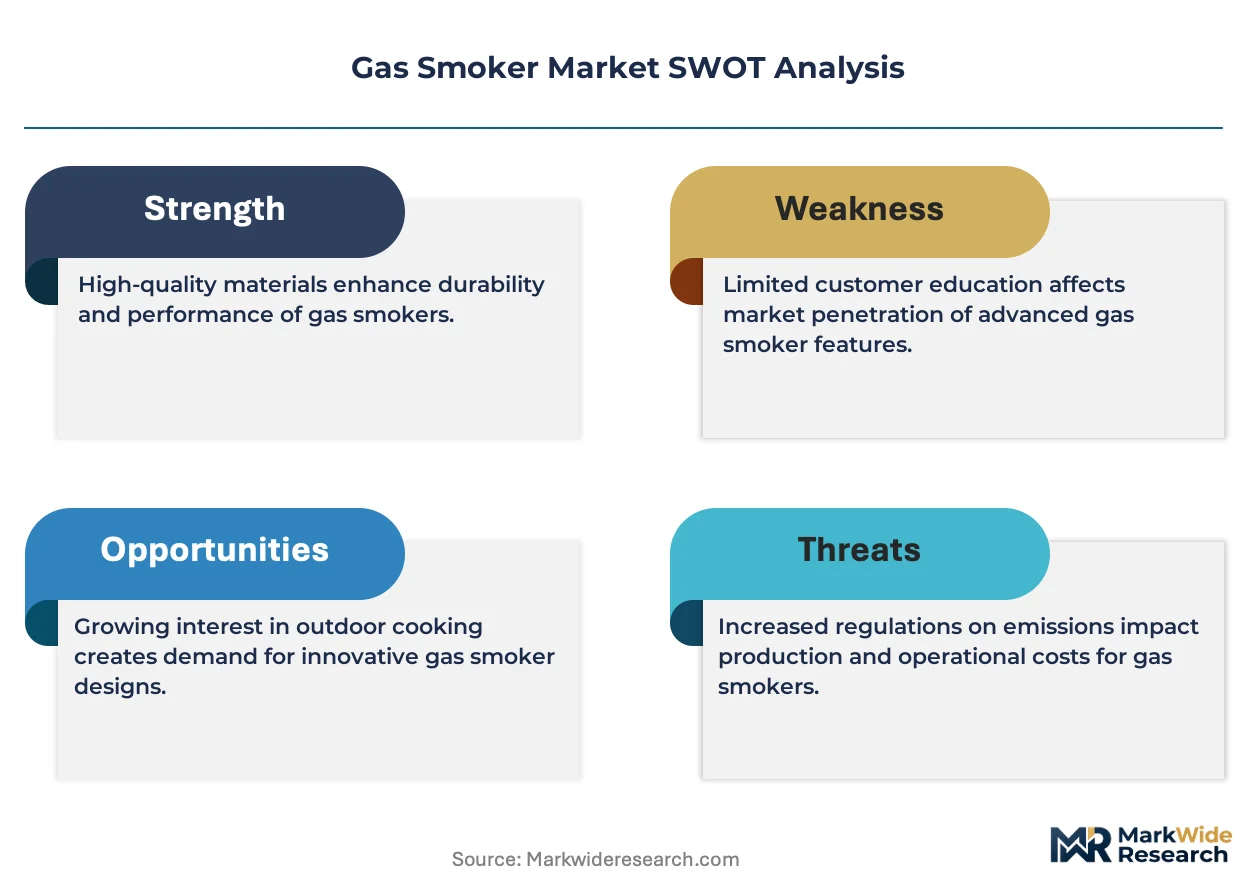
Stainless steel is decoupling from carbon steel in cabinet construction as EPA emission standards tighten certification requirements, forcing manufacturers to absorb compliance costs while outdoor cooking demand concentrates in barbecue culture clusters.
Growth Catalysts
- Propane infrastructure ubiquity:Residential propane distribution networks across the United States enable immediate fuel accessibility without specialized installation, removing adoption friction for first-time buyers.
- Outdoor living space expansion:Southern California municipalities are relaxing outdoor appliance ordinances, permitting permanent natural gas connections in new residential construction.
- Digital temperature control maturation:PID-enabled burner modulation now delivers ±5°F stability, satisfying competition barbecue precision requirements previously demanding charcoal expertise.
Market Restraints
- Steel price volatility:304-grade stainless input costs fluctuate with nickel futures, compressing margin pools for cabinet fabricators without long-term supply agreements.
- Testing laboratory concentration:CSA Group and UL certification capacity constraints in North America extend product launch timelines by four to six months for entry-tier manufacturers.
- Electric smoker substitution:Pellet-fueled electric units capture apartment-dwelling enthusiasts lacking propane storage permissions, eroding addressable market in urban cores.
Strategic Opportunities
- Natural gas conversion kits:Permanent outdoor kitchen installations in Texas and Florida create aftermarket attachment revenue streams for existing propane unit owners.
- Commercial catering contracts:Event rental services require NSF-certified durability specifications, opening margin-rich B2B channels distinct from retail price competition.
- EU F-Gas Regulation alignment:Manufacturers achieving CE marking compliance gain preferential access to German and Dutch specialty barbecue import channels.
Industry Challenges
- Welding technician scarcity:TIG-certified fabricators command premium wages in metalworking regions, constraining production scaling for cabinet assembly operations.
- Cross-jurisdictional fire code navigation:Municipal outdoor appliance ordinances vary between Texas counties and California cities, fragmenting distribution logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Smoker Market |
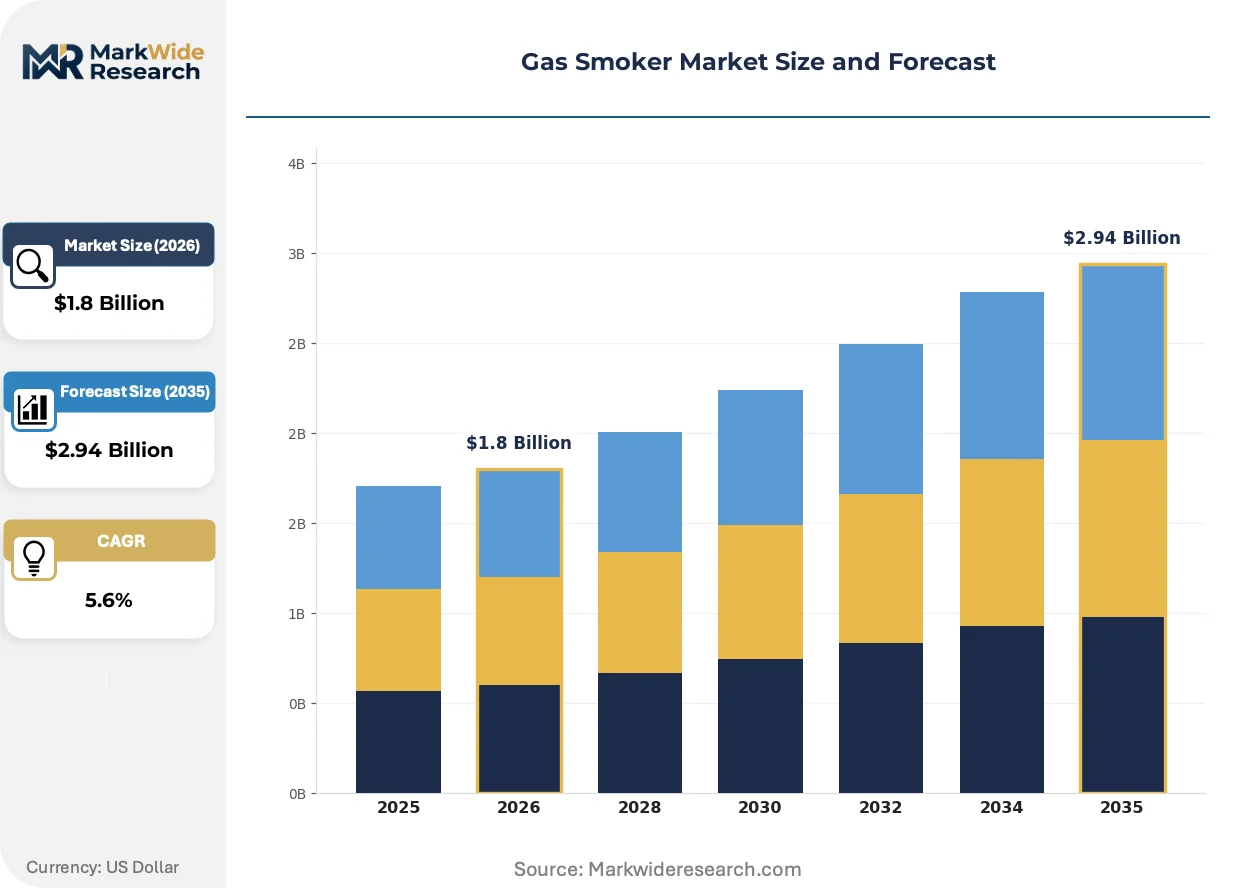
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Smoker, Horizontal Smoker, Offset Smoker, Portable Smoker Fuel Type: Natural Gas, Propane, Butane, Biogas End User: Residential, Commercial, Catering Services, Outdoor Activities Size: Small, Medium, Large, Extra-Large |
| Companies Covered | Masterbuilt, Char-Broil, Pit Boss, Cuisinart, Camp Chef, Dyna-Glo, Grilla Grills, Traeger, Meadow Creek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Smoker Market Evolving Landscape
Controlled combustion technology and connected monitoring systems are restructuring how residential and commercial operators manage thermal consistency, reducing operator attention requirements while tightening regulatory compliance.
Bluetooth-enabled temperature probes paired with smartphone applications are overtaking standalone analog dial thermometers in mid-tier product configurations. Competition barbecue teams and weekend enthusiasts alike demand remote monitoring capabilities that alert users to burner flame-outs or wood chip depletion. This connectivity layer is overtaking basic electromechanical controls as the default expectation above $400 price points, compressing margin for manufacturers lacking firmware development capabilities.
The US EPA's updated New Source Performance Standards for residential combustion equipment are elevating emissions testing documentation requirements. Manufacturers must now submit third-party verified NOx and CO output measurements for each burner configuration, adding $15,000-$25,000 per SKU in certification costs. Texas-style horizontal offset smokers with higher combustion chamber volumes face disproportionate testing burdens compared to compact vertical cabinets.
Specialty barbecue retailers are unbundling after-sales service from equipment sales, shifting toward subscription-based maintenance and seasonal cleaning packages. Independent hardware stores in barbecue culture clusters now capture recurring revenue through burner inspection and gasket replacement programs. This service model rotation is most visible in Houston and Austin metropolitan markets, where established pitmaster communities prioritize equipment longevity over replacement cycles.
Gas Smoker Market Segmentation
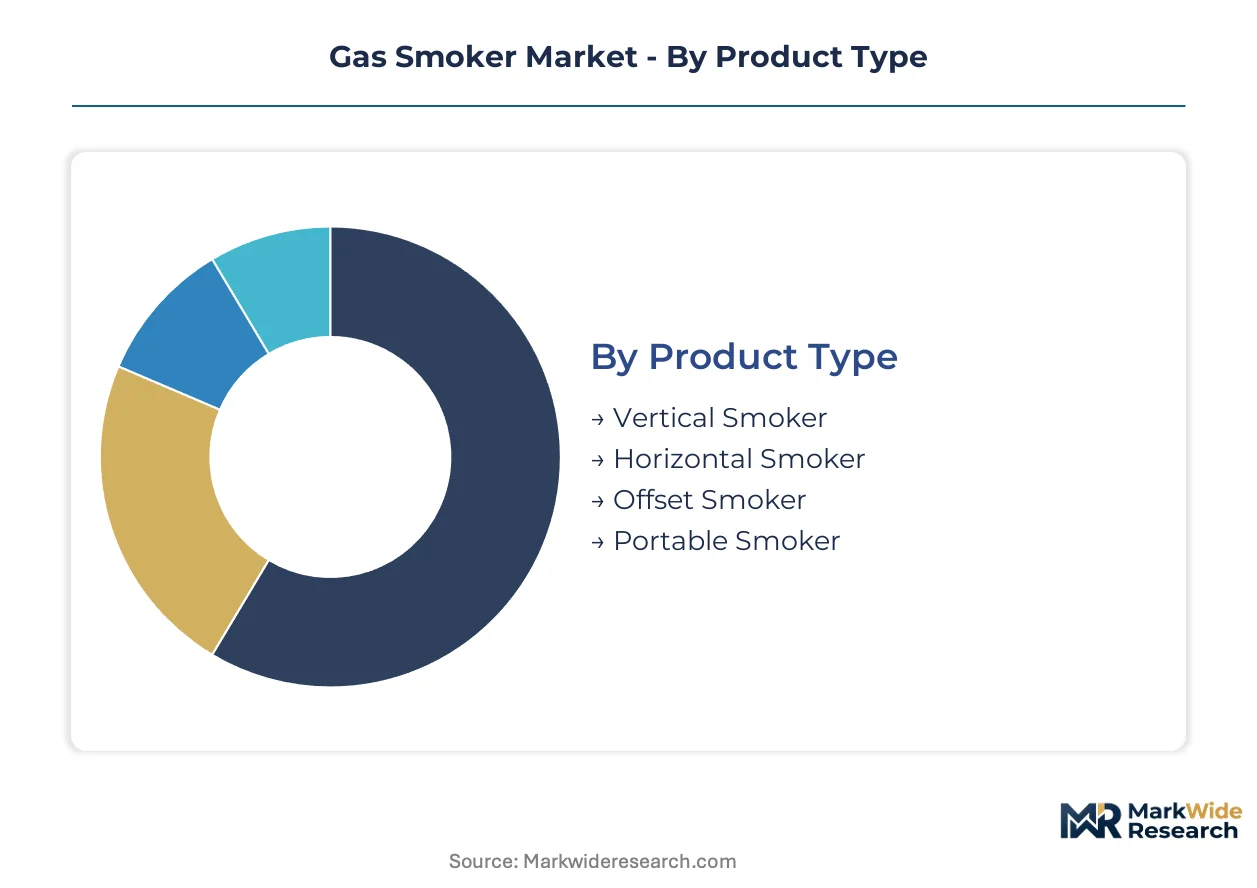
Gas smoker segmentation reveals divergent engineering requirements between permanent outdoor kitchen installations and mobile catering operations. Product architecture, fuel compatibility, and thermal capacity specifications vary sharply across end-use contexts, forcing manufacturers to maintain distinct SKU portfolios rather than unified platforms.
Product Type:
Integration depth separates cabinet configurations optimized for standalone residential patios versus embedded outdoor kitchen builds.
- Vertical Smoker:Thermally stacked chamber design maximizes cooking capacity within minimal footprint. Demand clusters in Southern California outdoor living markets where municipal ordinances restrict appliance dimensions on residential decks.
- Horizontal Smoker:Barrel-configuration cooking chamber enables Texas-style offset fire management. Pitmaster competitions across Houston and Austin metropolitan clusters sustain specification requirements for larger protein capacity and wood smoke penetration depth.
- Offset Smoker:Firebox separation from cooking chamber delivers indirect heat distribution prized by barbecue culture enthusiasts.
- Portable Smoker:Collapsible cabinet designs with detachable propane connections target tailgating and camping segments.
Volume placements concentrate in Vertical Smokers; the faster expansion belongs to Portable Smokers.
Fuel Type:
Cost tier stratification emerges between infrastructure-dependent natural gas and cylinder-based alternatives requiring no permanent installation.
- Propane:20-pound cylinder compatibility dominates residential adoption through hardware store distribution ubiquity. Texas barbecue culture clusters and Florida outdoor kitchen markets sustain replacement cylinder demand through established retail networks.
- Natural Gas:Permanent line connections require professional installation but eliminate fuel logistics for high-frequency users. Southern California new construction permits increasingly mandate natural gas rough-ins for outdoor appliance zones.
- Butane:Compact canister format suits portable smoker configurations where cylinder weight constraints matter.
- Biogas:Renewable methane compatibility appeals to sustainability-focused outdoor cooking enthusiasts in German and Dutch import markets.
Volume placements concentrate in Propane; the steepest expansion trajectory belongs to Natural Gas.
End User:
Application context dictates durability specifications and service attachment models across divergent usage intensities.
- Residential:Weekend-use patterns prioritize temperature stability over commercial-grade construction. EPA emission certification requirements for residential combustion equipment constrain entry-tier manufacturer participation.
- Commercial:NSF-certified construction and burner warranty terms anchor purchasing decisions for restaurants and barbecue operations. Repeat equipment replacement contracts in Texas and Florida create margin-rich B2B channels.
- Catering Services:Event rental fleets demand rapid heat recovery and transport-optimized cabinet geometry.
- Outdoor Activities:Tailgating and camping segments prioritize ignition reliability and wind-resistant burner performance.
Volume placements concentrate in Residential; the fastest share gain belongs to Catering Services.
Size:
Customer type segmentation maps household composition and entertainment frequency to thermal capacity requirements.
- Large:Six-rack vertical configurations or dual-barrel horizontal designs serve extended family gatherings and competition barbecue teams. Austin and Houston pitmaster communities sustain demand for 40+ pound protein capacity.
- Medium:Four-rack capacity balances footprint efficiency against typical suburban entertainment scales. Southern California municipal deck restrictions and Texas patio dimensions both accommodate this specification band.
- Small:Two-rack designs target apartment dwellers with limited outdoor appliance permissions.
- Extra-Large:Custom fabrication for commercial operations and competitive barbecue teams exceeds standard retail SKU boundaries.
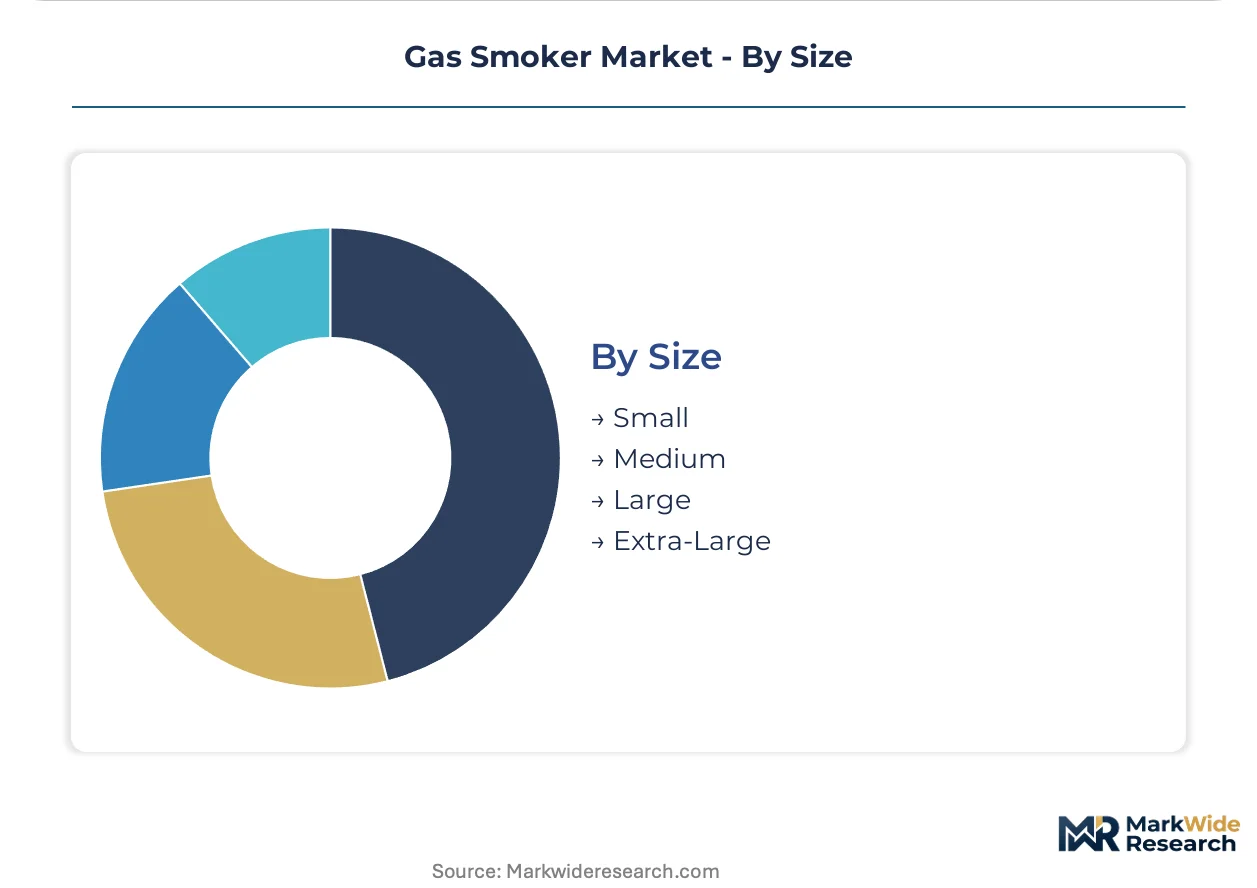
Volume placements concentrate in Medium; the fastest volume climb belongs to Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeport Foreign-Trade Zone incentives in Texas concentrate gas smoker assembly operations near Gulf Coast steel terminals, reducing tariff exposure on imported stainless components while positioning finished goods for rapid distribution across Southern barbecue culture clusters.
United States
Texas barbecue culture clusters in Houston and Austin sustain specification demand for horizontal offset configurations with 40+ pound protein capacity. The US EPA's New Source Performance Standards for residential combustion equipment mandate third-party verified NOx and CO documentation per SKU, elevating compliance costs for entry-tier manufacturers. Southern California municipalities including Los Angeles and Orange County are relaxing outdoor appliance ordinances to permit permanent natural gas rough-ins for new residential construction.
Germany
Sustainability-focused outdoor cooking enthusiasts in Bavaria and Baden-Württemberg drive biogas-compatible smoker import demand. The EU F-Gas Regulation shapes thermal system compliance requirements for equipment entering German and Dutch specialty barbecue channels. Berlin-Brandenburg industrial fabricators are developing CE-marked cabinet designs targeting premium positioning in European outdoor kitchen markets.
Canada
Seasonal cabin and cottage markets in Ontario and Quebec sustain portable propane smoker demand through hardware retail networks. Health Canada and CSA Group certification requirements govern combustion efficiency testing for residential gas-fired cooking equipment. Calgary and Edmonton metropolitan clusters exhibit concentration in natural gas conversion kit adoption for permanent outdoor kitchen installations.
Australia
Outdoor entertainment culture in New South Wales and Victoria sustains medium-capacity vertical smoker placements despite municipal deck dimension restrictions. The Australian Competition and Consumer Commission enforces product safety standards for gas appliance imports through mandatory compliance declarations. Melbourne and Sydney specialty barbecue retailers are unbundling after-sales service into subscription-based maintenance packages.
United Kingdom
Competition barbecue team formation in Greater London and the Midlands sustains demand for PID-enabled temperature control systems. UKCA marking requirements post-Brexit create parallel certification obligations distinct from EU CE marking for thermal equipment imports. Manchester and Birmingham fabrication clusters are developing compact cabinet designs targeting apartment-dwelling enthusiasts with limited outdoor appliance permissions.
Gas Smoker Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration into captive burner assembly protecting margin pools for established players while entry-tier fabricators face extended certification timelines. The vendor base concentrates around three strategic archetypes: stainless steel cabinet fabricators with in-house TIG welding capacity, digital control system integrators leveraging firmware development partnerships, and broad retail channel operators with big-box hardware network access. Dominant competitive moves include backward integration into burner component production and geographic expansion through specialty barbecue retail partnerships.
Within the branded specialist tier, Masterbuilt Manufacturing LLC and Char-Broil LLC exemplify divergent positioning strategies, with the former representing captive manufacturing archetypes and the latter anchoring broad retail channel control. Pit Boss Grills occupies a position on the aggressive price-competition vector while sustaining R&D intensity in digital temperature controls. These three entities collectively illustrate how scale, vertical integration depth, and distribution architecture determine competitive positioning across residential and commercial end-use segments.
| Leading Market Players |
|---|
| Masterbuilt |
| Char-Broil |
| Pit Boss |
| Cuisinart |
| Camp Chef |
| Dyna-Glo |
| Grilla Grills |
| Traeger |
| Meadow Creek |
| Others |
Value Network & Pricing Analysis
US EPA New Source Performance Standards for residential combustion equipment gate qualified supply and premium-tier pricing access, as third-party verified NOx and CO documentation requirements add substantial certification costs that only established manufacturers with in-house testing laboratories can absorb while passing compliance premiums to buyers.
Pricing Analysis
Short lead-time availability commands premium positioning in gas smoker procurement, with spot inventory from regional hardware networks trading at discounts against certified pre-order channels. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial units from residential EPA-compliant models and entry-tier uncertified imports. Price differentiation hinges on CSA Group or UL certification tier and after-sales service bundling. Cost compression in entry-tier propane vertical cabinets is intensifying because electric pellet smoker substitution erodes addressable market in urban cores. Catering services and competition barbecue teams exhibit lowest price sensitivity; apartment-dwelling enthusiasts with storage constraints show highest.
Supply Chain Analysis
Regional distribution centers in Texas and Southern California operate hub-and-spoke patterns radiating toward barbecue culture clusters and outdoor living markets. Manufacturing concentrates in China for burner component fabrication, Mexico for cabinet assembly near Freeport Foreign-Trade Zone, and domestic US facilities for TIG-welded stainless construction. Raw material flows draw from Indonesian nickel for 304-grade stainless, Canadian steel for carbon cabinet variants, and Taiwanese electronics for PID control modules. Single-source vulnerability concentrates in CSA Group and UL certification capacity constraints. Distribution runs through big-box hardware networks and specialty barbecue retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. US EPA emission standards for residential combustion equipment create a barrier-to-entry moat that protects margin pools for established suppliers with captive testing infrastructure.
For Market Incumbents: Hedge against electric smoker substitution by deepening firmware development capabilities for connected temperature monitoring systems. Anchor position through long-term supply agreements with 304-grade stainless producers to neutralize nickel futures volatility. Defend margin pools by accelerating natural gas conversion kit attachment revenue in Texas and Florida permanent outdoor kitchen installations. For New Entrants and Emerging Players: Enter via biogas-compatible cabinet designs targeting German and Dutch sustainability-focused import channels where EU F-Gas Regulation alignment creates preferential access. White-space concentrates in portable smoker configurations for Australian and Canadian seasonal cabin markets. Pursue direct partnerships with event rental services requiring NSF-certified durability specifications. For Investors and Strategic Acquirers: CSA Group certification backlog duration is the leading indicator that in-house testing laboratory capacity will command acquisition premiums. Five-to-ten-year viability favors vertically integrated fabricators with captive burner assembly and TIG welding technician retention programs. Monitor municipal outdoor appliance ordinance relaxation in Southern California as inflection signal for natural gas infrastructure plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Component Production | Captive supply of PID-enabled control modules protects margin pools from firmware development cost inflation. |
| NSF Certification Pathway Investment | Commercial catering contract eligibility opens margin-rich B2B channels distinct from retail price competition. |
| Natural Gas Conversion Kit Expansion | Aftermarket attachment revenue streams capture permanent outdoor kitchen build momentum in Texas and Florida. |
| Specialty Barbecue Retail Partnership | Unbundled subscription-based maintenance packages in Houston and Austin metropolitan clusters generate recurring revenue. |
| CE Marking Alignment for EU Access | Preferential positioning in German and Dutch import channels requires EU F-Gas Regulation thermal system compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with product development directors at cabinet fabricators, procurement leads at big-box hardware networks, TIG welding technicians in metalworking regions, and aftermarket service managers in specialty barbecue retail validated demand patterns. Secondary sources included US EPA New Source Performance Standards documentation, CSA Group certification databases, EU F-Gas Regulation implementation guidance, and stainless steel futures exchange data. Bottom-up SKU-level volume builds triangulated against top-down category expenditure estimates.
Data-stream reconciliation across shipment records, certification timelines, and channel inventory positions shaped the analytical framework. Segmentation dimensions modeled include product architecture, fuel compatibility, end-use intensity, and thermal capacity tier. CAGRs were derived from normalized growth rate convergence across the projection horizon. Industry-specific forecast inputs incorporated municipal ordinance relaxation schedules and welding technician wage trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility spikes or extended CSA Group certification delays. Forecasts reflect documented assumptions regarding EPA enforcement intensity and electric smoker substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Commercial Cookers Market