
 Global Stroke Diagnostics Market | 2026-2036
Global Stroke Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stroke Diagnostics Market Foresight
Hospital procurement channels for stroke diagnostics is tilting toward bundled imaging-and-software contracts rather than standalone device purchases. Siemens Healthineers anchors this shift through its integrated CT-angiography and AI workflow platforms that span detection through treatment planning. GE Healthcare competes by extending its Edison AI ecosystem into emergency department triage protocols. Philips Healthcare differentiates through its interventional imaging suites that combine neurovascular device navigation with real-time hemodynamic monitoring.
Stroke diagnostics encompasses the clinical identification and characterization of cerebrovascular events through neuroimaging, hemodynamic assessment, and biomarker analysis to distinguish ischemic from hemorrhagic pathology and guide time-sensitive therapeutic decisions. Magnetic resonance imaging with diffusion-weighted sequences detects acute infarction within minutes of symptom onset, while computed tomography perfusion mapping quantifies salvageable tissue penumbra to triage candidates for endovascular thrombectomy. Imaging equipment captures the dominant share of product-type revenue as health systems replace aging CT and MRI fleets with faster protocols that support 24/7 stroke code activation. Artificial intelligence algorithms represent the fastest-expanding technology segment as regulatory clearances accumulate for automated large vessel occlusion detection and ASPECTS scoring that compress radiologist interpretation times.
The FDA breakthrough device program and EU MDR conformity requirements shape product development timelines and commercialization strategies for neuroimaging and AI software vendors seeking transatlantic market access. Japan's PMDA accelerates review for stroke AI diagnostics that demonstrate equivalence to approved predicate devices, while WHO stroke care guidelines influence national health system procurement priorities in lower-resource settings. Stakeholders must monitor reimbursement decisions for AI-augmented reads by Medicare and Germany's G-BA, as these determinations will dictate whether software subscriptions achieve standalone payment or remain bundled within imaging procedure fees.
Market Dynamics
Hospital procurement for stroke diagnostics is consolidating around integrated imaging-and-software bundles that compress door-to-needle times, forcing standalone device vendors to embed AI workflows or lose access to neurovascular suite tenders.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated review mechanism for AI-assisted large vessel occlusion detection shortens time-to-market for stroke imaging algorithms, incentivizing venture investment into regulatory-stage platforms.
- Aging Demographics in Japan:Japan's super-aged population drives institutional demand for 24/7 stroke code activation capabilities, prompting hospital networks to replace legacy CT fleets with perfusion-capable scanners.
- Endovascular Thrombectomy Expansion:Mechanical clot retrieval protocols now extend to 24-hour windows in selected patients, requiring real-time CT perfusion mapping that upgrades scanner utilization rates in comprehensive stroke centers.
Market Restraints
- Gadolinium Supply Concentration:Contrast agent production concentrates among three chemical manufacturers, exposing MRI-dependent stroke protocols to price volatility and supply disruption risks.
- EU MDR Conformity Burden:The European Union's Medical Device Regulation imposes extended clinical evidence requirements on AI diagnostic software, delaying commercialization timelines and inflating regulatory compliance costs for transatlantic vendors.
- Helium Dependency for MRI:Superconducting magnet cooling relies on helium extraction concentrated in Qatar and the United States, creating input cost vulnerability for diffusion-weighted imaging infrastructure.
Strategic Opportunities
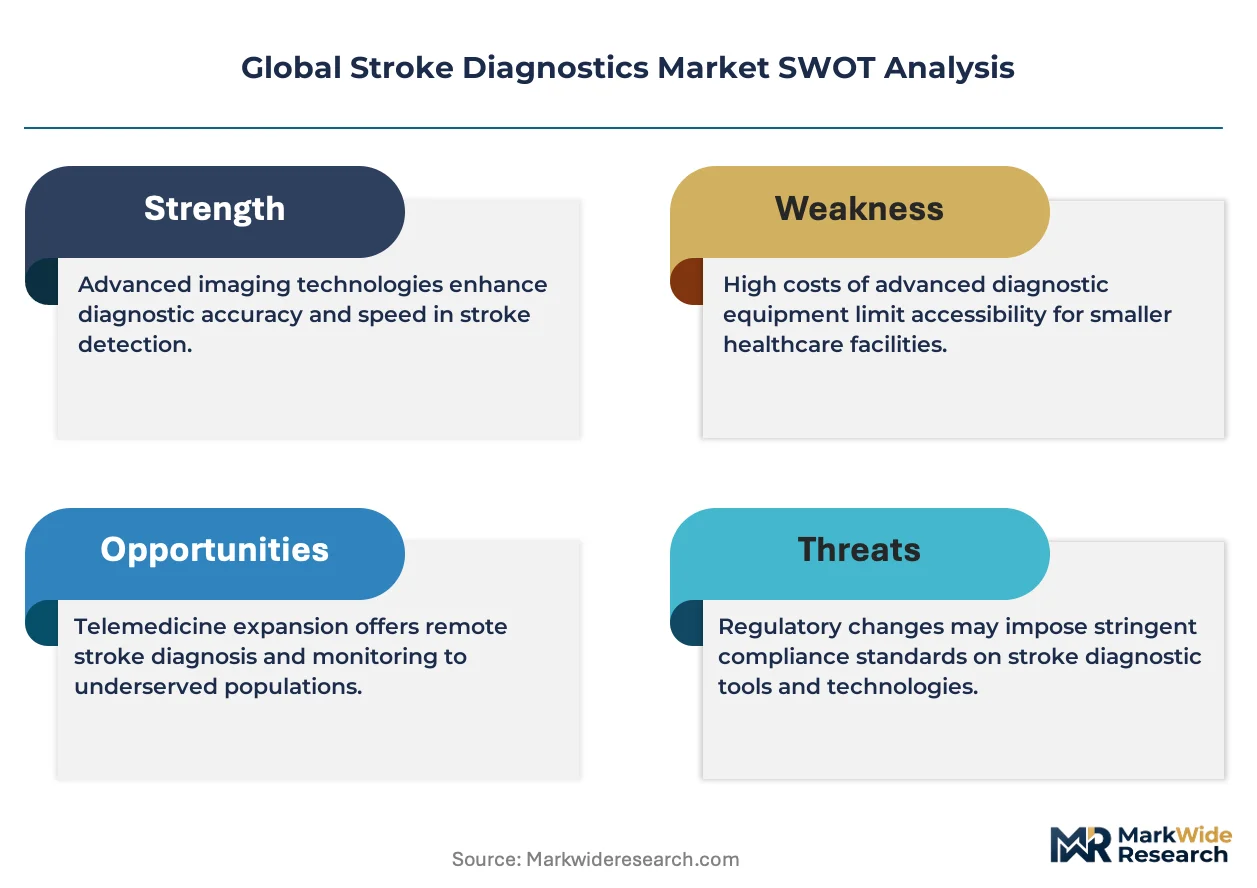
- Rural Network Telestroke:Hub-and-spoke telemedicine architectures in Brazil's interior states create demand for cloud-connected CT scanners with automated ASPECTS scoring that extends specialist coverage without physical relocation.
- Mobile Stroke Unit Deployment:Ambulance-mounted CT platforms equipped with point-of-care coagulation testing enable prehospital thrombolysis, opening new reimbursement categories for emergency medical services in Germany's densely networked regions.
- WHO Guideline Harmonization:The World Health Organization's stroke care standards influence national procurement priorities across Southeast Asia, creating first-mover advantages for imaging vendors that preconfigure equipment to WHO technical specifications.
Industry Challenges
- Neuroradiologist Workforce Scarcity:Fellowship-trained interpreters for acute stroke imaging remain concentrated in academic medical centers, constraining 24/7 coverage expansion at community hospitals purchasing AI-augmented platforms.
- Legacy PACS Integration Friction:Picture archiving and communication systems deployed in the early 2010s lack API architectures for real-time AI algorithm deployment, forcing costly middleware investments or full-stack replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stroke Diagnostics Market |
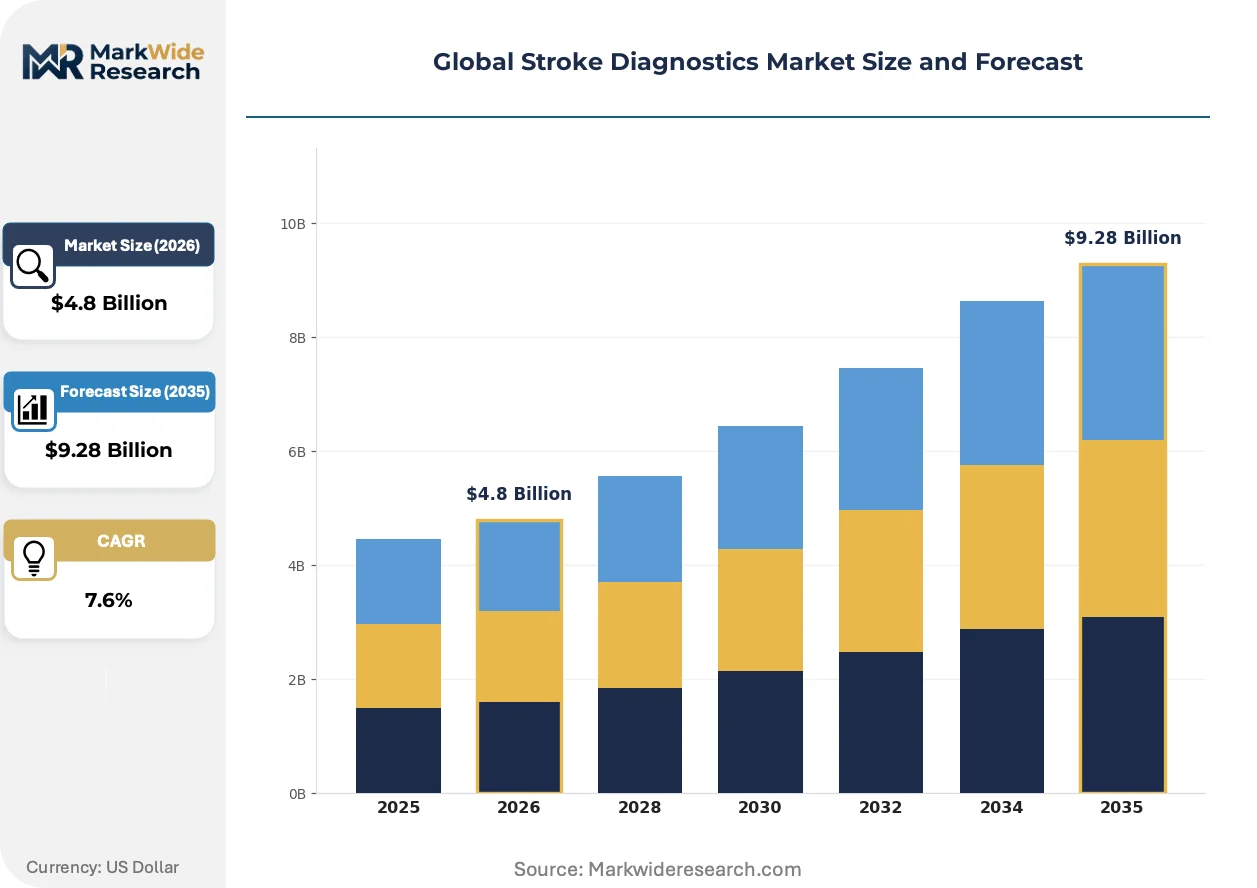
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Equipment, Neurovascular Devices, Blood Flow Monitors, Diagnostic Software Application: Ischemic Stroke, Hemorrhagic Stroke, Transient Ischemic Attack, Stroke Rehabilitation End User: Hospitals, Research Laboratories, Diagnostic Centers, Rehabilitation Facilities Technology: Computed Tomography, Magnetic Resonance Imaging, Ultrasound, Artificial Intelligence Algorithms |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Medtronic, Abbott Laboratories, Stryker Corporation, Canon Medical Systems Corporation, Roche Diagnostics, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stroke Diagnostics Market Shifts & Advancements
Stroke diagnostics is experiencing simultaneous compression of image acquisition times and interpretation workflows, with hardware acceleration and algorithmic automation converging to redefine clinical throughput benchmarks.
Computed tomography perfusion mapping is migrating from research-tier comprehensive stroke centers to standard emergency department protocols. Community hospitals in the United States are adopting these capabilities to retain thrombectomy candidates who would otherwise transfer to tertiary facilities. The technology is migrating from specialist neuroradiology suites to general radiology rotations, flattening the expertise gradient required for penumbra quantification.
The European Union's AI Act establishes risk classification frameworks for medical decision-support algorithms that influence stroke triage. CE marking requirements now mandate algorithmic transparency documentation and performance monitoring across diverse patient populations. AI software vendors targeting European hospital procurement are reengineering training datasets to satisfy bias audit provisions before MDR conformity assessment.
Academic medical centers are unbundling post-installation service contracts from capital equipment purchases, negotiating separate subscriptions for software updates and remote technical support. This purchasing pattern is displacing traditional ten-year comprehensive maintenance agreements in favor of annual renewable terms tied to uptime guarantees. Germany's university hospital networks are pioneering this shift, with G-BA reimbursement pressures forcing operational expenditure optimization.
Global Stroke Diagnostics Market Segmentation
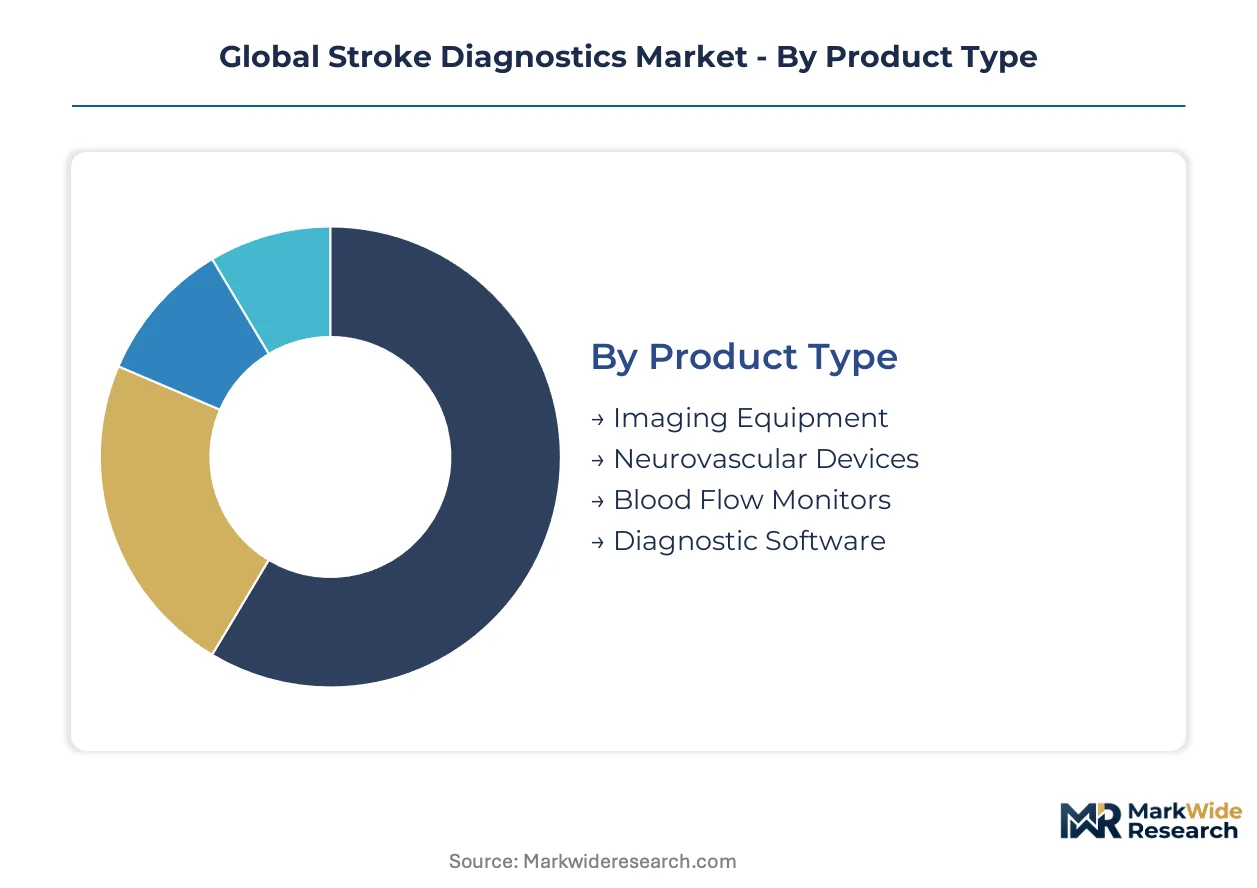
Stroke diagnostics procurement varies sharply by care setting and clinical urgency, with capital-intensive imaging suites demanding decade-long service commitments while AI software operates on renewable subscriptions. Vendors must architect entirely different commercial models across these segment boundaries.
Product Type:
After-sales service intensity peaks with imaging equipment, where magnet maintenance contracts and tube replacement schedules generate recurring revenue streams exceeding original hardware margins.
- Imaging Equipment:CT and MRI scanners with specialized neurovascular protocols require helium replenishment contracts and gradient coil servicing. Siemens Healthineers and GE Healthcare dominate tenders at comprehensive stroke centers in the United States and Germany, where 24/7 uptime clauses command premium pricing.
- Neurovascular Devices:Catheters, guidewires, and stent retrievers for mechanical thrombectomy carry single-use economics with consignment inventory models. Demand concentrates at high-volume comprehensive stroke centers performing over 100 thrombectomies annually.
- Blood Flow Monitors:Transcranial Doppler systems track cerebral autoregulation in neuro-intensive care units.
- Diagnostic Software:AI platforms for large vessel occlusion detection deploy via cloud subscriptions with per-study pricing.
By volume, Imaging Equipment leads. By growth pace, Diagnostic Software is ahead.
Application:
Cost tier stratification separates emergency ischemic stroke protocols reimbursed at DRG premium rates from rehabilitation applications dependent on bundled post-acute care payments.
- Ischemic Stroke:Acute vessel occlusion detection drives the highest-value diagnostic workflows, with CT perfusion mapping and CT angiography performed in sequence. Japan's aging population generates sustained demand for rapid imaging protocols that compress door-to-puncture intervals.
- Hemorrhagic Stroke:Non-contrast CT remains the gold standard for intracranial hemorrhage exclusion, with flat-panel CT scanners gaining traction for bedside monitoring in neuro-intensive care. Germany's university hospitals pilot mobile CT units for rapid hemorrhage triage.
- Transient Ischemic Attack:MRI with diffusion-weighted imaging identifies clinically silent infarcts that guide secondary prevention intensity.
- Stroke Rehabilitation:Functional MRI and transcranial magnetic stimulation mapping assess cortical reorganization potential.
By patient volume, Ischemic Stroke dominates. By technology intensity per case, Hemorrhagic Stroke commands comparable imaging expenditure.
End User:
Customer type determines procurement authority structure, with hospital networks centralizing capital decisions while rehabilitation facilities delegate to individual medical directors.
- Hospitals:Comprehensive stroke centers and primary stroke centers account for the dominant share of neurovascular imaging procurement. The United States maintains over 1,000 certified stroke centers with mandatory imaging capability requirements enforced by the Joint Commission.
- Research Laboratories:Academic medical centers purchase research-tier MRI scanners with 7-tesla field strength for stroke pathophysiology investigation. NIH-funded institutions in the United States drive demand for ultra-high-field systems.
- Diagnostic Centers:Outpatient imaging facilities perform carotid ultrasound and CT angiography for stroke risk stratification.
- Rehabilitation Facilities:Skilled nursing facilities and inpatient rehabilitation hospitals deploy functional assessment technologies.
By installed base, Hospitals lead. By expansion rate, Research Laboratories are climbing fastest.
Technology:
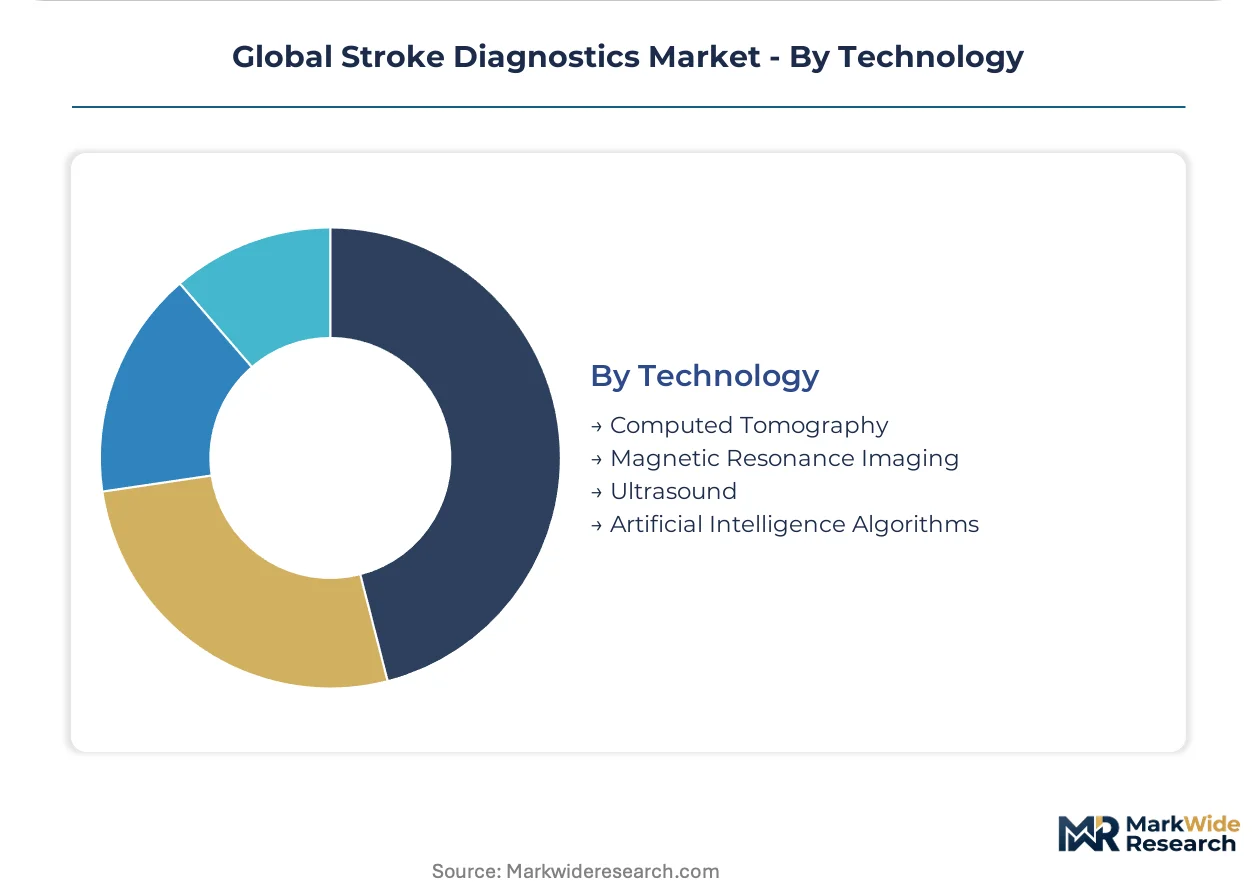
Volume concentration favors CT scanners deployed in emergency departments worldwide, while margin capture shifts toward AI algorithms with negligible marginal production cost.
- Computed Tomography:Non-contrast CT for hemorrhage exclusion and CT angiography for large vessel occlusion detection constitute the emergency standard of care. Flat-panel detector CT enables point-of-care neuroimaging in intensive care settings.
- Magnetic Resonance Imaging:Diffusion-weighted imaging detects acute infarction within minutes of symptom onset, with 3-tesla systems replacing 1.5-tesla platforms at academic centers. Helium supply constraints from Qatar and the United States create operational vulnerability.
- Ultrasound:Carotid duplex and transcranial Doppler provide portable, radiation-free hemodynamic assessment.
- Artificial Intelligence Algorithms:Automated ASPECTS scoring and large vessel occlusion notification systems integrate with PACS workflows. FDA breakthrough device clearances accelerate commercialization timelines for vendors.
By installed units, Computed Tomography leads. By investment growth, Artificial Intelligence Algorithms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in stroke diagnostics concentrates in Germany and Japan, where reimbursement clarity for AI-augmented imaging commands premium contract terms. Brazil and India operate at compressed price points, forcing vendors to strip service bundles and accept extended payment cycles.
United States
Over 1,000 Joint Commission-certified stroke centers mandate 24/7 neurovascular imaging capabilities, driving replacement demand for CT perfusion scanners. The FDA breakthrough device pathway accelerates clearance timelines for AI detection algorithms. Academic medical clusters in Boston and Houston pilot 7-tesla MRI protocols for acute infarction research.
Germany
G-BA reimbursement pressures force university hospital networks toward annual renewable service contracts rather than decade-long equipment agreements. The EU AI Act mandates algorithmic transparency documentation for stroke triage software. Medical technology procurement concentrates in Baden-Württemberg, where Siemens Healthineers anchors integrated imaging-and-software bundling.
Japan
Super-aged demographics sustain institutional demand for rapid door-to-puncture protocols, prompting hospital networks to upgrade legacy CT fleets. PMDA accelerates review for stroke AI diagnostics demonstrating equivalence to approved predicates. Tokyo and Osaka metropolitan areas host the densest concentration of comprehensive stroke centers in the Asia-Pacific region.
Brazil
Hub-and-spoke telestroke architectures across interior states create demand for cloud-connected CT scanners with automated ASPECTS scoring. ANVISA regulatory pathways for imported imaging equipment impose extended conformity assessment timelines. São Paulo's hospital networks serve as the primary staging ground for neurovascular suite modernization in Latin America.
India
CDSCO medical device regulations classify AI-assisted stroke detection software under risk-based frameworks that extend clinical evidence requirements. Diagnostic imaging procurement centralizes in Maharashtra and Karnataka, where private hospital chains invest in CT-angiography suites for tier-1 city stroke codes. Price sensitivity forces vendors to unbundle software subscriptions from hardware purchases.
Global Stroke Diagnostics Market Competitive Landscape
Integrated imaging conglomerates and AI-native software specialists split the market into divergent commercial models. Equipment vendors capture decade-long service revenue through magnet maintenance and tube replacement schedules. Software vendors pursue per-study pricing with negligible marginal production cost. Dominant competitive moves include strategic partnerships between hardware OEMs and algorithm developers, plus geographic expansion through distributor networks in underserved regions.
Among diversified medical technology conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare occupy positions that exemplify the integrated imaging-and-software archetype. These Germany-based and Netherlands-based entities anchor bundled procurement contracts at comprehensive stroke centers. Their commercial structures represent the prevailing template that forces standalone device vendors to embed AI workflows or forfeit access to neurovascular suite tenders.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Medtronic |
| Abbott Laboratories |
| Stryker Corporation |
| Canon Medical Systems Corporation |
| Roche Diagnostics |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Undercapacity in helium liquefaction facilities across Qatar and the United States constrains MRI scanner production schedules, forcing manufacturers to prioritize comprehensive stroke center contracts with premium after-sales bundling over discounted standalone hardware sales to price-sensitive buyers.
Pricing Analysis
The customization-premium spread between configured-to-order CT-angiography suites and standard emergency department scanners spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on AI workflow integration depth and Joint Commission certification tier. Cost compression in economy-tier CT scanners is intensifying because Brazilian and Indian hospital networks demand unbundled software subscriptions. Research laboratories exhibit lowest price sensitivity due to NIH and EU Horizon grant funding.
Supply Chain Analysis
Contract-manufacturing concentration for gradient coils and X-ray tubes rests on Siemens Healthineers' Erlangen facilities, GE Healthcare's Milwaukee operations, and Canon Medical Systems' Tochigi plants. Geographic supply concentration centers on Germany, Japan, and the United States for high-field MRI components. Raw material dependencies draw from niobium-titanium superconducting wire, rare earth elements for gradient assemblies, and specialized ceramics for detector arrays. Single-source vulnerability in helium extraction from Qatar creates supply chain risk. Distribution runs through hospital procurement committees and GPO contracts in developed markets, with distributor networks handling emerging market logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stroke diagnostics market represents high-growth disruption as FDA breakthrough device clearances compress AI algorithm commercialization timelines from years to months, rewriting competitive entry economics.
For Market Incumbents: Harden installed base retention by embedding proprietary AI workflows into PACS architectures that lock out standalone software vendors from neurovascular suite tenders. Deepen backward integration into helium recycling infrastructure to offset Qatar supply concentration. Prioritize annual renewable service contracts over decade-long equipment agreements to match Germany's G-BA reimbursement pressures. For New Entrants and Emerging Players: Brazil's interior telestroke networks present the most penetrable white-space opportunity, with ANVISA regulatory pathways creating first-mover windows for cloud-connected CT platforms. Target India's Maharashtra and Karnataka private hospital chains with stripped-down CT-angiography suites that separate hardware from AI subscription pricing. Pursue WHO guideline harmonization as the go-to-market angle for Southeast Asia procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI diagnostic software as cloud deployment eliminates hardware manufacturing overhead, shifting value capture toward algorithm developers with negligible marginal costs. Long-term viability favors platforms with regulatory clearances across FDA, EU MDR, and Japan PMDA jurisdictions. Monitor Medicare reimbursement decisions for AI-augmented reads as the inflection signal determining whether software subscriptions achieve standalone payment codes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates AI stroke detection clearances, compressing time-to-revenue for algorithm developers. |
| CE Marking Pathway | EU MDR and AI Act compliance opens transatlantic procurement access for comprehensive stroke centers. |
| Hospital System Partnership | Integrated imaging-and-software bundling locks out standalone vendors from neurovascular suite tenders. |
| Software Companion Development | ASPECTS scoring and LVO notification algorithms differentiate hardware platforms through workflow integration. |
| Reimbursement Strategy | Medicare and G-BA payment determinations dictate whether AI subscriptions achieve standalone fee schedules. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with neuroradiologists, hospital procurement managers, biomedical engineers, and GPO contracts directors; and secondary validation against FDA 510(k) filings, EU MDR conformity databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up triangulation across equipment install bases and top-down cross-checks against health system capital expenditure disclosures anchored volume estimates.
Forecast inputs span product type segmentation by imaging equipment, neurovascular devices, and diagnostic software; application segmentation across ischemic stroke, hemorrhagic stroke, and TIA protocols; and technology segmentation distinguishing CT, MRI, and AI algorithm deployment models. CAGRs were derived from installed base replacement cycles, regulatory clearance velocity, and reimbursement policy trajectories across the analysis window. Modeled variables include door-to-needle time compression targets, neuroradiologist workforce expansion rates, and helium supply contract durations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native software specialists bypassing hardware OEM partnerships would shift outcomes toward unbundled procurement models. Quarterly review of FDA breakthrough device clearance cadence, Medicare reimbursement determinations, and EU MDR conformity assessment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Global Sepsis Diagnostics Market