
 Global Premenstrual Syndrome Treatment Market | 2026-2036
Global Premenstrual Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premenstrual Syndrome Treatment Market Foresight
Serotonin reuptake modulation is pivoting from older tricyclic frameworks toward SSRI-based formulations with improved tolerability profiles. Eli Lilly and Company leverages its neurosciences pipeline to sustain leadership in mood-targeted therapeutics. Bayer AG anchors its position through integrated women's health portfolios spanning hormonal and non-hormonal modalities. Dr Reddy's Laboratories Ltd competes on cost-optimized manufacturing scale for generic SSRI equivalents.
Premenstrual syndrome treatment encompasses pharmacological and non-pharmacological interventions addressing luteal-phase symptom clusters, with SSRI compounds typically administered at dosages of 10–20 mg daily or in luteal-phase-specific regimens. The primary commercial purpose centers on reducing functional impairment across emotional, physical, and behavioral domains during the menstrual cycle. Medications occupy the dominant value share as first-line clinical protocols, while nutraceuticals represent the fastest-expanding category as patients seek magnesium and vitamin B6 supplementation with lower side-effect burdens. The oral delivery mode retains institutional preference, though transdermal formats are gaining traction among patients with gastrointestinal tolerability concerns.
The FDA maintains stringent efficacy demonstration requirements for PMS-specific indications through randomized controlled trial mandates, while the EMA's MDR framework governs companion diagnostic and digital therapeutic adjacencies in Europe. Japan's PMDA applies distinct cultural-symptom validation criteria that shape product development priorities for entrants targeting that market. Stakeholders must monitor evolving pharmacovigilance requirements for CNS-active compounds and the integration of digital biomarkers into regulatory submissions.
Market Dynamics
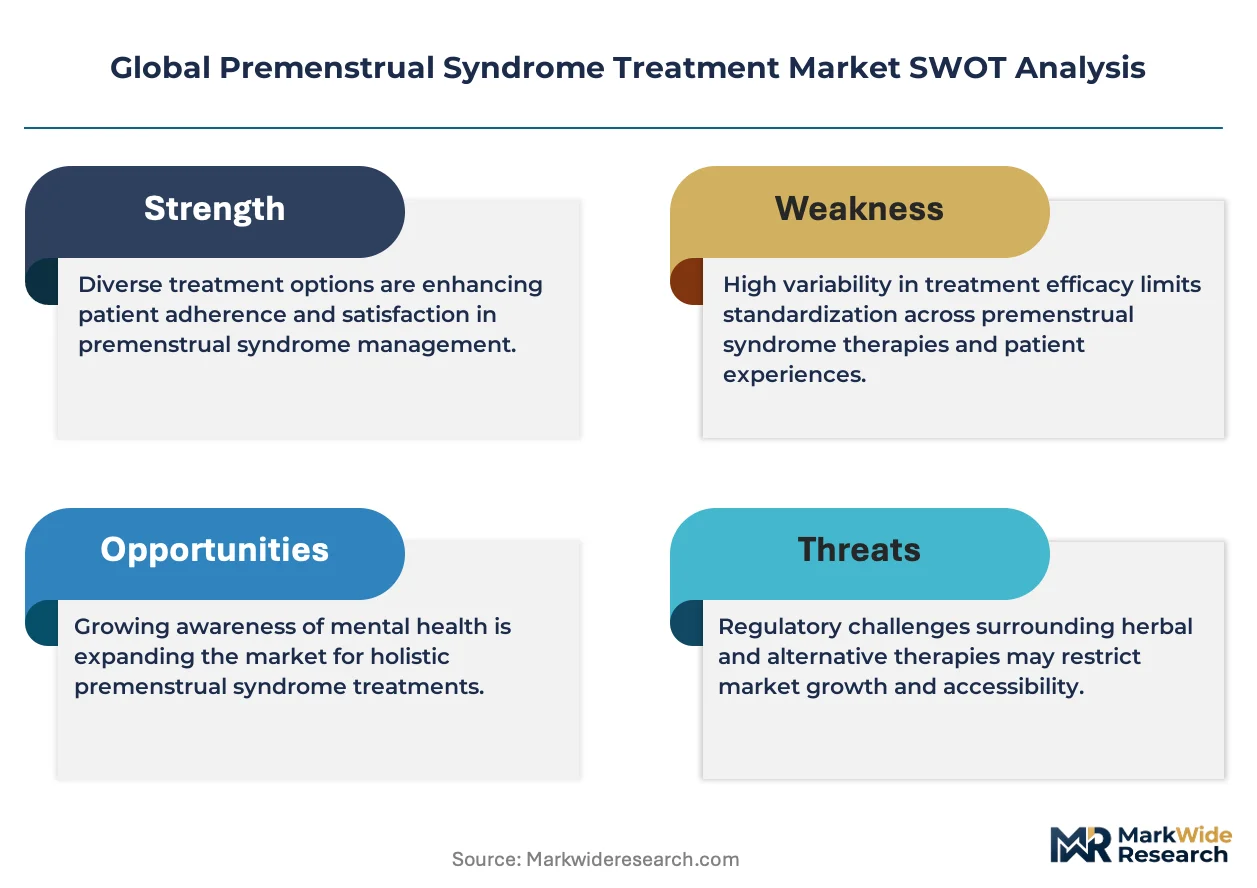
The FDA's streamlined review pathways for women's health therapeutics are compressing development timelines and redirecting R&D investment toward luteal-phase-specific formulations. This regulatory acceleration is restructuring competitive priorities across pharmaceutical and nutraceutical segments.
Growth Catalysts
- SSRI tolerability improvements:Luteal-phase-specific dosing regimens reduce discontinuation rates and expand prescriber comfort with first-line pharmacological intervention.
- FDA streamlined pathways:Accelerated approval mechanisms for women's health indications are shortening time-to-market for new molecular entities targeting mood and physical symptom clusters.
- Magnesium and vitamin B6 supplementation:Patient-driven demand for lower side-effect burden alternatives is expanding the nutraceutical category faster than institutional protocols.
Market Restraints
- Active pharmaceutical ingredient concentration:Generic SSRI manufacturing relies on concentrated supply from Indian and Chinese API producers, creating vulnerability to export policy shifts.
- EMA MDR compliance costs:Companion diagnostic and digital therapeutic adjacencies face elevated certification expenses that compress margins for mid-scale entrants.
- Tricyclic antidepressant substitution:Older frameworks retain formulary placement in cost-constrained reimbursement systems, delaying SSRI protocol adoption.
Strategic Opportunities
- Japan symptom validation criteria:PMDA's culturally-specific endpoint requirements create first-mover advantage for entrants adapting mood-targeted therapeutics to local presentation patterns.
- Transdermal delivery innovation:Gastrointestinal tolerability concerns among luteal-phase patients are opening formulation differentiation beyond oral dominance.
- Digital biomarker integration:Regulatory submissions incorporating wearable-derived cycle tracking data are gaining priority review consideration from the FDA.
Industry Challenges
- Neurosciences talent scarcity:Specialized clinical trial design expertise for CNS-active compounds commands premium compensation, constraining mid-tier sponsor capacity.
- Pharmacovigilance system integration:Legacy adverse event reporting infrastructure requires costly reconfiguration to capture real-world data from patient-administered luteal-phase regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premenstrual Syndrome Treatment Market |
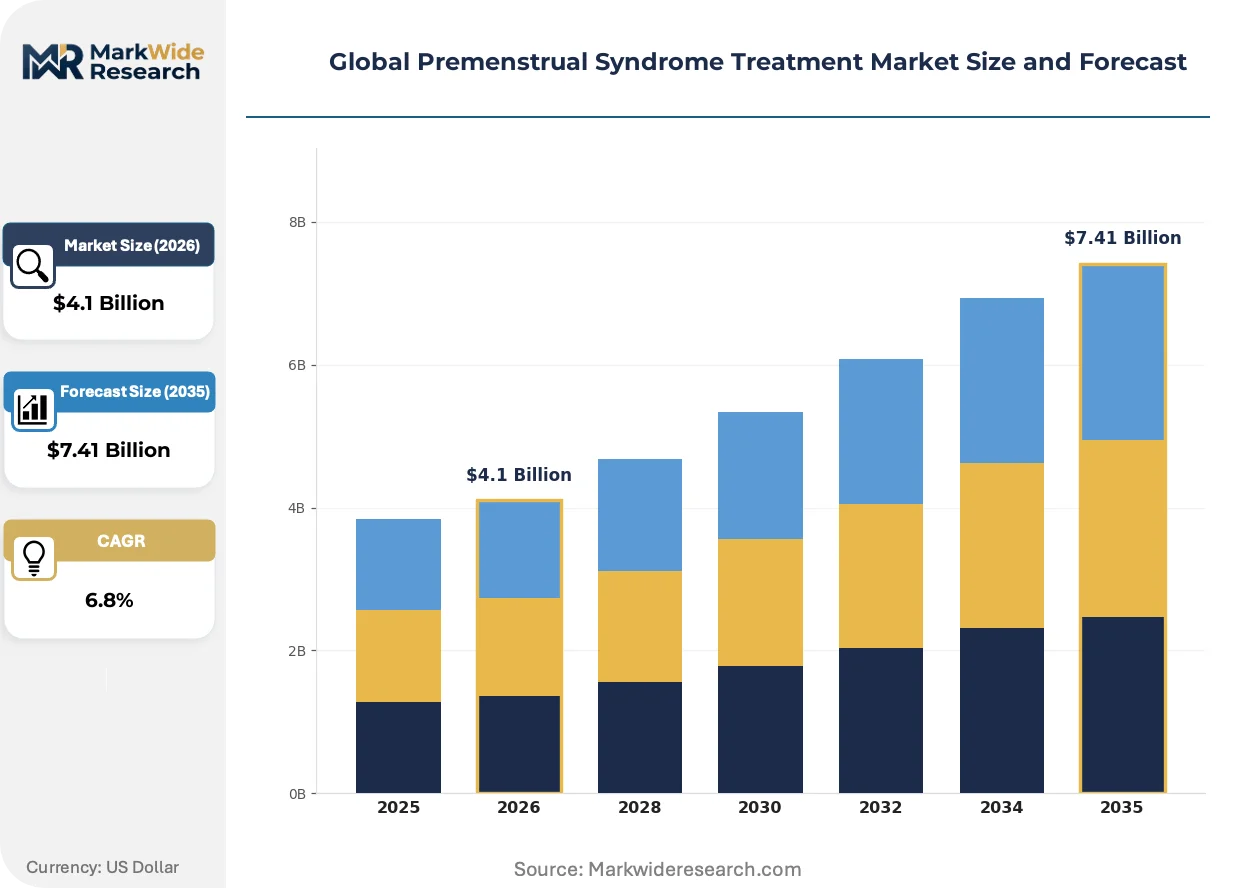
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Nutraceuticals, Herbal Remedies, Lifestyle Products Therapy Area: Physical Symptoms, Emotional Symptoms, Hormonal Treatments, Complementary Therapies End User: Clinics, Hospitals, Pharmacies, Online Platforms Delivery Mode: Oral, Transdermal, Injectable, Inhalation |
| Companies Covered | GlaxoSmithKline Plc, AbbVie Inc, Bayer AG, Eli Lilly and Company, Pfizer Inc, H Lundbeck A/S, AstraZeneca plc, Dr Reddy’s Laboratories Ltd, Shionogi Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premenstrual Syndrome Treatment Market Shifts & Advancements
Serotonin reuptake modulation is fragmenting across delivery modalities and dosing paradigms. Innovators are exploiting regulatory flexibility and patient preference data to compress traditional development cycles.
Transdermal SSRI patches are overtaking oral formulations among patients reporting gastrointestinal intolerance during luteal-phase symptom peaks. Gynecology clinics in Germany and the United States are piloting these systems for patients with prior discontinuation history. The technology is overtaking institutional preference for oral delivery by demonstrating comparable efficacy with reduced systemic side-effect profiles.
EMA's MDR framework for companion diagnostics is mandating clinical validation standards that exceed prior CE-marking requirements. Device-therapeutic combination submissions now require synchronized trial designs that lengthen initial filing timelines. European gynecology networks are responding by consolidating procurement around established diagnostic partners with proven regulatory track records.
Patients are self-directing toward cycle-tracking applications that generate longitudinal symptom data for clinical consultations. This behavioral shift is compressing the traditional diagnostic gap between symptom onset and treatment initiation. The United States and Japan exhibit the highest concentration of platform-integrated care pathways where digital biomarkers inform prescription decisions.
Global Premenstrual Syndrome Treatment Market Segmentation
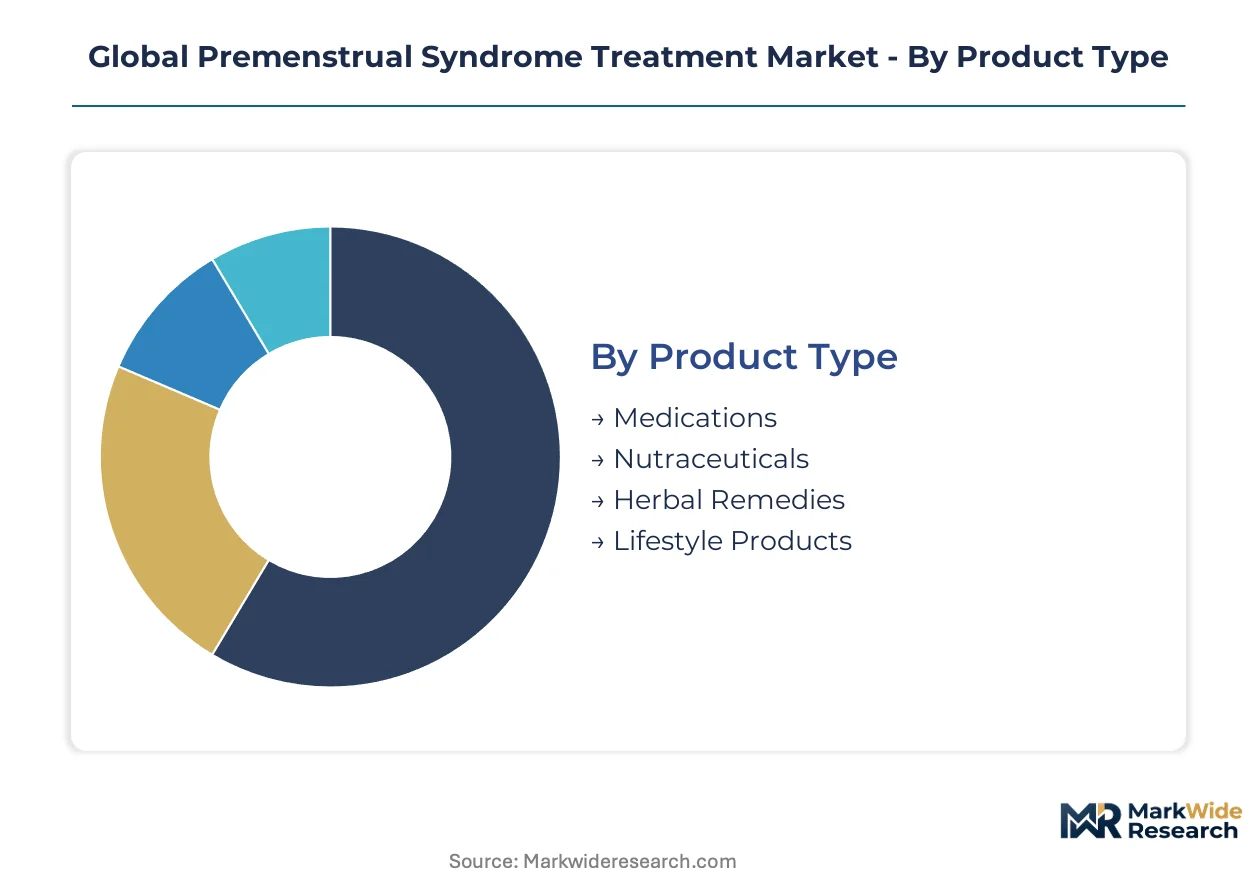
Segmentation in the PMS treatment market reveals divergent supply chain configurations across pharmacological and non-pharmacological modalities. Each category channels manufacturing investment toward distinct regulatory compliance burdens and patient access pathways.
Product Type:
Supply concentration clusters around API manufacturing hubs in India and China for synthetic compounds, while botanical extraction networks serve nutraceutical and herbal categories.
- Medications:SSRI formulations and hormonal interventions dominate institutional procurement. FDA streamlined pathways accelerate approvals for luteal-phase-specific dosing regimens in the United States.
- Nutraceuticals:Magnesium and vitamin B6 complexes lead patient-driven demand expansion. Germany's pharmacy reimbursement frameworks favor evidence-based supplementation protocols.
- Herbal Remedies:Chasteberry and evening primrose oil formulations circulate through specialty retail channels.
- Lifestyle Products:Heat therapy devices and sleep optimization tools target symptom management without pharmacological intervention.
Medications absorb the bulk of installed capacity; nutraceuticals are expanding most quickly.
Therapy Area:
Cost tier stratification separates premium biologic hormonal interventions from generic SSRI equivalents and low-margin complementary approaches.
- Physical Symptoms:Analgesic and anti-inflammatory protocols address bloating, breast tenderness, and cramping. Japan's PMDA applies distinct cultural-symptom validation criteria that shape product development priorities for pain-targeted entrants.
- Emotional Symptoms:Mood-targeted therapeutics concentrate R&D investment from neurosciences specialists. Eli Lilly leverages its pipeline to sustain leadership in this high-value segment.
- Hormonal Treatments:Oral contraceptives and GnRH analogs require specialized manufacturing infrastructure.
- Complementary Therapies:Acupuncture and cognitive behavioral therapy integration gains traction in Western European gynecology networks.
Emotional symptom interventions command premium pricing; complementary therapies are climbing the fastest as patients seek multimodal management.
End User:
Volume concentration shifts toward direct-to-patient channels as digital platforms displace traditional pharmacy dispensing for recurring prescriptions.
- Clinics:Gynecology practices in the United States and Germany pilot transdermal delivery systems and cycle-tracking integration. These sites generate longitudinal data that informs regulatory submissions incorporating digital biomarkers.
- Hospitals:Acute intervention for severe PMDD presentations drives episodic high-value utilization.
- Pharmacies:Community dispensing retains dominance for first-line SSRI prescriptions.
- Online Platforms:Telehealth prescribing and subscription nutraceutical delivery capture patient preference for convenience.
Clinics absorb the bulk of installed capacity; online platforms are gaining share fastest.
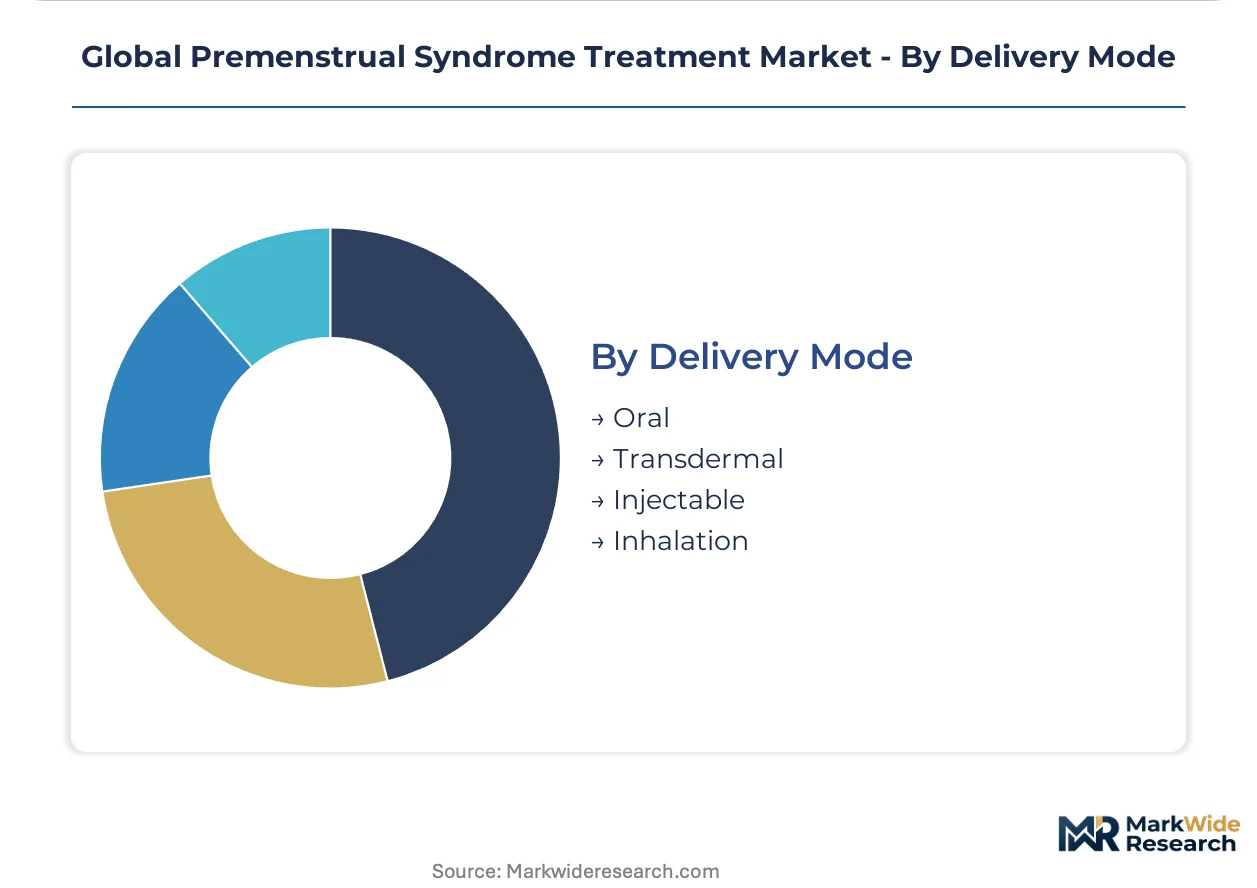
Delivery Mode:
Application requirements dictate formulation investment, with gastrointestinal tolerability concerns driving innovation beyond oral dominance.
- Oral:Tablet and capsule formats retain institutional preference for SSRI and hormonal protocols. Bayer AG anchors its position through integrated portfolios spanning these established delivery systems.
- Transdermal:Patch-based delivery overtakes oral formulations among patients reporting nausea during luteal-phase symptom peaks. German and United States gynecology networks pilot these systems for patients with prior discontinuation history.
- Injectable:Depot formulations serve long-acting hormonal suppression needs.
- Inhalation:Aromatherapy and acute anxiolytic delivery remain niche applications.
Oral delivery absorbs the bulk of installed capacity; transdermal formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where reimbursement frameworks favor evidence-based PMS interventions. Gynecology clinics across these markets are expanding non-hormonal prescription protocols. Regulatory acceleration through streamlined review pathways is compressing development timelines for new entrants.
United States
FDA streamlined pathways for women's health therapeutics are accelerating new molecular entity approvals. Gynecology networks in Boston and the Research Triangle pilot transdermal delivery systems and cycle-tracking integration. These sites generate longitudinal data that informs regulatory submissions incorporating digital biomarkers.
Germany
Germany's pharmacy reimbursement frameworks favor evidence-based supplementation protocols for magnesium and vitamin B6 complexes. EMA's MDR framework governs companion diagnostic and digital therapeutic adjacencies with elevated certification requirements. Bavaria and North Rhine-Westphalia host concentrated gynecology clinic networks piloting non-hormonal protocols.
Japan
PMDA applies distinct cultural-symptom validation criteria that shape product development priorities for mood-targeted entrants. Patient-driven demand for lower side-effect burden alternatives is expanding the nutraceutical category faster than institutional protocols. Tokyo and Osaka metropolitan areas exhibit the highest concentration of platform-integrated care pathways.
United Kingdom
NICE guidelines influence prescribing patterns for SSRI-based formulations with improved tolerability profiles. MHRA post-Brexit regulatory autonomy is creating divergence from EMA harmonization timelines. London and the Greater Manchester health innovation clusters are consolidating procurement around established diagnostic partners.
India
CDSCO oversight of active pharmaceutical ingredient manufacturing creates compliance leverage for export-oriented producers. Cost-optimized manufacturing scale for generic SSRI equivalents attracts contract manufacturing demand. Hyderabad and Mumbai pharmaceutical corridors concentrate API synthesis and formulation capacity for global supply.
Global Premenstrual Syndrome Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents expand across hormonal and non-hormonal modalities. The vendor base separates into three tiers: integrated pharmaceutical conglomerates with neurosciences pipelines, mid-scale generic manufacturers leveraging cost-optimized production, and regional specialists targeting culturally-specific symptom presentations. Strategic archetypes include mood-targeted therapeutic specialists, women's health portfolio integrators, and API-to-formulation vertical operators. M&A activity and transdermal delivery innovation represent the dominant competitive vectors reshaping positioning.
Among neurosciences-focused developers, Eli Lilly and Company and H Lundbeck A/S exemplify the mood-targeted therapeutic archetype through sustained R&D commitment to CNS-active compounds. Bayer AG occupies a position within the integrated portfolio tier, anchoring women's health market presence across delivery modalities. Dr Reddy's Laboratories Ltd represents the scale-driven manufacturing archetype, leveraging Indian production corridors for cost-optimized supply to global markets.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| AbbVie Inc |
| Bayer AG |
| Eli Lilly and Company |
| Pfizer Inc |
| H Lundbeck A/S |
| AstraZeneca plc |
| Dr Reddy's Laboratories Ltd |
| Shionogi Inc |
| Others |
Supply & Pricing Matrix
Specialized neurosciences talent concentration in Boston and Basel creates labor-cost differentials that widen pricing-tier spreads between premium SSRI formulations and commoditized generic equivalents. API synthesis expertise commands premium compensation that manufacturers pass through to institutional buyers, while cost-optimized production corridors in India compress margins for standard-grade entrants.
Pricing Analysis
Volume concentration in generic SSRI equivalents absorbs procurement volume, while margin capture clusters in luteal-phase-specific formulations and transdermal delivery innovations. Three-tier pricing structure across premium, standard, and economy levels separates patented neurosciences compounds from authorized generics and unbranded API-sourced tablets. Price differentiation hinges on FDA-tier certification status and prescriber familiarity with tolerability profiles. Cost compression in the generic tier intensifies as Indian manufacturers expand capacity, with hospital systems exhibiting lowest price sensitivity and retail pharmacy chains most responsive to tender-based procurement.
Supply Chain Analysis
Dual-sourcing requirements from European and North American gynecology networks mandate multi-supplier qualification for SSRI active pharmaceutical ingredients, forcing formulators to maintain parallel vendor relationships. Supply concentration clusters in India, China, and Switzerland for synthetic compounds, with botanical extraction networks spanning Germany and Italy for chasteberry and evening primrose oil. Raw material dependencies include fluoxetine hydrochloride precursors, magnesium oxide compounds, and specialized patch substrates for transdermal systems. Single-source vulnerability persists for luteal-phase-specific dosing technologies protected by process patents. Distribution runs through hospital procurement consortia and pharmacy benefit managers in the United States, with direct-to-patient subscription models gaining share in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as incumbents pursue captive API supply to defend margin structures against Indian generic exporters. Control over neurosciences manufacturing capacity represents the decisive upstream lever separating premium pricing tiers from commodity compression.
For Market Incumbents: Anticipate regulatory acceleration by pre-positioning luteal-phase-specific dossiers ahead of FDA streamlined pathway deadlines. Secure backward integration into SSRI API production to neutralize supply disruption threats from Indian export policy shifts. Prioritize transdermal formulation R&D to capture patients with gastrointestinal intolerance discontinuation history.
For New Entrants and Emerging Players: Digital biomarker-enabled prescribing platforms offer technology-first wedge positioning against established oral-delivery incumbents. Target Japan's culturally-specific symptom validation gap where PMDA requirements have slowed multinational entry. Pursue white-space capture in magnesium-vitamin B6 combination nutraceuticals through pharmacy reimbursement alignment in Germany.
For Investors and Strategic Acquirers: The window for entry favors mid-scale API-to-formulation operators with proven CDSCO compliance and European gynecology network relationships. Long-term viability rests on consolidation plays that aggregate manufacturing scale across generic SSRI and hormonal portfolios. Watch for FDA digital biomarker guidance publication as inflection signal for platform-integrated care pathway valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Scale-Up | Captures gastrointestinal-intolerant patients in German and United States gynecology networks. |
| API Backward Integration | Reduces exposure to Indian and Chinese export policy volatility for SSRI manufacturing. |
| Digital Biomarker Platform Partnership | Aligns with FDA priority review consideration for wearable-derived cycle tracking data. |
| Japan PMDA Symptom Adaptation | Unlocks first-mover positioning in culturally-specific mood-targeted therapeutic endpoints. |
| Nutraceutical Reimbursement Strategy | Secures pharmacy formulary placement for magnesium-B6 complexes in German frameworks. |
Research Methodology
Independent corroboration across regulatory submission databases, hospital procurement records, and pharmaceutical trade flows underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and gynecology clinic procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling and top-down revenue reconciliation anchored the segmentation outputs.
Comparable-period anchoring to historical prescription volume trends and API production capacity utilization established the forecast baseline across the projection horizon. The analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate blending with patent expiration and generic entry timing assumptions. Forecast inputs incorporated prescriber adoption curves for luteal-phase-specific regimens and nutraceutical reimbursement expansion trajectories.
Several conditions sit outside the modeled scope, including unforeseen FDA adverse event findings for CNS-active compounds, abrupt EMA MDR enforcement changes, and geopolitical trade restrictions affecting API flows. Forecasts reflect documented assumptions regarding prescriber comfort with SSRI first-line protocols and patient self-direction toward supplementation alternatives. Deviation in regulatory review timelines or pharmacovigilance requirement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Anti-Fungal Treatment Market