
 Veterinary Anti-Infectives Market | 2026-2036
Veterinary Anti-Infectives Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Anti-Infectives Market Intelligence
Buyer concentration across large-scale livestock operations and corporate veterinary chains is broadening the addressable base for bulk anti-infective procurement. Zoetis leverages its manufacturing scale to serve integrated pork and poultry producers across multiple continents. Boehringer Ingelheim anchors its position through R&D intensity in vaccine-antibiotic combination therapies. Merck Animal Health differentiates by controlling distribution channels that reach fragmented farm-level buyers in emerging production zones.
Veterinary anti-infectives comprise pharmaceutical agents formulated to inhibit or eliminate pathogenic microorganisms in animals, typically requiring species-specific pharmacokinetic profiles and residue withdrawal periods to ensure food safety. These products serve the primary commercial purpose of maintaining herd health, reducing mortality, and preserving the economic value of livestock and companion animal populations. Antibiotics occupy the largest revenue pool among product types due to entrenched use in mastitis control and respiratory disease management, while antiparasitics represent the fastest-expanding category driven by climate-driven vector migration and expanded companion animal prophylaxis. Companion animals command premium pricing relative to production animals, though the latter generates higher absolute volumes through farm-level procurement.
The FDA's Veterinary Feed Directive and the EMA's guidelines on responsible antibiotic use shape product registration pathways and restrict over-the-counter sales in major markets. The EU Green Deal's Farm to Fork strategy further tightens antimicrobial use targets, forcing reformulation investments and alternative therapy development. Stakeholders must monitor evolving residue testing protocols and antimicrobial stewardship mandates to anticipate which product categories will retain market access.
Market Dynamics
Antimicrobial stewardship mandates are compressing prescription volumes while simultaneously elevating unit prices for residue-compliant therapeutics, fundamentally restructuring how veterinary clinics and livestock operations source anti-infective portfolios.
Growth Catalysts
- Companion animal insurance expansion:Rising pet insurance penetration in the United States and Western Europe reduces price sensitivity for premium anti-infective therapies, expanding the addressable market for advanced formulations.
- FDA Veterinary Feed Directive:Prescription requirements for medically important antibiotics in feed create formal veterinary-client-patient relationships, channeling demand through licensed practitioners.
- Climate-driven vector expansion:Warming temperatures extend tick and parasite habitats northward, necessitating expanded prophylactic antiparasitic coverage in previously temperate livestock zones.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India dominate bulk antibiotic intermediate production, exposing formulators to supply disruptions and input cost volatility.
- EU Green Deal Farm to Fork targets:Mandatory antimicrobial reduction goals force premature product obsolescence and stranded inventory for non-compliant formulations.
- Biologic substitution threat:Vaccine and phage therapy development programs erode the chronic-use antibiotic segment in poultry and swine operations.
Strategic Opportunities
- Brazilian livestock consolidation:Integrated beef and poultry producers in Mato Grosso and Paraná seek volume procurement partnerships for herd health programs.
- Pharmacogenomic dosing platforms:Integration of rapid pathogen sequencing with species-specific pharmacokinetic modeling enables precision therapy selection.
- Direct-to-producer telemedicine channels:Virtual veterinary platforms bypass traditional distribution intermediaries, capturing margin and prescription control.
Industry Challenges
- Veterinary pharmacovigilance expertise scarcity:Qualified professionals capable of managing adverse event reporting and residue monitoring programs command premium compensation.
- Withdrawal period validation complexity:Species-specific residue depletion studies require extended timelines and specialized analytical laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Anti-Infectives Market |
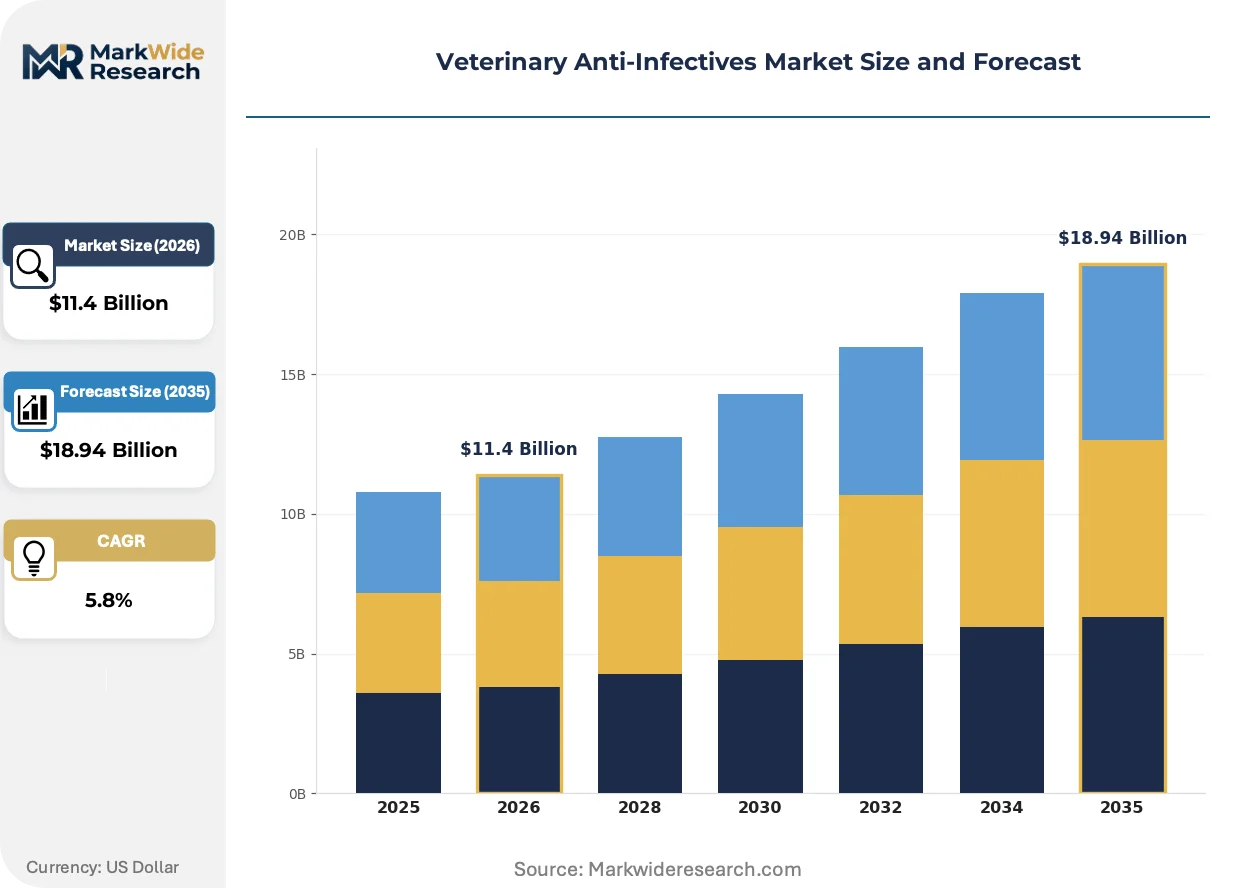
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Antifungals, Antiparasitics, Immunomodulators Animal Type: Companion Animals, Production Animals, Equines, Aquatic Species, Avian Species Administration Route: Oral, Injectable, Topical, Inhalation, Intramammary, Intravaginal End User: Veterinary Clinics, Animal Hospitals, Farms, Research Institutions, Animal Pharmacies |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Dechra Pharmaceuticals, Vetoquinol, Phibro Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Anti-Infectives Market Strategic Shifts & Innovations
Rapid diagnostics and alternative therapeutic modalities are fragmenting the traditional antibiotic-centric treatment paradigm, compelling manufacturers to reconfigure R&D priorities and commercial architectures around prevention-first portfolios.
Point-of-care polymerase chain reaction testing is decentralizing pathogen identification from centralized laboratories to clinic and farm settings. Large-scale dairy operations and corporate veterinary chains deploy portable diagnostic units to enable same-day susceptibility profiling. This capability is decentralizing treatment decision authority from specialist consultants to frontline practitioners, compressing the window between diagnosis and targeted therapy initiation.
REACH antimicrobial environmental risk assessment requirements are mandating ecotoxicity data packages for all new veterinary pharmaceutical registrations. Formulators must now demonstrate biodegradation pathways and aquatic toxicity profiles prior to market authorization. The swine and poultry segments face the steepest compliance burden, driving accelerated investment in green chemistry process modifications.
Subscription-based herd health management contracts are displacing transactional product sales in North American cattle feedlots. These arrangements bundle diagnostics, therapeutics, and veterinary labor into per-animal fees, transferring outcome risk from the buyer to the supplier. The model is most visible in the United States Plains states, where consolidated beef operations seek predictable cost structures for respiratory disease prevention programs.
Veterinary Anti-Infectives Market Segmentation
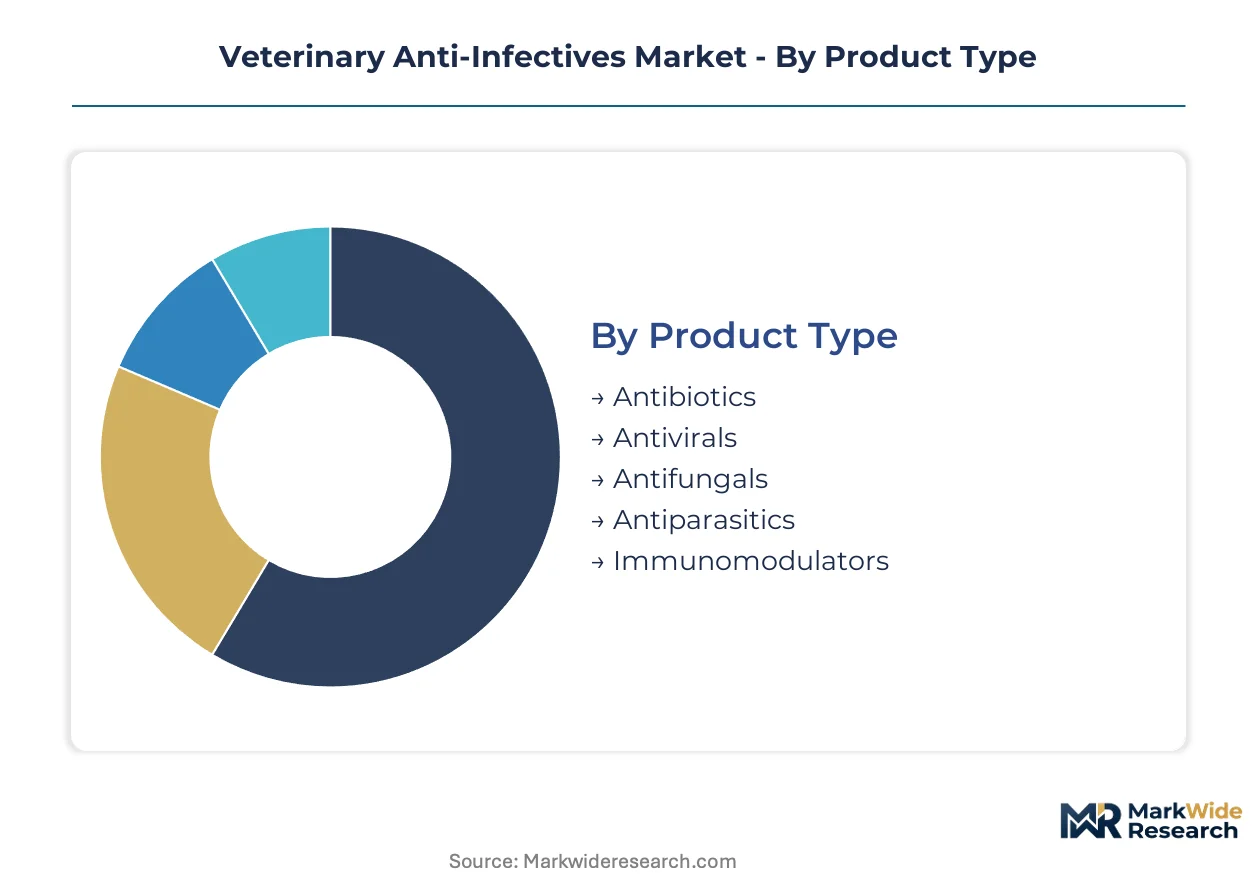
Veterinary anti-infectives require precise formulation matching across species pharmacokinetics, residue withdrawal protocols, and administration feasibility. Segmentation reveals where pricing power concentrates and which delivery formats face substitution pressure from diagnostics and biologics.
Product Type:
Standardization dominates commodity antibiotics while antiparasitics and immunomodulators command customization premiums for vector resistance and species-specific dosing.
- Antibiotics:Beta-lactams, tetracyclines, and macrolides formulated for mastitis control and respiratory disease management in dairy and feedlot operations. Demand concentrates in the United States where FDA Veterinary Feed Directive prescriptions channel procurement through licensed veterinarians, constraining over-the-counter access but stabilizing unit pricing for residue-compliant formulations.
- Antiparasitics:Endectocides, benzimidazoles, and ectoparasiticides targeting climate-driven vector expansion into temperate zones. Expansion is steepest in Western Europe where tick migration necessitates expanded companion animal prophylaxis and where EMA guidelines on environmental risk assessment accelerate green chemistry investments in formulation biodegradation.
- Antivirals:Nucleoside analogs and neuraminidase inhibitors for equine influenza and feline herpesvirus management.
- Antifungals:Azoles and polyenes addressing dermatophytosis in companion animals and aspergillosis in avian species.
- Immunomodulators:Cytokine therapies and toll-like receptor agonists enabling vaccine adjuvant applications and chronic infection management.
Most installed capacity flows through Antibiotics. Expansion is steepest in Antiparasitics.
Animal Type:
Volume scales inversely with margin across this category—production animals drive tonnage while companion species sustain premium pricing.
- Companion Animals:Dogs, cats, and exotic pets receiving individualized therapy selection supported by pet insurance reimbursement. Demand clusters in urban veterinary clinics across the United States, Germany, and the United Kingdom where diagnostic workups precede targeted anti-infective prescribing.
- Production Animals:Cattle, swine, and small ruminants managed through herd health protocols emphasizing prevention and metaphylaxis. Procurement concentrates in integrated operations across Brazil, the United States Plains states, and Denmark where volume contracts bundle diagnostics, therapeutics, and veterinary labor.
- Equines:Racing and pleasure horses requiring anthelmintic rotation programs and respiratory infection management.
- Aquatic Species:Salmon, shrimp, and ornamental fish in recirculating aquaculture systems facing limited therapeutic options due to environmental discharge restrictions.
- Avian Species:Layer and broiler chickens subject to strict antimicrobial reduction targets under EU Green Deal Farm to Fork mandates.
Production Animals absorb the highest absolute volumes. Companion Animals generate the steepest margin expansion.
Administration Route:
Route selection balances bioavailability requirements against labor constraints and residue control precision.
- Oral:Water-soluble powders, premixes, and bolus formulations enabling mass medication in swine and poultry operations. Adoption concentrates in automated feeding systems across the United States and Brazil where labor scarcity drives preference for medicated feed and water delivery over individual animal handling.
- Injectable:Long-acting formulations providing sustained plasma concentrations for respiratory disease metaphylaxis in cattle. Demand clusters in North American feedlots and Brazilian integrated beef operations where single-dose convenience reduces chute time and labor exposure.
- Topical:Pour-ons, sprays, and ointments for ectoparasite control and localized dermatological infections.
- Inhalation:Nebulized antibiotics for equine respiratory disease and swine influenza management.
- Intramammary:Dry cow and lactating cow formulations for mastitis prevention and treatment in dairy herds.
- Intravaginal:Pessaries and infusions for metritis control and reproductive tract infections in cattle.
Oral delivery handles the largest prescription volumes. Injectable formats are climbing the fastest as long-acting formulations displace repeated dosing protocols.
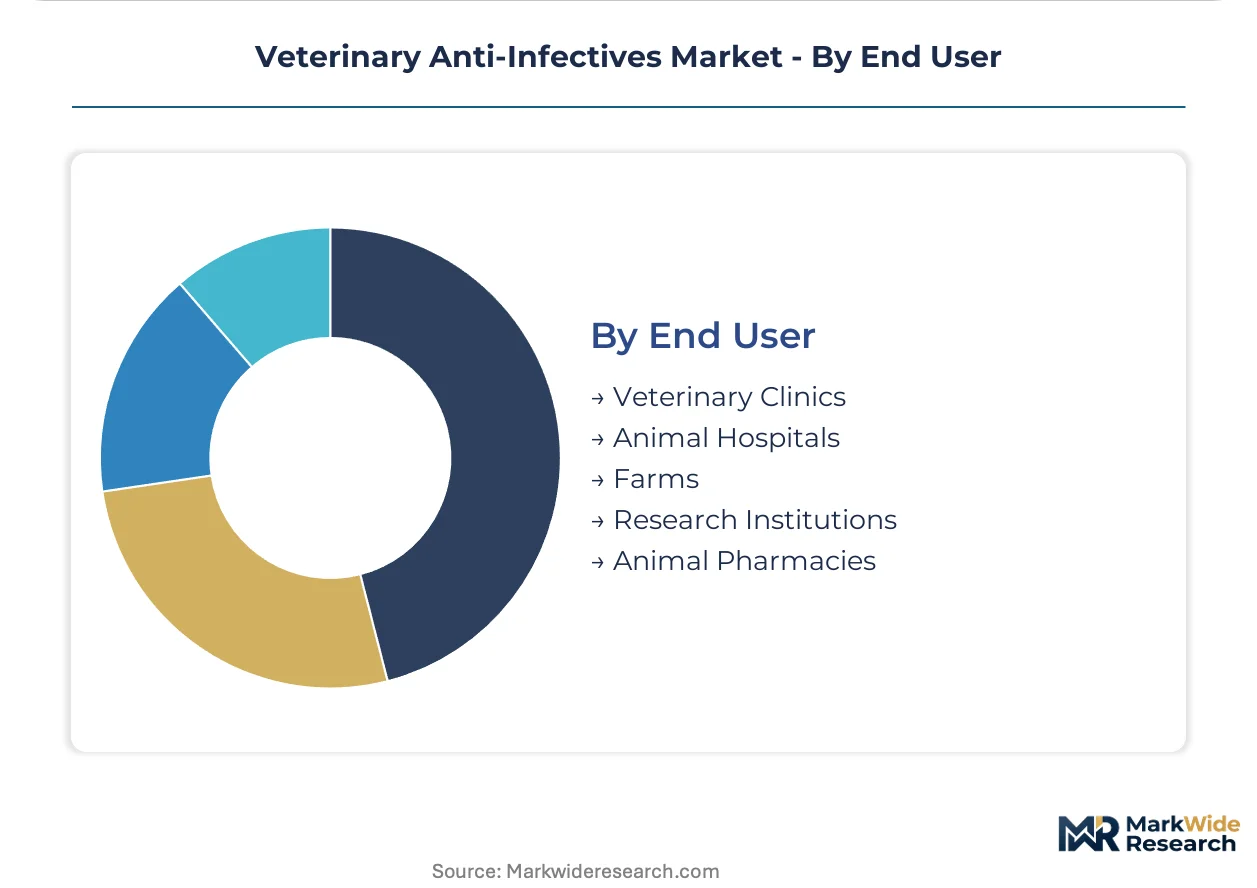
End User:
Channel structure fragments between institutional procurement and retail dispensing, each with distinct regulatory and margin profiles.
- Veterinary Clinics:Primary care and specialty practices capturing prescription authority under FDA and EMA antimicrobial stewardship mandates. Concentration is highest in the United States and France where corporate veterinary chains consolidate purchasing and standardize formularies across multi-site networks.
- Farms:Direct procurement by integrated livestock operations and cooperatives bypassing traditional distribution. Expansion is steepest in Brazil's Mato Grosso and Paraná states where beef and poultry consolidation enables volume-based herd health contracting.
- Animal Hospitals:24-hour emergency and referral centers managing complex infectious cases in companion animals.
- Research Institutions:Universities and contract research organizations conducting pharmacokinetic studies and antimicrobial resistance surveillance.
- Animal Pharmacies:Compounding and retail dispensing operations filling prescriptions for companion animal owners.
Veterinary Clinics control the highest-value prescription flows. Farms are gaining share fastest through direct procurement and telemedicine-enabled veterinary relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian livestock consolidation contrasts sharply with European antimicrobial reduction mandates, creating divergent procurement patterns across major veterinary markets. Regulatory frameworks in the United States and Western Europe tighten prescription protocols while emerging production zones expand volume contracting.
United States
Companion animal insurance expansion and corporate veterinary chain consolidation drive premium anti-infective demand. The FDA Veterinary Feed Directive channels antibiotic procurement through licensed practitioners, constraining over-the-counter access. Texas and Iowa feedlot clusters adopt subscription-based herd health contracts bundling diagnostics with therapeutics.
Germany
EMA antimicrobial stewardship guidelines and REACH environmental risk assessments elevate compliance costs for residue-compliant formulations. The EU Green Deal Farm to Fork strategy accelerates green chemistry investments. Bavarian dairy cooperatives integrate precision dosing platforms with rapid pathogen sequencing capabilities.
Brazil
Integrated beef and poultry producers in Mato Grosso and Paraná seek volume procurement partnerships for respiratory disease prevention programs. ANVISA registration pathways align with export-market residue standards. São Paulo-based corporate veterinary chains standardize formularies across multi-site networks serving fragmented farm-level buyers.
China
Domestic livestock biosecurity upgrades and aquaculture expansion sustain anti-infective demand despite antimicrobial reduction targets. The country's national pharmaceutical regulator tightens environmental discharge restrictions for recirculating aquaculture systems. Shandong Peninsula poultry operations face steep compliance burdens for ecotoxicity data packages.
United Kingdom
Urban veterinary clinic concentration in London and the Southeast sustains premium pricing for individualized companion animal therapies. Pet insurance reimbursement reduces price sensitivity for advanced formulations. Midlands-based dairy operations deploy portable diagnostic units enabling same-day susceptibility profiling for mastitis management.
Veterinary Anti-Infectives Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation characterizes the upper tier where manufacturing scale determines access to integrated livestock operations, while mid-tier fragmentation persists among regional formulators serving fragmented farm-level buyers. Three archetypes dominate: multinational pharmaceutical conglomerates leveraging R&D intensity, pure-play animal health specialists controlling niche therapeutic categories, and emerging telemedicine-enabled platforms bypassing traditional distribution. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers seek backward integration into active pharmaceutical ingredient supply.
Within the multinational conglomerate tier, Zoetis, Boehringer Ingelheim, and Merck Animal Health exemplify scale-driven positioning. These entities occupy positions anchored in manufacturing breadth and continental distribution reach. Zoetis represents the integrated production animal specialist archetype. Boehringer Ingelheim exemplifies vaccine-antibiotic combination therapy focus. Merck Animal Health sits within the channel-control archetype targeting emerging production zones.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals |
| Vetoquinol |
| Phibro Animal Health |
| Others |
Cost & Logistics Intelligence
Premium residue-compliant formulations and commodity-grade antibiotics diverge across a widening price-performance gap, with the former commanding sustained premiums through FDA Veterinary Feed Directive prescription channels while the latter faces compression from Indian and Chinese API oversupply. This bifurcation reshapes procurement patterns as integrated livestock operations consolidate volume contracts around certified suppliers and fragmented farm-level buyers retreat to spot-market sourcing.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for tetracycline and beta-lactam intermediates, compressing margins for non-integrated formulators. Three-tier pricing structure across premium certified, standard compliant, and economy generic tiers reflects withdrawal-period validation costs and brand assurance premiums. Pricing pressure stems from EMA antimicrobial reduction mandates accelerating product obsolescence. Corporate veterinary chains exhibit lowest price sensitivity; smallholder cooperatives show highest elasticity.
Supply Chain Analysis
REACH environmental risk assessment compliance and FDA cGMP certification gate access to Western European and North American procurement channels. Active pharmaceutical ingredient production concentrates in China, India, and Italy. Formulation depends on fermentation-derived intermediates, specialized excipients, and cold-chain distribution infrastructure. Single-source vulnerability runs through Shandong Peninsula penicillin G production. Distribution runs through veterinary distributor networks, direct farm contracting, and emerging telemedicine platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
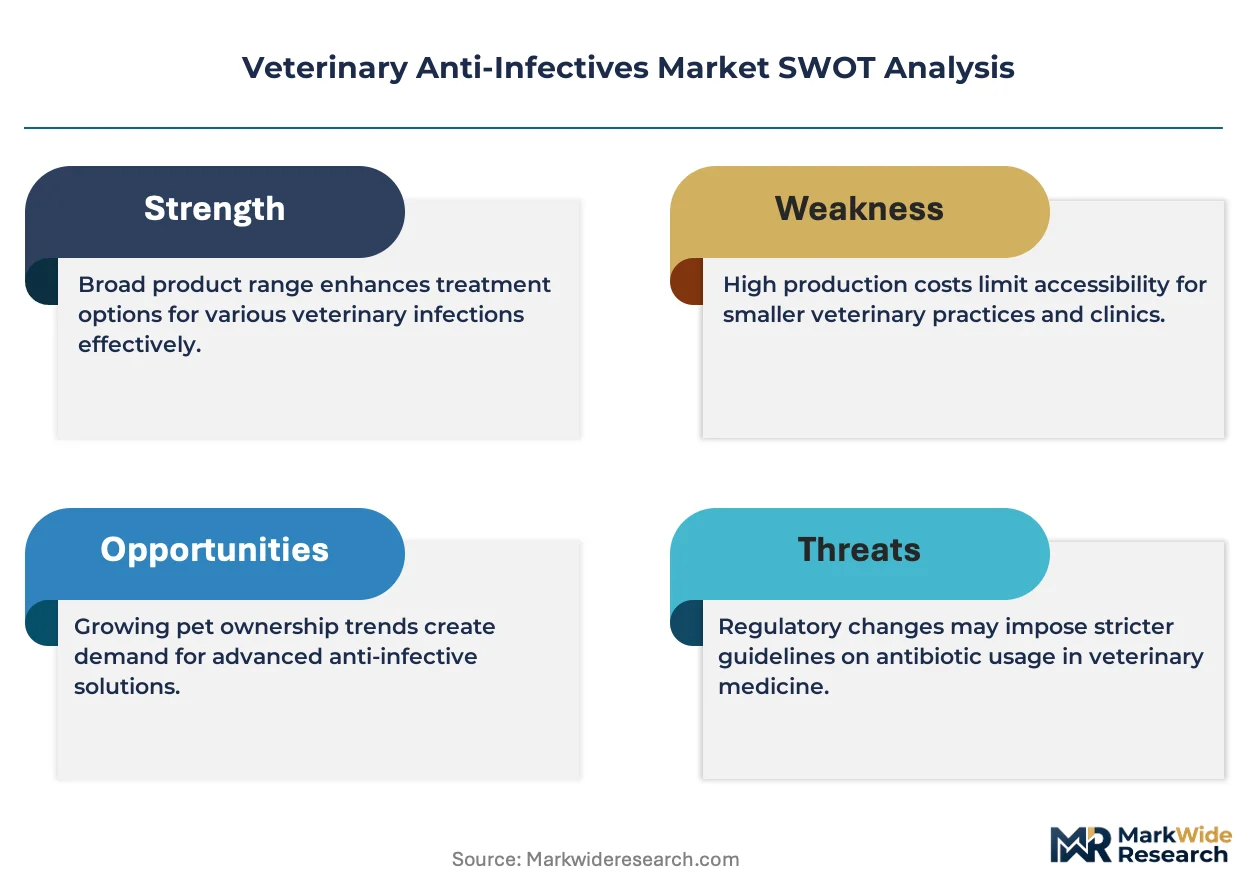
Veterinary anti-infectives function as a stable compounder anchored by irreplaceable livestock health economics and companion animal humanization trends that sustain recurring demand regardless of cyclical pressures.
For Market Incumbents: Deepen backward integration into fermentation capacity and residue-testing laboratory networks to defend margin position against API price volatility. Prioritize pharmacogenomic dosing platform development to differentiate from generic substitution and biologic substitution threats in poultry and swine segments. For New Entrants and Emerging Players: Rapid point-of-care diagnostic sequencing offers a technology-first wedge into underserved Brazilian integrated beef operations and Southeast Asian aquaculture zones. Target direct-to-producer telemedicine channels in Mato Grosso and Paraná where veterinary practitioner scarcity creates procurement access without traditional distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier formulators lack REACH compliance infrastructure and FDA-approved manufacturing sites. Position for five-to-ten year holding periods around precision therapy platforms and green chemistry formulation capabilities. Monitor ANVISA registration acceleration in Brazil as inflection signal for emerging market volume contract viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Manufacturing | Captive supply of fermentation capacity insulates formulators from Shandong supply disruptions and Indian export restrictions. |
| Precision Dosing Platform Development | Pharmacogenomic integration with rapid pathogen sequencing enables outcome-based contracting with integrated cattle feedlots. |
| REACH Environmental Compliance Investment | Ecotoxicity data packages secure EU market access as Farm to Fork antimicrobial reduction targets tighten. |
| Direct-to-Producer Telemedicine Channel | Virtual veterinary platforms bypass distributor markups and capture prescription control in Brazilian livestock consolidation zones. |
| Green Chemistry Formulation Transition | Biodegradation pathway demonstration meets EMA environmental risk assessment requirements for swine and poultry registrations. |
Research Approach
Bottom-up livestock operation and veterinary clinic modeling reconciled against top-down API production and pharmaceutical import tracking forms the analytical core. Primary interviews with herd health managers at integrated beef and poultry operations, regulatory affairs directors at animal health formulators, procurement leads at corporate veterinary chains, and distribution channel partners in Brazil and Germany combined with secondary validation from FDA Veterinary Feed Directive implementation reports, EMA antimicrobial stewardship guidelines, ANVISA registration databases, and customs trade data on veterinary pharmaceutical imports.
Historical antibiotic and antiparasitic consumption trendlines across dairy, feedlot, and companion animal segments established baseline growth patterns extrapolated across the analysis window. Segmentation dimensions modeled include product type, animal species, administration route, end-user channel, and regional regulatory cluster. CAGRs derived from weighted average of segment-level growth trajectories incorporating antimicrobial stewardship mandate penetration rates, pet insurance reimbursement expansion curves, and climate-driven vector habitat migration patterns.
The model holds under stable regulatory enforcement intensity and intact API trade flows; deviation in Chinese environmental shutdown directives or EU Green Deal acceleration timelines would shift volume and value projections. A model refresh is warranted upon material change in FDA prescription mandate expansion or Brazilian livestock consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Skin Care Products Market
Veterinary Medicine
Veterinary Medicine Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Veterinary Pain Management Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Veterinary Palliative Care Management Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market