
 Alcohol Wipes Market | 2026-2036
Alcohol Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Wipes Market Analysis
EPA Safer Choice labeling is pivoting the cost-of-entry calculus for new entrants seeking retail shelf placement in the United States. Cardinal Health leverages its hospital distribution network to sustain institutional contract density across acute care settings. Kimberly-Clark Corporation anchors North American private-label manufacturing capacity for major pharmacy chains. 3M Company differentiates through proprietary substrate technologies that extend alcohol retention during extended shelf storage.
Alcohol wipes are non-woven fabric substrates saturated with isopropyl alcohol or ethanol solutions typically formulated at concentrations between 60% and 75% by volume, designed for rapid surface disinfection and skin antisepsis in clinical, commercial, and consumer environments. Disinfecting formulations command the dominant volume position within product type segmentation due to hospital-grade efficacy requirements, while surface cleaning variants are gaining fastest in household channels as consumers blur the line between general cleaning and targeted sanitization. Individual pack formats within packaging type segmentation occupy premium margin pools tied to travel and on-the-go use cases, though canister formats dominate absolute dollar throughput in institutional procurement.
FDA oversight of skin-contact antiseptic products and EPA registration requirements for surface disinfectant claims create a dual-track compliance burden that shapes formulation decisions and label architecture for manufacturers operating in the United States. ISO 13485 quality management standards and EU MDR traceability requirements govern market access for medical-grade wipe producers serving European healthcare systems. Stakeholders must monitor evolving EPA List N renewal criteria and state-level ingredient disclosure mandates to anticipate reformulation cycles and preserve market access across jurisdictions.
Market Dynamics
Terminal cleaning protocols in US acute care facilities are hardening around pre-saturated wipe formats, compressing procurement cycles and forcing substrate suppliers to demonstrate EPA-registered efficacy documentation before contract eligibility.
Growth Catalysts
- EPA Emerging Viral Pathogens Framework:The EPA's tightened efficacy claim requirements for surface disinfectants are elevating demand for documented, hospital-grade alcohol wipe formulations in US healthcare procurement.
- Hospital-Acquired Infection Prevention Budgets:United States health systems have institutionalized infection control spending as permanent operational line items, securing recurring institutional demand for disinfecting wipes.
- Isopropyl Alcohol Retention Substrates:Proprietary non-woven fabric technologies that extend alcohol stability during extended shelf storage are unlocking retail channel expansion and reducing spoilage-driven returns.
Market Restraints
- Isopropyl Alcohol Price Volatility:Feedstock costs for isopropyl alcohol fluctuate with propylene and acetone market conditions, compressing margins for contract manufacturers locked into fixed-price hospital supply agreements.
- Dual-Track Compliance Burden:FDA oversight of skin-contact antiseptics combined with EPA surface disinfectant registration creates parallel regulatory pathways that lengthen product development timelines and inflate legal review costs.
- Quaternary Ammonium Substitutes:Longer-lasting surface disinfectants based on quaternary ammonium compounds are displacing alcohol wipes in certain environmental cleaning applications where extended antimicrobial persistence is prioritized.
Strategic Opportunities
- Travel and On-the-Go Individual Packs:Premium-margin single-use sachet formats remain underpenetrated in US airport retail and hospitality amenity channels relative to canister household penetration.
- EU MDR Traceability Compliance:European medical device regulation mandates for supply chain documentation create competitive moats for ISO 13485-certified producers serving European healthcare systems.
- Household Surface Cleaning Blur:Consumer confusion between general cleaning and targeted sanitization is accelerating demand for dual-claim wipes that bridge disinfecting efficacy with everyday usability.
Industry Challenges
- Reformulation Cycle Compression:Evolving EPA List N renewal criteria and state-level ingredient disclosure mandates in California and New York are forcing shorter product refresh timelines.
- Substrate-Formulation Integration:Matching alcohol retention properties to specific non-woven fiber densities requires specialized polymer science expertise that resides in a narrow supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Wipes Market |
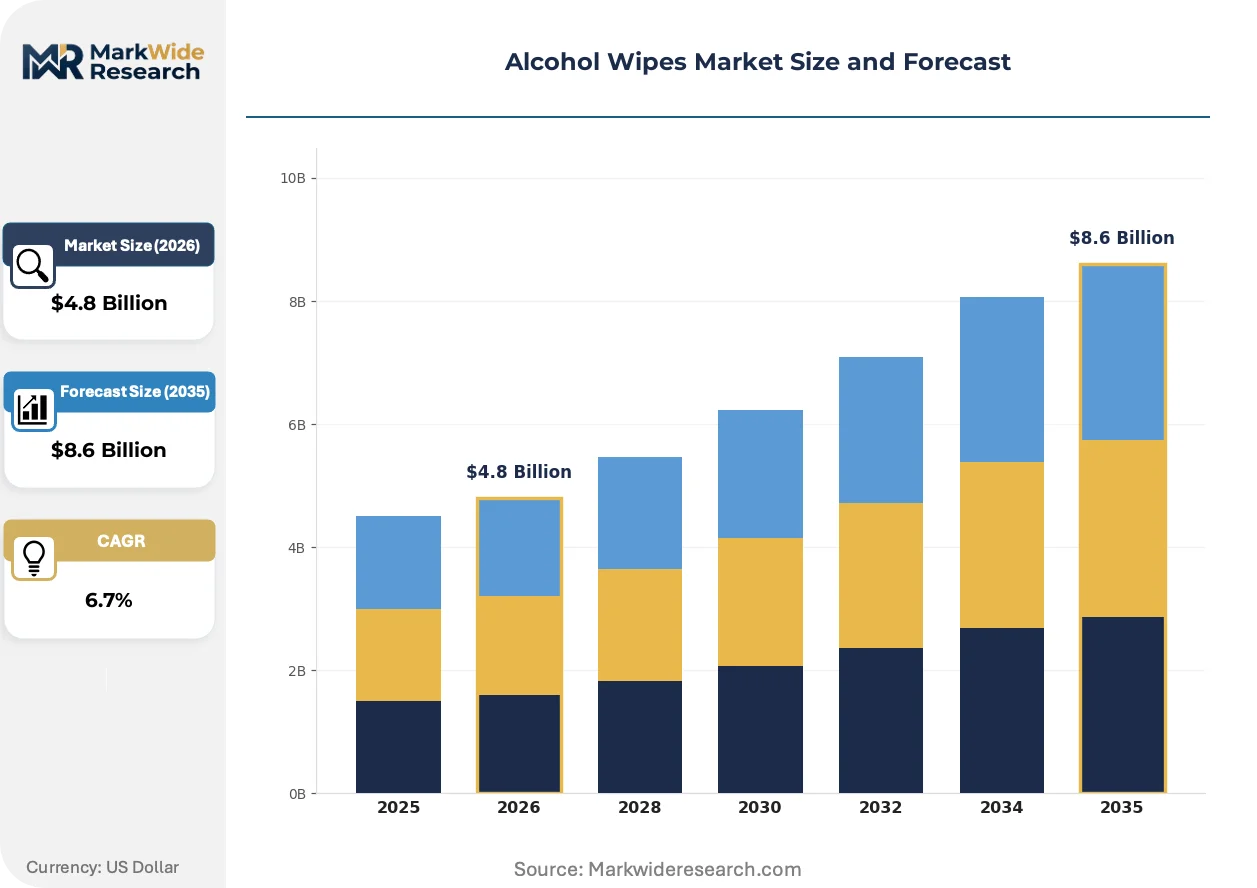
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibacterial, Disinfecting, Sanitizing, Surface Cleaning End User: Healthcare Facilities, Educational Institutions, Households, Industrial Packaging Type: Canister, Pouch, Box, Individual Pack Distribution Channel: Online Retailers, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | The Clorox Company, Cardinal Health, 3M Company, Kimberly-Clark Corporation, Nice-Pak Products Inc., GAMA Healthcare Ltd, Diamond Wipes International Inc, Clarisan, Medline Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Wipes Market Emerging Trajectories
Substrate engineering and regulatory documentation are converging to reshape competitive positioning, with manufacturers racing to differentiate through material science rather than alcohol concentration alone.
Biodegradable cellulose-based non-woven substrates are integrating plant-derived binders to maintain structural integrity during alcohol saturation without petroleum-based synthetic fibers. European healthcare procurement offices in Germany and France are piloting these materials for scope-compliant tenders. This substrate transition is integrating sustainability credentials into contract evaluation matrices previously dominated by unit cost metrics.
REACH registration requirements for imported disinfectant substances are tightening documentation obligations for non-EU manufacturers seeking European market access. The European Chemicals Agency's expanded substance evaluation program is extending compliance timelines for novel wipe formulations. Small and mid-sized producers serving EU healthcare systems are responding by consolidating formulation portfolios around pre-registered base chemistries.
Direct contracting between hospital systems and wipe converters is shortening traditional distribution hierarchies that previously flowed through medical-surgical distributors. US integrated delivery networks in Texas and Florida are negotiating volume commitments directly with private-label manufacturers. This channel restructuring is most visible in acute care settings where standardized formularies enable multi-year supply agreements.
Alcohol Wipes Market Segmentation
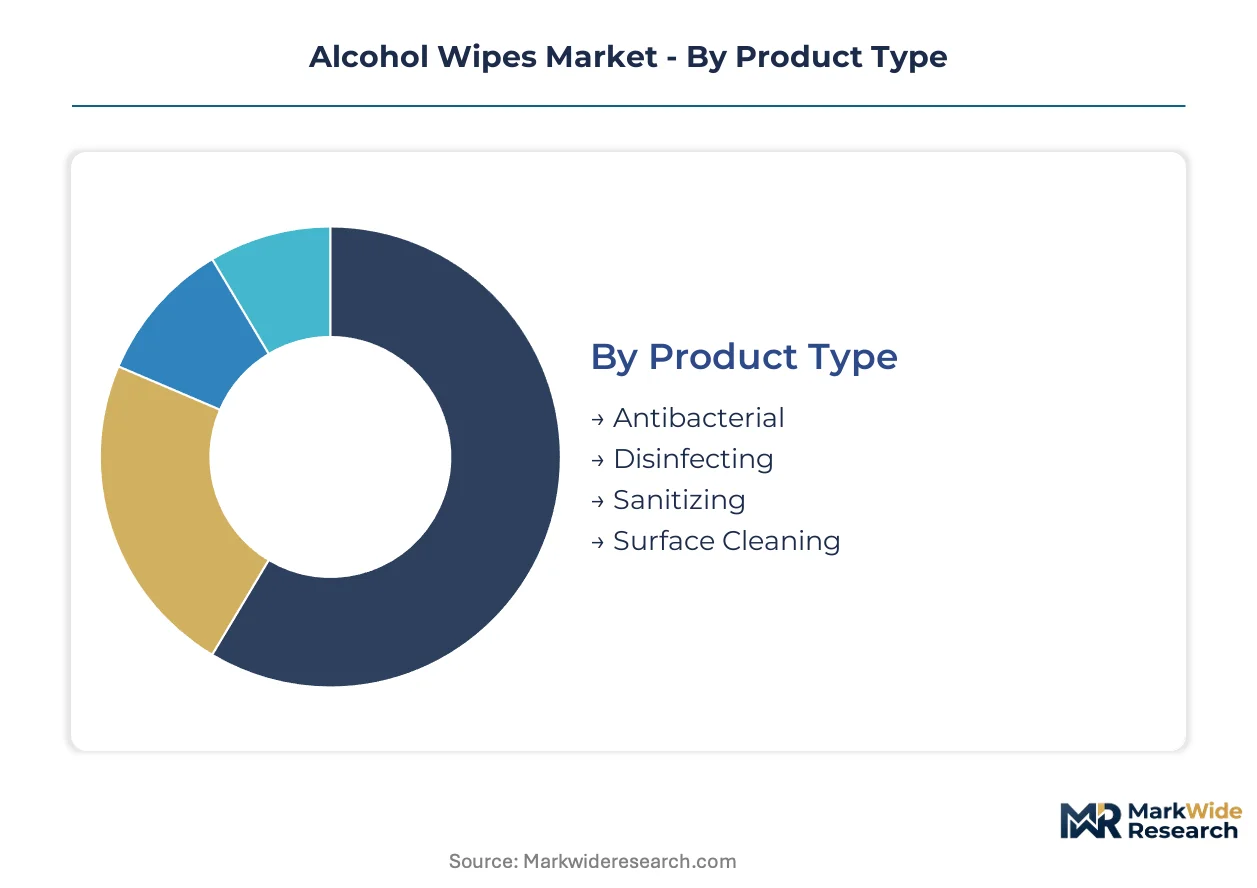
Alcohol wipe manufacturers must align substrate engineering, formulation chemistry, and packaging formats against distinct use environments where efficacy claims and convenience requirements diverge sharply. Segmentation strategy determines whether producers capture institutional procurement contracts or consumer retail shelf space.
Product Type:
Standalone disinfecting formulations operate independently of secondary cleaning protocols, while surface cleaning variants embed into broader household hygiene routines with lower concentration thresholds.
- Disinfecting:Hospital-grade formulations carrying EPA-registered kill claims against specified pathogens dominate acute care procurement in the United States. Terminal cleaning protocols in US hospitals mandate pre-saturated formats with documented efficacy against emerging viral pathogens, securing recurring institutional contracts.
- Antibacterial:Skin-contact formulations regulated under FDA antiseptic monographs target pre-injection site preparation and wound cleansing in outpatient settings. FDA compliance burdens lengthen development timelines for entrants seeking healthcare channel placement.
- Sanitizing:Intermediate-tier formulations bridge food-contact surface applications and hand hygiene in commercial food service environments.
- Surface Cleaning:Lower-concentration variants for household dusting and degreasing applications blur category boundaries with general wet wipes.
Volume placements concentrate in Disinfecting; the faster expansion belongs to Surface Cleaning as household consumers merge sanitization with daily cleaning habits.
End User:
Cost tier stratification separates premium-priced healthcare procurement from price-sensitive household purchasing, with institutional buyers prioritizing documented efficacy over unit economics.
- Healthcare Facilities:Acute care hospitals, outpatient clinics, and long-term care facilities drive demand for EPA-registered formulations with validated kill times. Infection prevention budgets in US health systems have become permanent operational line items, insulating this segment from discretionary spending cuts.
- Households:Consumer purchases through pharmacy and mass retail channels prioritize convenience packaging and multi-surface compatibility over clinical-grade documentation. Post-pandemic hygiene habit persistence sustains above-baseline consumption in US suburban markets.
- Educational Institutions:K-12 schools and universities represent mid-volume procurement with seasonal demand spikes tied to academic calendar reopenings.
- Industrial:Manufacturing floor applications for equipment sanitization and cleanroom maintenance require specialized low-lint substrates.
Revenue concentration sits with Healthcare Facilities; steepest expansion trajectory runs through Households as retail channel penetration deepens.
Packaging Type:
Application context dictates format selection, with mobility requirements and usage frequency determining whether bulk canisters or portable individual packs capture the transaction.
- Canister:Resealable plastic containers holding 40-100 wipes dominate household pantry storage and healthcare supply closet stocking. Kimberly-Clark Corporation anchors North American private-label manufacturing capacity for major pharmacy chains in this format.
- Individual Pack:Single-use sachets command premium margins in travel retail, hospitality amenities, and field medical kits where portability outweighs per-wipe cost. Underpenetration persists in US airport retail relative to Asian hub penetration benchmarks.
- Pouch:Flexible film packaging offers intermediate portability for gym bags and personal carry without full individual wrapping economics.
- Box:Cardboard dispensers serve institutional bulk purchasing with lower packaging cost per unit for high-throughput settings.
Absolute dollar throughput flows through Canister formats; premium margin capture concentrates in Individual Pack placements.
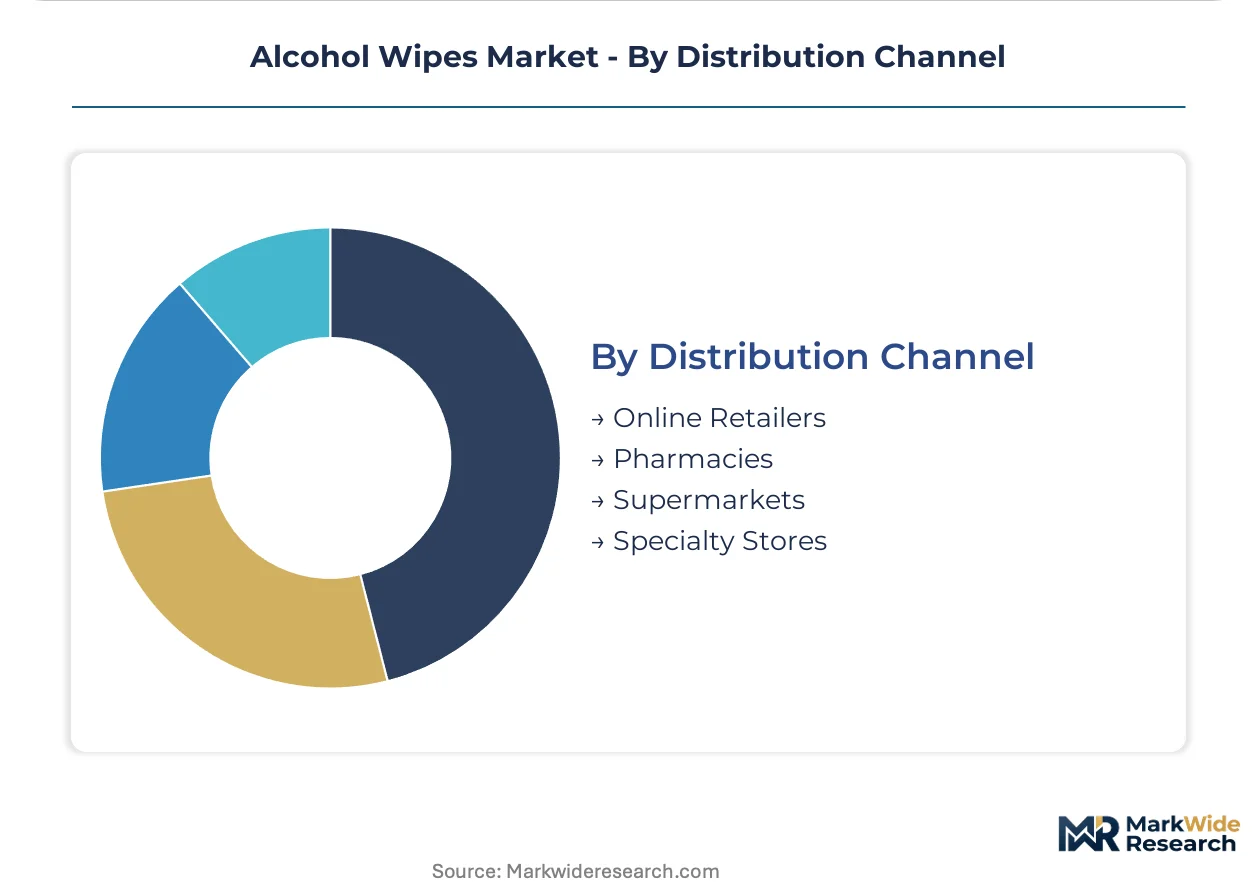
Distribution Channel:
Customer type and purchase urgency shape channel selection, with stock-up behavior favoring mass retail and immediate need driving pharmacy and online transactions.
- Pharmacies:CVS, Walgreens, and independent drugstores capture planned replenishment purchases with established private-label programs. Cardinal Health leverages its hospital distribution network to sustain institutional contract density across acute care settings.
- Online Retailers:Amazon and direct-to-consumer platforms enable subscription replenishment and bulk purchasing with lower per-unit delivery economics. 3M Company differentiates through proprietary substrate technologies that extend alcohol retention during extended shelf storage, reducing spoilage-driven returns in e-commerce fulfillment.
- Supermarkets:Mass merchant shelf space competition intensifies around EPA Safer Choice labeling as a cost-of-entry requirement.
- Specialty Stores:Medical supply dealers and industrial distributors serve niche professional applications with technical specification support.
Procurement volume aggregates in Pharmacies; channel share is climbing the fastest through Online Retailers as subscription models lock in recurring household purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates are concentrating Middle East distribution capacity for alcohol wipe exporters serving Gulf health systems. Tax-advantaged manufacturing parks in Ireland and Singapore anchor European and Asia-Pacific supply chain nodes respectively.
United States
Hospital-acquired infection prevention budgets in Texas and Florida integrated delivery networks have become permanent operational line items, securing recurring institutional demand. EPA's emerging viral pathogens claim framework tightens efficacy documentation requirements for surface disinfectants entering healthcare procurement. Cardinal Health leverages its acute care distribution network across the Midwest and Southeast to sustain institutional contract density.
Germany
REACH registration requirements for imported disinfectant substances are tightening documentation obligations for non-EU manufacturers seeking European market access. The European Chemicals Agency's expanded substance evaluation program extends compliance timelines for novel wipe formulations. Bavarian healthcare procurement offices pilot biodegradable cellulose-based substrates for scope-compliant tenders.
China
Dual carbon goals under national environmental policy are accelerating substrate transitions away from petroleum-based synthetic fibers toward plant-derived binders. The National Medical Products Administration oversees quality management standards for medical-grade wipe producers serving domestic hospital systems. Yangtze River Delta manufacturing clusters concentrate non-woven fabric conversion capacity for export-oriented producers.
India
Production-linked incentive schemes for medical device manufacturing are attracting private-label converters to establish domestic wipe production capacity. The Central Drugs Standard Control Organization regulates skin-contact antiseptic products under pharmaceutical oversight frameworks. Maharashtra and Gujarat industrial corridors host emerging substrate engineering facilities serving both domestic pharmacy chains and export markets.
United Kingdom
EU MDR traceability requirements continue governing market access for medical-grade wipe producers serving NHS procurement systems despite post-Brexit regulatory divergence. The Medicines and Healthcare products Regulatory Agency maintains parallel oversight pathways for disinfectant claims. London and Southeast England distribution hubs coordinate private-label manufacturing for major pharmacy chains across Northern Europe.
Alcohol Wipes Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate engineering, formulation chemistry, and distribution channel control. The vendor base stratifies into three tiers: multinational healthcare suppliers with hospital distribution networks, private-label manufacturers with retail pharmacy relationships, and specialized substrate technology developers. Competitive moves concentrate on direct contracting with hospital systems and proprietary alcohol retention substrate development.
Among diversified healthcare suppliers, Cardinal Health and 3M Company occupy positions spanning institutional procurement and proprietary technology development respectively. Kimberly-Clark Corporation anchors North American private-label manufacturing capacity for major pharmacy chains. These three entities exemplify the scale-driven tier where distribution network density and substrate engineering capabilities determine contract eligibility.
| Leading Market Players |
|---|
| The Clorox Company |
| Cardinal Health |
| 3M Company |
| Kimberly-Clark Corporation |
| Nice-Pak Products Inc. |
| GAMA Healthcare Ltd |
| Diamond Wipes International Inc |
| Clarisan |
| Medline Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Isopropyl alcohol feedstock costs trace from propylene and acetone commodity markets through contract manufacturer margins into hospital procurement tiers, with fixed-price supply agreements locking producers into margin compression during feedstock spikes.
Pricing Analysis
Short lead-time premiums attach to EPA-registered formulations with documented emerging viral pathogen claims, while spot inventory of uncertified household variants trades at discounted clearing rates. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade disinfecting wipes with validated kill times from intermediate sanitizing formats and basic surface cleaning variants. Pricing pressure stems from isopropyl alcohol price volatility tied to petrochemical feedstock markets. Household consumers through mass retail channels exhibit highest price sensitivity, while acute care procurement committees prioritize efficacy documentation over unit economics.
Supply Chain Analysis
EPA registration and ISO 13485 certification gating restricts contract eligibility to substrate converters with documented quality management systems and validated alcohol retention properties. Manufacturing concentrates in the United States, China, and Germany, with Yangtze River Delta clusters anchoring non-woven fabric conversion and Midwest US facilities serving hospital distribution networks. Supply chains draw from petroleum-based synthetic fiber feedstocks, plant-derived cellulose alternatives, and specialized polymer binders. Single-source vulnerability concentrates in proprietary substrate technology holders. Distribution runs through medical-surgical distributors, direct hospital contracting, and pharmacy retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substrate engineering capacity constraints prop pricing power for ISO 13485-certified producers, as hospital systems face limited qualified supplier pools for terminal cleaning protocols.
For Market Incumbents: Cement proprietary alcohol retention substrate positions through backward integration into non-woven fiber production, locking out competitors from EPA-registered contract eligibility. Expand capacity in Texas and Florida integrated delivery network corridors where direct hospital contracting is shortening distribution hierarchies. Quaternary ammonium compound substitutes threaten displacement in environmental cleaning applications where extended antimicrobial persistence is prioritized. For New Entrants and Emerging Players: Enter via biodegradable cellulose-based substrate segments where Bavarian and French procurement offices are piloting scope-compliant tenders ahead of mandate expansion. Target US airport retail and hospitality amenity channels for premium-margin individual pack formats, currently underpenetrated relative to Asian hub benchmarks. Lead with EU MDR traceability compliance as competitive moat for European healthcare system access. For Investors and Strategic Acquirers: Distressed-cycle entries favor private-label converters with pharmacy chain relationships in India and Southeast Asia, where production-linked incentive schemes are attracting medical device manufacturing capacity. Long-term viability hinges on substrate-formulation integration capabilities that reduce reformulation cycle compression risks. Watch EPA List N renewal criteria evolution as inflection indicator for portfolio consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Engineering Investment | Proprietary alcohol retention technologies differentiate producers during EPA registration reviews. |
| Direct Hospital Contracting | Texas and Florida integrated delivery networks negotiate multi-year volume commitments bypassing distributors. |
| Biodegradable Substrate Transition | German and French procurement pilots integrate sustainability credentials into contract evaluation matrices. |
| EU MDR Compliance Certification | ISO 13485 quality management standards create competitive moats for European healthcare market access. |
| Individual Pack Channel Expansion | US airport retail and hospitality amenity placements capture premium margins in underpenetrated segments. |
Methodological Framework
Document review covered EPA registration databases, FDA antiseptic monographs, hospital procurement records, and customs trade data, complemented by interviews with infection prevention officers, GPO contracts managers, substrate R&D directors, and pharmacy category buyers. Secondary validation drew from SEC filings of diversified healthcare suppliers, EU MDR technical documentation, and REACH substance registrations. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Historical shipment data cross-referenced against panel input from procurement committees and converter operations to establish baseline trajectory assumptions. Segmentation dimensions spanned product type, end user, packaging format, and distribution channel, with additional modeling of regulatory compliance tier effects. CAGRs derived from curve-fitting approaches applied to validated endpoint estimates. Forecast inputs incorporated EPA List N renewal timelines and substrate engineering pipeline maturity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt isopropyl alcohol feedstock shocks or accelerated quaternary ammonium substitution in healthcare settings. Model assumptions reflect documented efficacy claim requirements and procurement budget institutionalization trends. A model refresh is warranted upon material change in EPA emerging viral pathogens framework criteria or state-level ingredient disclosure mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Medical Washer Disinfector Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Hygiene Stations Market
Infection Control
Staphylococcal Infection Treatment Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Infection Control Market
Infection Control
Botulism Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Global Disinfection Robots Market
Infection Control
Sterilization Monitoring Market
Infection Control
North America Hand Sanitizer Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Denture Disinfectants Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Blood Stream Infection Testing Market