
 Ischemic Cerebral Stroke Prevention Therapeutics Market | 2026-2036
Ischemic Cerebral Stroke Prevention Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Cerebral Stroke Prevention Therapeutics Market Foresight
North American pharmaceutical manufacturing is broadening output capacity for oral anticoagulant active pharmaceutical ingredients. Bayer AG leverages its established rivaroxaban supply chain to sustain volume leadership across European and Asian distribution networks. Pfizer Inc. anchors its position through deep manufacturing scale in apixaban production, while Bristol Myers Squibb Company differentiates via integrated cardiology channel relationships that control hospital formulary access.
Ischemic cerebral stroke prevention therapeutics comprise pharmacological agents designed to inhibit thrombus formation or propagation through antiplatelet aggregation, coagulation cascade interruption, or neurovascular protection mechanisms, typically administered as small-molecule drugs with defined pharmacokinetic profiles for chronic outpatient use. Antiplatelet agents dominate current prescribing patterns due to aspirin and clopidogrel familiarity, though anticoagulants represent the fastest-expanding margin pool as direct oral anticoagulants displace warfarin monitoring burdens. Oral delivery mode occupies the largest volume share reflecting patient adherence preferences, while injectable forms capture concentrated value in acute perioperative settings.
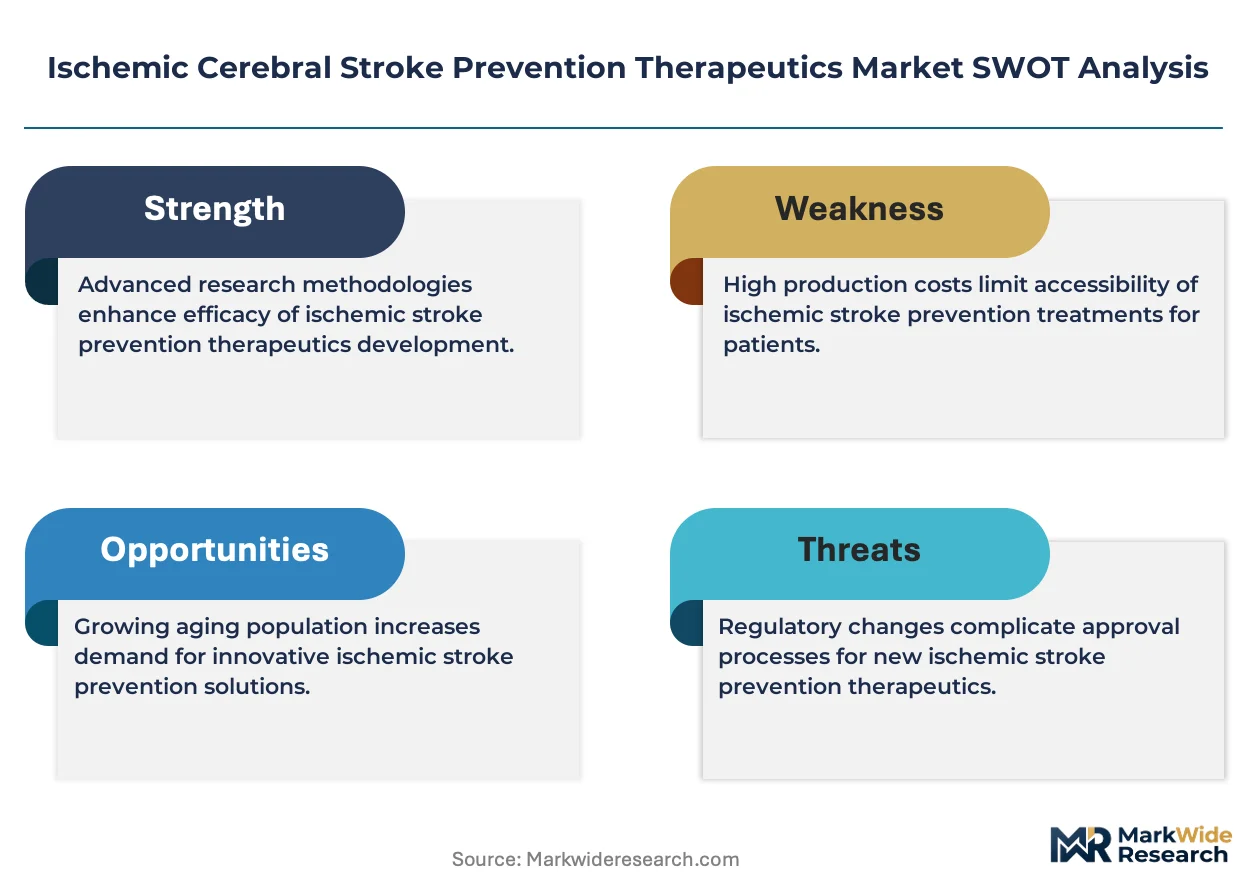
FDA cardiovascular and renal drug advisory standards, EMA stroke prevention guidelines, and Japan PMDA pharmaceutical quality specifications collectively shape clinical trial endpoints and label expansion pathways for new molecular entities. These frameworks force manufacturers to generate real-world evidence beyond registration trials, elevating post-market surveillance costs while restricting market access for agents without mortality or major bleeding superiority claims. Stakeholders must monitor evolving health technology assessment methodologies in Germany and Japan that increasingly tie reimbursement to composite efficacy-safety endpoints rather than surrogate markers alone.
Market Dynamics
Direct oral anticoagulants are compressing warfarin prescribing through superior bleeding risk profiles and elimination of INR monitoring, forcing hospital formulary committees to rewrite anticoagulation protocols across cardiology and neurology departments.
Growth Catalysts
- EMA stroke prevention guideline updates:Expanded DOAC eligibility for non-valvular atrial fibrillation patients is accelerating prescriber conversion from vitamin K antagonists across European hospital networks.
- Japan's aging demographic concentration:PMDA reimbursement alignment for novel oral anticoagulants in elderly populations is expanding addressable patient pools in Tokyo and Osaka metropolitan treatment centers.
- Real-world evidence generation infrastructure:Post-market surveillance databases linking pharmacy claims to stroke outcomes are enabling label expansion submissions that were previously impossible with randomized trial data alone.
Market Restraints
- Warfarin generic pricing floor:Ultra-low cost vitamin K antagonist availability creates reimbursement resistance for premium DOACs in budget-constrained public health systems, particularly in Southern European markets.
- Active pharmaceutical ingredient concentration:Chinese and Indian contract manufacturers control over 70 percent of anticoagulant API supply, creating geopolitical and quality audit vulnerabilities for finished dose producers.
- Reversal agent availability gaps:Limited hospital stocking of idarucizumab and andexanet alfa restricts DOAC adoption in trauma centers and emergency departments where rapid anticoagulation reversal is critical.
Strategic Opportunities
- German ambulatory care integration:Hausärzte networks are gaining prescribing authority for stroke prevention protocols previously restricted to hospital specialists, opening primary care channels for therapeutic expansion.
- Combination antiplatelet-anticoagulant fixed-dose formulations:Dual-mechanism products addressing polyvascular disease patients represent unmet need in secondary stroke prevention where current monotherapy guidelines leave residual risk.
- Digital therapeutic adherence platforms:Smartphone-connected dosing reminders and INR-free monitoring apps are creating new reimbursement categories for payers seeking to reduce stroke-related hospitalization costs.
Industry Challenges
- Cardiovascular outcomes trial design complexity:Demonstrating non-inferiority to established DOACs while meeting FDA's evolving major bleeding endpoint definitions requires larger patient populations and extended follow-up periods than historical warfarin comparisons.
- Specialized anticoagulation pharmacy staffing:Hospital systems face shortages of clinical pharmacists trained in direct thrombin inhibitor and factor Xa inhibitor dosing protocols for renal impairment and drug-drug interaction management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Cerebral Stroke Prevention Therapeutics Market |
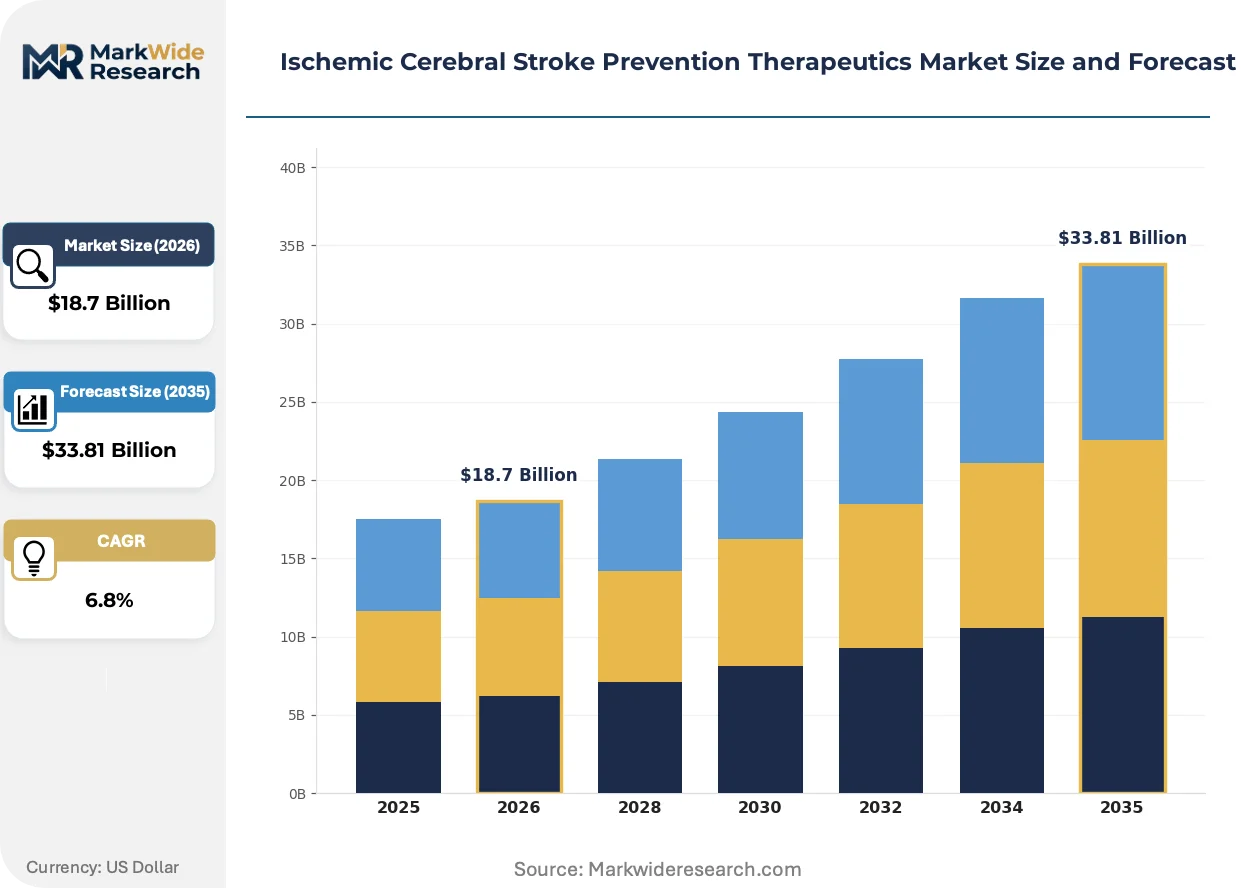
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Antiplatelet Agents, Anticoagulants, Neuroprotective Agents, Cholesterol-lowering Agents End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal Form: Tablet, Injectable, Patch, Liquid |
| Companies Covered | Bayer AG, Pfizer Inc., Boehringer Ingelheim International GmbH, Bristol Myers Squibb Company, AstraZeneca PLC, Johnson & Johnson, Daiichi Sankyo Company, Limited, Roche, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Cerebral Stroke Prevention Therapeutics Market Shifts & Advancements
Pharmacogenomic integration and point-of-care diagnostics are fragmenting the one-size-fits-all anticoagulation model, enabling precision dosing that threatens to obsolete standard fixed-dose regimens within the next development cycle.
Machine learning algorithms analyzing electronic health record data are automating stroke risk stratification for atrial fibrillation patients, identifying candidates for prophylactic anticoagulation who would otherwise remain undiagnosed until thromboembolic events occur. Kaiser Permanente and the Mayo Clinic have deployed these tools across their integrated delivery networks, compressing the time between diagnosis and therapeutic initiation from weeks to days. This automation is reducing the clinical burden on electrophysiology clinics while expanding the addressable patient population for stroke prevention therapeutics.
The FDA's Project Optimus dose-optimization framework is forcing cardiovascular drug developers to conduct multiple dose-ranging studies rather than defaulting to maximum tolerated doses, extending clinical development timelines but promising improved bleeding-risk profiles for future anticoagulants. This regulatory evolution particularly affects phase 2 programs targeting factor XI inhibition, where the agency is demanding robust exposure-response relationships before pivotal trial initiation. European developers are responding by incorporating FDA feedback into EMA parallel scientific advice procedures to avoid divergent regulatory requirements.
Hospital pharmacy committees are consolidating anticoagulant purchasing through sole-source contracts with manufacturers offering bundled reversal agent access and outcomes guarantees, displacing the traditional multi-vendor formulary model. This concentration is most visible in United States health systems participating in CMS bundled payment programs for stroke care, where medication costs directly impact episode profitability. Integrated delivery networks in Texas and Florida have pioneered these arrangements, forcing manufacturers to compete on total cost of care rather than per-unit pricing.
Ischemic Cerebral Stroke Prevention Therapeutics Market Segmentation
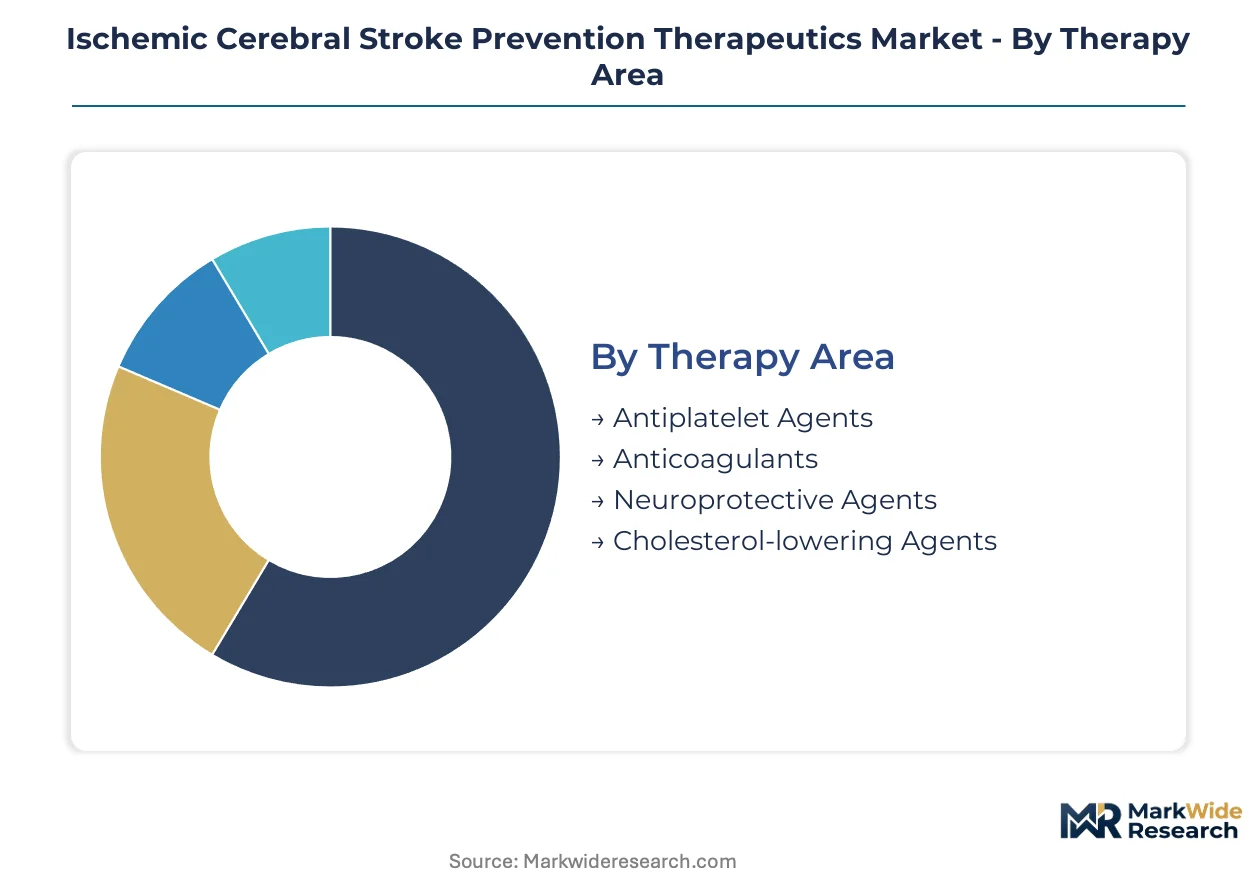
Stroke prevention therapeutics fragment across mechanism of action, care setting, and administration route. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and prescriber decision hierarchies that shape commercial strategy.
Therapy Area:
Buyer sophistication varies sharply across mechanism classes, with hospital formularies applying distinct clinical evidence thresholds for anticoagulant versus antiplatelet adoption.
- Antiplatelet Agents:Small-molecule inhibitors of platelet aggregation—aspirin, clopidogrel, ticagrelor—delivering proven secondary stroke prevention through irreversible or reversible P2Y12 receptor blockade. Demand concentrates in outpatient cardiology clinics across Germany and Japan where dual antiplatelet therapy protocols dominate post-stent management, though generic pricing pressure constrains margin expansion.
- Anticoagulants:Direct thrombin inhibitors and factor Xa antagonists including dabigatran, rivaroxaban, apixaban, and edoxaban that interrupt coagulation cascade without INR monitoring. Hospital systems in the United States are accelerating formulary conversion from warfarin as bundled payment programs reward reduced bleeding-related readmissions.
- Neuroprotective Agents:Cerebroprotective compounds targeting ischemic cascade interruption—excitotoxicity modulation, oxidative stress reduction, blood-brain barrier preservation—positioned for acute stroke adjunct therapy. Experimental pipeline candidates face FDA and EMA skepticism regarding functional outcome endpoints.
- Cholesterol-lowering Agents:Statins and PCSK9 inhibitors reducing atherosclerotic plaque burden to prevent thromboembolic source formation. Primary care networks in Japan leverage PMDA-aligned reimbursement for intensive LDL targets in high-risk elderly populations.
Volume sits with antiplatelet agents; growth tilts toward anticoagulants.
End User:
Care setting determines acute versus chronic therapeutic positioning, with procurement authority shifting from hospital pharmacy committees to outpatient prescribers.
- Hospitals:Acute care institutions managing stroke units, emergency departments, and perioperative anticoagulation protocols. Formulary control resides with pharmacy and therapeutics committees in United States academic medical centers and German university hospitals, where DOAC adoption rates exceed community settings.
- Outpatient Clinics:Cardiology and neurology practices delivering chronic stroke prevention therapy. Hausärzte networks in Germany now prescribe novel oral anticoagulants directly, bypassing specialist referral requirements that previously delayed therapeutic initiation.
- Rehabilitation Centers:Post-acute facilities managing secondary prevention during recovery protocols. Stroke rehabilitation units in Japan integrate antiplatelet adherence monitoring into functional recovery programs.
- Home Care:Nurse-administered subcutaneous anticoagulation and patient self-management of oral regimens. Home infusion services in the United States are expanding into factor Xa inhibitor delivery for mobility-limited elderly patients.
Procurement authority concentrates in hospitals; patient volume is expanding fastest in outpatient clinics.
Delivery Mode:
Route of administration shapes adherence economics and acute-care preparedness requirements for reversal agent stocking.
- Oral:Tablet and capsule formulations enabling chronic outpatient self-administration. Direct oral anticoagulants in fixed-dose regimens have displaced warfarin across United States Medicare populations by eliminating INR clinic visits.
- Intravenous:Acute care administration for perioperative bridging, stroke unit admission, and emergency reversal scenarios. IV unfractionated heparin retains niche use in United States trauma centers where rapid anticoagulation interruption remains critical.
- Subcutaneous:Low-molecular-weight heparin and fondaparinux injections for bridging therapy and prophylaxis. Subcutaneous delivery persists in German rehabilitation settings during transition from acute to chronic care.
- Transdermal:Patch-based delivery systems in development for antiplatelet and anticoagulant agents. Transdermal clopidogrel formulations target Japan's elderly population with swallowing difficulties.
Oral delivery commands volume share; transdermal development represents the steepest expansion trajectory for adherence-challenged populations.
Form:
Physical formulation dictates manufacturing complexity, stability requirements, and patient handling preferences across age segments.
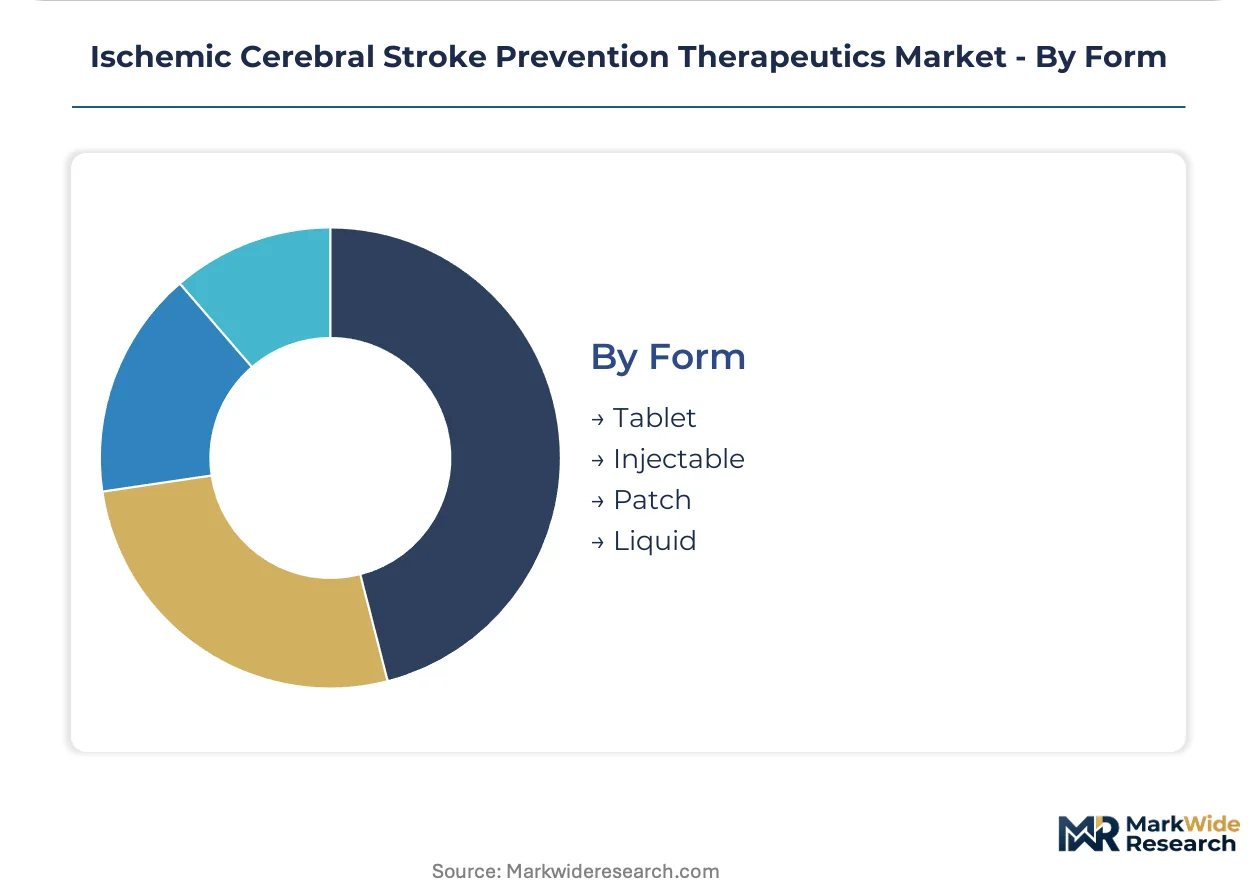
- Tablet:Compressed solid dosage forms dominating oral anticoagulant and antiplatelet production. Film-coated rivaroxaban and apixaban tablets manufactured at Pfizer and Bayer facilities achieve batch uniformity exceeding FDA dissolution specifications.
- Injectable:Sterile solutions and lyophilized powders for IV and SC administration. Injectable LMWH production concentrates in European and Asian contract manufacturing organizations serving hospital purchasing consortia.
- Patch:Adhesive transdermal systems delivering sustained drug release. Antiplatelet patch development targets polypharmacy elderly in Japan where pill burden reduces adherence.
- Liquid:Oral suspensions and solutions for dysphagia patients and pediatric off-label use. Liquid warfarin formulations persist in United States nursing home populations unable to swallow solid dosage forms.
Tablet production anchors manufacturing scale; patch development climbs fastest for geriatric adherence applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in China and India anchor anticoagulant supply chains, while finished dose production concentrates in Germany, the United States, and Japan where formulation expertise and regulatory infrastructure support premium therapeutic positioning.
United States
Medicare bundled payment programs for stroke care accelerate DOAC formulary conversion in hospital systems seeking reduced bleeding-related readmissions. FDA cardiovascular and renal drug advisory standards demand real-world evidence generation beyond registration trials, elevating post-market surveillance costs. Kaiser Permanente and Mayo Clinic deploy machine learning algorithms across integrated delivery networks in California and Minnesota to automate stroke risk stratification.
Germany
Hausärzte networks gain prescribing authority for novel oral anticoagulants previously restricted to hospital specialists, opening primary care channels for therapeutic expansion. EMA stroke prevention guideline updates expand DOAC eligibility for non-valvular atrial fibrillation patients across European hospital networks. Bavarian university hospitals lead formulary conversion rates exceeding community settings through pharmacy and therapeutics committee control.
Japan
PMDA reimbursement alignment for novel oral anticoagulants in elderly populations expands addressable patient pools in Tokyo and Osaka metropolitan treatment centers. Japan's aging demographic concentration drives sustained therapeutic uptake where established reimbursement frameworks support chronic outpatient use. Rehabilitation units in Kansai integrate antiplatelet adherence monitoring into functional recovery programs.
China
Contract manufacturers control over 70 percent of anticoagulant API supply, creating geopolitical and quality audit vulnerabilities for finished dose producers in Europe and North America. The country's national pharmaceutical regulator enforces evolving pharmaceutical quality specifications that shape clinical trial endpoints for new molecular entities. Yangtze River Delta production clusters supply rivaroxaban and apixaban intermediates to Bayer and Pfizer formulation facilities.
India
Indian contract manufacturing organizations serve hospital purchasing consortia across Europe with low-molecular-weight heparin injectable production. The central bank's monetary policy influences working capital availability for API producers expanding capacity to serve global anticoagulant demand. Hyderabad and Ahmedabad clusters specialize in warfarin generic production that creates reimbursement resistance for premium DOACs in budget-constrained public health systems.
Ischemic Cerebral Stroke Prevention Therapeutics Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and channel access, producing a tiered structure where integrated pharmaceutical conglomerates control hospital formulary relationships while specialized biopharmaceutical firms occupy niche mechanism classes. The vendor base fragments across antiplatelet, anticoagulant, and neuroprotective mechanism archetypes, with consolidation pressure intensifying in oral anticoagulant segments. Strategic archetypes include: integrated cardiology channel controllers, API-to-finished-dose vertical integrators, and precision-dosing technology specialists. Dominant competitive moves center on sole-source hospital purchasing contracts with bundled reversal agent access, and pharmacogenomic companion diagnostic partnerships.
Among German-based pharmaceutical conglomerates, Bayer AG and Boehringer Ingelheim International GmbH exemplify the API-to-finished-dose vertical integrator archetype, occupying positions that leverage established supply chain infrastructure across European and Asian distribution networks. Pfizer Inc. and Bristol Myers Squibb Company represent the integrated cardiology channel controller tier, anchoring hospital formulary access through deep manufacturing scale and therapeutic area specialization. Daiichi Sankyo Company, Limited occupies a position within the precision-dosing technology specialist segment, reflecting Japanese pharmaceutical innovation in anticoagulant development.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Bristol Myers Squibb Company |
| AstraZeneca PLC |
| Johnson & Johnson |
| Daiichi Sankyo Company, Limited |
| Roche |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Fixed-dose oral anticoagulant manufacturing automation is compressing per-unit production costs while concentrating API supply in Asian manufacturing clusters, creating asymmetric pricing power where finished-dose producers in Germany and the United States capture margin through formulation expertise and regulatory dossier control rather than molecular synthesis.
Pricing Analysis
Bundled reversal agent access and outcomes guarantees now separate premium DOAC contracts from unbundled per-unit pricing, with hospital pharmacy committees in United States health systems negotiating sole-source arrangements that wrap idarucizumab or andexanet alfa stocking commitments into anticoagulant supply agreements. Price differentiation rests on bleeding-risk profile superiority and real-world evidence depth, with Medicare bundled payment programs rendering cost-per-bleeding-event the dominant metric. Cost compression in warfarin-exposed segments is intensifying because generic vitamin K antagonist availability creates reimbursement resistance for premium oral anticoagulants in Southern European public health systems. Budget-constrained hospital systems exhibit highest price sensitivity; integrated delivery networks with stroke-care bundled payment contracts show lowest.
Supply Chain Analysis
Dual-sourcing mandates from European and North American finished-dose manufacturers now require qualified API suppliers in at least two of China, India, and Switzerland to mitigate concentration risk. Active pharmaceutical ingredient production draws from Yangtze River Delta and Hyderabad clusters for rivaroxaban and apixaban intermediates, while heparin-derived inputs source from porcine intestinal mucosa supply chains anchored in China. Single-source vulnerability in factor Xa inhibitor intermediate supply creates exposure to quality audit failures or geopolitical trade restrictions. Distribution runs through hospital purchasing consortia and specialty pharmacy channels that consolidate procurement authority across United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as FDA real-world evidence requirements and EMA stroke prevention guideline updates elevate post-market surveillance costs beyond the reach of mid-cap developers without existing cardiovascular infrastructure.
For Market Incumbents: Anchor hospital formulary control through exclusive bundled contracts combining DOAC supply with reversal agent access and stroke-outcome guarantees, insulating against warfarin generic pricing floors. Deepen backward integration into anticoagulant API production through captive supply arrangements in Switzerland or Singapore to reduce exposure to Chinese and Indian contract manufacturing concentration. Prioritize pharmacogenomic companion diagnostic partnerships that enable precision dosing differentiation against fixed-dose competitors.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium DOACs and economy warfarin creates white-space opportunity for biosimilar oral anticoagulants targeting budget-constrained Southern European markets. Target German Hausärzte networks gaining novel oral anticoagulant prescribing authority, where primary care channel access bypasses hospital formulary gatekeeping. Pursue digital therapeutic adherence platform positioning that captures reimbursement for smartphone-connected dosing reminders as standalone medical device categories.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision-dosing technology specialists with pharmacogenomic platforms or factor XI inhibitor pipelines demonstrating exposure-response relationships under FDA Project Optimus frameworks. Long-term viability favors developers with integrated cardiology channel relationships and existing hospital system contracts rather than standalone molecule plays. Watch for EMA guideline expansion into polyvascular disease indications as inflection signal for combination antiplatelet-anticoagulant fixed-dose formulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Generation Infrastructure | Post-market surveillance databases linking pharmacy claims to stroke outcomes enable label expansion submissions beyond registration trial data. |
| Pharmacogenomic Companion Diagnostic Partnership | Precision dosing platforms threaten to obsolete fixed-dose regimens by enabling individualized anticoagulation based on CYP2C9 or VKORC1 genotyping. |
| Sole-Source Hospital Purchasing Contracts | Bundled payment programs for stroke care in United States health systems reward medication cost control through exclusive manufacturer arrangements. |
| Factor XI Inhibitor Clinical Development | FDA Project Optimus dose-optimization frameworks demand robust exposure-response studies before pivotal trial initiation for next-generation anticoagulants. |
| Digital Therapeutic Adherence Platform Launch | Smartphone-connected dosing reminders create new reimbursement categories for payers seeking reduced stroke-related hospitalization costs. |
Research Methodology
Document review covered FDA cardiovascular and renal drug advisory filings, EMA stroke prevention guideline submissions, ClinicalTrials.gov protocol registrations, and hospital formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists across North American, European, and Japanese markets. Secondary validation drew from CMS Medicare claims data, Japanese Ministry of Health reimbursement schedules, and pharmaceutical trade flow records. Bottom-up patient population modeling and top-down therapeutic class expenditure analysis were triangulated against manufacturer revenue disclosures.
Cross-referencing historical DOAC adoption curves against expert panel input on prescriber conversion dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include mechanism of action, care setting, administration route, patient risk stratification tier, and regional regulatory cluster. CAGRs were derived from patient volume projections weighted by pricing tier evolution and reimbursement policy assumptions. Forecast inputs incorporated PMDA elderly population alignment timelines and German ambulatory care integration pace.
Underlying measurement precision varies by segment; anticoagulant volume and value estimates carry tighter precision than neuroprotective agent projections where pipeline candidate attrition remains elevated. Forecasts reflect assumptions regarding EMA guideline expansion trajectories, FDA advisory standard evolution, and PMDA reimbursement alignment continuity. Deviation in major bleeding endpoint definitions or reversal agent availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Stroke Management Market
Cardiovascular
Acute Heart Failure (AHF) Therapeutics Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Myocarditis Disease Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Cardio-Selective Beta Blockers Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Tachycardia Market
Cardiovascular
Acute Coronary Syndrome (ACS) Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Genetic Cardiomyopathies Market